
 Taiwan Pet Food Market | 2026-2036
Taiwan Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Pet Food Market Outlook
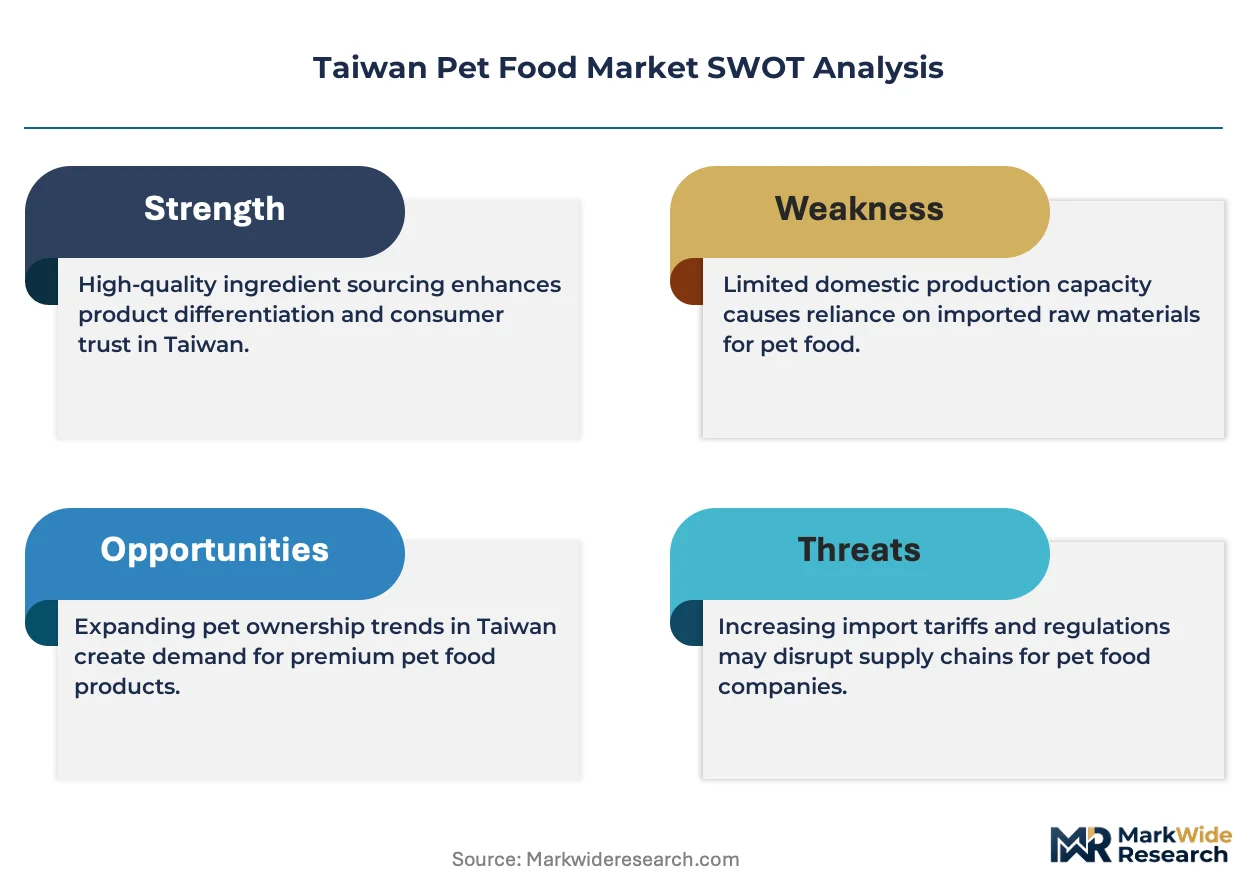
Premium ingredient certification is bifurcating the Taiwan pet food landscape into veterinarian-endorsed therapeutic tiers and mass-market nutrition lines. Mars Inc. leverages its veterinary clinic partnerships to anchor therapeutic distribution, while Nestlé Purina PetCare competes through specialized wet food formulations targeting renal health. Han Shuo Food Co. Ltd. sustains domestic manufacturing scale with ISO-compliant facilities serving private-label contracts.
Taiwan pet food comprises commercially manufactured nutritional products formulated to specific AAFCO or FEDIAF nutrient profiles, with moisture content, crude protein ratios, and additive compliance determining product classification and shelf stability. Dry food occupies the volume base due to storage convenience and lower per-feeding cost, while wet food commands margin concentration through palatability advantages and prescription positioning. Grain-free and natural ingredient segments within the ingredient quality dimension attract disproportionate R&D allocation as Taipei-based consumers prioritize clean-label transparency.
The Council of Agriculture enforces pet food safety inspections under the Animal Industry Act, while the Food and Drug Administration monitors cross-border imports for mycotoxin and pathogen thresholds. Taiwan's mandatory product registration and ingredient disclosure requirements create compliance barriers that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor evolving veterinary channel consolidation and shifting e-commerce fulfillment standards as online retail captures growing share of recurring purchases.
Market Dynamics
Veterinary channel consolidation in Taipei is compressing distribution pathways, forcing manufacturers to secure direct clinic partnerships or lose shelf access to therapeutic-grade formulations.
Growth Catalysts
- AAFCO Nutrient Profile Alignment:Taiwan's Council of Agriculture mandates AAFCO-equivalent labeling standards, creating compliance clarity that accelerates premium product registration timelines for domestic and imported formulations.
- Feline Therapeutic Diets:Renal and urinary health wet food prescriptions are pulling volume through veterinary clinics as Taipei cat ownership rates climb among apartment-dwelling professionals.
- Grain-Free R&D Investment:Domestic manufacturers are redirecting formulation budgets toward clean-label ingredient decks, capturing margin premiums from label-conscious urban buyers.
Market Restraints
- Import Mycotoxin Screening:Taiwan Food and Drug Administration pathogen thresholds create 14-21 day customs delays for European and North American suppliers, elevating working capital requirements.
- Single-Source Protein Concentration:Reliance on Thai and Australian chicken meal suppliers exposes formulators to avian influenza disruption cycles and price volatility.
- Wet Food Shelf Stability:Retort packaging limitations constrain distribution radius for high-moisture therapeutic diets, restricting rural pharmacy penetration.
Strategic Opportunities
- E-Commerce Subscription Models:Recurring delivery platforms in New Taipei City and Taichung bypass traditional retail markups, capturing lifetime value from multi-cat households.
- Senior Cat Functional Nutrition:Cognitive support and joint health formulations targeting cats aged 10+ represent underdeveloped white space with minimal domestic competition.
- ISO 22000 Certification Arbitrage:Small-batch producers achieving food safety management certification can displace unbranded imports in veterinary clinic exclusivity agreements.
Industry Challenges
- Veterinary Nutritionist Shortage:Taiwan lacks sufficient board-certified animal nutritionists to staff regulatory affairs and formulation teams at scaling manufacturers.
- Legacy ERP Integration:Domestic producers running on-premise inventory systems face friction migrating to cloud-based lot-traceability platforms required by Council of Agriculture audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Pet Food Market |
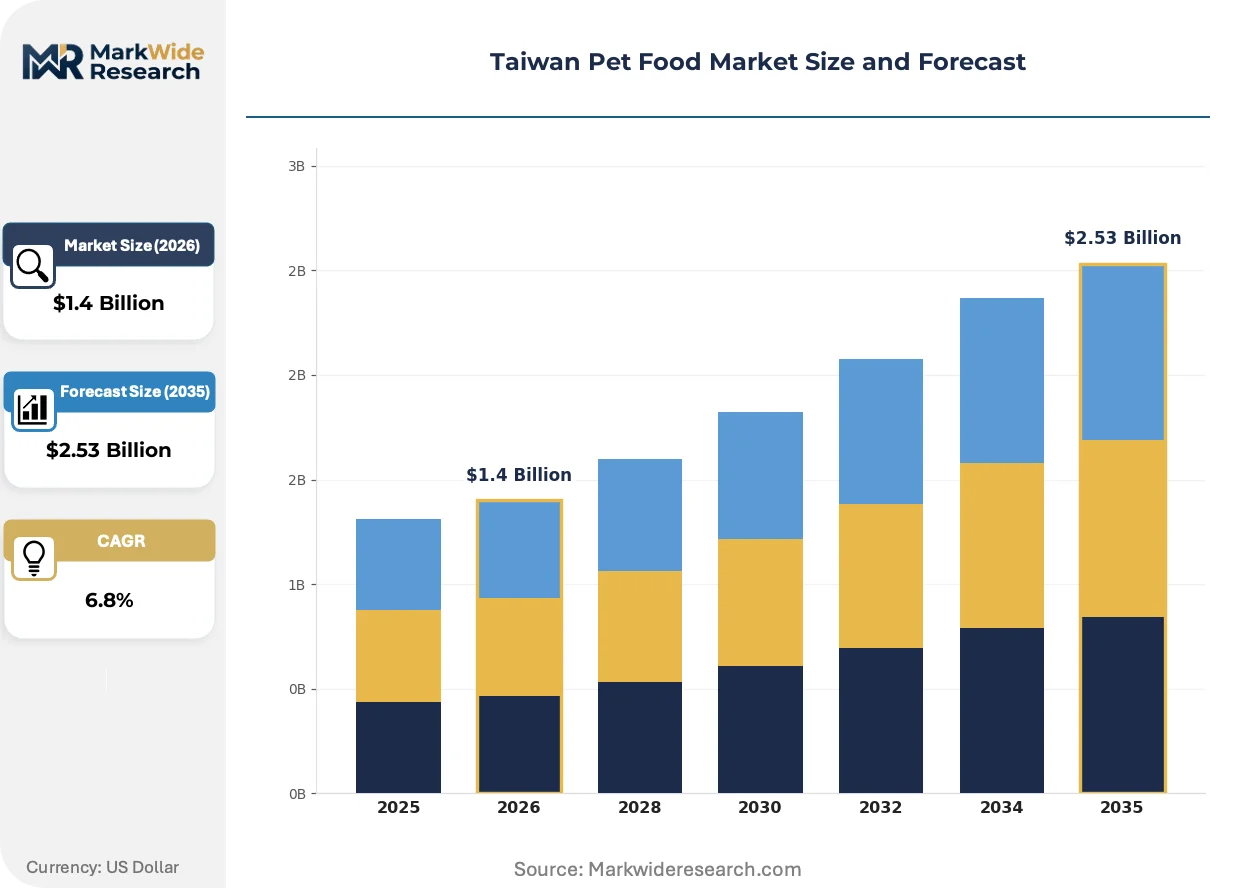
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Birds, Small Animals Distribution Channel: Supermarkets, Online Retail, Pet Shops, Veterinary Clinics Ingredient Quality: Natural, Organic, Grain-Free, Feed Grade |
| Companies Covered | General Mills Inc. (Blue Buffalo), Han Shuo Food Co. Ltd., Mars Inc., YOYO Chic Intl. Co. Ltd., Pettric Pet Food Co. Ltd., Nestlé Purina PetCare, Yoda Pet Food Co. Ltd., J.M. Smucker Company (Nutrish), Colgate-Palmolive Company (Hill's Pet Nutrition), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Pet Food Market Strategic Shifts
Formulation science and distribution architecture are diverging sharply, with biotechnology-enabled ingredient processing reshaping product pipelines while direct-to-consumer channels erode traditional retail gatekeepers.
Cold-pressed protein processing is fragmenting conventional extrusion dominance in dry food manufacturing. This method preserves amino acid bioavailability at lower thermal thresholds. Premium domestic brands in Taipei are adopting it to justify 40-60% price premiums over mass-market kibble. The technology is fragmenting equipment supplier relationships as Taiwanese manufacturers bypass European machinery vendors for South Korean press systems.
Taiwan's Council of Agriculture amended the Animal Industry Act inspection protocols in 2024, mandating real-time temperature logging for imported refrigerated wet food shipments. Cold chain compliance costs have eliminated marginal importers from the veterinary channel. Domestic producers with captive cold storage in Taoyuan are absorbing displaced volume and securing multi-year clinic contracts.
Subscription-based replenishment is displacing supermarket bulk purchasing among Taipei millennials. Automated reorder algorithms linked to RFID-enabled smart feeders are capturing consumption data that manufacturers leverage for personalized formulation recommendations. This behavioral shift concentrates most visibly in Da'an and Xinyi districts, where pet tech adoption rates exceed national averages by significant margins.
Taiwan Pet Food Market Segmentation
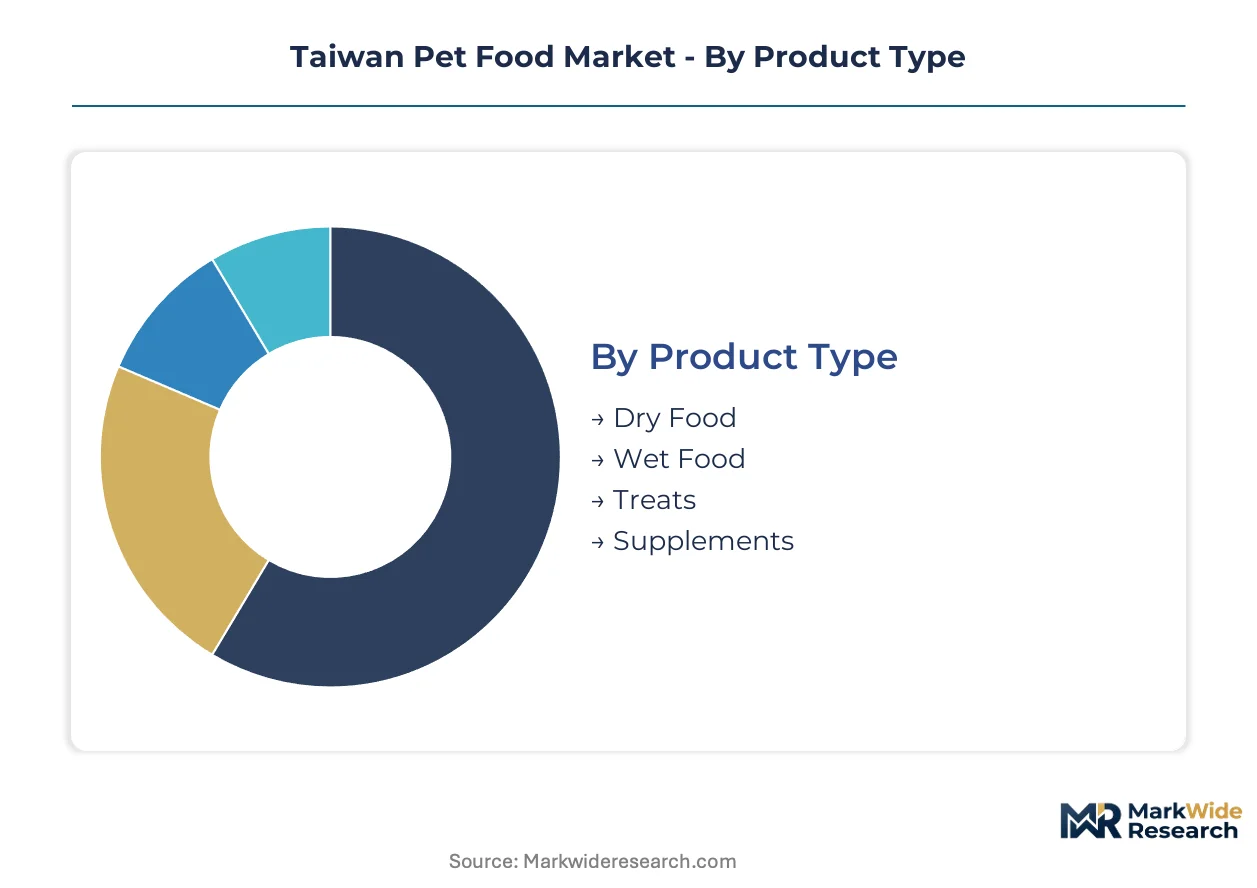
Taiwan's pet food market segments reflect divergent compliance burdens and margin structures. Council of Agriculture labeling mandates and FDA import screening create asymmetric cost profiles across product categories, rewarding suppliers with dedicated regulatory infrastructure.
Product Type:
The Council of Agriculture applies distinct moisture-content thresholds and additive disclosure rules to each formulation class, determining registration complexity and shelf-life claims.
- Dry Food:Extruded kibble with 6-10% moisture content dominates volume throughput in Taichung warehouse clubs and New Taipei hypermarkets. Taipei apartment dwellers favor 10-15kg bulk formats for storage efficiency in constrained living spaces.
- Wet Food:Retort-pouched formulations with 75-85% moisture capture margin concentration through veterinary prescription positioning. Renal and urinary health variants pull disproportionate volume through Taipei clinic networks as feline ownership concentrates among professionals.
- Treats:Functional dental chews and training rewards occupy impulse-purchase positioning in pet shop checkout lanes.
- Supplements:Omega-3 and probiotic add-ons target aging pet demographics through online subscription bundling.
Dry food handles the majority of throughput; wet food is the fastest mover on share.
Animal Type:
Species-specific nutritional standards from AAFCO and FEDIAF create formulation specialization barriers that domestic manufacturers exploit against generic importers.
- Cats:Obligate carnivore protein requirements drive premiumization in Taipei urban corridors. Grain-free and limited-ingredient diets for indoor cats aged 10+ attract R&D investment from ISO-certified domestic producers.
- Dogs:Breed-size segmentation and therapeutic weight management prescriptions sustain veterinary channel relevance.
- Birds:Psittacine pellet formulations serve concentrated hobbyist communities in Kaohsiung.
- Small Animals:Rabbit and guinea pig hay-supplement bundles occupy niche pet shop shelf space.
Cat nutrition commands the steepest margin expansion; dog food retains the broadest distribution footprint.
Distribution Channel:
Fulfillment infrastructure requirements fragment channel economics, with cold-chain mandates eliminating marginal players from veterinary and premium online segments.
- Veterinary Clinics:Therapeutic diet exclusivity agreements lock in recurring revenue from chronic condition management. Taoyuan-based cold storage operators capture displaced import volume through multi-year service contracts.
- Online Retail:Subscription algorithms linked to RFID-enabled feeders capture consumption data in Da'an and Xinyi districts. Automated replenishment bypasses traditional retail markups for multi-pet households.
- Supermarkets:Mass-market dry food and treat assortments serve price-sensitive bulk purchasers.
- Pet Shops:Curated premium assortments and live-animal cross-selling sustain foot traffic in neighborhood formats.
Online retail is expanding most quickly; veterinary clinics defend the highest customer lifetime value.
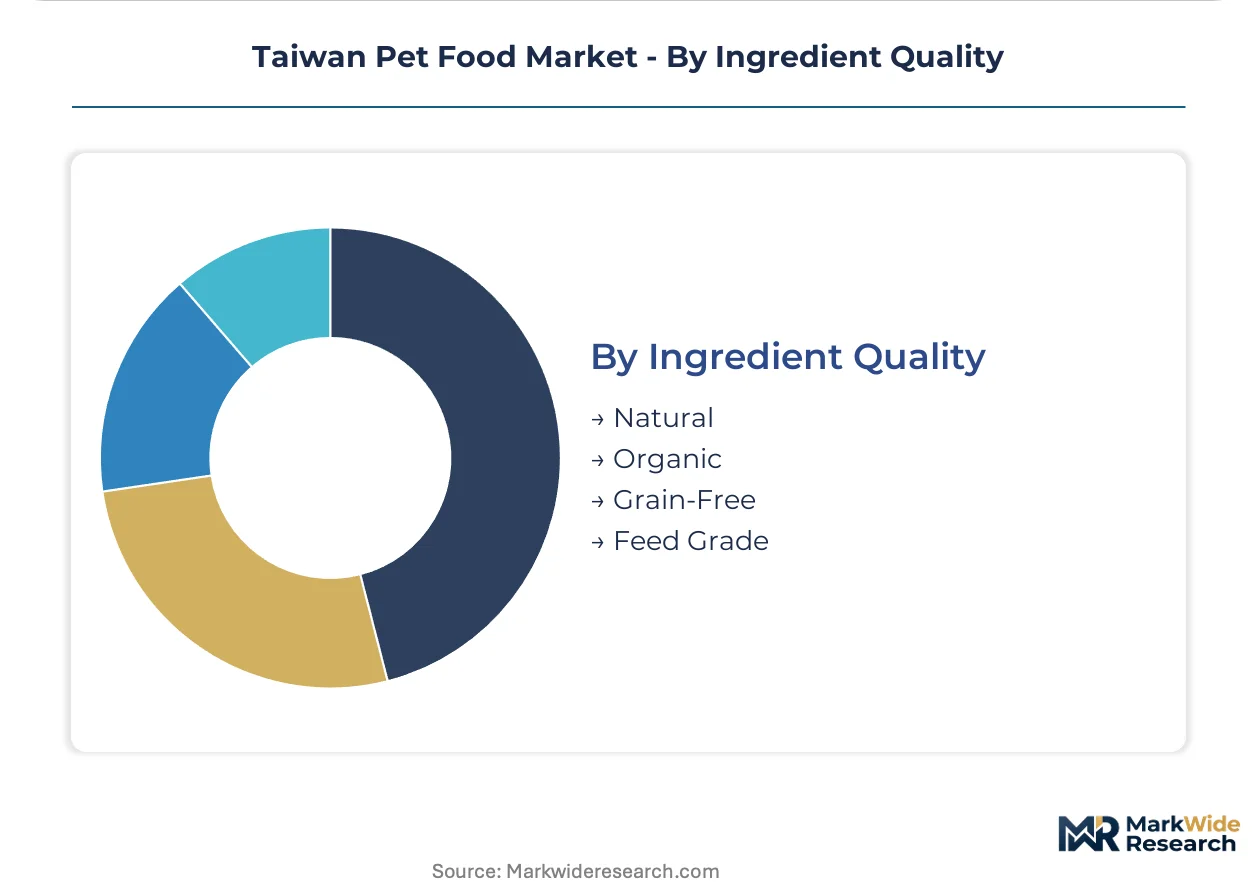
Ingredient Quality:
Clean-label certification tiers separate veterinarian-endorsed therapeutic positioning from mass-market nutrition lines, with ISO 22000 compliance becoming a baseline clinic admission requirement.
- Grain-Free:Legume and tuber carbohydrate substitutes command 40-60% price premiums in Taipei premium channels. Cold-pressed processing adoption justifies label claims of enhanced amino acid bioavailability.
- Natural:Minimal-processing claims without synthetic additives attract margin-conscious urban buyers seeking transparency.
- Organic:Certified ingredient sourcing remains limited by domestic agricultural supply constraints.
- Feed Grade:Commodity formulations serve cost-optimized shelter and breeder procurement.
Grain-free holds the dominant revenue position; natural is climbing the fastest on share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing capacity clusters around Taoyuan's cold storage corridor, where ISO-certified facilities exploit import compliance gaps to capture displaced veterinary channel volume. Taipei anchors consumption through apartment-dwelling professionals driving premium cat nutrition demand.
Taipei
Da'an and Xinyi districts concentrate RFID-enabled smart feeder adoption among millennial cat owners, generating consumption data streams that manufacturers leverage for personalized formulation recommendations. Council of Agriculture labeling mandates accelerate premium product registration timelines for domestic suppliers. Veterinary clinic consolidation in the capital compresses distribution pathways, forcing manufacturers to secure direct partnerships or lose therapeutic-grade shelf access.
New Taipei City
E-commerce subscription platforms bypass traditional retail markups to capture lifetime value from multi-cat households through automated replenishment algorithms. The Food and Drug Administration's mycotoxin screening protocols create 14-21 day customs delays for imported formulations, elevating working capital requirements that favor local fulfillment operators. Cold-chain logistics providers in Linkou and Zhonghe absorb displaced import volume through multi-year service contracts.
Taichung
Warehouse clubs and hypermarkets in the central region serve price-sensitive bulk purchasers with 10-15kg dry food formats optimized for storage efficiency. Han Shuo Food Co. Ltd. sustains domestic manufacturing scale from ISO-compliant facilities serving private-label contracts to regional distributors. The city's industrial parks host equipment suppliers adopting South Korean cold-press systems to justify 40-60% price premiums over mass-market kibble.
Taoyuan
Captive cold storage infrastructure eliminates marginal importers from veterinary channel competition following 2024 Animal Industry Act amendments mandating real-time temperature logging for refrigerated wet food shipments. Domestic producers with compliant facilities secure multi-year clinic exclusivity agreements for therapeutic diet distribution. The logistics corridor connects manufacturing capacity to Taipei consumption centers through temperature-controlled distribution networks.
Kaohsiung
Psittacine pellet formulations serve concentrated hobbyist communities in southern Taiwan's bird-keeping subculture, occupying niche pet shop shelf space with species-specific nutritional standards. Local retailers curate premium assortments alongside live-animal cross-selling to sustain neighborhood foot traffic. Import dependency for specialized avian ingredients exposes formulators to supply disruption cycles from Southeast Asian protein meal suppliers.
Taiwan Pet Food Market Competitive Environment
Concentration sits with multinational nutrition conglomerates anchoring therapeutic distribution through veterinary clinic partnerships, while domestic ISO-certified manufacturers capture displaced import volume in premium private-label segments. The competitive terrain fragments across three strategic tiers: veterinarian-endorsed therapeutic formulators, mass-market extruded kibble producers, and cold-pressed clean-label specialists. M&A activity targets regional cold storage assets to secure compliance advantage under amended Animal Industry Act protocols, while portfolio diversification into senior cat functional nutrition opens white space with minimal domestic competition.
Among multinational nutrition conglomerates, Mars Inc. and Nestlé Purina PetCare exemplify the therapeutic-tier archetype through specialized wet food formulations targeting renal health prescriptions. Within domestic manufacturing, Han Shuo Food Co. Ltd. represents ISO-certified scale production serving private-label contracts, while YOYO Chic Intl. Co. Ltd. occupies a position in the specialty segment. These named entities anchor industry-level commentary without constraining competitive dynamics to specific strategic actions or market positions.
| Leading Market Players |
|---|
| General Mills Inc. (Blue Buffalo) |
| Han Shuo Food Co. Ltd. |
| Mars Inc. |
| YOYO Chic Intl. Co. Ltd. |
| Pettric Pet Food Co. Ltd. |
| Nestlé Purina PetCare |
| Yoda Pet Food Co. Ltd. |
| J.M. Smucker Company (Nutrish) |
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| Others |
Value Chain & Pricing Dynamics
Multi-year clinic exclusivity contracts lock in both cold storage capacity and price visibility for domestic producers, insulating them from the 14-21 day customs delays that plague European and North American importers under Taiwan Food and Drug Administration mycotoxin screening protocols. These arrangements concentrate pricing power with ISO 22000-certified manufacturers in Taoyuan while marginal players absorb volatility in spot procurement for Thai and Australian chicken meal.
Pricing Analysis
The Council of Agriculture's Animal Industry Act dictates the pricing tier structure across veterinary therapeutic, premium clean-label, and mass-market feed-grade segments. Pricing stratifies across certification tiers, with ISO 22000 compliance and cold-pressed processing commanding 40-60% premiums over extruded kibble in Taipei premium channels. Cost compression in mass-market dry food is intensifying because warehouse club bulk formats face margin pressure from e-commerce subscription models. Price-sensitive bulk purchasers in Taichung hypermarkets drive volume, while least-sensitive millennial cat owners in Da'an district absorb premium positioning for grain-free functional diets.
Supply Chain Analysis
Container availability constraints on the Thailand-Taiwan and Australia-Taiwan trade lanes elevate inbound logistics costs for protein meal shipments, compressing margins for formulators without captive cold storage. Domestic manufacturing draws from Thai and Australian chicken meal suppliers, with secondary inputs of South Korean cold-press equipment and domestic legume carbohydrate substitutes. Single-source protein concentration exposes the supply chain to avian influenza disruption cycles. Distribution runs through Taoyuan's temperature-controlled logistics corridor to veterinary clinics and New Taipei e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's pet food market operates as a defensive-moat story where regulatory entrenchment through Council of Agriculture registration requirements and mandatory cold-chain compliance creates switching costs that protect incumbent positions.
For Market Incumbents: Consolidate veterinary channel access through multi-year clinic exclusivity agreements before cold storage capacity saturates in Taoyuan. Deepen backward integration into captive protein meal processing to offset Thai and Australian supplier volatility. ISO 22000 certification investment remains the critical lever for displacing unbranded imports in therapeutic distribution. For New Entrants and Emerging Players: Senior cat functional nutrition for cognitive support and joint health represents a service-layer gap where domestic competition remains minimal. Target this white space through direct-to-consumer subscription platforms in New Taipei City, bypassing the veterinary channel consolidation that blocks shelf access for unproven brands. Partner with RFID-enabled smart feeder manufacturers to capture consumption data for personalized formulation recommendations. For Investors and Strategic Acquirers: Regional cold storage operators with Council of Agriculture-compliant facilities present the most compelling acquisition target archetype, given the 2024 Animal Industry Act amendments eliminated marginal importers from veterinary competition. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch for inflection when subscription algorithm penetration in Da'an and Xinyi districts crosses threshold density for personalized nutrition platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Storage Capacity Expansion | Taoyuan-based ISO 22000 facilities capture displaced import volume under amended Animal Industry Act protocols. |
| Subscription Platform Development | Automated replenishment algorithms in New Taipei bypass traditional retail markups for multi-cat household lifetime value. |
| Senior Cat Functional Nutrition R&D | Cognitive support and joint health formulations target aging feline demographics with minimal domestic competition. |
| Veterinary Clinic Partnership Consolidation | Direct therapeutic distribution agreements lock out competitors as Taipei clinic networks compress. |
| Cold-Pressed Processing Equipment Adoption | South Korean press systems justify 40-60% price premiums through enhanced amino acid bioavailability claims. |
Study Parameters
Desk research of customs import records, Council of Agriculture registration filings, and veterinary clinic distribution databases preceded structured interviews with regulatory affairs directors at domestic manufacturers, procurement managers at Taipei veterinary networks, cold chain logistics operators in Taoyuan, and category buyers at New Taipei e-commerce platforms. Primary fieldwork combined with secondary validation from Taiwan Food and Drug Administration enforcement notices and AAFCO nutrient profile documentation. Bottom-up volume estimates from product registration data triangulated against top-down consumption surveys from RFID-enabled feeder deployment metrics.
Variance decomposition across the projection horizon isolates volume drivers by animal type, product moisture content, ingredient certification tier, and distribution channel fulfillment model. Segmentation dimensions include therapeutic versus wellness positioning, cold-pressed versus extruded processing, and subscription versus transactional purchase patterns. CAGRs derive from regression analysis of historical registration velocity and clinic network expansion rates, with inputs from feline ownership demographic shifts and e-commerce penetration curves in Taipei metropolitan zones.
Forecasts assume regulatory continuity in Taiwan's Animal Industry Act and Food and Drug Administration import screening regimes; material policy shifts would require re-modeling. Specific risk factors include avian influenza disruption to Thai and Australian protein meal supply, veterinary nutritionist shortage constraints on formulation team scaling, and legacy ERP migration friction for lot-traceability compliance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Pet Collar Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
US Dog Food Market