
 Baby Food Dispensing Spoon Market | 2026-2036
Baby Food Dispensing Spoon Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Food Dispensing Spoon Market Outlook
ISO 9001 quality management certification is collapsing the supplier base, forcing smaller manufacturers to either upgrade systems or exit. Munchkin leverages extensive retail distribution to sustain shelf presence across North American baby product stores. Béaba differentiates through design-forward positioning anchored by European safety credentials.
A baby food dispensing spoon integrates a reservoir chamber with a squeezable body or plunger mechanism, typically constructed from food-grade silicone or BPA-Free thermoplastic elastomer, to meter pureed food onto the spoon tip during feeding. The device serves commercial purpose by reducing mealtime mess and enabling single-handed feeding for caregivers. Squeeze Spoon configurations dominate unit volume due to intuitive operation, while Self-Feeding Spoon designs capture expanding margin pools as developmental feeding gains traction among toddler-age segments. Silicone material grades command premium positioning over standard plastic alternatives because of thermal stability and oral-safety profiles.
FDA food-contact substance regulations govern silicone and plastic material approvals in the United States, while the EU's REACH framework restricts phthalate and chemical migration across European markets. China's SAMR enforces GB standards for infant feeding products, creating a three-jurisdiction compliance burden for multinational suppliers. Stakeholders must monitor evolving material restrictions and certification reciprocity agreements to preserve cross-border market access.
Market Dynamics
ISO 9001 quality management certification is collapsing the supplier base, forcing smaller manufacturers to either upgrade systems or exit. This structural consolidation is reshaping competitive positioning as mid-tier producers face binary outcomes between compliance investment and market withdrawal.
Growth Catalysts
- REACH chemical migration limits:The EU's phasing of stricter phthalate restrictions is accelerating material substitution toward medical-grade silicone across European supply chains.
- Single-handed feeding functionality:Millennial and Gen-Z parents prioritize ergonomic designs that enable smartphone multitasking during meal preparation and feeding routines.
- Online retail channel expansion:Direct-to-consumer platforms are compressing traditional wholesale margins while capturing first-time parent segments in the United States.
Market Restraints
- Food-grade silicone price volatility:Silicone raw material costs fluctuate with petrochemical feedstock indices, squeezing margin structures for non-integrated assemblers.
- Three-jurisdiction compliance burden:Simultaneous FDA, REACH, and GB standard enforcement creates fixed regulatory overhead that disadvantages smaller exporters.
- Reusable squeeze pouch substitution:Stand-up pouch formats with spout attachments compete for the same feeding-convenience use case at lower per-unit price points.
Strategic Opportunities
- German premium retail expansion:Pharmacy and organic specialty chains in Germany command price premiums for CE-marked, design-forward feeding accessories.
- Self-feeding developmental application:Toddler-age segments between 12-24 months represent an emerging use case beyond traditional infant feeding windows.
- SAMR certification reciprocity:China's evolving mutual recognition agreements with EU notified bodies could streamline dual-market entry for compliant manufacturers.
Industry Challenges
- ISO 13485 medical device pathway complexity:Manufacturers pursuing clinical-grade positioning face 18-24 month certification timelines that delay revenue recognition.
- Multi-material assembly integration:Bonding silicone reservoirs to thermoplastic handles requires specialized molding expertise that concentrates among East Asian contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Food Dispensing Spoon Market |
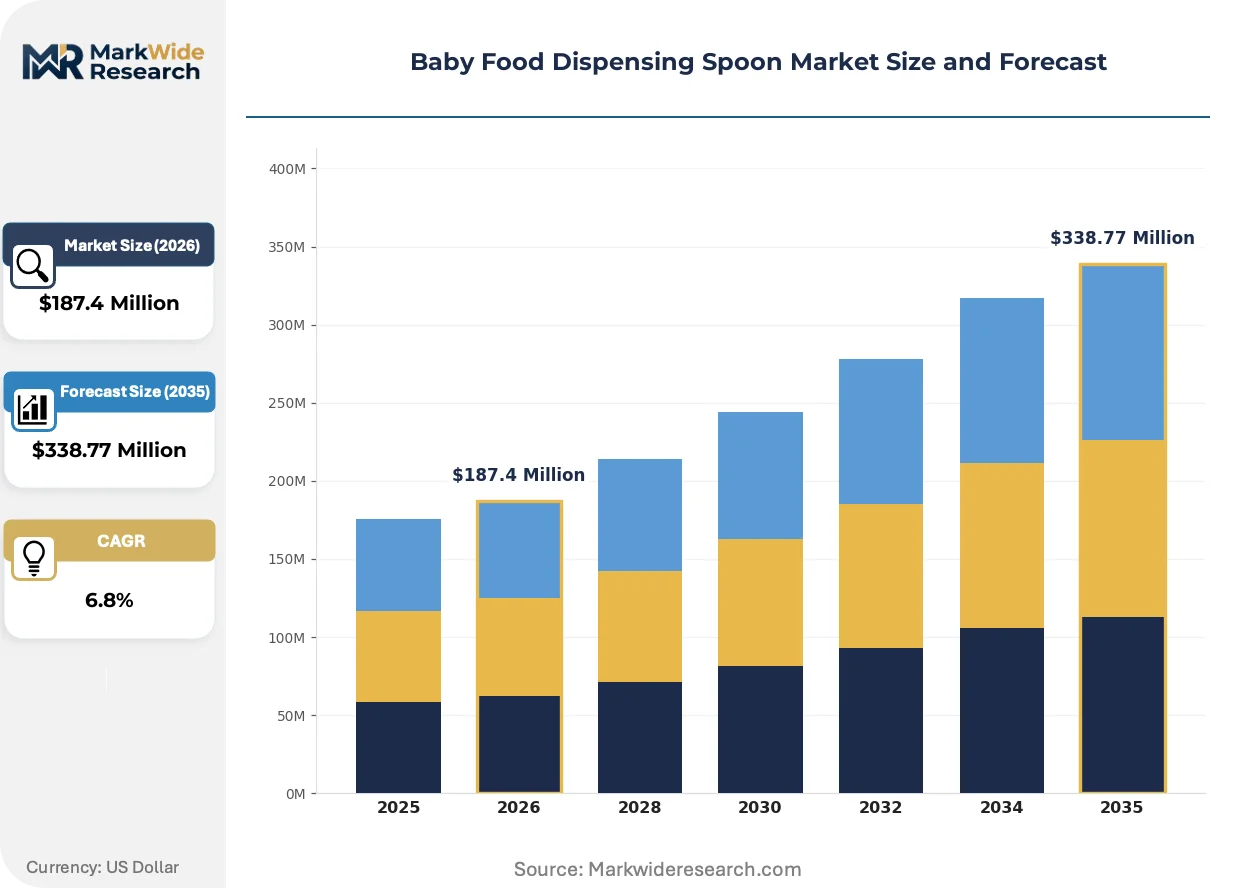
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Squeeze Spoon, Self-Feeding Spoon, Portion Controlled Spoon, Dispensing Syringe Material: Silicone, Plastic, Stainless Steel, BPA-Free Age Group: Infants, Toddlers, Newborns, Children Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Baby Product Stores |
| Companies Covered | Olababy, SAMiGO, WeeSprout, Oxo Tot, EZPZ, Béaba, Nuby, Munchkin, Bumkins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Food Dispensing Spoon Market Strategic Shifts
Material science advances and regulatory harmonization pressures are decomposing traditional product architectures. These forces are creating openings for modular designs that separate disposable from durable components while satisfying tightening chemical safety mandates.
Platinum-cured liquid silicone rubber is decomposing conventional peroxide-cured alternatives in premium product tiers. Millennial parents purchasing through specialty baby retailers now specify thermal stability above 200°C for microwave sterilization compatibility. This material transition is compressing margin pools for manufacturers locked into commodity-grade silicone supply agreements.
China's SAMR is tightening GB 4806 series standards for food-contact plastics and silicones used in infant products. The industrial consequence is a wave of pre-market testing requirements that extend product development cycles by 4-6 months. Domestic Chinese brands with established testing laboratory relationships are responding faster than import-dependent competitors.
Subscription-based replenishment models are displacing one-time purchase patterns among digitally native parents. Direct-to-consumer channels in the United States are capturing recurring revenue through silicone tip replacement programs bundled with pediatric nutrition content. This behavior shift is most visible in coastal metropolitan markets where same-day delivery infrastructure supports impulse replenishment cycles.
Baby Food Dispensing Spoon Market Segmentation
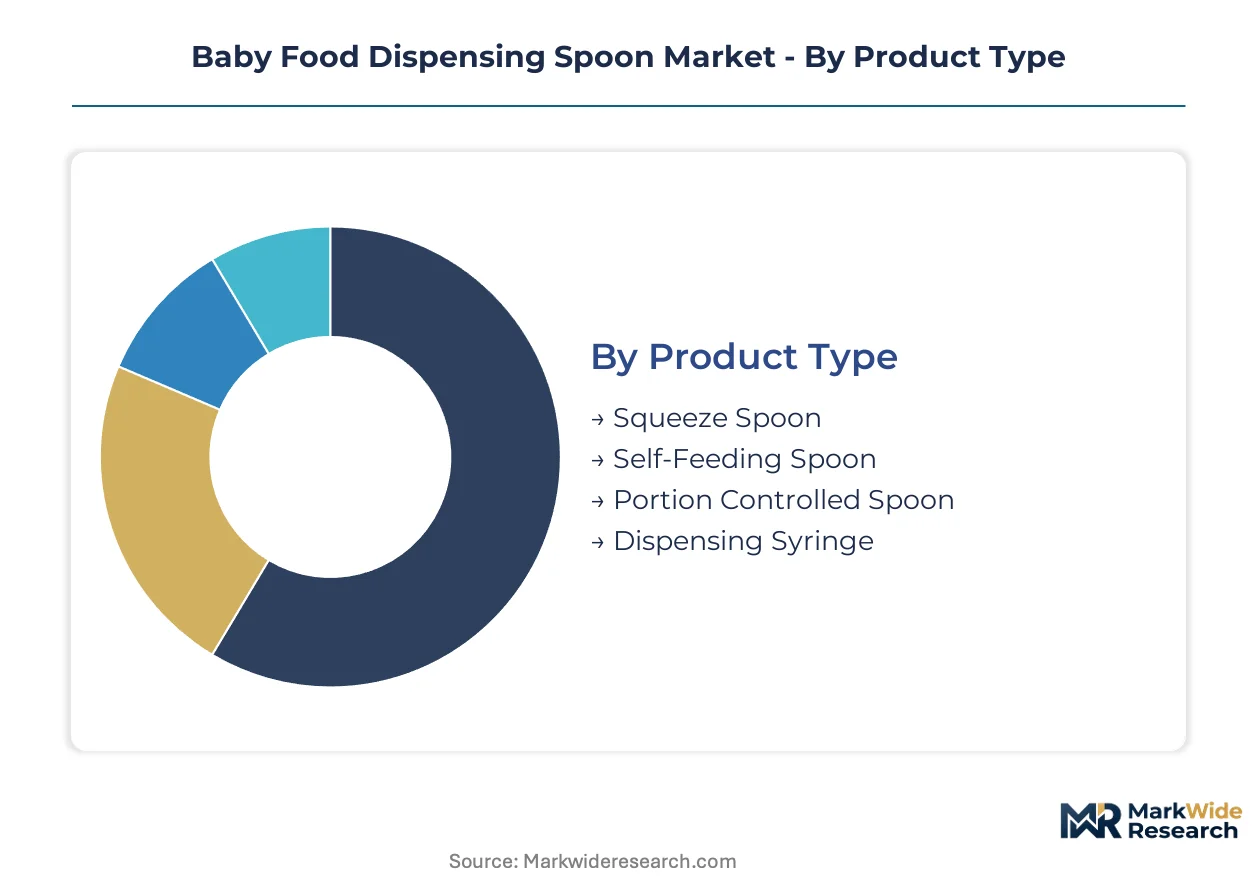
Segmentation in baby food dispensing spoons reveals how feeding-stage requirements and caregiver purchasing patterns fragment demand across distinct product architectures. Understanding these divisions exposes where margin pools concentrate and which material and channel combinations command sustainable price premiums.
Product Type:
Export-led demand concentrates in Squeeze Spoon configurations shipped to North American and European premium retailers, while Self-Feeding Spoon development remains domestically concentrated in Chinese manufacturing clusters serving local millennial parents.
- Squeeze Spoon:Integrates a squeezable silicone body with a reservoir chamber that meters pureed food through a perforated tip during compression. Demand clusters in United States coastal metropolitan markets where single-handed feeding functionality supports smartphone multitasking behaviors among Millennial caregivers.
- Self-Feeding Spoon:Features rigid handles with shallow scoop geometries engineered for toddler grip autonomy and oral motor development. German pharmacy and organic specialty chains command price premiums for CE-marked variants as developmental feeding gains traction among 12-24 month age segments.
- Portion Controlled Spoon:Incorporates pre-measured chamber volumes to standardize serving sizes for nutritional tracking.
- Dispensing Syringe:Utilizes plunger-driven mechanisms for precise flow control during therapeutic or high-viscosity feeding applications.
Squeeze Spoon holds the largest share; momentum sits with Self-Feeding Spoon as developmental feeding applications expand beyond traditional infant windows.
Material:
Cost tier stratification separates medical-grade silicone commanding premium positioning from commodity plastics facing margin compression from petrochemical feedstock volatility.
- Silicone:Platinum-cured liquid silicone rubber delivers thermal stability above 200°C for microwave sterilization compatibility. REACH phthalate restrictions across European supply chains are accelerating substitution toward medical-grade grades that satisfy EFSA migration limits.
- Plastic:BPA-Free thermoplastic elastomers offer lower unit economics for price-sensitive mass-market penetration. FDA food-contact substance regulations and China's GB 4806 series standards impose pre-market testing burdens that extend development cycles for non-integrated assemblers.
- Stainless Steel:Durable metal reservoirs paired with silicone tips target longevity-focused sustainable purchasing segments.
- BPA-Free:Certification-marked materials satisfy tightening chemical safety mandates across United States, EU, and Chinese regulatory jurisdictions.
Silicone dominates premium tier revenue; plastic maintains volume leadership in emerging market penetration.
Age Group:
Application maturity varies sharply, with infant feeding representing established replacement-cycle demand while toddler segments present greenfield expansion opportunity.
- Infants:Traditional 4-12 month feeding window drives baseline replacement demand through standardized silicone tip configurations.
- Toddlers:12-24 month developmental feeding applications represent the steepest expansion trajectory as self-feeding skill acquisition extends product relevance beyond conventional infant windows.
- Newborns:Specialized low-volume reservoirs address early feeding coordination challenges in 0-3 month segments.
- Children:Extended-use designs accommodate neurodivergent feeding requirements and therapeutic applications.
Infant segments anchor current revenue; toddler applications are climbing the fastest as developmental feeding positioning gains traction.
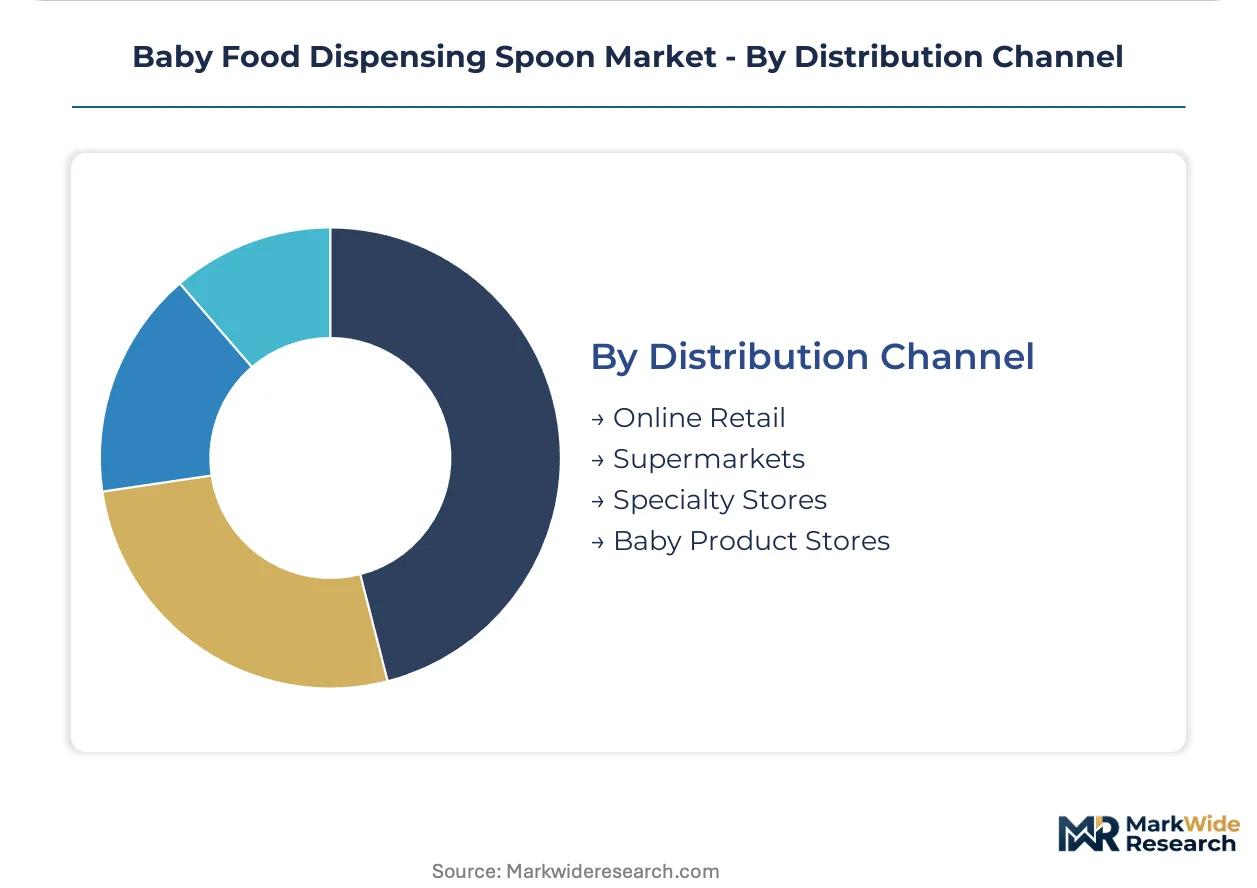
Distribution Channel:
Customer type bifurcation separates digitally native parents seeking subscription replenishment from traditional shoppers prioritizing tactile product evaluation.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through silicone tip replacement programs bundled with pediatric nutrition content. Same-day delivery infrastructure in United States coastal markets supports impulse replenishment cycles among subscription-adopting Millennial and Gen-Z parents.
- Specialty Stores:Pharmacy and organic baby chains in Germany command price premiums for design-forward, CE-marked feeding accessories with demonstrated safety credentials.
- Supermarkets:Mass-market shelf presence targets first-time parent segments through impulse purchase placement adjacent to baby food categories.
- Baby Product Stores:North American specialty retailers sustain Munchkin's extensive retail distribution through dedicated shelf space and staff recommendation authority.
Online Retail captures the fastest share gain; Baby Product Stores defend the largest absolute volume position through established retail relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen-Z parents in premium urban markets drive demand concentration, with purchasing patterns diverging sharply between digitally native subscription adopters and traditional retail-dependent segments.
United States
Coastal metropolitan markets anchor North American demand as smartphone-multitasking caregivers prioritize single-handed feeding functionality. FDA food-contact substance regulations govern silicone and plastic material approvals, creating pre-market testing burdens for new entrants. Los Angeles and New York City retail corridors sustain specialty baby store networks that command staff recommendation authority.
Germany
Pharmacy and organic specialty chains extract price premiums for CE-marked, design-forward feeding accessories. ECHA REACH phthalate restrictions accelerate material substitution toward medical-grade silicone across European supply chains. Bavaria's industrial testing infrastructure supports rapid certification turnaround for domestic brands.
China
SAMR GB 4806 series standards tighten food-contact requirements for infant feeding products, extending development cycles by 4-6 months. Yangtze River Delta manufacturing clusters concentrate multi-material assembly expertise for bonding silicone reservoirs to thermoplastic handles. Shanghai-based domestic brands leverage established laboratory relationships to outpace import-dependent competitors.
Japan
METI industrial standards and PMDA safety frameworks impose rigorous material migration testing for infant product categories. Kanto region retail density supports premium positioning for platinum-cured silicone configurations with microwave sterilization compatibility. Tokyo metropolitan parents demonstrate early adoption of subscription-based silicone tip replacement programs.
United Kingdom
Post-Brexit regulatory divergence from EU REACH creates dual compliance obligations for suppliers serving both markets. London and Southeast England concentrate direct-to-consumer platform adoption among digitally native parent segments. Midlands distribution hubs facilitate cross-border fulfillment into continental European markets.
Baby Food Dispensing Spoon Market Competitive Environment
Player mix skews toward design-forward specialists and mass-market retail incumbents competing across distinct price-performance tiers. Market structure exhibits moderate consolidation with ISO 9001 certification requirements forcing smaller manufacturers toward upgrade investment or exit. Two strategic archetypes dominate: European safety-credential specialists and North American retail distribution scale players. Competitive moves concentrate on M&A-driven portfolio diversification and direct-to-consumer channel expansion.
Within the design-specialist tier, Béaba exemplifies European safety-credential positioning, while Munchkin anchors North American retail distribution scale. Olababy occupies a position among silicone-focused product innovators. These three entities represent the dominant competitive archetypes: CE-marked premium positioning, shelf-presence scale advantage, and material-science specialization.
| Leading Market Players |
|---|
| Olababy |
| SAMiGO |
| WeeSprout |
| Oxo Tot |
| EZPZ |
| Béaba |
| Nuby |
| Munchkin |
| Bumkins |
| Others |
Value Chain & Pricing Dynamics
Long-term silicone supply contracts with petrochemical indexation lock in both raw material access and margin predictability for baby food dispensing spoon manufacturers navigating volatile feedstock markets. These arrangements tether pricing power to global energy benchmarks while insulating integrated producers from spot market swings that compress assembler margins.
Pricing Analysis
Cost-plus contracts indexed to silicone feedstock benchmarks dominate procurement between Yangtze River Delta molders and North American brand owners. Three-tier pricing structure across platinum-cured medical grade, peroxide-cured standard grade, and BPA-Free thermoplastic separates certification tiers. Cost compression in commodity plastic segments is intensifying because of GB 4806 pre-market testing burdens. Mass-market supermarket buyers exhibit highest price sensitivity; German pharmacy chains demonstrate lowest.
Supply Chain Analysis
Multi-material bonding expertise concentrates in Dongguan and Shenzhen industrial corridors, creating a chokepoint for silicone-to-thermoplastic assembly integration. Raw material flows draw from Singapore petrochemical refineries, Zhangjiagang silicone polymer plants, and Guangdong colorant compounders. Single-source vulnerability runs through platinum-cured liquid silicone rubber suppliers qualified for FDA food-contact substance approvals. Distribution runs through Los Angeles and Rotterdam port gateways into direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
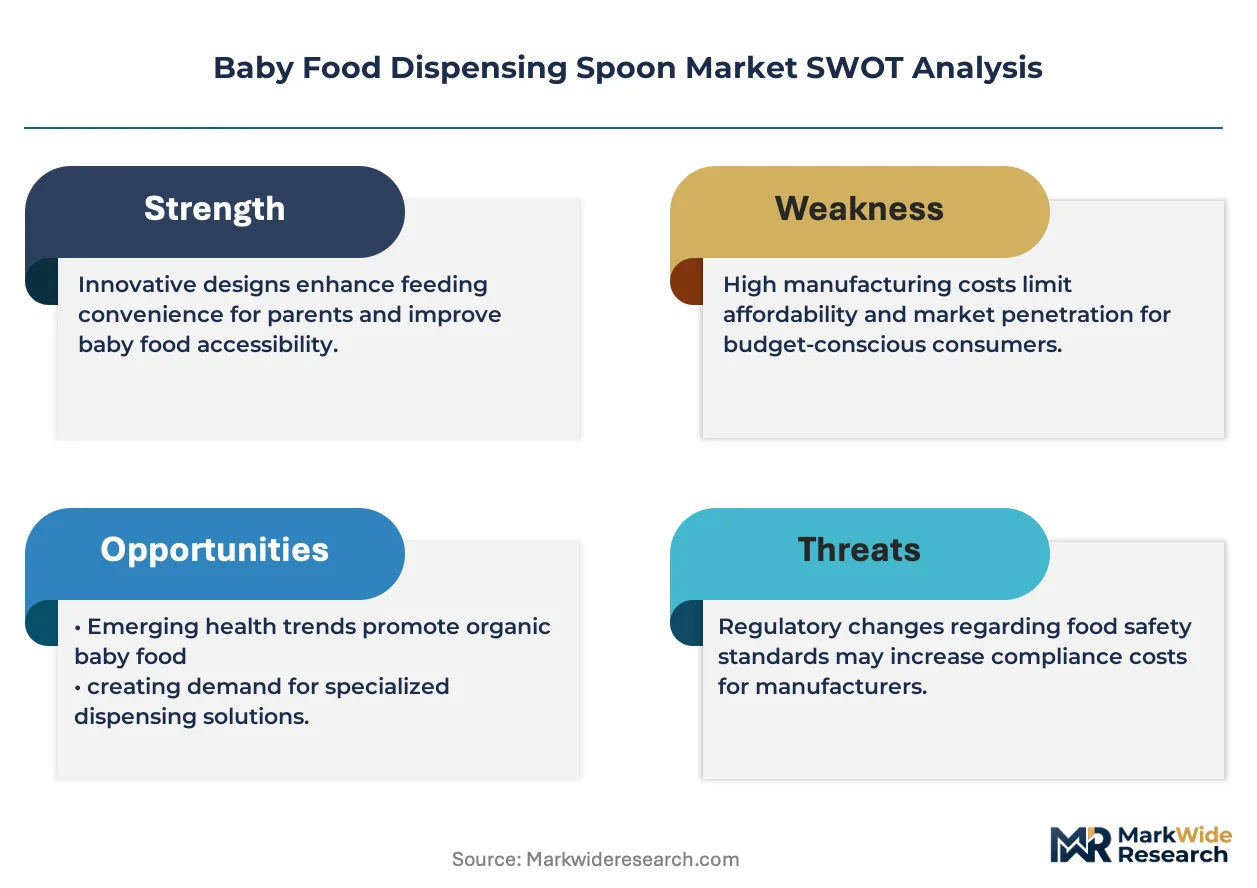
Incumbents face a substitution defense against reusable squeeze pouch formats that compete for the same feeding-convenience use case at lower per-unit economics. Reusable pouch substitution threatens to commoditize the core value proposition unless manufacturers differentiate through developmental feeding positioning and subscription replenishment lock-in.
For Market Incumbents: Secure exclusive platinum-cured silicone supply agreements with Zhangjiagang polymer plants to defend margin position against feedstock volatility. Deepen backward integration into mold fabrication capabilities to reduce dependency on Dongguan contract manufacturers for multi-material bonding expertise. Counter reusable pouch substitution by bundling silicone tip replacement programs with pediatric nutrition content subscriptions. For New Entrants and Emerging Players: Anchor in German pharmacy and organic specialty chains where CE-marked, design-forward feeding accessories command price premiums unavailable in mass-market channels. Target the 12-24 month toddler developmental feeding segment as the most penetrable white space beyond saturated infant feeding windows. Pursue SAMR certification reciprocity pathways to streamline dual-market entry into China and EU markets simultaneously. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors ISO 9001-certified mid-tier manufacturers with established laboratory testing relationships. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone, positioning certified contract manufacturers as attractive acquisition targets. Watch for SAMR-EU mutual recognition agreement announcements as the inflection signal for streamlined cross-border market access.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Silicone Transition | REACH phthalate restrictions accelerate medical-grade substitution across European supply chains. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models capture recurring revenue from digitally native Millennial parents. |
| SAMR Certification Reciprocity Pursuit | Mutual recognition agreements with EU notified bodies streamline dual-market entry pathways. |
| Developmental Feeding Product Extension | Toddler-age 12-24 month segments expand addressable market beyond traditional infant windows. |
| Multi-Material Assembly Integration | In-house bonding capabilities reduce dependency on concentrated East Asian contract manufacturers. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with product development leads at silicone molding specialists, regulatory affairs managers navigating FDA and SAMR frameworks, category buyers at North American baby product retailers, and procurement directors at German pharmacy chains; alongside secondary validation through FDA food-contact substance filings, SAMR GB standard registration databases, ECHA REACH restriction updates, and customs trade flow records. Bottom-up manufacturer capacity assessments triangulated against top-down channel revenue estimates.
Across the projection horizon, the analytical framework modeled volume and value trajectories across product type, material grade, age group application, and distribution channel dimensions. CAGRs derived from regression analysis of historical replacement cycle patterns, channel shift elasticities, and regulatory compliance cost pass-through coefficients. Silicone feedstock price indices and online retail penetration curves served as key industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory reciprocity and feedstock price assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as SAMR-EU mutual recognition negotiations and REACH phthalate restriction phase-ins evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Baby Bottle Warmers Market
Baby Products
Pregnancy Products Market
Baby Products
Baby High Chair Market
Baby Products
LAMEA Baby Care Products Market
Baby Products
Indonesia Baby Care Products Market
Baby Products
Baby Wipes Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Smart Baby Monitor Market
Baby Products
Baby Wet Wipes Market
Baby Products
Sippy Cups Market
Baby Products
Crib Mattress Market
Baby Products
Global Baby Product Market
Baby Products
Travel Pillow Market
Baby Products
Baby Digital Monitor Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Baby Walker Market