
 Smart Pet Collar Market | 2026-2036
Smart Pet Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pet Collar Market Outlook
Specialty pet retail is narrowing as veterinary clinics and direct-to-consumer platforms capture higher-margin collar sales. Garmin leverages its GPS heritage to dominate rugged outdoor tracking segments. Tractive sustains European market presence through localized cellular partnerships. Halo Collar differentiates via proprietary geofencing software tied to subscription services.
A smart pet collar integrates sensors for location tracking, biometric monitoring, and behavioral analysis within a wearable form factor typically rated IP67 or higher for water and dust resistance. The device transmits data via Bluetooth, Wi-Fi, or cellular protocols to enable real-time owner alerts and veterinary dashboards. GPS Trackers anchor current revenue due to universal appeal among dog owners, while Health Monitors represent the fastest-expanding category as chronic disease management shifts toward preventive, data-driven models. Bluetooth-enabled collars occupy the economy tier, whereas cellular-connected units command premium positioning through persistent coverage independent of smartphone proximity.
FCC emission standards in the United States, CE marking requirements under EU Radio Equipment Directive, and REACH substance restrictions on wearable materials collectively elevate compliance costs for cross-border manufacturers. The EU AI Act introduces emerging scrutiny on algorithmic health interpretations generated by collar sensors, prompting firms to clarify diagnostic boundaries. Stakeholders must weigh subscription revenue durability against hardware margin compression as cellular data plans and cloud analytics become the primary profit centers.
Market Dynamics
Cellular-enabled health monitoring is displacing Bluetooth-only designs as veterinary clinics demand continuous biometric data streams independent of owner smartphone proximity. FCC emission standards and REACH substance restrictions are simultaneously tightening hardware specifications while subscription revenue models restructure profit pools toward cloud analytics.
Growth Catalysts
- Veterinary Remote Monitoring:Post-surgical and chronic condition management programs in North American and European clinics are standardizing collar-integrated patient dashboards. This institutional procurement channel locks in multi-year hardware refresh cycles.
- EU AI Act Algorithmic Scrutiny:Emerging diagnostic boundary requirements for sensor-generated health interpretations are forcing manufacturers to clarify veterinary versus consumer-grade claims. This regulatory clarity accelerates clinical adoption by reducing liability ambiguity.
- German Urban Density:Dense pet ownership in German metropolitan corridors combined with advanced veterinary digitization creates concentrated demand for GPS and health-monitoring collars with persistent cellular connectivity.
Market Restraints
- Modular Radio Cost Structure:FCC electromagnetic emission standard tightening pushes manufacturers toward modular cellular radio designs. This component substitution elevates bill-of-materials costs versus integrated chip architectures.
- CE Marking Compliance Burden:EU Radio Equipment Directive certification timelines and REACH substance testing for wearable skin-contact materials extend product launch windows by four to six months for cross-border manufacturers.
- Cellular Subscription Dependency:Persistent coverage requirements tether hardware margins to carrier data plan negotiations. Operator concentration in rural coverage gaps limits addressable market expansion for premium cellular-enabled units.
Strategic Opportunities
- Preventive Health Data Monetization:Chronic disease management shifts toward data-driven models create white space for predictive analytics subscriptions. Veterinary insurers represent an emerging channel for risk-adjusted premium pricing tied to collar-reported activity metrics.
- Geofencing Software Differentiation:Proprietary boundary-training algorithms tied to recurring subscription revenue are displacing hardware-only positioning in premium segments. This convergence of GPS hardware and behavioral AI creates defensible recurring revenue streams.
- Direct-to-Consumer Platform Capture:Specialty pet retail contraction opens channel space for manufacturer-owned e-commerce and veterinary clinic partnerships. These routes capture margin otherwise lost to distributor markups.
Industry Challenges
- Biometric Sensor Calibration Expertise:Veterinary-grade accuracy requirements for heart rate variability and temperature monitoring demand specialized firmware engineering talent. This skill scarcity constrains product development velocity for mid-tier manufacturers.
- Cross-Border Certification Parallel Processing:Simultaneous FCC, CE marking, and REACH compliance documentation creates administrative overhead. Manufacturers face timeline compression risks when regulatory interpretations diverge across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pet Collar Market |
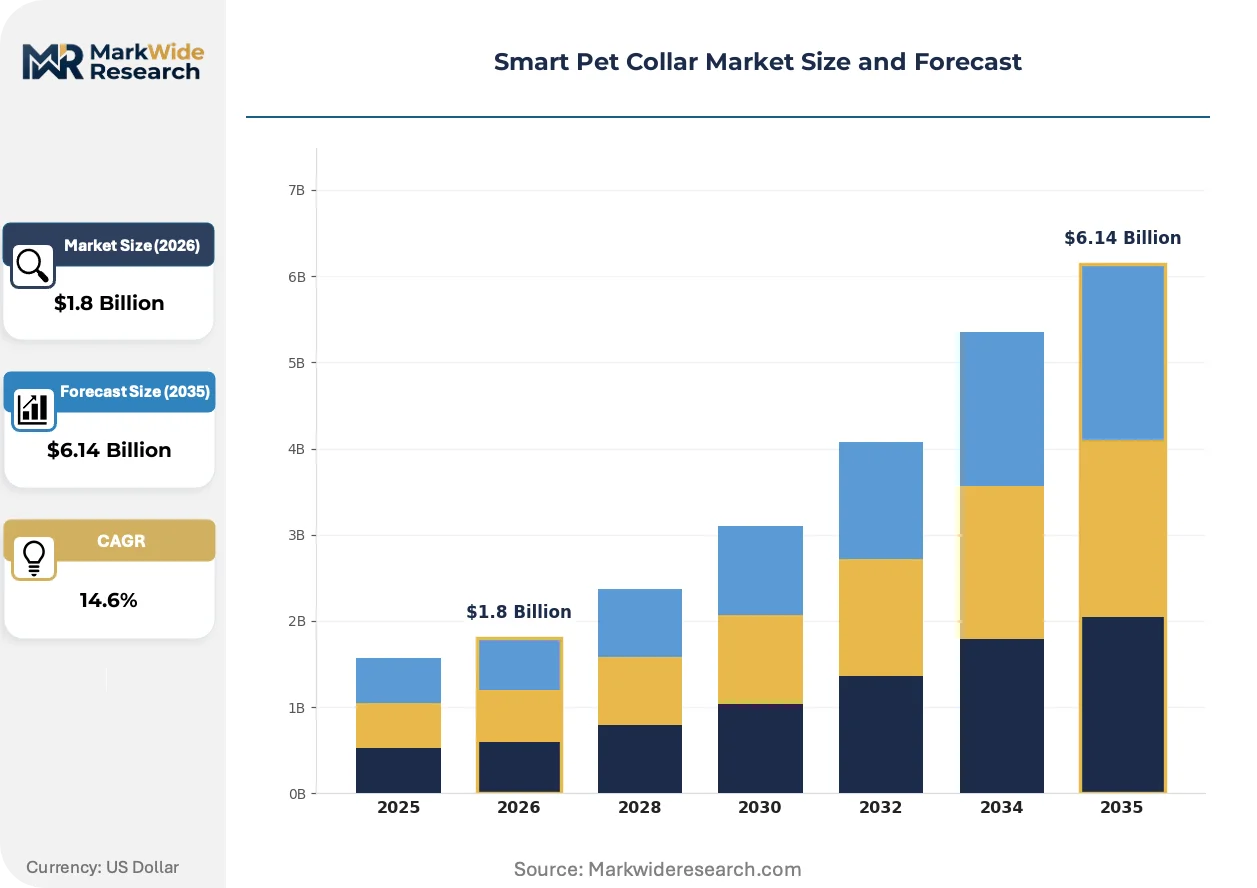
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Trackers, Activity Monitors, Health Monitors, Smart Tags Technology: Bluetooth, Wi-Fi, Cellular, NFC End User: Pet Owners, Veterinarians, Pet Care Providers, Animal Shelters Distribution Channel: Online Retail, Pet Stores, E-commerce Platforms, Veterinary Clinics |
| Companies Covered | Garmin, PetPace, SpotOn, Invoxia, SportDog, Halo Collar, Tractive, Whistle, Fi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pet Collar Market Strategic Shifts
Hardware commoditization is accelerating as sensor module costs decline and cellular connectivity becomes table stakes. Differentiation is migrating toward software-defined geofencing, predictive health algorithms, and subscription-locked feature tiers that bind customer lifetime value to data platform stickiness.
Multi-constellation GNSS chipsets integrating GPS, Galileo, and GLONASS signal reception are rendering obsolete single-system trackers that lose lock in urban canyon environments. Premium outdoor dog owners in mountainous regions of Switzerland and Austria are adopting these units at replacement cycle compression rates. The structural consequence is collapsing price premiums for basic positioning hardware as precision becomes baseline specification.
EU AI Act algorithmic interpretability requirements are mandating disclosure of how collar sensors translate accelerometer and photoplethysmography signals into behavioral or health assessments. Manufacturers serving European veterinary clinics must now document diagnostic boundary limitations and human-in-the-loop escalation protocols. Health Monitor category participants are responding by segregating consumer-facing wellness tips from clinical-grade data feeds accessible only to credentialed veterinarians.
After-sales service unbundling is fragmenting traditional warranty bundles into modular subscription tiers. Hardware purchasers in Germany and the United Kingdom now encounter activation fees for advanced geofencing, historical location playback, and multi-pet dashboard consolidation. This behavioral shift concentrates lifetime value in recurring revenue streams while compressing upfront hardware price sensitivity among urban dog owners with established veterinary relationships.
Smart Pet Collar Market Segmentation
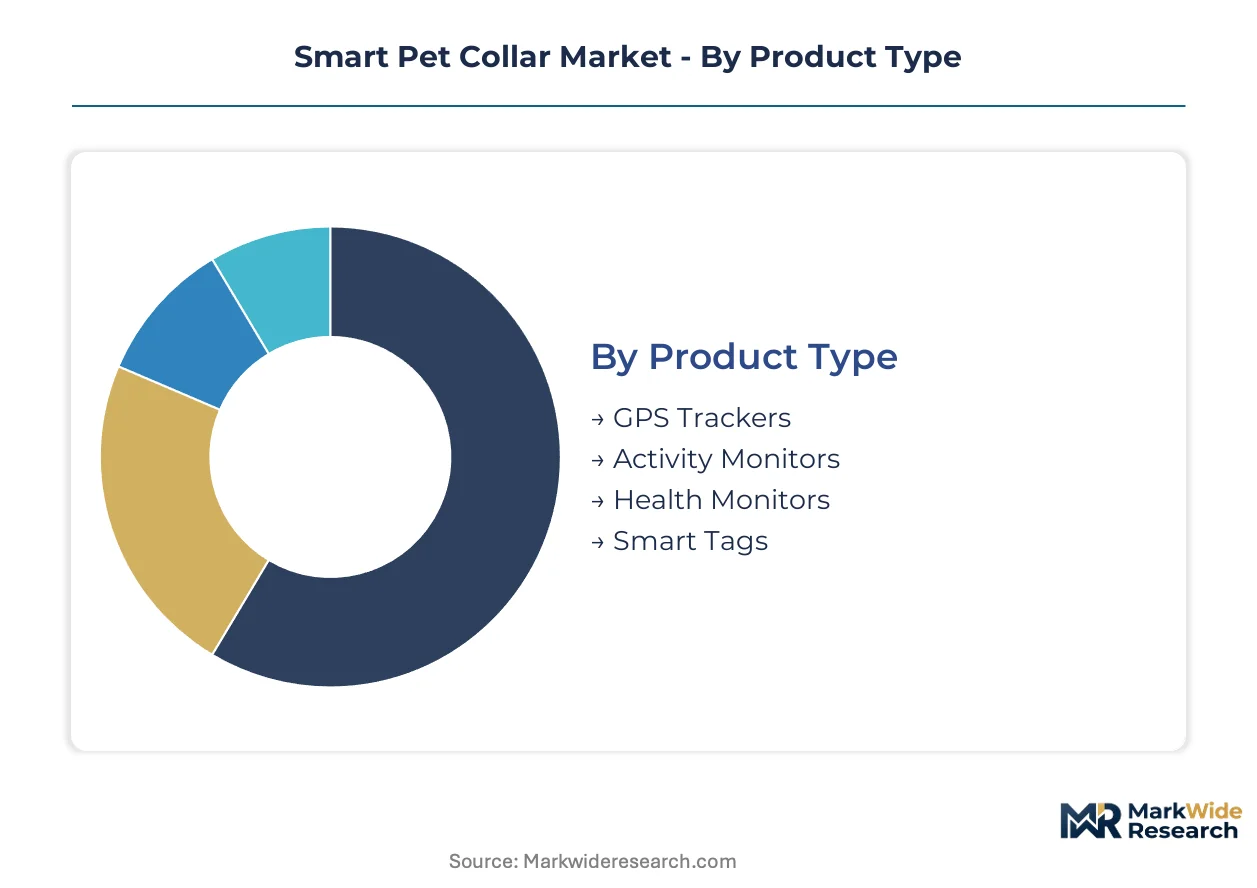
Smart pet collar manufacturers structure product portfolios around connectivity reliability and data granularity tiers. Subscription revenue durability depends on matching hardware capabilities to owner willingness for recurring payments.
Product Type:
After-sales-service intensity varies sharply across collar categories, with cellular-enabled units demanding continuous cloud platform support.
- GPS Trackers:Multi-constellation GNSS chipsets integrate GPS, Galileo, and GLONASS signal reception for urban canyon resilience. German and Swiss outdoor dog owners in mountainous corridors adopt these at compressed replacement cycles, driven by precision requirements for off-leash hiking.
- Health Monitors:Photoplethysmography and accelerometer arrays capture heart rate variability, temperature, and behavioral biometrics. North American veterinary clinics standardize these for post-surgical remote monitoring, locking in multi-year hardware refresh agreements.
- Activity Monitors:Step-counting and sleep-pattern sensors serve wellness-conscious urban owners.
- Smart Tags:QR-code and NFC-enabled identification tags occupy the entry price tier.
GPS Trackers hold the largest share; momentum sits with Health Monitors.
Technology:
Component cost tiers separate economy Bluetooth units from premium cellular designs with persistent coverage.
- Cellular:Modular LTE-M and NB-IoT radios enable real-time alerts independent of smartphone proximity. FCC emission standard tightening elevates bill-of-materials costs versus integrated architectures, compressing hardware margins.
- Bluetooth:Low-energy protocols tether data sync to owner smartphone range, limiting utility to urban density zones.
- Wi-Fi:Home-bound connectivity suits indoor pet monitoring with geofenced safe zones.
- NFC:Passive tags enable tap-to-read identification without battery maintenance.
Cellular commands premium positioning; Bluetooth anchors volume.
End User:
Procurement authority shifts from individual owners toward institutional veterinary channels.
- Pet Owners:Direct purchasers prioritize geofencing reliability and subscription transparency. German metropolitan corridors show concentrated demand for GPS-health hybrid units with persistent cellular connectivity.
- Veterinarians:Clinical procurement channels demand veterinary-grade accuracy for heart rate variability and temperature monitoring. EU AI Act diagnostic boundary requirements are accelerating institutional adoption by reducing liability ambiguity.
- Pet Care Providers:Commercial kennels and dog walkers utilize multi-pet dashboard consolidation.
- Animal Shelters:Budget-constrained operations favor basic identification and location tracking.
Pet Owners generate the highest absolute volume; Veterinarians drive margin expansion.
Distribution Channel:
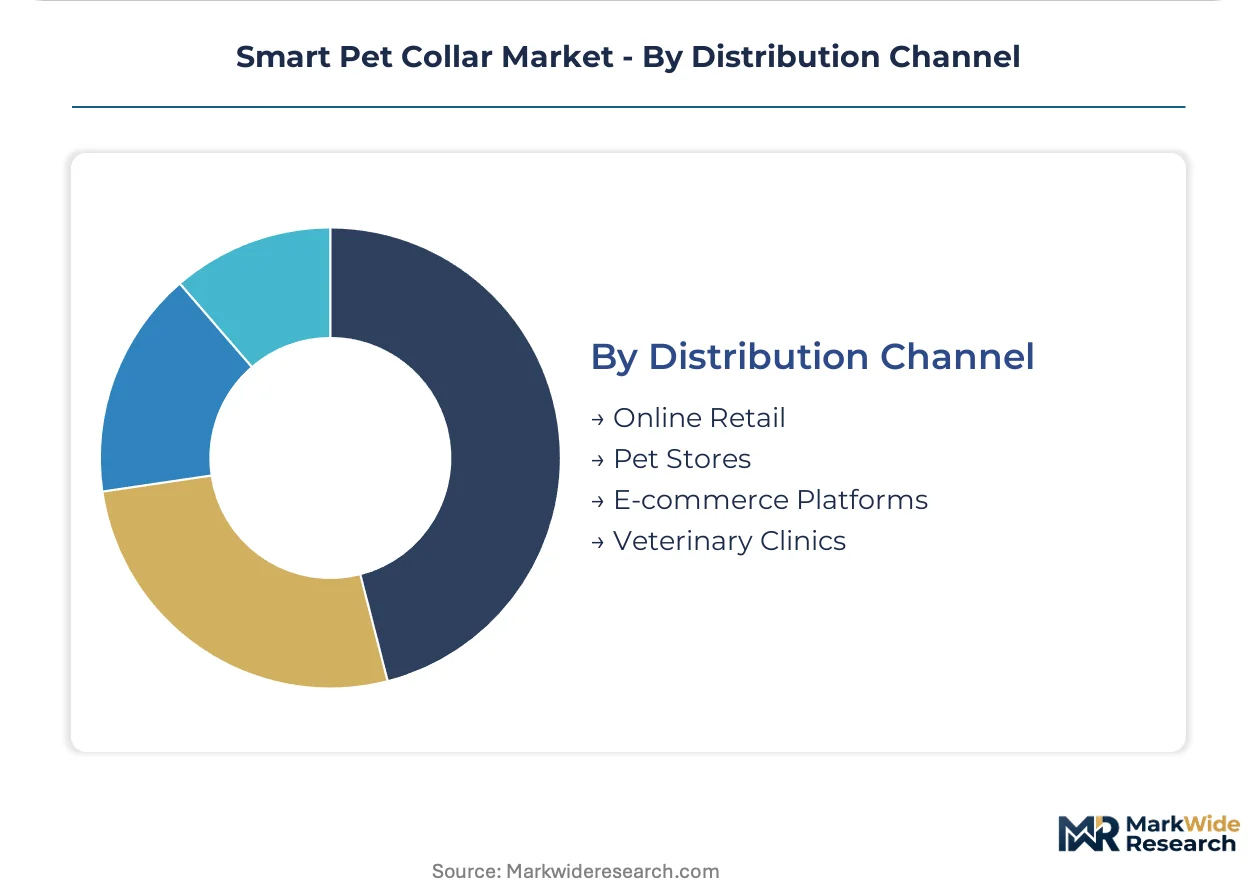
Channel concentration is reshaping margin capture away from specialty retail intermediaries.
- Veterinary Clinics:Institutional sales lock in hardware-software bundles with embedded data plans. North American and European clinics expanding remote patient monitoring programs create multi-year procurement cycles.
- E-commerce Platforms:Direct-to-consumer routes capture margin otherwise lost to distributor markups. Manufacturer-owned storefronts enable subscription tier unbundling for geofencing and historical playback features.
- Online Retail:Third-party marketplaces provide discovery for price-sensitive entry-tier buyers.
- Pet Stores:Specialty retail contraction limits this channel to impulse purchases and accessory attachments.
Veterinary Clinics deliver the highest lifetime value per customer; E-commerce Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Atlantic undersea cable landing stations in Germany and the Netherlands anchor European data throughput for cloud-connected pet health platforms. Dense metropolitan fiber networks in Munich and Hamburg enable real-time veterinary dashboard synchronization. Cross-border cellular roaming agreements across the Schengen zone eliminate coverage gaps for GPS tracking collars.
United States
Veterinary clinic consolidation in Texas and Florida drives institutional procurement of remote patient monitoring hardware. FCC emission standard tightening under the FCC modular radio certification framework elevates compliance costs for cellular-enabled collar manufacturers. Austin and Seattle tech corridors host firmware engineering clusters specializing in biometric sensor calibration.
Germany
Dense urban pet ownership in Berlin and Munich corridors concentrates demand for GPS-health hybrid collars with persistent LTE-M connectivity. EU AI Act diagnostic boundary requirements accelerate clinical adoption by reducing liability ambiguity for veterinary practices. Bavaria's precision electronics manufacturing belt supplies photoplethysmography sensor modules to collar assemblers.
Switzerland
Swissmedic regulatory clarity on wearable medical device classifications attracts health-monitoring collar developers seeking veterinary-grade certification. Alpine outdoor dog culture in Zurich and Geneva metropolitan areas drives replacement demand for multi-constellation GNSS units. Basel's pharmaceutical corridor incubates predictive analytics partnerships between collar data platforms and veterinary insurers.
United Kingdom
Post-Brexit CE marking divergence creates parallel certification tracks for collar manufacturers serving EU and UK markets separately. London's veterinary digitization programs standardize collar-integrated patient dashboards for chronic condition management. Cambridge sensor engineering clusters develop accelerometer firmware for behavioral biometrics interpretation.
Smart Pet Collar Market Competitive Environment
On the supply side, the industry is tiered between GPS heritage specialists, cellular platform operators, and subscription-locked software providers. Garmin and Tractive exemplify geographic anchor strategies leveraging regional cellular partnerships. Halo Collar represents the proprietary geofencing archetype binding hardware to recurring revenue. Strategic moves concentrate on veterinary clinic channel capture and direct-to-consumer platform buildout.
Within the GPS heritage tier, Garmin exemplifies rugged outdoor positioning specialization. Tractive occupies the European cellular partnership anchor position. Halo Collar represents the subscription-locked software differentiation archetype. These three players illustrate how competitive positioning migrates from hardware specifications toward data platform stickiness and recurring revenue durability.
| Leading Market Players |
|---|
| Garmin |
| PetPace |
| SpotOn |
| Invoxia |
| SportDog |
| Halo Collar |
| Tractive |
| Whistle |
| Fi |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Shenzhen sensor module assembly is compressing component costs while elevating pricing power for collar integrators with veterinary clinic channel control. This utilization asymmetry rewards manufacturers who bundle cellular data plans with hardware, shifting margin capture toward subscription platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cellular-enabled veterinary-grade units from Bluetooth consumer collars and basic identification tags. Price differentiation hinges on FCC modular radio certification tier and after-sales service bundling intensity. Cost compression in the Bluetooth tier is intensifying because sensor module commoditization outpaces firmware differentiation. Individual pet owners in price-sensitive segments exhibit highest elasticity, whereas North American veterinary clinics lock in multi-year hardware refresh cycles with limited substitution.
Supply Chain Analysis
Extended payment terms from Bavarian photoplethysmography sensor suppliers are easing working capital constraints for mid-tier collar assemblers. Manufacturing concentrates in China, Germany, and Switzerland, with component sourcing drawing from Taiwanese GNSS chipset foundries and South Korean LTE-M radio module producers. Single-source vulnerability in multi-constellation GNSS receivers creates chokepoint exposure for precision positioning tiers. Distribution runs through veterinary clinic procurement channels and manufacturer-owned e-commerce platforms, bypassing contracting specialty pet retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Pet Collar Market functions as a service-attach opportunity where cloud analytics and cellular data subscriptions expand faster than hardware unit economics. Recurring revenue durability now determines valuation premiums more than sensor specification differentiation.
For Market Incumbents: Harden subscription platform stickiness through proprietary geofencing algorithm development and veterinary dashboard integration. Deepen backward integration into photoplethysmography sensor calibration firmware to offset biometric engineering talent scarcity. Lock in multi-year clinic procurement contracts before EU AI Act diagnostic boundary clarifications mature. For New Entrants and Emerging Players: Build out direct-to-consumer e-commerce capabilities targeting German metropolitan corridors where dense pet ownership and veterinary digitization concentrate demand. Exploit white space in predictive analytics partnerships with veterinary insurers, a channel incumbents have underdeveloped. Lead with transparent subscription tiering to capture margin otherwise lost to distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cellular-enabled health monitoring specialists with veterinary clinic channel penetration. Long-term viability across the projection horizon favors platforms with data platform architecture and cloud analytics infrastructure over hardware-only positioning. The signal to watch is EU AI Act compliance documentation velocity as an inflection indicator for clinical adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Partnership Expansion | Institutional procurement channels in Texas and Florida lock in multi-year hardware refresh cycles with embedded data plans. |
| Proprietary Geofencing Algorithm Development | Behavioral AI differentiation creates defensible recurring revenue streams independent of commoditized GNSS hardware. |
| Cellular Data Platform Integration | LTE-M and NB-IoT connectivity subscriptions shift profit pools from hardware margins toward cloud analytics. |
| EU AI Act Compliance Documentation | Diagnostic boundary clarity accelerates clinical adoption by reducing liability ambiguity for European veterinary practices. |
| Predictive Analytics Insurance Partnership | Risk-adjusted premium pricing tied to collar-reported activity metrics opens veterinary insurer channel expansion. |
Study Parameters
Operator-level perspectives from veterinary clinic procurement managers, collar firmware engineering leads, cellular carrier IoT platform directors, and pet insurance actuarial specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation drawing from FCC equipment authorization databases, EU MDR technical documentation, REACH substance restriction filings, and veterinary trade association remote monitoring adoption surveys. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across connectivity tiers and end-user segments.
Scenario-bracketing around cellular subscription attach rates and veterinary clinic penetration curves structured the analytical framework across the modeling period. Segmentation dimensions included connectivity protocol, product type, end-user procurement authority, and regional regulatory cluster complexity. CAGRs derived from logistic diffusion curves fitted to hardware replacement cycles and subscription renewal patterns, with inputs calibrated against GNSS chipset cost decline trajectories and cellular data plan pricing elasticity.
Stress conditions across FCC emission standard enforcement intensity, EU AI Act diagnostic boundary interpretation divergence, and cellular carrier rural coverage expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sensor module cost compression and veterinary digitization adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UAE Dog Food Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Cat Litter Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
South America Pet Food Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
United States Pet Market
Pet Care Products
Pet Pee Pads Market