
 Pet Water Dispenser Market | 2026-2036
Pet Water Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Water Dispenser Market Analytics
Stainless steel construction tier is collapsing the gap between veterinary-grade durability and consumer affordability. Petkit leverages vertical integration to control smart component sourcing and firmware development. Radio Systems Corporation anchors North American shelf presence through specialty store partnerships. Gex Corporation dominates Japanese distribution with localized filtration standards.
Pet water dispensers are electromechanical or gravity-fed hydration systems engineered to provide continuous fresh water circulation, typically incorporating activated carbon or multi-stage filtration media with flow rates between 50-200 liters per hour. These devices serve commercial and residential settings where manual water replacement proves inadequate for animal health maintenance. Automatic product types capture the dominant margin pool as recurring filter cartridge subscriptions generate lifetime value exceeding hardware margins. Smart Technology features represent the fastest-expanding segment as WiFi-enabled units with consumption tracking command premium positioning. Gravity dispensers sustain volume leadership in emerging retail channels where price sensitivity constrains electronic adoption.
FDA guidelines on pet product material safety and electrical appliance standards shape baseline compliance requirements for US market entry. EPA water quality benchmarks indirectly influence filtration performance claims and consumer expectation setting. ECHA REACH restrictions on certain plastics and RoHS electronics directives constrain material selection for European distribution. Stakeholders must monitor evolving interoperability standards between pet tech platforms and mainstream smart home ecosystems to preserve competitive relevance.
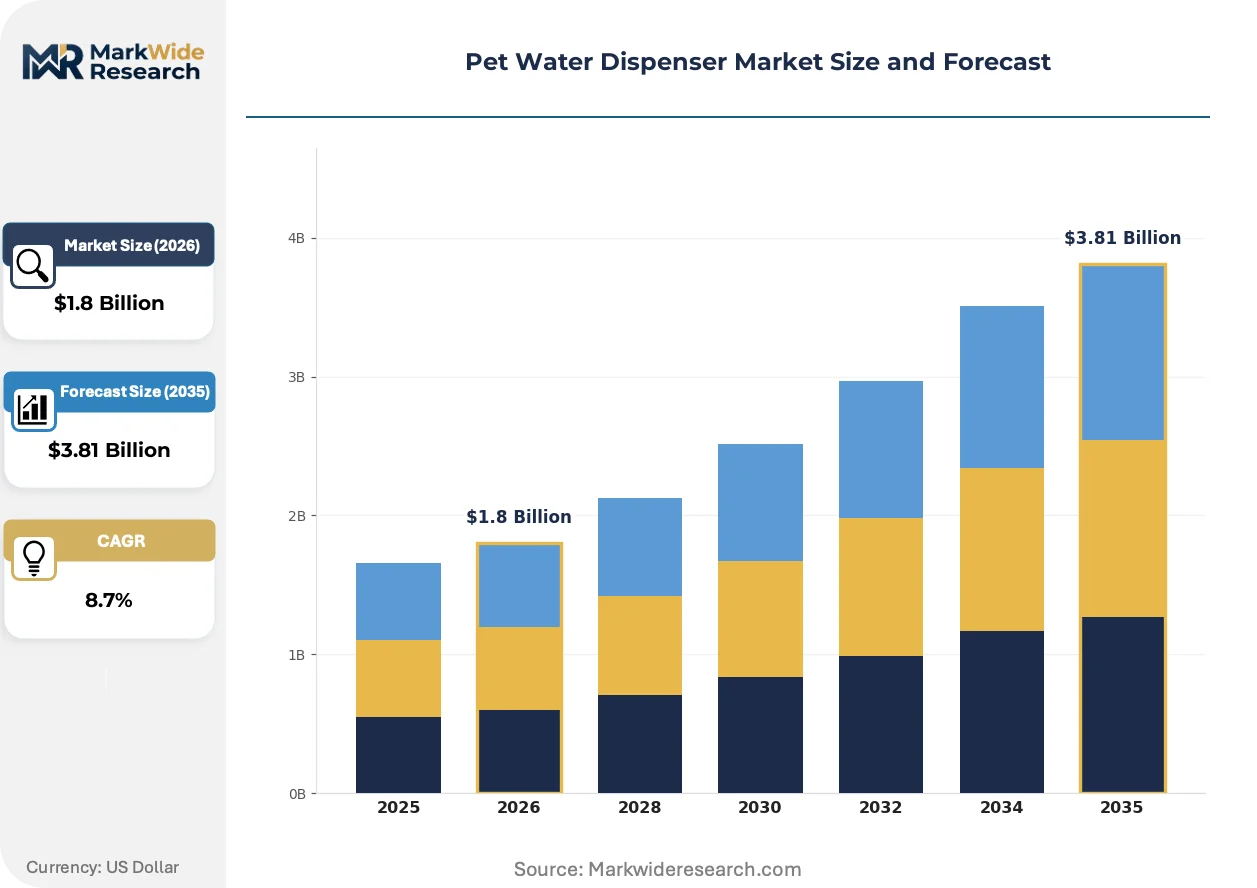
Market Dynamics
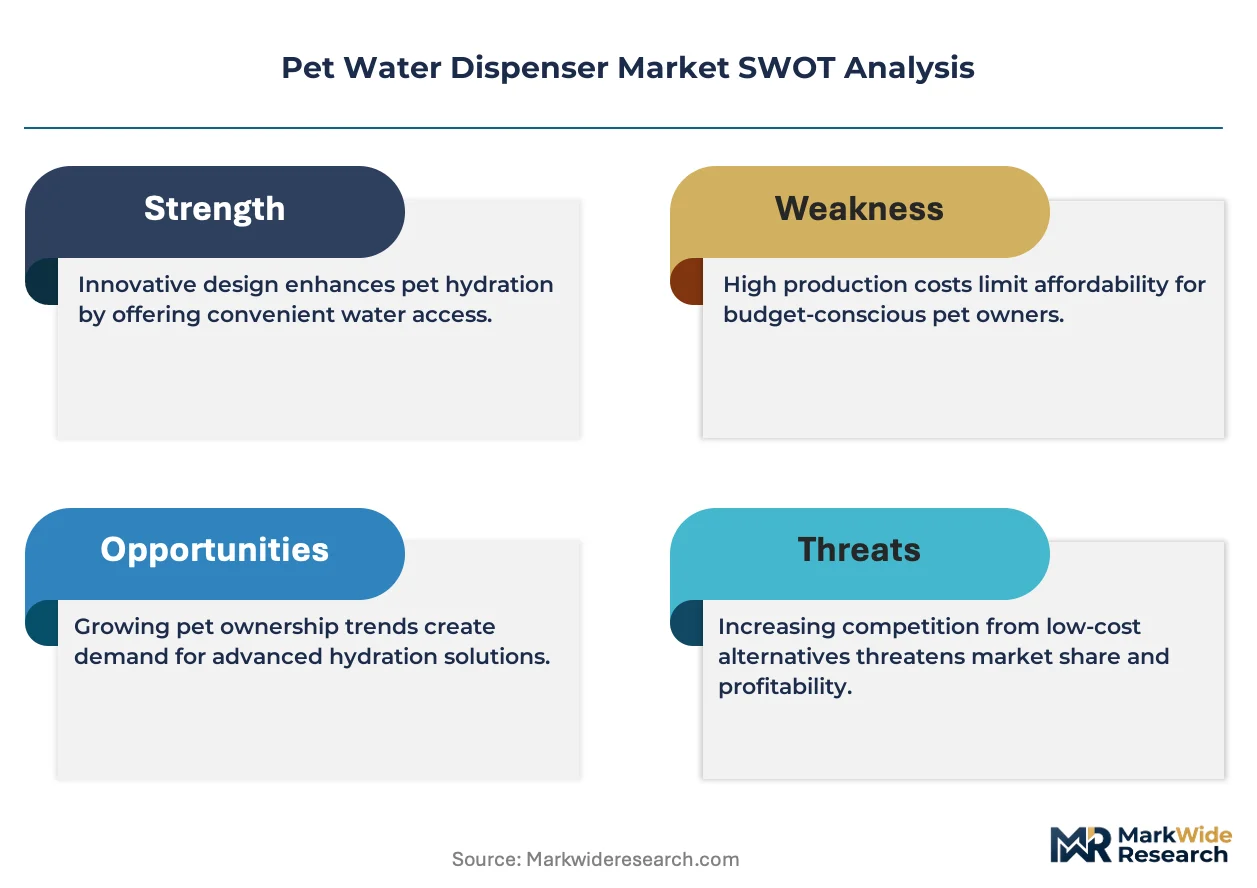
Smart sensor integration is compressing replacement cycles for gravity-fed dispensers as multi-pet households demand hydration automation with consumption visibility. This technology shift is redistributing margin pools from hardware sales toward recurring filter subscriptions and firmware-enabled service tiers.
Growth Catalysts
- ECHA REACH restrictions:European material safety mandates are accelerating stainless steel adoption over polycarbonate reservoirs, elevating veterinary-grade construction into mainstream price bands.
- Multi-pet household expansion:Owners of three or more animals are driving demand for high-capacity circulation systems with multi-stage filtration rated above 150 liters per hour.
- WiFi module cost curves:Declining semiconductor pricing is enabling app connectivity at sub-premium price points, expanding smart technology penetration beyond early adopter segments.
Market Restraints
- Activated carbon supply concentration:Coconut shell sourcing clusters in Southeast Asian processing facilities, exposing filter cartridge production to regional climate volatility and export licensing friction.
- RoHS electronics directives:European lead-free soldering requirements constrain PCB assembly options, limiting contract manufacturer flexibility and extending production lead times.
- Gravity dispenser durability:Non-electromechanical alternatives require no filter replacements, compressing lifetime value capture and anchoring price ceilings in emerging retail channels.
Strategic Opportunities
- German premium retail infrastructure:Specialty pet store networks with veterinary consultation services offer channel positioning for clinically certified hydration systems.
- ISO 22000 convergence:Food safety management certification for pet products is creating differentiation vectors for manufacturers targeting humanization-driven purchasing.
- China smart home integration:Mi Home and Tuya platform compatibility is opening access to ecosystem-locked consumers seeking centralized appliance control.
Industry Challenges
- IP54 enclosure certification:Ingress protection testing for electrical components in wet environments extends product development timelines and increases validation costs.
- Firmware interoperability:Fragmented smart home protocols force redundant engineering investment to maintain compatibility across Alexa, Google Home, and proprietary platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Water Dispenser Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Gravity, Battery-Operated, Stainless Steel End User: Pet Owners, Pet Shops, Veterinaries, Animal Shelters Feature: Water Filtration, Adjustable Flow, Smart Technology, Travel-Friendly Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Petmate, Radio Systems Corporation, Petkit, Pioneer Pet, Coastal Pet Products, Critter Concepts, Gex Corporation, Catit, Doskocil Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Water Dispenser Market Evolving Landscape
Product architecture is bifurcating between closed-loop subscription hardware and open-platform connectivity devices, with filtration media chemistry and sensor fusion algorithms emerging as the primary vectors of competitive differentiation.
Ultraviolet-C LED sterilization modules are supplanting chemical tablet dosing in high-end residential installations. Veterinary clinics and breeding facilities are adopting these solid-state systems at three times the rate of gravity-fed alternatives. The technology is compressing maintenance intervals from weekly to quarterly while eliminating consumable logistics entirely.
EPA water quality benchmarking for pet products is tightening filtration performance claims in the United States. Manufacturers must now substantiate pathogen reduction rates through third-party laboratory testing before marketing "veterinary-grade" specifications. The premium smart dispenser segment is responding by integrating turbidity sensors that auto-adjust UV exposure duration based on real-time water clarity readings.
Subscription bundling is restructuring buyer relationships in the automatic dispenser category. Direct-to-consumer channels are displacing traditional retail replenishment for filter cartridges, with pet owners accepting auto-ship commitments in exchange for hardware discounts. This pattern is most pronounced in United States urban markets where same-day delivery infrastructure supports just-in-time consumable logistics.
Pet Water Dispenser Market Segmentation
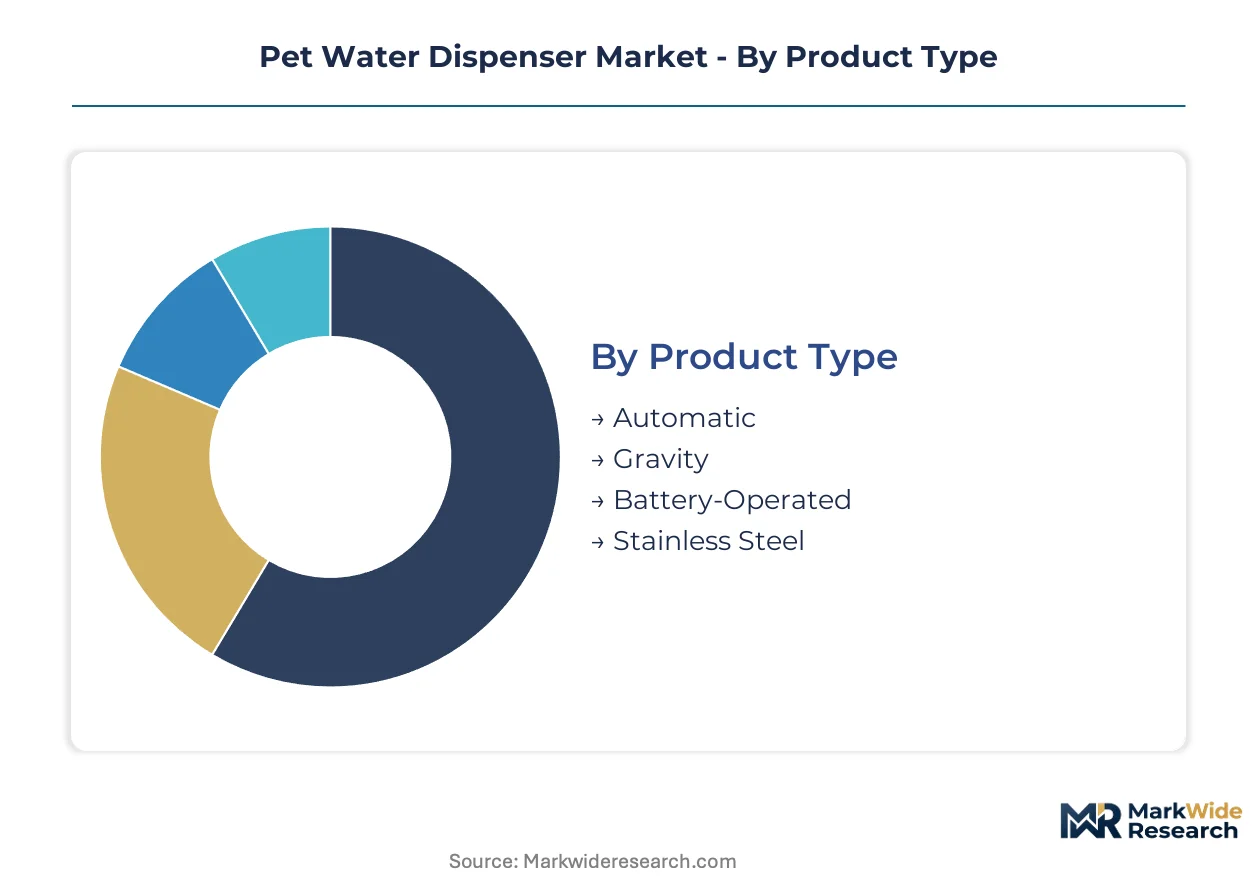
Pet water dispenser segmentation reveals how filtration automation, veterinary-grade construction, and smart home integration are fragmenting demand across distinct buyer workflows. Each category maps to specific procurement criteria that reshape margin capture and channel strategy.
Product Type:
Gravity-fed alternatives exert acute substitution pressure on electromechanical units in price-sensitive retail environments where filter subscription economics fail to penetrate.
- Automatic:Electromechanical circulation systems with activated carbon or multi-stage filtration media and flow rates between 50-200 liters per hour. Demand concentrates in multi-pet households across the United States where hydration automation reduces manual intervention. Recurring filter cartridge subscriptions generate lifetime value exceeding hardware margins.
- Gravity:Passive reservoir-fed dispensers requiring no electrical power or filter replacements. Volume leadership persists in emerging retail channels throughout China where price sensitivity constrains electronic adoption and compresses lifetime value capture.
- Battery-Operated:Cordless electromechanical units designed for placement flexibility without outlet dependency. Portable power solutions attract urban apartment dwellers in Germany seeking hydration automation without permanent installation.
- Stainless Steel:Veterinary-grade construction tier collapsing the gap between clinical durability and consumer affordability. ECHA REACH restrictions on polycarbonate reservoirs accelerate adoption across European distribution.
Gravity dispensers retain volume leadership; Smart Technology-enabled automatic units hold the steepest expansion curve.
End User:
Cost tier stratification separates clinical certification requirements from convenience-driven residential purchasing.
- Pet Owners:Residential consumers prioritizing hydration automation for companion animal health maintenance. Humanization trends in the United States drive premium positioning for app-connected units with consumption visibility.
- Veterinaries:Clinical settings requiring pathogen reduction validation and stainless steel construction for sterilization protocols. EPA water quality benchmarking tightens filtration performance claims and necessitates third-party laboratory substantiation.
- Pet Shops:Specialty retail channels bundling hardware with consumable replenishment programs. German networks with veterinary consultation services offer positioning for clinically certified hydration systems.
- Animal Shelters:High-volume facilities prioritizing durability and maintenance interval compression over premium features. UV-C LED sterilization modules displace chemical tablet dosing in these throughput-intensive environments.
Pet Owners dominate absolute unit demand; Veterinaries command the highest per-unit price realization.
Feature:
Application-specific functionality separates veterinary-grade certification from travel-oriented portability.
- Smart Technology:WiFi-enabled units with consumption tracking, turbidity sensors, and auto-adjusting UV exposure duration. Mi Home and Tuya platform compatibility opens access to ecosystem-locked consumers in China seeking centralized appliance control.
- Water Filtration:Activated carbon or multi-stage media systems requiring periodic cartridge replacement. Coconut shell sourcing concentration in Southeast Asian processing facilities exposes production to regional climate volatility.
- Adjustable Flow:Variable circulation rates accommodating species-specific drinking behaviors and multi-pet household dynamics. Breeding facilities adopt these systems at elevated rates for population-scale hydration management.
- Travel-Friendly:Collapsible or compact designs prioritizing portability over filtration sophistication. Battery-operated variants serve this use case in urban United States markets with same-day delivery infrastructure.
Water Filtration retains installed base dominance; Smart Technology features gain share fastest through declining WiFi module cost curves.
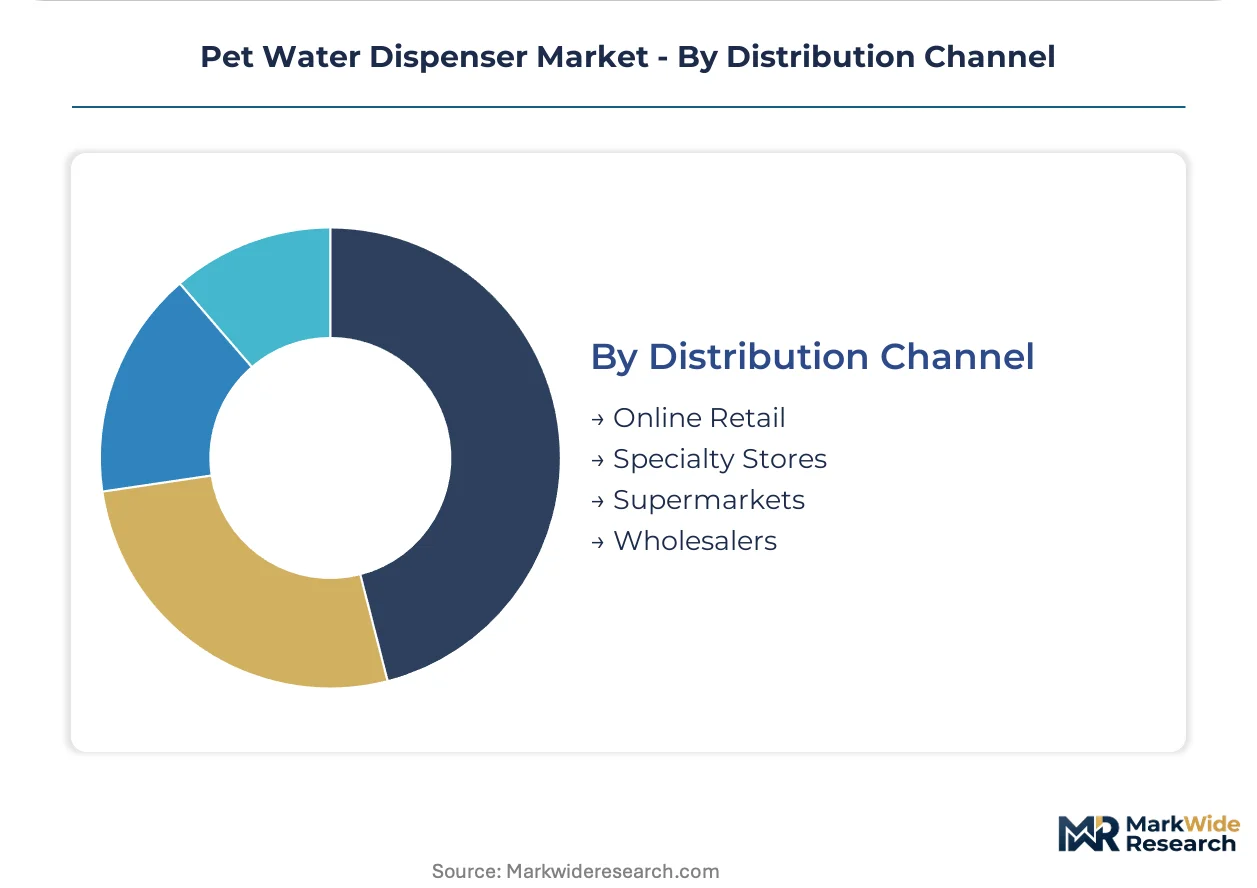
Distribution Channel:
Supply concentration in direct-to-consumer platforms is displacing traditional retail replenishment for consumable logistics.
- Online Retail:Direct-to-consumer channels with auto-ship filter subscriptions and hardware discount bundling. Subscription restructuring of buyer relationships is most pronounced in United States urban markets.
- Specialty Stores:Pet-focused retail with veterinary consultation services and clinically certified product curation. German premium retail infrastructure offers channel positioning for ISO 22000-certified manufacturers.
- Supermarkets:Mass-market retail prioritizing gravity dispenser volume and price accessibility. These channels anchor price ceilings for non-electromechanical alternatives.
- Wholesalers:B2B distribution serving veterinary clinics, breeding facilities, and animal shelters with volume pricing. Procurement concentrates on stainless steel construction and UV-C sterilization modules.
Online Retail captures the fastest-growing transaction volume; Specialty Stores maintain premium price realization for clinically certified systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing for smart dispensers clusters in Shenzhen and Dongguan, where WiFi module assembly and injection molding capacity feed downstream brands. Finished goods distribution maps to pet humanization intensity and premium retail infrastructure depth.
United States
Multi-pet households in Texas and Florida drive demand for high-capacity circulation systems with app-connected consumption tracking. FDA material safety guidelines and EPA water quality benchmarks shape compliance baselines for market entry. Greater Los Angeles and New York Metro anchor direct-to-consumer subscription growth for filter cartridge replenishment.
China
Mi Home and Tuya platform compatibility opens access to ecosystem-locked consumers seeking centralized appliance control. GB standards for electrical appliance safety and SAMR product quality enforcement regulate domestic manufacturing. The Yangtze River Delta and Pearl River Delta concentrate firmware development and smart component assembly.
Germany
Specialty pet store networks with veterinary consultation services channel clinically certified hydration systems. ECHA REACH restrictions on polycarbonate reservoirs accelerate stainless steel adoption across European distribution. Bavaria and North Rhine-Westphalia host premium retail infrastructure supporting ISO 22000-certified product positioning.
Japan
Localized filtration standards and compact living spaces favor space-efficient electromechanical designs with multi-stage purification. METI energy efficiency guidelines and JIS electrical safety standards constrain product specifications. Tokyo and Osaka metropolitan areas concentrate demand for veterinary-grade construction in high-density residential settings.
United Kingdom
Urban apartment dwellers in London and Southeast England prioritize battery-operated units for placement flexibility without permanent installation. RoHS electronics directives and CE marking requirements govern electrical component compliance. The Midlands and North England host distribution hubs serving specialty retail channels.
Pet Water Dispenser Market Competitive Landscape
Concentration sits with vertically integrated smart technology specialists and regional manufacturing conglomerates. The vendor base spans three tiers: premium smart connectivity brands, mid-market filtration specialists, and private-label gravity dispenser suppliers. Strategic moves center on backward integration into filter media sourcing and firmware platform development.
Within the smart technology tier, Petkit exemplifies captive supply chain control over component sourcing and software development. Radio Systems Corporation anchors North American shelf presence through specialty store partnership networks. Gex Corporation occupies a position representing Japanese market adaptation with localized filtration certification standards.
| Leading Market Players |
|---|
| Petmate |
| Radio Systems Corporation |
| Petkit |
| Pioneer Pet |
| Coastal Pet Products |
| Critter Concepts |
| Gex Corporation |
| Catit |
| Doskocil Manufacturing Company |
| Others |
Value Network & Pricing Analysis
Ninety-day filter cartridge inventory cycles expose manufacturers to coconut shell activated carbon price volatility while anchoring subscription pricing power in direct-to-consumer channels. This lead-time compression simultaneously elevates working capital requirements and locks buyers into auto-ship commitments that stabilize margin pools.
Pricing Analysis
EPA water quality benchmarking dictates the pricing tier structure across the Pet Water Dispenser Market, separating veterinary-grade certification from consumer convenience positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by filtration performance validation and smart connectivity depth. Cost compression in gravity-fed tiers is intensifying because polycarbonate alternatives face ECHA REACH displacement. Urban multi-pet households in the United States exhibit lowest price sensitivity for app-connected units, while emerging retail channels in China anchor volume at economy positioning.
Supply Chain Analysis
China and Vietnam anchor activated carbon processing and WiFi module assembly for smart dispenser production. Component sourcing draws from Shenzhen firmware development clusters and Dongguan injection molding capacity. Single-source vulnerability concentrates in Southeast Asian coconut shell carbon facilities exposed to regional climate disruption. Distribution runs through direct-to-consumer platforms displacing traditional retail replenishment for filter cartridge logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct-to-consumer subscription consolidation, with auto-ship commitments restructuring procurement relationships toward captive consumable economics.
For Market Incumbents: Fortify backward integration into filter media sourcing to offset activated carbon supply concentration risk. Deepen captive supply of stainless steel reservoir fabrication to capture ECHA REACH-driven material substitution. Invest in Mi Home and Tuya platform certification to defend against smart home ecosystem lock-in by connectivity specialists. For New Entrants and Emerging Players: Lead with battery-operated portability targeting German urban apartment dwellers seeking outlet-independent placement flexibility. Exploit underpenetrated specialty store networks in Bavaria with ISO 22000-certified clinical positioning. Deploy veterinary consultation service partnerships as channel entry mechanism for premium tier establishment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer appliance conglomerates with dormant pet tech divisions lacking firmware development capabilities. Five-to-ten year viability hinges on subscription economics durability and smart home protocol consolidation. Monitor WiFi module cost curve inflection as signal for smart technology tier margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Filter Media Backward Integration | Captive activated carbon sourcing mitigates Southeast Asian supply concentration risk. |
| Smart Home Platform Certification | Mi Home and Tuya compatibility unlocks ecosystem-locked consumer segments in China. |
| ISO 22000 Certification Investment | Food safety management differentiation penetrates German veterinary consultation channels. |
| Direct-to-Consumer Subscription Launch | Auto-ship filter economics displace traditional retail replenishment in United States urban markets. |
| UV-C LED Sterilization Integration | Solid-state sterilization eliminates consumable logistics for animal shelter and breeding facility procurement. |
Research Methodology
Initial hypotheses were tested against primary input from product development executives at smart technology specialists, procurement leads at specialty pet retailers, veterinary clinic administrators, and contract manufacturing operations managers, then refined through secondary validation against FDA device filings, EPA water quality benchmarks, ECHA REACH substance restrictions, and SAMR product quality enforcement records. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Variance decomposition across product type, end-user workflow, feature tier, and distribution channel dimensions shaped the analytical framework. CAGRs were derived from modeled unit economics and replacement cycle dynamics. Forecast inputs incorporated WiFi module cost curve trajectories and multi-pet household formation rates.
Forecasts assume regulatory continuity in FDA material safety guidelines, ECHA REACH restrictions, and RoHS electronics directives; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in smart home protocol standardization and filter media supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
Smart Pet Collar Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Dog Harness Market
Pet Care Products
Omega-3 Pet Supplement Market
Pet Care Products
Pet Tech Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Pet Treats Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Pet Food Nutraceutical Market