
 Pet Car Seat Protectors Market | 2026-2036
Pet Car Seat Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Car Seat Protectors Market Analytics
ISO 10993 biocompatibility assessment is reorganizing supplier qualification protocols for Pet Car Seat Protectors, as brands face pressure to validate that prolonged pet contact with treated fabrics poses no dermal risk. Kurgo leverages extensive crash-testing partnerships with automotive safety institutes to anchor its premium positioning. 4Knines sustains manufacturing scale through vertically controlled production facilities in North Carolina. Ruff Liners differentiates through specialized hammock configurations engineered for truck bed applications.
Pet car seat protectors constitute barrier textiles engineered from laminated polyester or woven nylon substrates with polyurethane waterproof membranes, typically rated to 300D–600D denier for abrasion resistance, designed to shield vehicle upholstery from claw damage, shedding, moisture, and soiling during pet transport. Hammock-style installations command the dominant volume share due to their dual function as seat coverage and restraint containment, while custom-fit configurations capture disproportionate margin pools through vehicle-specific patterning. Waterproof fabric treatments outperform raw canvas in replacement-cycle economics, as stain-resistant coatings extend functional lifespan and reduce consumer churn.
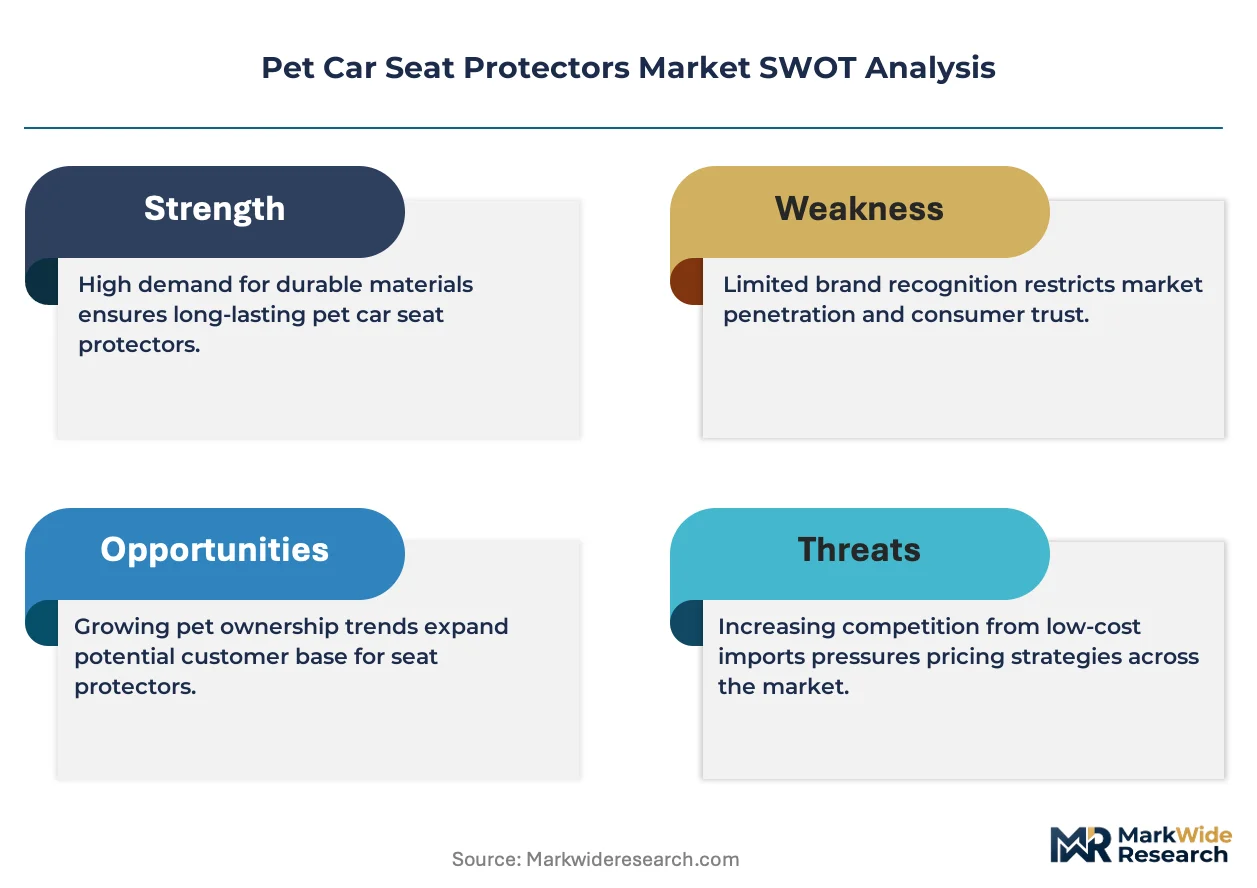
The Consumer Product Safety Commission and state-level departments of agriculture in the United States enforce textile labeling and chemical disclosure requirements that shape material selection and import documentation burdens for pet accessory distributors. The European Chemicals Agency's REACH restrictions on perfluorinated compounds compel reformulation of legacy water-repellent finishes, redirecting R&D expenditure toward silicone-based alternatives. Stakeholders must monitor evolving automotive OEM pet-accessory integration programs and emerging subscription-based vehicle protection services that could displace aftermarket purchase patterns.
Market Dynamics
Pet humanization among suburban vehicle owners is compressing replacement cycles and elevating material performance expectations, forcing manufacturers to reconcile premium positioning with REACH and Proposition 65 compliance burdens.
Growth Catalysts
- ISO 10993 biocompatibility protocols:Brands validating dermal safety for prolonged pet contact are capturing veterinary channel endorsements and premium shelf placement.
- Crash-tested safety certifications:Partnerships with automotive safety institutes create defensible differentiation against commodity imports.
- Suburban vehicle ownership density:High household vehicle counts in the United States expand the installed base of addressable protection needs.
Market Restraints
- Polyurethane membrane cost volatility:Petrochemical input fluctuations compress margin buffers for waterproof laminate producers.
- REACH perfluorinated compound restrictions:ECHA reformulation mandates redirect R&D spend toward silicone-based water-repellent alternatives.
- Direct-to-consumer import penetration:Unbranded Asian manufacturers erode pricing power through marketplace platform arbitrage.
Strategic Opportunities
- OEM integration programs:Automotive manufacturers bundling pet accessories with new vehicle purchases could displace aftermarket channel volumes.
- Subscription-based vehicle protection services:Fleet and lease operators adopting recurring protection models create predictable revenue streams.
- Truck bed specialization:Hammock configurations engineered for pickup applications address an underserved functional segment.
Industry Challenges
- Material certification timelines:ISO 10993 testing protocols extend supplier qualification cycles by 8-14 months.
- Legacy water-repellent inventory obsolescence:REACH-driven reformulation strands existing perfluorinated compound stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Car Seat Protectors Market |
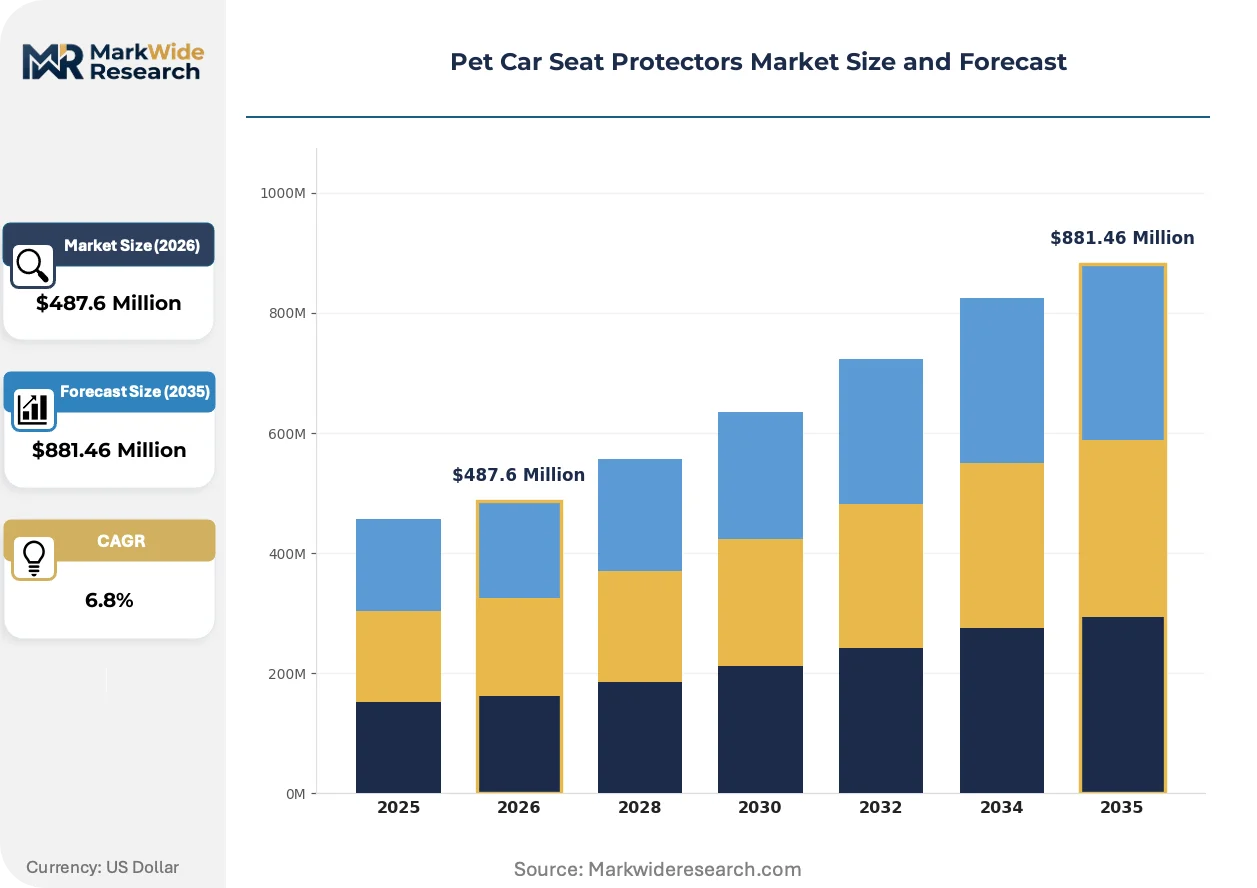
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammock, Bench, Bucket, Custom-Fit Material: Canvas, Waterproof Fabric, Nylon, Polyester Feature: Non-Slip, Easy Clean, Scratch Resistant, Portable Installation: Strap-On, Clip-In, Universal Fit, Customizable |
| Companies Covered | Kurgo, 4Knines, Ruff Liners, Barks Bar, Arf Pets, 3 Dog Pet Supply, Frisco, Carhartt, Ruffwear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Car Seat Protectors Market Evolving Landscape
Material science advancement and regulatory chemistry constraints are bifurcating competitive advantage between biocompatibility-validated premium offerings and cost-optimized commodity imports.
Silicone-based water-repellent treatments are fragmenting the legacy fluoropolymer-dominated finishing market. Tier-one brands adopting these reformulations are securing European market access ahead of competitors. The technology is fragmenting supplier concentration as specialty chemical houses displace incumbent finish providers.
ECHA's REACH restrictions on perfluorinated compounds are forcing wholesale reformulation of durable water-repellent chemistries. Manufacturers face stranded inventory risk and accelerated R&D burn rates. European distributors are responding by consolidating supplier bases around pre-validated silicone-alternative providers.
Vehicle-specific custom patterning is displacing universal-fit configurations among premium buyers. Direct-to-consumer configurators and 3D scanning services are compressing the traditional retail channel. This shift concentrates most acutely in the United States where high vehicle model diversity rewards precise fit solutions.
Pet Car Seat Protectors Market Segmentation
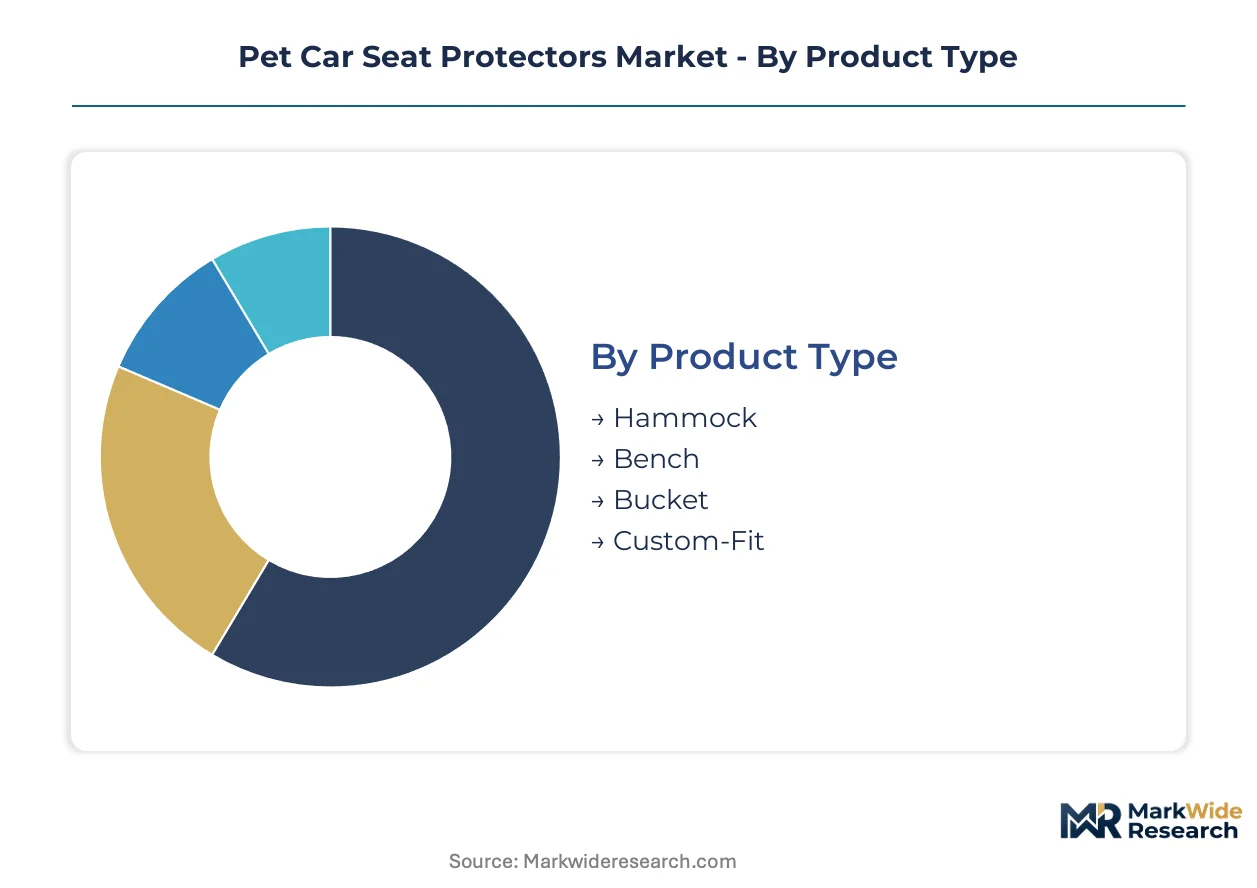
Segmentation in pet car seat protectors reveals how installation geometry, material chemistry, and functional features create distinct margin profiles. Manufacturers must align R&D spend against the segments where ISO 10993 validation and REACH compliance confer sustainable pricing power.
Product Type:
Hammock configurations face the strongest substitution pressure from universal-fit bench alternatives, yet their dual-function containment value sustains premium positioning against commoditized imports.
- Hammock:Suspended barrier designs spanning front and rear seat anchors create enclosed zones that prevent pets from falling into footwells during braking events. Suburban SUV and truck owners in the United States concentrate demand here, drawn by the combined upholstery protection and restraint containment that reduces driver distraction incidents.
- Bench:Flat protective layers covering rear seat cushions without vertical barriers serve entry-level buyers and multi-pet households prioritizing coverage area over containment. Direct-to-consumer imports from unbranded Asian manufacturers erode pricing power in this segment through marketplace platform arbitrage.
- Bucket:Contoured single-seat protectors address front passenger and third-row applications where space constraints prevent hammock deployment. Fleet operators and ride-share drivers represent concentrated end-use.
- Custom-Fit:Vehicle-specific patterning derived from OEM seat dimensions delivers precise edge-to-edge coverage. United States premium buyers with high vehicle model diversity reward the elimination of gapping and slippage endemic to universal alternatives.
Hammock anchors the volume base while custom-fit gains share at the steepest rate.
Material:
Cost tier stratification separates REACH-compliant silicone-treated substrates from legacy fluoropolymer inventory facing obsolescence.
- Canvas:Untreated woven cotton or cotton-blend fabrics offer breathable, natural-fiber aesthetics that appeal to sustainability-oriented buyers. Replacement-cycle economics disadvantage canvas against coated alternatives, as unsealed fibers absorb moisture and stain permanently, accelerating consumer churn.
- Waterproof Fabric:Laminated polyester or woven nylon substrates with polyurethane membranes rated to 300D–600D denier dominate functional performance expectations. European distributors consolidating supplier bases around silicone-alternative providers concentrate demand here as ECHA perfluorinated compound restrictions strand legacy inventory.
- Nylon:High-tenacity synthetic weave delivers abrasion resistance for claw-prone large breeds. Veterinary channel endorsements flow to brands validating dermal safety through ISO 10993 protocols.
- Polyester:Cost-optimized staple fiber construction serves price-sensitive mass retail placement. Petrochemical input volatility compresses margin buffers for producers dependent on polyurethane laminate bonding.
Waterproof fabric anchors the volume base while nylon climbs the fastest among premium-positioned offerings.
Feature:
Application-driven feature bundling separates fleet procurement specifications from individual consumer preferences.
- Non-Slip:Silicone dot matrices or rubberized backing layers prevent protector migration during vehicle acceleration and cornering. Safety-conscious suburban vehicle owners in the United States treat this as non-negotiable.
- Easy Clean:Wipeable surface treatments and machine-washable constructions reduce maintenance burden for high-frequency pet transport users. Multi-pet households and professional dog handlers drive concentration.
- Scratch Resistant:Reinforced weave densities and ripstop constructions extend functional lifespan against large-breed claw damage. Tier-one brands leverage this feature to justify premium positioning against commodity imports.
- Portable:Lightweight, foldable designs with integrated storage pouches serve occasional users and multi-vehicle households. Travel and outdoor recreation segments concentrate demand.
Non-slip anchors the volume base while scratch resistant expands most quickly as durability expectations rise.
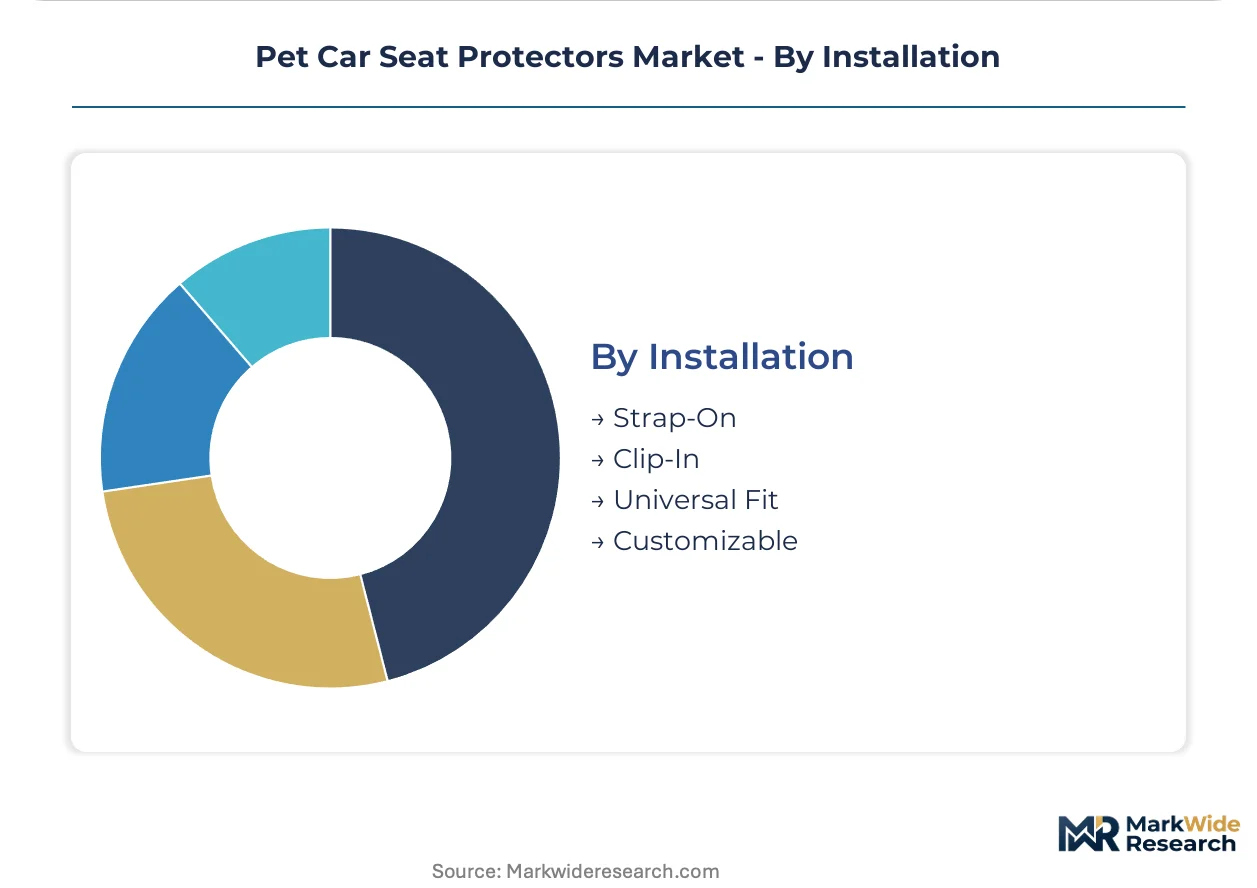
Installation:
Customer type bifurcation separates OEM integration programs from aftermarket channel complexity.
- Strap-On:Adjustable webbing configurations wrapping around headrests and seat bases enable tool-free deployment across diverse vehicle architectures. Entry-level consumers and rental fleet operators prioritize this flexibility.
- Clip-In:Integrated attachment points connecting to vehicle LATCH anchors or seatbelt receivers provide crash-tested security validation. Kurgo and similar brands leverage automotive safety institute partnerships here.
- Universal Fit:One-size designs accommodating broad vehicle model ranges minimize inventory carrying costs for retailers. E-commerce marketplaces favor this segment for cross-border fulfillment efficiency.
- Customizable:Modular components allowing consumers to adapt coverage zones and restraint configurations to specific transport scenarios. Direct-to-consumer configurators compress traditional retail channel margins.
Strap-on anchors the volume base while clip-in shows the steepest expansion trajectory as safety certification becomes a purchase prerequisite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific textile import flows that sustain North American pet accessory distribution networks. European rail corridors connecting Rotterdam to German industrial clusters enable REACH-compliant material consolidation. East Asian manufacturing hubs feed both branded and private-label supply chains.
United States
Suburban vehicle ownership density and premium pet spending patterns drive category development. California's Proposition 65 constrains material chemistries and elevates compliance documentation burdens. North Carolina hosts vertically controlled production facilities serving domestic manufacturing scale.
Germany
Automotive OEM integration programs and stringent material safety standards shape procurement specifications. ECHA's REACH restrictions on perfluorinated compounds compel wholesale reformulation of water-repellent finishes. Bavaria concentrates specialty chemical houses developing silicone-based alternative treatments.
China
Direct-to-consumer export manufacturing and petrochemical feedstock access define competitive positioning. SAMR textile labeling requirements and GB standards govern export documentation. Yangtze River Delta clusters dominate coated fabric laminate production for waterproof membrane applications.
United Kingdom
Veterinary channel endorsement networks and premium retail placement sustain margin pools. CE marking obligations and post-Brexit UK REACH divergence create dual compliance burdens. London-Southeast distribution hubs coordinate European aftermarket logistics.
Canada
Cross-border supply chain integration with US markets and comparable vehicle ownership patterns sustain demand. Health Canada textile safety guidelines align with US CPSC disclosure frameworks. Ontario-based distributors consolidate North American fulfillment operations.
Pet Car Seat Protectors Market Competitive Landscape
Listed leaders compete with private specialists across certification-intensive premium tiers and cost-optimized mass channels. Market structure bifurcates between biocompatibility-validated brands capturing veterinary endorsements and unbranded imports eroding pricing power through marketplace arbitrage. Three archetypes dominate: automotive safety institute partners, vertically integrated domestic fabricators, and direct-to-consumer configurators. Competitive moves concentrate on crash-tested certification acquisition and silicone-based material reformulation ahead of regulatory deadlines.
Within the automotive safety partnership tier, Kurgo occupies a position exemplifying institute-validated premium positioning. Among vertically integrated fabricators, 4Knines represents captive production control over North Carolina manufacturing scale. At the specialized-application end, Ruff Liners anchors truck bed hammock configuration expertise.
| Leading Market Players |
|---|
| Kurgo |
| 4Knines |
| Ruff Liners |
| Barks Bar |
| Arf Pets |
| 3 Dog Pet Supply |
| Frisco |
| Carhartt |
| Ruffwear |
| Others |
Value Network & Pricing Analysis
ISO 10993 biocompatibility validation gates both supplier qualification timelines and tiered price positioning, compressing margin buffers for manufacturers unable to secure veterinary channel endorsements while rewarding certified brands with premium shelf placement and defensible pricing power against commodity imports.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with ISO 10993-validated and crash-tested offerings commanding substantial premiums over unbranded alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects material chemistry compliance, installation geometry complexity, and channel control intensity. Price erosion runs through the universal-fit bench segment as direct-to-consumer Asian imports arbitrage marketplace platforms. Fleet operators and multi-pet households exhibit highest price sensitivity, while suburban SUV owners with single large-breed dogs demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on trans-Pacific lanes elevate inbound logistics costs for coated fabric laminate producers dependent on Yangtze River Delta manufacturing clusters. Supply concentrates in China for waterproof membrane lamination, North Carolina for vertically controlled domestic cut-and-sew operations, and Germany for specialty silicone-based chemical finishing. Raw material dependencies center on polyurethane resins, high-tenacity nylon yarns, and REACH-compliant water-repellent treatments. Single-source vulnerability in perfluorinated compound alternatives creates reformulation risk as ECHA deadlines approach. Distribution runs through automotive aftermarket retailers, veterinary clinic networks, and direct-to-consumer configurators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEM procurement teams and fleet lease operators, fragmenting the traditional aftermarket channel and forcing suppliers to choose between volume scale through bundling agreements or margin defense through certification-intensive premium positioning.
For Market Incumbents: Compound defensible positioning by deepening crash-testing partnerships with automotive safety institutes and accelerating silicone-based material reformulation ahead of REACH perfluorinated compound deadlines. Secure exclusive veterinary channel endorsements to lock out commodity competitors. Prioritize backward integration into North Carolina manufacturing capacity to insulate against trans-Pacific logistics volatility and tariff exposure. For New Entrants and Emerging Players: ISO 10993 fast-track certification programs open white-space entry through truck bed hammock specialization and direct-to-consumer custom-fit configurators leveraging 3D scanning services. Target the underserved pickup owner segment with vehicle-specific patterning for domestic truck architectures. Pursue go-to-market partnerships with outdoor recreation retailers to bypass entrenched pet specialty channel gatekeepers. For Investors and Strategic Acquirers: ECHA REACH perfluorinated compound phase-out deadlines reshape the acquisition landscape toward pre-validated silicone-alternative material platforms and captive North American manufacturing footprints. Long-term viability favors vertically integrated fabricators with veterinary endorsement networks over pure brand plays dependent on Asian contract manufacturing. Watch for consolidation signals among specialty chemical houses developing REACH-compliant finishing technologies as inflection indicators for sector-wide supplier base restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Crash-Tested Safety Certification | Kurgo's automotive safety institute partnerships create defensible differentiation against unbranded commodity imports. |
| Silicone-Based Material Reformulation | REACH-compliant water-repellent alternatives secure European market access ahead of perfluorinated compound restrictions. |
| Vertical Manufacturing Integration | 4Knines' North Carolina captive production controls quality and insulates against trans-Pacific logistics disruption. |
| Truck Bed Specialization | Ruff Liners' hammock configurations address an underserved functional segment with limited direct competition. |
| Direct-to-Consumer Configuration | 3D scanning services compress traditional retail margins by eliminating inventory carrying costs and enabling vehicle-specific fit. |
Research Methodology
Desk research of trade customs data, automotive OEM accessory program disclosures, and ECHA regulatory filings preceded structured interviews with pet accessory brand managers, coated fabric procurement leads at textile laminators, veterinary clinic purchasing administrators, and automotive aftermarket category buyers. Secondary validation drew from CPSC enforcement actions, REACH substance restriction updates, and SEC filings of publicly traded pet product distributors. Bottom-up demand modeling triangulated against top-down market sizing from vehicle ownership demographics and pet humanization expenditure surveys.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning installation geometry, material chemistry compliance tier, functional feature bundling, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation moderated by saturation assumptions and replacement-cycle compression factors. Industry-specific forecast inputs incorporated petrochemical feedstock volatility indices and automotive OEM pet-accessory bundling penetration assumptions.
Underlying assumptions cover REACH reformulation timeline adherence, continued suburban vehicle ownership density in the United States, and silicone-based water-repellent treatment performance parity with legacy fluoropolymers, with deviation risk concentrated in regulatory deadline acceleration, automotive OEM bundling program expansion, and trans-Pacific logistics cost spikes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Bird Toy Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Dog Food Market
Pet Care Products
United States Pet Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
Pet Collar Market
Pet Care Products
Pet Daycare Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Dog Pillow Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Pet Tech Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Pet Selfie Tools Market