
 Frozen Pet Food Market | 2026-2036
Frozen Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Pet Food Market Analysis
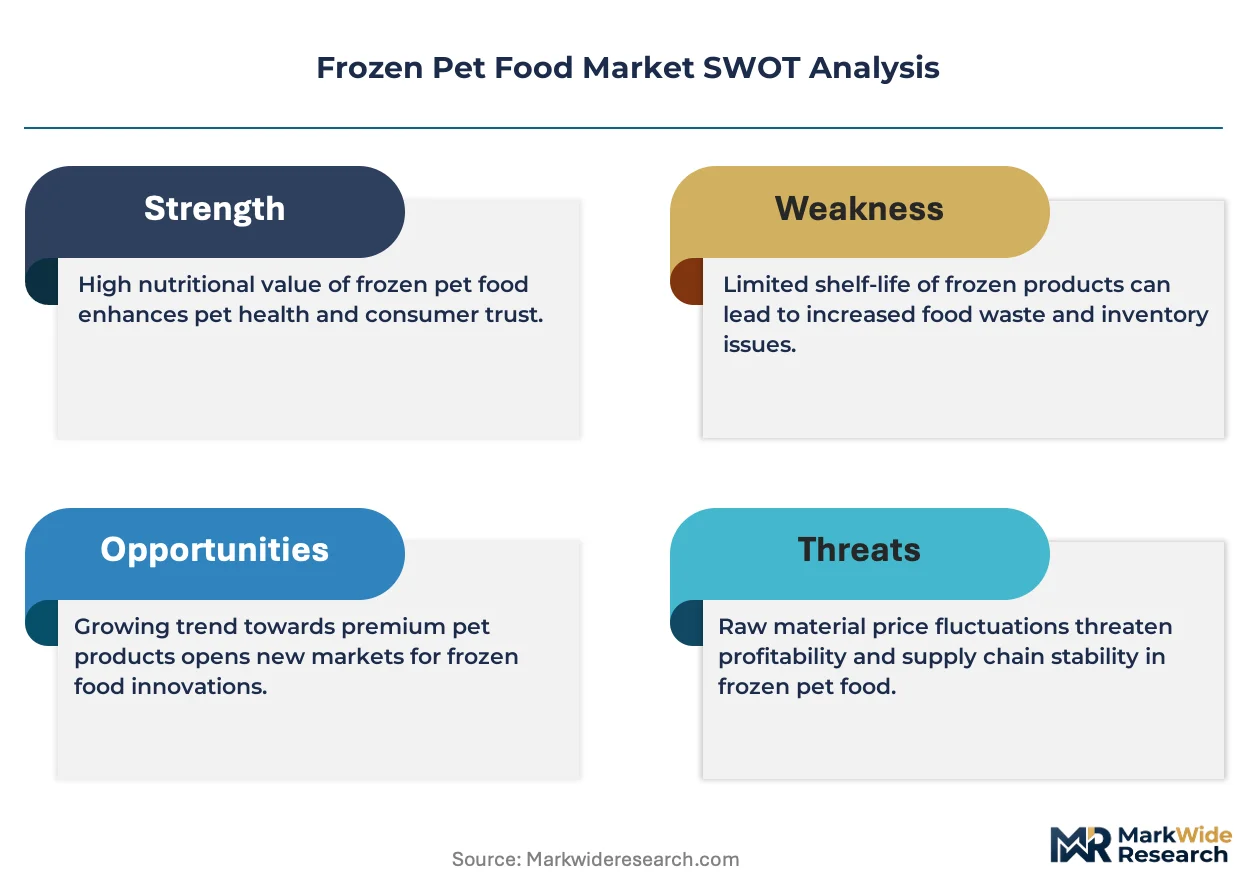
Premium raw-meat specification tiers is rotating the frozen pet food category toward veterinary-grade nutrition claims. Stella & Chewy's leverages its USDA-inspected manufacturing network to anchor quality consistency across retail and veterinary channels. Mars Petcare competes through scale advantages in cold-chain distribution, while Primal Pet Foods differentiates via species-specific raw formulations targeting allergen-sensitive companion animals.
Frozen pet food denotes minimally processed animal proteins preserved below freezing temperatures, typically formulated at negative eighteen degrees Celsius to maintain enzymatic activity and amino acid integrity; this preservation method serves commercial purposes by delivering unaltered nutrient profiles that extruded kibble cannot replicate. Raw food and freeze-dried segments command the deepest margin pools due to ingredient transparency premiums and shorter ingredient decks, whereas frozen kibble occupies volume leadership through price accessibility and freezer-section placement density in mass retail. The online retailer channel within end-user segmentation is expanding fastest as refrigerated last-mile logistics mature and subscription auto-ship models reduce customer acquisition costs.
FDA Center for Veterinary Medicine oversight and AAFCO model feed regulations shape permissible label claims, nutrient profiles, and pathogen-testing protocols for raw and frozen formats entering interstate commerce. State-level agriculture departments in Wisconsin, Texas, and Pennsylvania enforce additional cold-chain sanitation standards that create compliance barriers for uninspected facilities. Stakeholders must monitor evolving raw-meat pathogen guidance and freezer-capacity constraints in specialty retail as shelf-space competition intensifies between established brands and direct-to-consumer entrants.
Market Dynamics
Cold-chain logistics maturation is compressing delivery windows for temperature-sensitive raw diets, enabling subscription models to displace traditional retail freezer placement as the primary customer acquisition channel.
Growth Catalysts
- AAFCO Model Feed Regulations:Standardized nutrient profiles reduce formulation ambiguity for raw-food manufacturers entering interstate commerce, accelerating product registration timelines.
- Freeze-drying technology:Lyophilization equipment advances cut moisture-removal energy costs by half, expanding margin pools for small-batch producers competing against mass-market extruded kibble.
- Urban pet ownership clusters:Dense metropolitan populations in the United States concentrate demand for veterinary-grade nutrition claims, driving premium-tier volume through direct-to-consumer channels.
Market Restraints
- Protein input volatility:Beef and poultry trim prices fluctuate with livestock commodity cycles, compressing gross margins for raw-formulation specialists without long-term supply contracts.
- Cold-chain infrastructure gaps:Last-mile refrigerated delivery remains underdeveloped in secondary US markets, limiting geographic expansion for frozen-format entrants.
- Pathogen testing mandates:FDA Center for Veterinary Medicine protocols require lot-level Salmonella and Listeria screening, adding fixed compliance costs that disproportionately burden small manufacturers.
Strategic Opportunities
- Veterinary channel integration:Prescription raw diets positioned for allergen management and renal support capture margin premiums unavailable in mass retail.
- High-pressure processing (HPP):Non-thermal pasteurization technology convergence with raw nutrition preserves enzymatic activity while satisfying retailer liability requirements.
- Subscription auto-ship platforms:Recurring revenue models reduce customer acquisition costs and build predictable demand signals for production planning.
Industry Challenges
- Cold-chain talent scarcity:Refrigerated logistics specialists and HACCP-certified plant managers command wage premiums that inflate operational overhead.
- Freezer capacity constraints:Specialty pet retail chains face shelf-space competition between established brands and direct-to-consumer entrants, forcing slotting fee negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Pet Food Market |
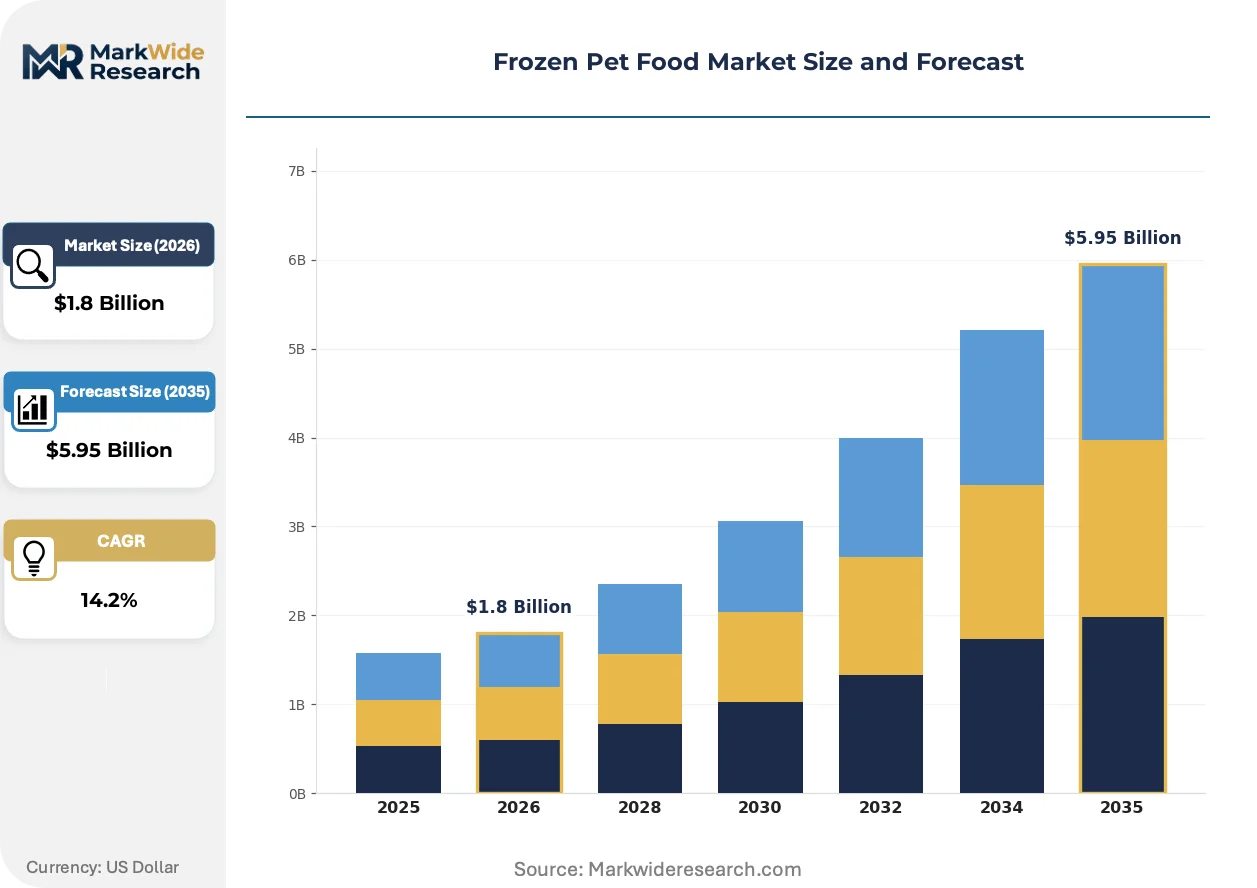
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Food, Frozen Kibble, Freeze-Dried, Frozen Treats End User: Pet Owners, Veterinary Clinics, Pet Stores, Online Retailers Packaging Type: Frozen Bags, Resealable Pouches, Trays, Cartons Form: Cubes, Patties, Medallions, Chunks |
| Companies Covered | Stella & Chewy's, Primal Pet Foods, Nestle Purina PetCare, Mars Petcare, WellPet, Northwest Naturals, Bravo, Vital Essentials, Freshpet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Pet Food Market Emerging Trajectories
Preservation technology advances and regulatory clarity are converging to expand addressable demand beyond niche raw-feeding communities into mainstream pet owner segments previously deterred by safety concerns.
High-pressure processing (HPP) systems apply isostatic pressure to raw meat slurries, neutralizing vegetative pathogens without thermal degradation of amino acid structures. Mid-size manufacturers in Wisconsin and Pennsylvania are adopting HPP lines to secure placement in conventional grocery freezer sections. This technology is miniaturizing equipment footprints, enabling in-house processing that previously required tolling arrangements with third-party facilities.
The FDA Center for Veterinary Medicine issued updated guidance on raw-meat pet food manufacturing in 2023, clarifying pathogen-testing frequencies and environmental monitoring expectations. Facilities must now implement preventive controls analogous to human food safety plans, raising capital requirements for market entry. Small-batch producers in Texas and California are responding by consolidating production into USDA-inspected co-manufacturing networks rather than building captive capacity.
Subscription auto-ship models now capture the fastest-growing channel share as refrigerated last-mile carriers expand route density in metropolitan corridors. Direct-to-consumer entrants bypass retail slotting fees and freezer-space constraints, instead capturing lifetime value through personalized portioning algorithms. This shift concentrates demand in coastal urban clusters where cold-chain infrastructure supports reliable delivery windows.
Frozen Pet Food Market Segmentation
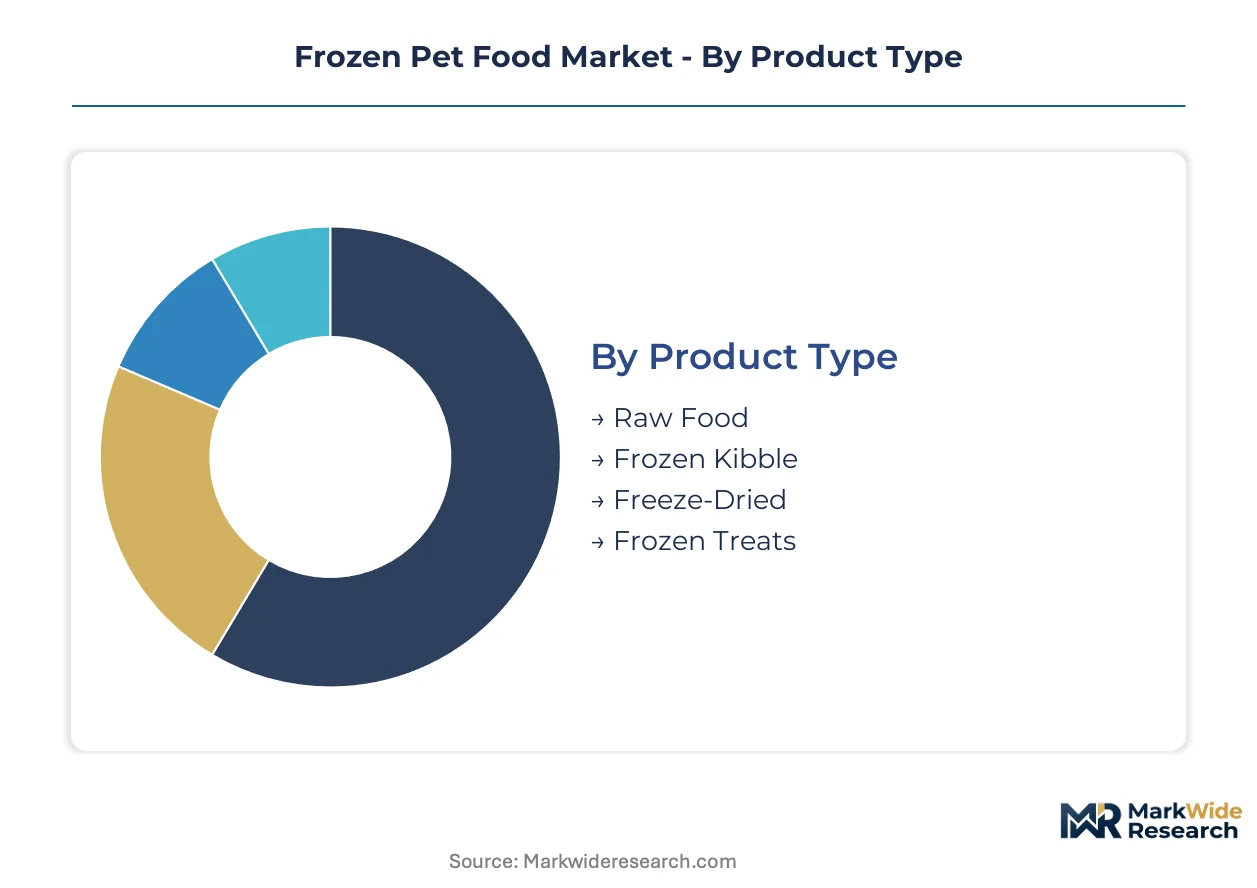
Frozen pet food segmentation reveals divergent margin structures across preservation technologies and channel economics. Raw and freeze-dried formats extract premium pricing through ingredient transparency, while frozen kibble competes on freezer-section accessibility. Understanding these segment boundaries clarifies where capital deployment yields sustainable returns versus commodity exposure.
Product Type:
Raw Food and Freeze-Dried segments concentrate in coastal metropolitan clusters with mature cold-chain infrastructure, while Frozen Kibble and Frozen Treats penetrate inland markets through mass retail distribution.
- Raw Food:Minimally processed animal proteins preserved below negative eighteen degrees Celsius maintain enzymatic activity and amino acid integrity that thermal processing destroys. Demand clusters in United States urban corridors where veterinary-grade nutrition claims resonate with allergen-sensitive companion animal owners. FDA Center for Veterinary Medicine pathogen-testing mandates raise compliance barriers that favor USDA-inspected manufacturing networks.
- Freeze-Dried:Lyophilization removes moisture through sublimation, yielding shelf-stable formats that bypass freezer-section constraints entirely. Metropolitan United States pet owners drive volume through subscription auto-ship platforms where portion personalization algorithms capture lifetime value. Energy cost advances in lyophilization equipment expand margin pools for small-batch producers competing against extruded kibble.
- Frozen Kibble:Extruded and rapidly chilled formulations occupy mass retail freezer density through price accessibility.
- Frozen Treats:Portion-controlled novelty formats target impulse purchase occasions in specialty pet retail chains.
Frozen Kibble commands the established base. The steepest expansion runs through Freeze-Dried.
End User:
Channel segmentation stratifies by customer acquisition economics, with subscription platforms reducing churn through auto-ship algorithms versus retail slotting fees that burden conventional freezer placement.
- Pet Owners:Direct-to-consumer subscription models bypass retail intermediary margins, capturing recurring revenue through personalized portioning based on breed, weight, and activity level. United States metropolitan corridors with reliable refrigerated last-mile logistics concentrate demand, particularly among urban households seeking veterinary-grade nutrition claims without clinic markups.
- Veterinary Clinics:Prescription raw diets for allergen management and renal support capture margin premiums unavailable in mass retail channels. Wisconsin and Pennsylvania facilities with USDA-inspected co-manufacturing relationships secure placement through therapeutic positioning that justifies reimbursement pathways.
- Pet Stores:Specialty retail chains face freezer capacity constraints forcing slotting fee negotiations between established brands and direct-to-consumer entrants.
- Online Retailers:Third-party marketplace platforms aggregate fragmented demand but compress margins through fulfillment fee structures.
Pet Stores command the established base. The steepest expansion runs through Online Retailers.
Packaging Type:
Packaging economics track cold-chain requirements, with multi-layer insulated formats commanding material cost premiums against standard frozen bags that depend on retail freezer infrastructure.
- Frozen Bags:Multi-layer polyethylene constructions with metallized barriers maintain thermal stability through distribution, dominating mass retail freezer sections where placement density drives volume. United States secondary markets with underdeveloped last-mile refrigeration rely on retail cold storage, reinforcing bag-format dominance.
- Resealable Pouches:Zipper-equipped flexible packaging extends product usability across multiple feedings, reducing waste perception among premium-tier purchasers. Direct-to-consumer subscription channels favor pouches for portion flexibility and shipping cube efficiency.
- Trays:Rigid thermoformed formats suit single-serve patties and medallions targeting precise portion control.
- Cartons:Paperboard-based frozen packaging addresses sustainability positioning in European markets with extended producer responsibility frameworks.
Frozen Bags command the established base. The steepest expansion runs through Resealable Pouches.
Form:
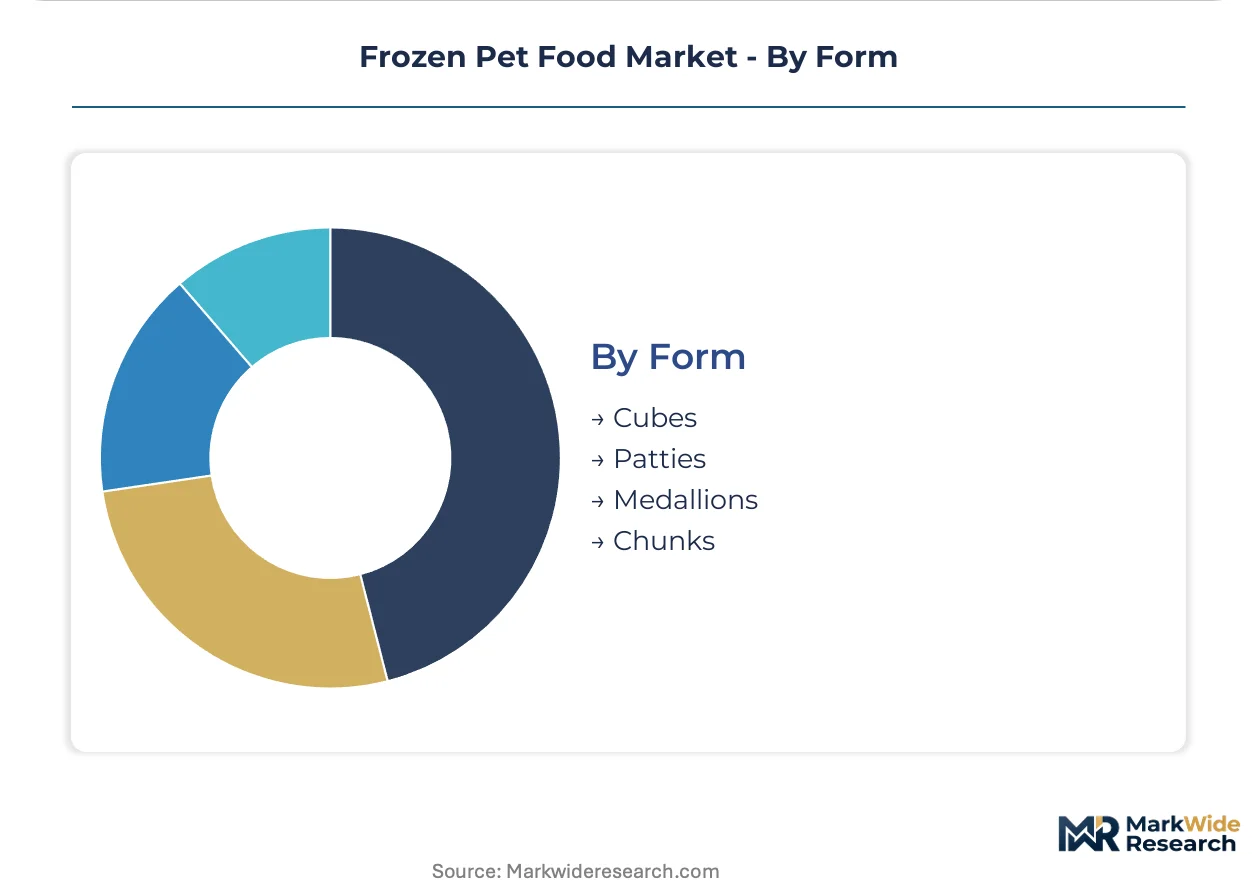
Physical form factors align with feeding ritual preferences and storage constraints, with portion-calibrated shapes reducing preparation friction for time-constrained urban owners.
- Patties:Pre-formed circular portions standardize feeding quantities across breed sizes, eliminating measurement steps that deter raw-feeding adoption. Veterinary clinic channels favor patties for prescription diet compliance, where precise caloric intake supports therapeutic outcomes for renal and weight-management protocols.
- Medallions:Smaller-diameter portion discs suit toy and small-breed companions, addressing the fastest-growing demographic in United States urban pet ownership. Subscription platforms leverage medallion formats for algorithm-driven portion customization.
- Cubes:Bulk frozen formats target multi-pet households seeking cost efficiency through manual portioning.
- Chunks:Irregular meat pieces replicate ancestral feeding textures for raw-feeding purists.
Cubes command the established base. The steepest expansion runs through Medallions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States exporters ship frozen raw pet food formulations to Canadian and British buyers through established cold-chain corridors, while German manufacturers supply freeze-dried formats across Continental Europe. This trade-flow pattern concentrates regulatory scrutiny and manufacturing investment in source markets with USDA-inspected or EFSA-aligned facilities.
United States
Urban pet ownership clusters in New York, Los Angeles, and Chicago drive subscription-format demand for veterinary-grade raw nutrition. FDA Center for Veterinary Medicine pathogen-testing mandates require lot-level Salmonella screening for interstate commerce. Wisconsin and Pennsylvania host USDA-inspected co-manufacturing networks that supply direct-to-consumer brands with HACCP-certified production capacity.
Germany
Metropolitan households in Berlin, Munich, and Hamburg prioritize freeze-dried formats with short ingredient decks and transparent sourcing. EFSA feed hygiene regulations enforce strict cold-chain documentation for raw-meat products entering cross-border distribution. Baden-Württemberg industrial clusters specialize in lyophilization equipment manufacturing that serves domestic pet food processors.
United Kingdom
London and Southeast England concentrate demand for premium raw diets through veterinary clinic channels and specialty retail chains. FSA and DEFRA import controls require third-country equivalence certification for frozen pet food entering from non-EU sources. Manchester-area cold-storage facilities expand capacity to handle growing direct-to-consumer fulfillment volumes.
Canada
Toronto and Vancouver metropolitan areas exhibit strong uptake of subscription-based frozen raw diets among urban millennials. Health Canada and CFIA enforce parallel pathogen-testing protocols to FDA standards for products crossing the US border. Alberta livestock supply chains provide beef and poultry trim inputs to Prairie-based raw-formulation specialists.
France
Île-de-France and Lyon urban centers show accelerating preference for frozen medallion formats targeting small-breed companions. ANSES nutritional safety guidelines shape permissible label claims for raw and freeze-dried products. Normandy agricultural regions supply antibiotic-free protein inputs to domestic manufacturers seeking export qualification.
Frozen Pet Food Market Vendor Landscape
Listed leaders compete with private specialists across cold-chain infrastructure and veterinary channel access, creating a tiered structure where scale advantages clash with formulation agility. Publicly traded entities leverage refrigerated distribution networks and retail freezer placement density, while private operators exploit subscription auto-ship models and species-specific recipes. Three archetypes dominate: diversified conglomerates with pet care divisions, pure-play raw-format specialists, and direct-to-consumer entrants with algorithm-driven personalization. Competitive moves center on co-manufacturing consolidation to secure USDA-inspected capacity and high-pressure processing technology licensing to unlock conventional grocery placement.
Within the raw-format specialist tier, Stella & Chewy's and Primal Pet Foods exemplify archetypes built on veterinary-grade positioning and species-specific formulations respectively. Mars Petcare occupies a position representing conglomerate-scale advantages in cold-chain distribution and mass retail penetration. These three anchors illustrate how competitive positioning stratifies between quality-certification depth and operational scale.
| Leading Market Players |
|---|
| Stella & Chewy's |
| Primal Pet Foods |
| Nestle Purina PetCare |
| Mars Petcare |
| WellPet |
| Northwest Naturals |
| Bravo |
| Vital Essentials |
| Freshpet |
| Others |
Supply Flow & Price Mechanics
USDA-inspected facility certification gates both supply qualification and price differentiation simultaneously, creating tiered access where only co-manufacturing networks with HACCP-certified cold-chain capacity can serve veterinary clinic and subscription channels commanding premium positioning.
Pricing Analysis
Subscription-format buyers anchor pricing structures around recurring revenue predictability rather than transactional spot purchasing. Three-tier pricing structure across premium raw, freeze-dried convenience, and frozen kibble accessibility segments reflects ingredient transparency grades and cold-chain delivery reliability. Cost compression in mass retail tiers is intensifying because freezer-section slotting fees inflate fixed cost absorption. Price-sensitive volume purchasers in secondary US markets without reliable last-mile refrigeration drive commoditization pressure, while least-sensitive urban subscribers absorb personalization premiums.
Supply Chain Analysis
Inventory lead times for temperature-sensitive raw meat formulations stretch 14-21 days from USDA-inspected slaughter to frozen finished goods, compressing production planning windows. Protein sourcing concentrates in Wisconsin, Texas, and Pennsylvania where livestock processing infrastructure feeds co-manufacturing networks. Beef trim, poultry meal, and synthetic vitamin premixes constitute critical input dependencies. Single-source vulnerability runs through limited HACCP-certified plant manager talent pools. Distribution runs through refrigerated last-mile carriers expanding metropolitan route density alongside conventional mass retail freezer placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription-format aggregators as direct-to-consumer platforms consolidate demand signals and disintermediate specialty retail freezer placement, fragmenting traditional channel control.
For Market Incumbents: Consolidate USDA-inspected co-manufacturing capacity in Wisconsin and Pennsylvania to secure production access against emerging direct-to-consumer entrants with algorithm-driven personalization. Lock in multi-year protein supply contracts with Alberta and Midwest livestock processors to buffer beef and poultry trim volatility. Deepen veterinary channel relationships through prescription diet positioning that justifies reimbursement pathways unavailable to mass retail competitors. For New Entrants and Emerging Players: Differentiate on species-specific raw formulations targeting allergen-sensitive companion animals, a white-space segment where incumbent portfolios remain underdeveloped. Penetrate secondary US markets with underdeveloped cold-chain infrastructure through freeze-dried formats that bypass freezer-section constraints entirely. Launch through veterinary clinic partnerships rather than mass retail to capture margin premiums and build clinical credibility. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine's 2023 updated guidance on raw-meat manufacturing reshapes the acquisition landscape by raising capital barriers for small-batch producers lacking preventive control infrastructure. Five-to-ten-year viability favors mid-size manufacturers with existing HPP technology licensing and USDA-inspected co-manufacturing relationships over greenfield entrants facing facility buildout timelines. Target acquisition archetypes include freeze-dried specialists with proprietary lyophilization equipment and established subscription auto-ship platforms with coastal metropolitan customer density. Watch for pathogen-testing mandate enforcement intensity as the signal indicating regulatory compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Technology Licensing | Non-thermal pasteurization unlocks conventional grocery freezer placement for raw formats. |
| USDA-Inspected Co-Manufacturing Consolidation | Captive production capacity secures supply access against rising pathogen-testing compliance barriers. |
| Subscription Auto-Ship Platform Buildout | Recurring revenue models reduce customer acquisition costs in metropolitan corridors. |
| Veterinary Channel Prescription Diet Positioning | Therapeutic claims capture margin premiums unavailable through mass retail intermediation. |
| Species-Specific Raw Formulation Development | Allergen-sensitive companion animal targeting differentiates against commoditized kibble portfolios. |
Methodological Framework
A spread of perspectives from frozen pet food manufacturing executives, veterinary clinic procurement managers, specialty retail category buyers, refrigerated logistics specialists, and direct-to-consumer platform operators converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, AAFCO model feed regulation filings, USDA-inspected facility registries, cold-chain logistics trade data, and refrigerated last-mile carrier route expansion disclosures. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segmentation dimensions modeled span preservation technology, distribution channel, packaging format, and physical form factor across the projection horizon. CAGRs derived from growth driver elasticity analysis calibrated to protein input cost trajectories and cold-chain infrastructure expansion patterns. Forecast inputs incorporated veterinary-grade nutrition claim penetration rates and subscription auto-ship adoption curves by metropolitan market density tier.
Material uncertainties — livestock commodity cycle volatility, FDA pathogen-testing enforcement intensity, and refrigerated last-mile carrier route expansion timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory guidance updates or cold-chain infrastructure investment delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Italy Pet Food Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
Aquarium Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Dog Collars Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Australia Pet Boarding Market