
 Dog Brush Market | 2026-2036
Dog Brush Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Brush Market Analytics
Subscription-based replacement blade programs is restructuring how consumable brush components reach end users. FURminator leverages direct-to-consumer replenishment models to lock in recurring revenue from deshedding tool owners. Wahl Clipper Corporation anchors its position through professional grooming channel relationships that sustain premium pricing. Spectrum Brands competes across mass retail with broad distribution controls that extend its shelf presence.
A dog brush is a handheld grooming implement featuring arranged filaments, pins, or rubber nodules designed to detangle coat fibers, distribute skin oils, and remove loose undercoat hair through mechanical friction against canine fur. Manufacturing typically involves injection-molded plastic handles with stainless steel or coated pin inserts, where pin density and tip geometry determine functional suitability across coat types. Slicker brush configurations dominate professional grooming margins due to their versatility across medium-to-long coat breeds. Bamboo material variants capture premium positioning as sustainability-conscious pet owners shift away from petroleum-based substrates. Grooming salons represent the highest-velocity end user channel, with volume purchasing patterns that differ structurally from individual pet owner buying behavior.
REACH in Europe governs chemical composition of polymer coatings and metal platings used in brush pin manufacturing, while FDA guidelines classify veterinary-grade grooming instruments under device quality standards that shape product liability exposure. The EPA regulates antimicrobial claims embedded in brush marketing, creating compliance costs for brands positioning products as hypoallergenic or bacteria-resistant. Stakeholders must monitor evolving material disclosure requirements across multiple jurisdictions while calibrating sourcing strategies between cost-optimized plastic production and certified sustainable alternatives that command shelf price premiums.
Market Dynamics
Subscription replenishment models for replacement blades are restructuring buyer relationships and locking in recurring revenue streams across professional and consumer grooming channels.
Growth Catalysts
- REACH compliance in Europe:Chemical safety mandates for polymer coatings are accelerating certified material sourcing among brush pin suppliers, creating competitive differentiation for compliant manufacturers.
- Pet humanization in grooming salons:Professional channels now command volume purchasing with service bundling that sustains premium pricing for veterinary-grade instruments.
- Bamboo substrate adoption:Sustainability-conscious pet owners are displacing petroleum-based handles with certified renewable alternatives that command shelf price premiums.
Market Restraints
- Stainless steel input volatility:Brush pin manufacturing faces margin pressure from fluctuating commodity costs for coated metal filaments.
- Chinese manufacturing concentration:Domestic scaling for export markets creates supply-side dependency on a single geography for cost-optimized plastic production.
- FDA device classification friction:Veterinary-grade instrument standards impose extended compliance timelines and liability exposure for professional grooming tool suppliers.
Strategic Opportunities
- Underpenetrated professional channels in India:Rising pet ownership and grooming service expansion create white space for veterinary-grade instrument distribution.
- Antimicrobial claim positioning:EPA-regulated hypoallergenic marketing opens premium tier development for bacteria-resistant coating technologies.
- Direct-to-consumer blade replenishment:Locked-in recurring revenue models for deshedding tool consumables bypass traditional retail margin structures.
Industry Challenges
- Pin geometry certification complexity:Breed-specific coat compatibility testing requires specialized veterinary dermatology partnerships that extend product development cycles.
- Multi-jurisdiction material disclosure:REACH, FDA, and EPA filing requirements create fragmented compliance documentation that strains smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Brush Market |
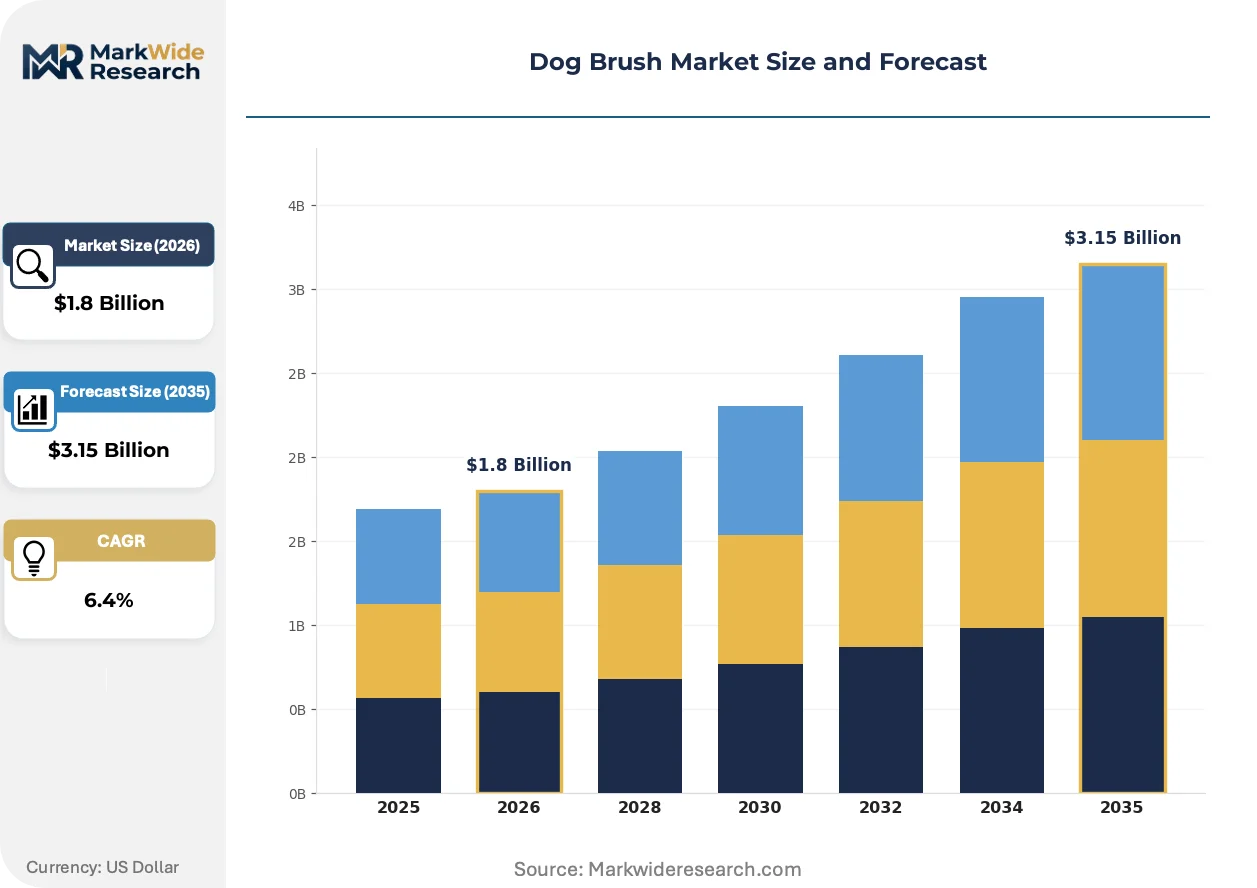
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slicker Brush, Pin Brush, Bristle Brush, Rubber Brush Material: Plastic, Metal, Bamboo, Nylon End User: Pet Owners, Grooming Salons, Veterinary Clinics, Pet Retailers Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | FURminator, Wahl Clipper Corporation, Ancol Pet Products, Ferplast S.p.A., Petco Animal Supplies Inc., PetEdge, Hertzko, KONG Company, Spectrum Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Brush Market Evolving Landscape
Material convergence and regulatory disclosure requirements are compressing traditional supply chains while opening premium positioning for certified sustainable alternatives.
Biodegradable polymer composites are unifying handle construction with end-of-life disposal standards. Grooming salons in Germany and France are adopting these materials at accelerated pace to meet municipal waste directives. This technology is unifying cost-optimized manufacturing with circular economy certification that commands professional channel premiums.
REACH substance of very high concern screening now governs nickel release from brush pin platings used in veterinary-grade instruments. European manufacturers face reformulation costs for chrome alternatives that satisfy ECHA disclosure thresholds. Slicker brush configurations with certified hypoallergenic coatings are most affected, with suppliers accelerating stainless steel substitution programs.
Replacement blade subscription contracts are compressing traditional retail replenishment cycles. Professional groomers now source consumables through locked-in direct relationships rather than distributor intermediaries. This pattern is most visible in United States grooming salon chains where volume purchasing agreements consolidate supplier relationships.
Dog Brush Market Segmentation
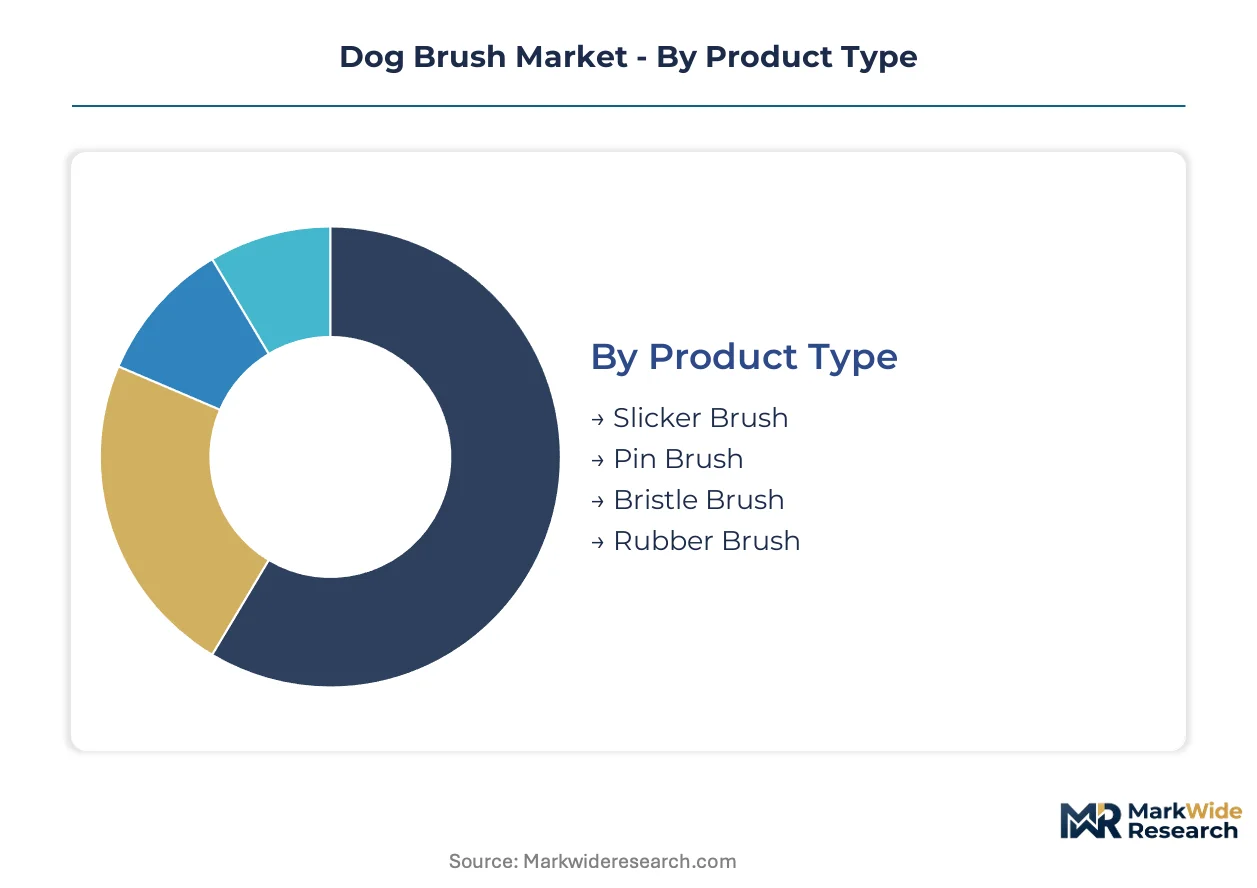
Segmentation in the dog brush market reveals how capital allocation, regulatory exposure, and channel economics diverge across product configurations. Manufacturers calibrate tooling investments and material sourcing strategies against the specific compliance burdens and margin profiles of each segment cluster.
Product Type:
Capital intensity varies sharply across brush architectures, with injection mold complexity and pin insertion automation driving fixed cost differentiation.
- Slicker Brush:Dense wire pin matrices mounted on cushioned pads require precision stamping and angled tip grinding. Grooming salons in Germany and France absorb the majority of volume as professional groomers prioritize coat penetration versatility across medium-to-long fur breeds.
- Pin Brush:Longer, widely spaced pins with rounded tips demand lower tooling investment but specialized veterinary dermatology partnerships for safety certification. Pet owners in the United States concentrate demand here for daily maintenance of double-coated breeds.
- Bristle Brush:Natural or synthetic fiber tufts bonded into wooden or plastic blocks serve short-coated breeds with minimal undercoat. The configuration suits mass retail distribution with compressed margin structures.
- Rubber Brush:Molded silicone or rubber nodules integrated into palm-fit designs target bath-time deshedding applications. Domestic Chinese manufacturers dominate supply with cost-optimized thermoplastic elastomer formulations.
Slicker brush configurations absorb the bulk of installed capacity; rubber brush variants are expanding most quickly.
Material:
Raw material selection determines REACH filing obligations, FDA device classification exposure, and end-of-life disposal compliance costs.
- Plastic:Polypropylene and ABS handle substrates paired with injection-molded grip textures dominate volume production. Chinese manufacturing clusters in Zhejiang and Guangdong supply cost-optimized grades that face ECHA substance of very high concern screening for phthalate plasticizers.
- Metal:Stainless steel pin stock with nickel or chrome plating requires the highest capital intensity for plating line installation and wastewater treatment. European suppliers absorb elevated compliance costs for ECHA nickel release thresholds.
- Bamboo:Laminated grass fiber handles certified under FSC or PEFC chain-of-custody command shelf price premiums. Sustainability-conscious pet owners in California and Pacific Northwest metropolitan areas drive demand concentration.
- Nylon:Glass-filled polyamide substrates deliver structural rigidity for large-breed brush heads. The material bridges cost efficiency with performance specifications for veterinary-grade instrument durability.
Plastic substrates carry the heaviest production volume; bamboo variants gain share fastest among premium-positioned SKUs.
End User:
Procurement patterns diverge structurally between individual purchasing decisions and institutional volume agreements with service bundling requirements.
- Pet Owners:Individual consumers purchasing through mass retail or direct-to-consumer channels prioritize ergonomic design and price accessibility. Amazon and Chewy fulfillment networks concentrate distribution with compressed delivery timelines.
- Grooming Salons:Professional service providers negotiate locked-in replenishment contracts for consumable blade components. United States salon chains consolidate supplier relationships through volume purchasing agreements that bypass distributor margins.
- Veterinary Clinics:Clinical settings demand FDA device classification compliance for instruments used in dermatological examinations. Extended liability exposure and sterilization compatibility requirements elevate procurement standards.
- Pet Retailers:Specialty store buyers curate assortment breadth across coat type compatibility with SKU productivity metrics governing shelf space allocation. Independent pet stores in suburban markets maintain higher service bundling rates than big-box competitors.
Grooming salons command the highest procurement velocity; veterinary clinics impose the steepest compliance burden per unit.
Capacity:
Scale segmentation aligns brush head dimensions with breed size distribution and coat volume handling requirements.
- Small:Compact brush heads under 3 inches suit toy breeds and facial grooming precision. The segment carries minimal material cost but requires specialized pin density configurations.
- Medium:Standard 3-4 inch brush heads serve the broadest breed range from Beagles to Border Collies. Mass retail distribution concentrates here with economy-to-premium tier differentiation.
- Large:Extended brush surfaces accommodate Golden Retrievers and German Shepherds with accelerated grooming throughput. Professional groomers prioritize large-capacity tools for salon productivity metrics.
- Extra Large:Oversized configurations for Giant Schnauzers, Newfoundlands, and Great Pyrenees demand reinforced handle structures. The segment represents the lowest volume but highest per-unit margin opportunity.
Medium capacity absorbs the bulk of unit volume; extra large configurations climb the fastest among professional channel SKUs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo anchors the global manufacturing footprint for injection-molded brush handles, with Zhejiang province clusters supplying cost-optimized plastic substrates to export markets across North America and Europe.
United States
Pet humanization drives grooming salon expansion in California and Texas metropolitan corridors. FDA device classification standards for veterinary-grade instruments elevate compliance costs for professional channel suppliers. Chicago-area distributors consolidate volume purchasing agreements that bypass traditional retail intermediaries.
Germany
Grooming salons in Bavaria and North Rhine-Westphalia absorb premium-tier slicker brush volumes for medium-to-long coat breeds. ECHA nickel release thresholds under REACH force reformulation of chrome-plated pin stock toward stainless steel alternatives. Hamburg-based importers curate certified sustainable bamboo handle assortments for sustainability-conscious pet owners.
China
Domestic pet ownership surges in Shanghai and Beijing metro areas, creating parallel demand for both mass-market and premium brush configurations. MEE environmental standards tighten wastewater treatment requirements for plating operations in the Pearl River Delta. Ningbo manufacturers scale thermoplastic elastomer production for rubber brush variants serving bath-time deshedding applications.
France
Professional groomers in Île-de-France and Provence-Alpes-Côte d'Azur prioritize REACH-compliant hypoallergenic coating technologies. ANSM oversight of dermatological safety claims shapes marketing language for slicker brush positioning. Lyon-area veterinary clinics drive procurement of sterilization-compatible instruments with extended liability coverage.
India
Rising pet ownership in Mumbai and Delhi-NCR metros expands grooming service penetration beyond traditional veterinary channels. BIS quality certification requirements for imported grooming instruments create entry barriers for uncertified suppliers. Maharashtra-based distributors test professional channel consolidation models mirroring United States salon chain procurement patterns.
Dog Brush Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where injection molding investments separate volume manufacturers from brand marketers. The vendor base clusters around three archetypes: integrated fabricators controlling handle molding and pin insertion, brand licensors outsourcing production to Asian contract manufacturers, and subscription-platform operators capturing recurring blade replenishment revenue. Consolidation pressures concentrate among mid-tier players lacking scale for REACH compliance or direct-to-consumer infrastructure. Dominant competitive moves include backward integration into captive polymer compounding and strategic partnerships with veterinary dermatology certification bodies.
Within the subscription-platform archetype, FURminator exemplifies locked-in recurring revenue models for deshedding tool consumables. Wahl Clipper Corporation anchors the professional grooming channel tier through United States-based manufacturing heritage. Spectrum Brands occupies a position across mass retail distribution networks with broad shelf presence controls. These three represent divergent strategic postures: direct-to-consumer replenishment, professional channel premium pricing, and economy-tier volume scale.
| Leading Market Players |
|---|
| FURminator |
| Wahl Clipper Corporation |
| Ancol Pet Products |
| Ferplast S.p.A. |
| Petco Animal Supplies Inc. |
| PetEdge |
| Hertzko |
| KONG Company |
| Spectrum Brands |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Zhejiang province anchor injection-molded handle production, translating concentrated ownership into disciplined capacity management that limits price erosion across export tiers. Their financing patterns favor equipment reinvestment over margin competition, creating structural pricing floors that resist commodity pressure from mass-market competitors.
Pricing Analysis
Throughput-based grooming efficiency anchors professional channel pricing, with salon productivity metrics justifying premium tiers for large-capacity slicker configurations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified veterinary-grade instruments from mass retail SKUs. Cost compression in plastic substrate tiers intensifies because Chinese manufacturers scale thermoplastic elastomer output for rubber brush variants. Individual pet owners through Amazon and Chewy fulfillment networks exhibit highest price sensitivity; grooming salon chains with locked-in replenishment contracts show least.
Supply Chain Analysis
Replacement blade return flows from grooming salon chains feed refurbishment programs that recover stainless steel pin stock for reprocessing, compressing raw material procurement cycles. Manufacturing gravity centers on China, with Ningbo and Guangdong clusters supplying injection-molded handles, while Germany and Italy host specialized plating operations for hypoallergenic coatings. Brush pin production draws from stainless steel feedstock, nickel and chrome plating chemicals, and thermoplastic elastomer formulations. Single-source vulnerability concentrates in Zhejiang province mold-making capacity. Distribution runs through Chicago-area consolidators for United States professional channels and Hamburg-based importers for European premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plating line capacity for REACH-compliant hypoallergenic coatings operates at effective constraint, propping pricing premiums for veterinary-grade instruments across European professional channels.
For Market Incumbents: Extend backward integration into captive polymer compounding to secure phthalate-free substrate supply ahead of ECHA substance screening expansion. Lock in veterinary dermatology certification partnerships to defend against emerging bamboo-handle specialists capturing sustainability premiums. Channel control through direct-to-consumer blade replenishment platforms offers defensive moat against mass retail price erosion. For New Entrants and Emerging Players: The mid-tier price gap between FSC-certified bamboo handles and commodity polypropylene substrates offers entry point for laminated grass fiber specialists with municipal waste directive alignment. India's underpenetrated professional grooming channel in Maharashtra and Delhi-NCR metros presents most penetrable geography. Go-to-market through BIS-certified import partnerships bypasses quality certification barriers for uncertified suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European plating specialists facing ECHA nickel release reformulation costs in Germany and France. Five-to-ten year viability hinges on subscription-platform infrastructure for consumable blade replenishment. Watch for grooming salon chain consolidation velocity in United States metropolitan corridors as inflection signal for professional channel pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive phthalate-free substrate supply secures REACH compliance ahead of ECHA screening expansion. |
| Veterinary Dermatology Certification Partnership | Breed-specific coat compatibility testing extends product development cycles but locks in professional channel premiums. |
| Direct-to-Consumer Blade Replenishment Platform | Locked-in recurring revenue bypasses distributor margins and compresses retail replenishment cycles. |
| Bamboo Handle FSC Certification Investment | Chain-of-custody credentials command shelf price premiums from California and Pacific Northwest pet owners. |
| Indian Professional Channel Distribution Buildout | BIS-certified import partnerships capture rising grooming service penetration in Mumbai and Delhi-NCR metros. |
Research Methodology
Multi-period observation of grooming salon procurement patterns, veterinary clinic instrument standards, and e-commerce SKU velocity anchored the trend analysis, supplemented by interviews with injection molding plant managers in Zhejiang province, professional groomer association heads in Bavaria and Texas, pet retailer category buyers, and REACH compliance consultants. Secondary validation drew from ECHA substance screening databases, FDA device classification filings, customs records for brush handle trade flows, and SEC disclosures from listed pet care conglomerates. Bottom-up capacity estimates from Ningbo manufacturing clusters triangulated against top-down demand modeling from pet ownership surveys.
Segment-weighting across product type, material substrate, end-user channel, and capacity tier shaped the analytical framework across the projection horizon. Modeled dimensions included slicker versus pin versus bristle versus rubber architectures; plastic, metal, bamboo, and nylon material grades; pet owner, grooming salon, veterinary clinic, and pet retailer procurement patterns; and small through extra-large capacity specifications. CAGRs were derived from installed capacity trajectories and replacement cycle frequencies. Industry-specific forecast inputs incorporated REACH compliance cost pass-through rates and subscription replenishment adoption curves.
Inputs from professional groomer procurement databases and veterinary clinic purchasing records were available through the study window; gaps in real-time salon chain inventory positioning introduce uncertainty bands around near-term demand spikes. Forecasts reflect documented assumptions regarding pet humanization trend persistence and regulatory disclosure timeline stability. Practitioners should monitor ECHA nickel release threshold enforcement intensity and United States grooming salon chain consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
India Pet Food Market
Pet Care Products
Dog Pen Market
Pet Care Products
Pet Care Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
Poland Pet Food Market
Pet Care Products
Paw Plunger Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Plant-Based Pet Food Market