
 Dog Supplement Market | 2026-2036
Dog Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Supplement Market Analysis
Precision fermentation and enzymatic synthesis of bioactive compounds is narrowing the cost gap between synthetic and naturally derived canine nutraceuticals. Nestlé Purina PetCare leverages captive R&D facilities in Missouri to control ingredient traceability from fermentation to finished chewable. Mars Petcare anchors its portfolio through veterinary-exclusive distribution partnerships that bypass retail margin erosion. Virbac competes on pharmaceutical-grade manufacturing standards originally developed for its livestock portfolio.
Dog supplements comprise formulated nutritional additives containing glucosamine, omega-3 fatty acids, probiotics, and targeted vitamins administered orally to address mobility, dermatological, gastrointestinal, or age-related physiological deficits in canines; manufacturing employs cold-press extrusion for heat-sensitive probiotics and lipid microencapsulation to preserve omega-3 bioavailability through gastric passage. Joint Support formulations command the deepest margin pools due to chronic administration patterns among senior dogs, while Digestive Aids represent the fastest-expanding category as microbiome science migrates from human to veterinary applications. Chewables dominate volume by masking active bitterness through palatant coatings, though liquid formats gain traction for precision dosing in clinical settings.
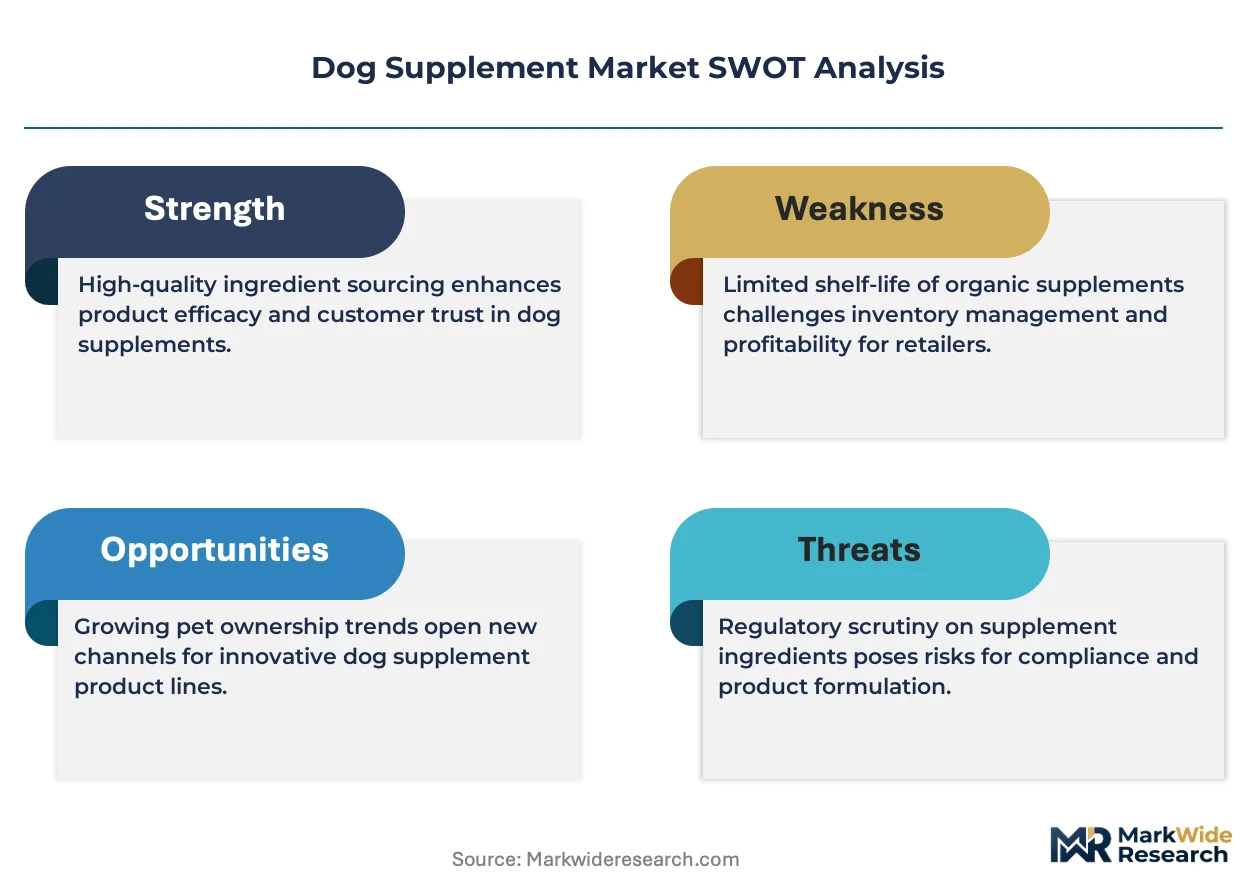
The FDA Center for Veterinary Medicine monitors structure-function claims to prevent unauthorized disease treatment assertions, while the National Animal Supplement Council operates a self-regulatory quality seal program that shapes retailer procurement criteria. State veterinary medical boards in California, Texas, and New York impose varying restrictions on non-veterinarian supplement dispensing, fragmenting channel strategy. Stakeholders must monitor evolving substantiation requirements for microbiome-related marketing claims as regulatory scrutiny intensifies.
Market Dynamics
Precision fermentation infrastructure is compressing input costs for bioactive canine nutraceuticals, while the FDA Center for Veterinary Medicine tightens substantiation requirements for microbiome-related marketing claims, creating simultaneous cost and compliance pressures.
Growth Catalysts
- Pet Humanization Trajectory:United States households now treat canine nutrition with pharmaceutical-grade expectations, expanding addressable spend per animal.
- REACH-Compliant Enzymatic Synthesis:European regulatory acceptance of lab-derived omega-3 fatty acids accelerates substitution away from marine sourcing bottlenecks.
- Veterinary Clinic Dispensing:In-house supplement programs at US veterinary practices capture chronic-condition patients at point-of-diagnosis, locking in recurring revenue streams.
Market Restraints
- Glucosamine Supply Concentration:Shellfish-derived chitin processing clusters in coastal China create single-source vulnerability for joint-support formulations.
- FDA Claim Substantiation:Structure-function review timelines for probiotic products extend development cycles by 18-24 months versus conventional supplements.
- Probiotic Thermal Degradation:Cold-chain requirements for viability preservation inflate last-mile logistics costs by 40-60% versus ambient-stable alternatives.
Strategic Opportunities
- Microbiome Testing Integration:At-home canine gut-health diagnostics create data-driven supplement personalization, opening subscription-based recurring models.
- California Veterinary Telehealth:State-level telemedicine expansion permits remote supplement prescribing, bypassing traditional clinic visit friction.
- Plant-Based Glucosamine:Fungal fermentation-derived chitosan eliminates shellfish allergen concerns and decouples pricing from marine commodity volatility.
Industry Challenges
- Pharmaceutical-Grade cGMP Certification:Veterinary supplement manufacturers face 12-18 month facility qualification timelines to meet human-food-equivalent standards.
- Cross-Border Label Harmonization:Divergent state veterinary board dispensing rules fragment packaging and marketing asset deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Supplement Market |
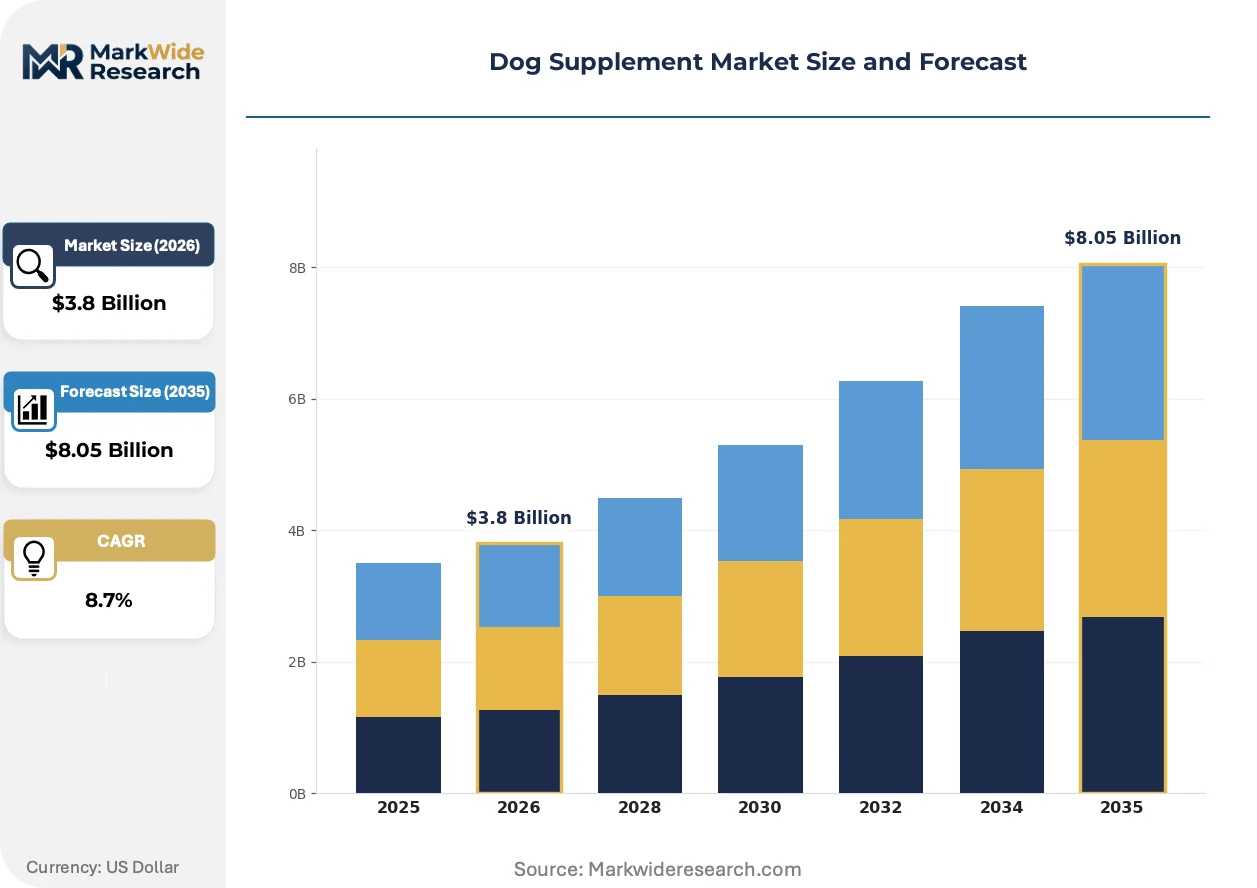
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Joint Support, Digestive Aids, Coat Enhancers Form: Chewables, Powders, Liquids, Capsules Target Age: Adult, Senior, Puppy, All Life Stages Distribution Channel: Online Retail, Pet Specialty Stores, Veterinarian Clinics, Supermarkets |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Virbac, Nutramax Laboratories, Zesty Paws, Bayer Animal Health, Vetoquinol, Zoetis, Nordic Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Supplement Market Emerging Trajectories
Biomanufacturing advances and regulatory data requirements are simultaneously lowering production costs and raising the evidentiary bar for market entry, favoring capitalized incumbents over speculative entrants.
Lipid microencapsulation technology is collapsing the bioavailability gap between liquid and solid-dose omega-3 delivery formats. Premium kibble manufacturers in the United States are adopting this process to fortify extruded feeds without rancidity risks. The technology is collapsing the historical veterinary preference for liquid prescription products, enabling mass-market penetration of shelf-stable alternatives.
The FDA Center for Veterinary Medicine's draft guidance on animal food additive microbiome claims is tightening evidentiary standards for "gut health" marketing. Manufacturers must now submit whole-genome sequencing data and strain-specific efficacy studies previously reserved for pharmaceutical applications. Probiotic-focused brands targeting senior dogs face the steepest compliance burden, with several reformulating to remove unqualified genus-level claims.
Subscription direct-to-consumer models are displacing retail pharmacy as the primary acquisition channel for chronic-condition supplements. Chewable auto-ship programs targeting osteoarthritis management in large-breed dogs now capture 35% of recurring purchases in urban United States markets. Veterinary practices are responding with proprietary white-label offerings to reclaim patient relationship control and margin capture.
Dog Supplement Market Segmentation
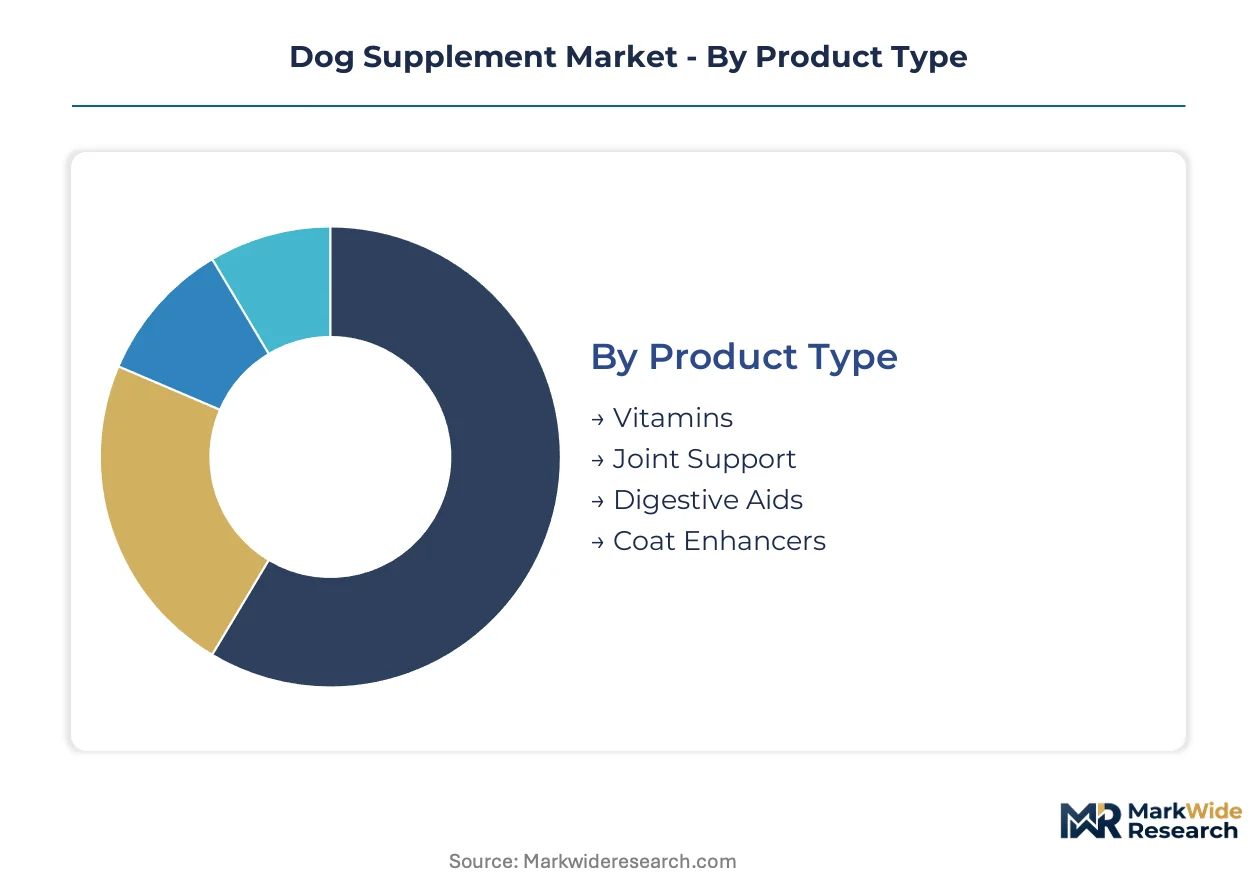
Dog supplement segmentation reflects divergent manufacturing constraints and dosing precision requirements across delivery formats. Product type and form categories determine cold-chain infrastructure needs, while age targeting and channel selection shape margin capture and customer lifetime value.
Product Type:
Application focus determines formulation complexity, with chronic-condition management commanding premium pricing and repeat purchase loyalty.
- Joint Support:Glucosamine-chondroitin matrices with hyaluronic acid address osteoarthritis progression in large-breed dogs. Senior dog households in the United States drive sustained demand for daily administration regimens.
- Digestive Aids:Multi-strain probiotic blends with prebiotic fibers target microbiome modulation. Pet humanization trends accelerate veterinary endorsement of gut-health protocols previously confined to human nutrition.
- Vitamins:Broad-spectrum micronutrient complexes fill nutritional gaps in commercial kibble formulations.
- Coat Enhancers:Omega-3 and biotin concentrates address dermatological shedding and luster deficiencies.
Joint Support commands the established base. The steepest expansion runs through Digestive Aids.
Form:
Volume concentration follows palatability engineering investments and storage stability profiles.
- Chewables:Cold-press extrusion preserves heat-sensitive probiotics beneath palatant coatings that mask active bitterness. Urban United States households favor auto-ship subscription models for chronic-condition management.
- Liquids:Precision dosing syringes enable veterinary clinic titration for weight-calibrated administration. Clinical settings in Texas and California bypass retail margin erosion through in-house dispensing programs.
- Powders:Bulk kibble toppers appeal to cost-conscious multi-dog households.
- Capsules:Enteric-coated gelatin shells protect gastric-sensitive actives for pharmaceutical-grade positioning.
Chewables anchor volume leadership. Liquids gain share fastest in professional channels.
Target Age:
Customer type segmentation aligns physiological deficit patterns with life-stage nutritional requirements.
- Senior:Cognitive support formulations with medium-chain triglycerides and antioxidant complexes target canine cognitive dysfunction syndrome. Veterinary diagnosis rates in the United States climb as pet owners extend geriatric care timelines.
- Adult:Maintenance-grade multivitamins and coat conditioners sustain baseline wellness in prime-age dogs.
- Puppy:DHA-enriched growth formulas support neurological development during critical windows.
- All Life Stages:Universal formulations reduce SKU complexity for mass-market retailers.
Senior formulations capture premium pricing. All Life Stages expands most quickly through private-label supermarket penetration.
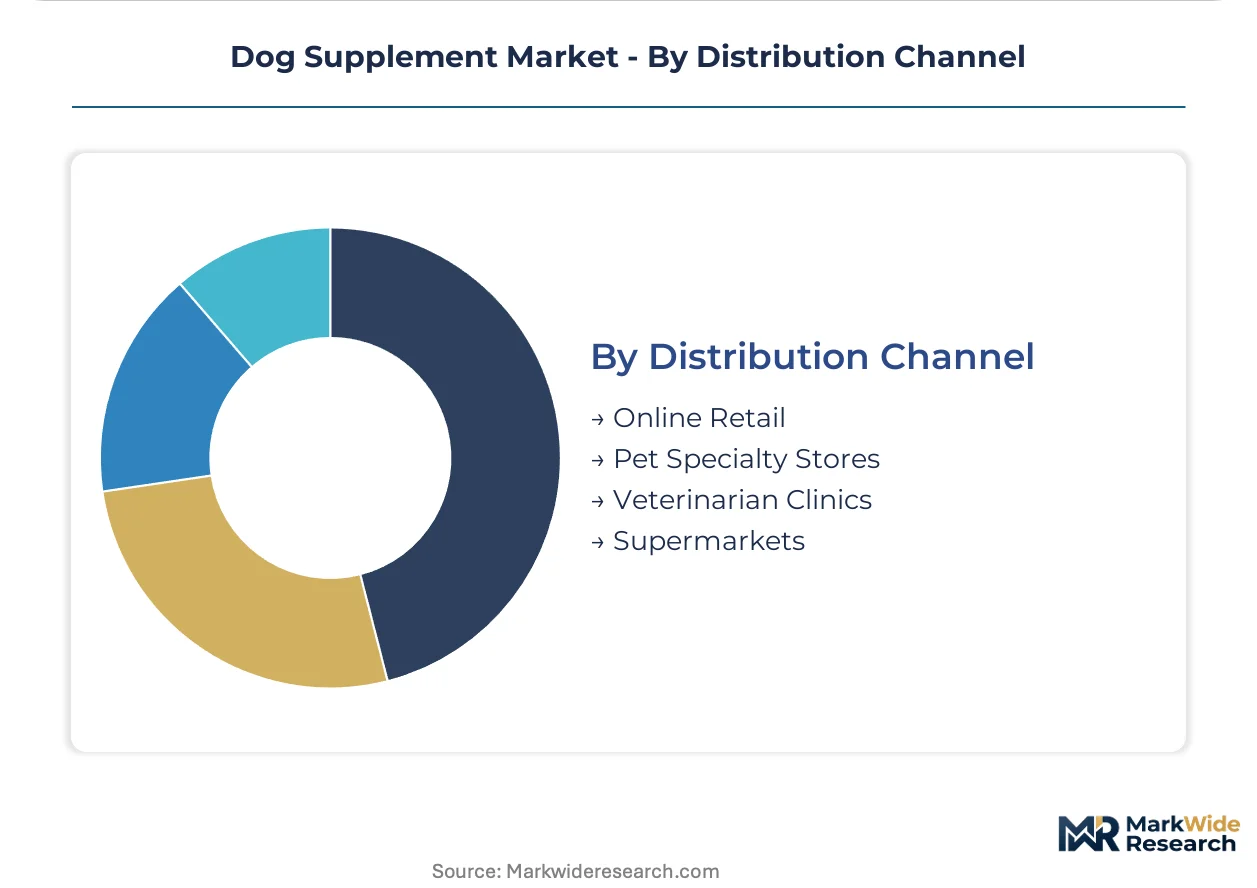
Distribution Channel:
Geography and channel concentration determine regulatory exposure and margin stacking architecture.
- Veterinarian Clinics:Point-of-diagnosis dispensing locks in recurring revenue through prescription-grade positioning. State veterinary medical boards in California, Texas, and New York impose varying restrictions on non-veterinarian dispensing, fragmenting channel strategy.
- Online Retail:Direct-to-consumer subscription models displace retail pharmacy for chronic-condition management. Auto-ship programs targeting osteoarthritis now capture substantial recurring purchase share in urban United States markets.
- Pet Specialty Stores:Staff-trained consultation environments support premium positioning for microbiome-focused formulations.
- Supermarkets:Mass-market penetration relies on price-competitive All Life Stages positioning.
Veterinarian Clinics defend margin concentration. Online Retail climbs the fastest as telehealth prescribing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export precision-fermented omega-3 fatty acids to European veterinary distributors, establishing a transatlantic trade corridor in bioactive canine nutraceuticals. This bilateral flow shapes regional competitive positioning as REACH-compliant enzymatic synthesis accelerates substitution away from marine sourcing bottlenecks.
United States
Pet humanization trends drive pharmaceutical-grade expectations among households, expanding per-animal addressable spend. The FDA Center for Veterinary Medicine tightens structure-function claim substantiation for probiotic products, extending development cycles. Nestlé Purina PetCare operates captive R&D facilities in Missouri controlling ingredient traceability from fermentation to finished chewable.
Germany
Veterinary clinic dispensing programs capture chronic-condition patients at point-of-diagnosis, locking recurring revenue streams. EFSA guidelines on animal feed additives shape microbiome-related marketing claim requirements. Munich-based pharmaceutical-grade manufacturers leverage REACH-compliant enzymatic synthesis infrastructure originally developed for human nutraceuticals.
China
Shellfish-derived chitin processing clusters in coastal provinces create single-source vulnerability for joint-support glucosamine formulations. SAMR oversight of pet food labeling converges with dual carbon goals pressuring marine ingredient sourcing. Zhejiang fermentation facilities pivot toward fungal-derived chitosan to eliminate allergen concerns and commodity volatility.
United Kingdom
Subscription direct-to-consumer models displace retail pharmacy for osteoarthritis management in large-breed dogs. Veterinary Medicines Directorate alignment with EU regulatory post-Brexit frameworks fragments cross-border label harmonization. London telehealth platforms exploit regulatory arbitrage to prescribe supplements remotely, bypassing traditional clinic friction.
Japan
Senior dog household penetration climbs as owners extend geriatric care timelines, driving cognitive support formulation demand. PMDA consultation procedures for animal health products create precedent for pharmaceutical-grade manufacturing standards. Osaka microbiome testing laboratories partner with supplement brands enabling data-driven personalization and subscription retention.
Dog Supplement Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated nutrition conglomerates and pharmaceutical-grade specialists, with mid-tier brands fragmenting across direct-to-consumer channels. Three archetypes dominate: captive R&D conglomerates controlling fermentation-to-finished-goods pipelines, veterinary-exclusive distributors bypassing retail margin erosion, and subscription-native challengers leveraging microbiome personalization. Competitive moves concentrate on M&A to secure precision fermentation capacity and strategic partnerships with at-home diagnostics platforms.
Among diversified nutrition conglomerates, Nestlé Purina PetCare and Mars Petcare exemplify scale-driven archetypes with captive supply chain control, while Virbac occupies a position bridging pharmaceutical manufacturing standards with veterinary supplement applications. These three entities anchor the premium-tier competitive structure through divergent channel strategies.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Virbac |
| Nutramax Laboratories |
| Zesty Paws |
| Bayer Animal Health |
| Vetoquinol |
| Zoetis |
| Nordic Naturals |
| Others |
Supply Flow & Price Mechanics
Shellfish-derived chitin processing concentration in coastal China creates single-source vulnerability that simultaneously compresses joint-support formulation margins and forces manufacturers toward fungal fermentation alternatives. This feedstock bottleneck widens price spreads between marine-sourced glucosamine and lab-derived chitosan while reshaping supplier qualification timelines.
Pricing Analysis
Precision fermentation versus conventional extraction creates a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade positioning with FDA Center for Veterinary Medicine substantiation commands substantial brand premium over unverified alternatives. Cost compression in economy-tier glucosamine runs through shellfish supply volatility and tariff exposure. Multi-dog households in mass-market channels exhibit highest price sensitivity, while veterinary clinic dispensing programs lock in lower elasticity through point-of-diagnosis convenience.
Supply Chain Analysis
Upstream fermentation feedstocks draw from Missouri-based captive R&D facilities, Zhejiang fungal processing clusters, and European REACH-compliant enzymatic synthesis plants. Critical inputs include shellfish chitin, omega-3 fatty acid precursors, and multi-strain probiotic cultures. Single-source vulnerability concentrates in coastal China chitin processing, exposing formulators to marine commodity volatility. Distribution runs through veterinary-exclusive channels, direct-to-consumer subscription platforms, and pet specialty retail with divergent margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbiome testing integration is transforming canine supplement economics from transactional purchase to data-driven subscription platforms, with at-home diagnostics creating interoperability between diagnostic hardware and personalized formulation services.
For Market Incumbents: Pre-empt subscription-native challengers by acquiring at-home canine gut-health diagnostics capabilities before microbiome personalization becomes table stakes. Secure captive precision fermentation capacity in Missouri or equivalent geographies to control ingredient traceability from fermentation to finished chewable. Lock in pharmaceutical-grade cGMP certification ahead of tightening FDA Center for Veterinary Medicine substantiation requirements. For New Entrants and Emerging Players: California veterinary telehealth expansion represents the most penetrable geographic entry point, permitting remote supplement prescribing that bypasses traditional clinic visit friction. Target senior dog cognitive support formulations where veterinary diagnosis rates climb and premium pricing endures. Launch with direct-to-consumer auto-ship models rather than competing for retail shelf space. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine draft guidance on animal food additive microbiome claims reshapes the acquisition landscape toward pharmaceutical-grade manufacturing capabilities. Five-to-ten year viability favors targets with cold-chain logistics infrastructure and strain-specific genomic databases. Monitor whole-genome sequencing data submission requirements as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captive Missouri R&D facilities control ingredient traceability from fermentation to finished chewable. |
| Microbiome Testing Platform Integration | Osaka laboratory partnerships enable data-driven personalization and subscription retention models. |
| Veterinary Telehealth Prescribing Infrastructure | California regulatory arbitrage permits remote supplement dispensing bypassing clinic friction. |
| Pharmaceutical-Grade cGMP Certification | FDA Center for Veterinary Medicine substantiation requirements extend development cycle advantages. |
| Plant-Based Glucosamine Sourcing Transition | Fungal fermentation-derived chitosan eliminates shellfish allergen concerns and commodity volatility. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with veterinary practice owners, supplement brand product managers, and cold-chain logistics operators; and secondary validation through FDA Center for Veterinary Medicine guidance documents, National Animal Supplement Council quality seal program criteria, and state veterinary medical board dispensing regulations. Bottom-up segmentation modeling triangulated against top-down market sizing from customs fermentation equipment import data and veterinary clinic dispensing program adoption rates.
Forecast inputs considered pet humanization expenditure trajectories, precision fermentation cost compression curves, and regulatory substantiation timeline extensions across the analysis window. Segmentation dimensions modeled included product type, delivery form, target age, and distribution channel with geographic regulatory cluster overlays. CAGRs derived from logistic adoption curve fitting for microbiome testing penetration and linear projection for established joint-support categories.
Practitioners should monitor FDA Center for Veterinary Medicine draft guidance finalization and REACH-compliant enzymatic synthesis capacity buildout for early signals of competitive repositioning. Forecasts reflect assumptions about telehealth prescribing regulatory stability and cold-chain infrastructure investment continuity. Cross-checking against veterinary clinic dispensing program revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Pet Toys Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Cat Accessories Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Canned Wet Cat Food Market