
 Asia-Pacific Pet Treats Market | 2026-2036
Asia-Pacific Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pet Treats Market Insights
Subscription-based treat curation and replenishment services is restructuring how Asia-Pacific pet treat brands monetize customer relationships. Mars, Incorporated leverages its direct-to-consumer infrastructure to lock in recurring revenue across Southeast Asian metros. Nestle (Purina) anchors its regional position through veterinary channel partnerships that bundle treats with nutritional consultations. Unicharm Corp. competes on single-serve portion innovation tailored to Japanese apartment-dwelling pet owners.
Asia-Pacific pet treats comprise formulated edible products—typically containing proteins, carbohydrates, binders, and moisture content controlled below 20 percent for shelf-stable formats—manufactured through extrusion, baking, or freeze-drying processes to serve as reward, training aid, or dental hygiene supplement for companion animals. Chews and freeze-dried segments command premium shelf positioning as pet owners trade up to longer-lasting and minimally processed formats. Functional ingredient formulations, spanning probiotics and joint-support additives, capture expanding margin pools as veterinarians in Australia and South Korea incorporate treats into wellness protocols.
FSSAI in India enforces contaminant thresholds for imported pet treats, while Australia's Department of Agriculture mandates biosecurity clearance for animal-derived ingredients. Japan's Ministry of Agriculture, Forestry and Fisheries oversees quarantine and labeling standards that constrain raw material sourcing flexibility. Stakeholders must monitor how China's evolving pet food registration rules under the Ministry of Agriculture and Rural Affairs reshape market access for foreign brands seeking direct distribution.
Market Dynamics
Pet humanization in China's tier-one cities is compressing purchase cycles and elevating ingredient transparency expectations, forcing reformulation investments across the entire Asia-Pacific supply base.
Growth Catalysts
- Freeze-drying technology:Low-temperature dehydration preserves enzymatic activity in functional treats, unlocking veterinary channel adoption in Australia and South Korea.
- FSSAI contaminant thresholds:India's enforcement of strict residue limits for imported products is accelerating domestic manufacturing capacity buildout.
- Urban apartment living:Space constraints in Tokyo and Seoul are driving demand for single-serve portion formats and odor-controlled formulations.
Market Restraints
- Animal protein input volatility:Beef and poultry meal prices fluctuate with Australia's livestock export cycles and regional feed grain costs.
- Quarantine clearance bottlenecks:Japan's Ministry of Agriculture, Forestry and Fisheries inspection protocols delay raw material sourcing from non-approved origins.
- Functional treat substitution:Veterinarians in premium clinics increasingly prescribe therapeutic diets that incorporate treat-equivalent nutrition, reducing standalone treat volumes.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Rising middle-class pet ownership in Ho Chi Minh City and Jakarta offers first-mover positioning before regulatory frameworks mature.
- Direct-to-consumer subscription:Replenishment models bypass traditional veterinary and retail markups while capturing recurring revenue streams.
- Probiotic-joint health convergence:Dual-function formulations address aging pet demographics in Japan and Australia with single-SKU solutions.
Industry Challenges
- Freeze-drying technician scarcity:Specialized equipment operation and moisture-content calibration require skills concentrated in Japan and South Korea.
- Biosecurity certification timelines:Australia's Department of Agriculture clearance processes for novel protein sources extend product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pet Treats Market |
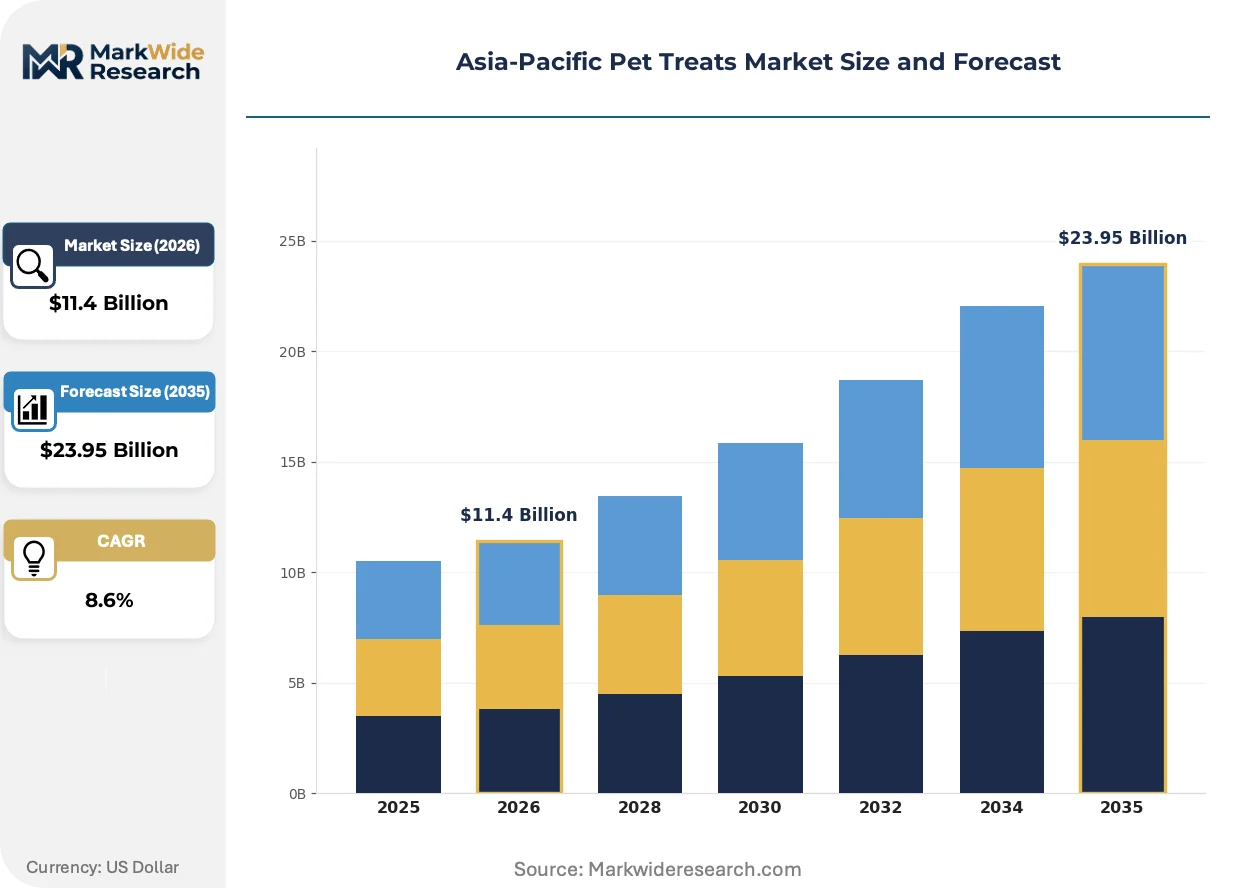
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biscuit, Chews, Jerky, Freeze-Dried End User: Dog Owners, Cat Owners, Retailers, Veterinarians Distribution Channel: Online Retail, Supermarkets, Pet Stores, Specialty Shops Ingredient: Meat-Based, Grain-Free, Organic, Functional |
| Companies Covered | Mars, Incorporated, Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.), General Mills Inc., ADM, EBOS Group Limited, Nestle (Purina), Unicharm Corp., Perfect Companion Group, IB Group (Drools Pet Food Pvt. Ltd.), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pet Treats Market Trends and Innovations
Formulation science and channel architecture are diverging sharply across the Asia-Pacific region, with premium freeze-dried segments pulling away from mass-market extruded products on both technology and pricing dimensions.
Lyophilization equipment is rewriting cost structures for functional treat production. Australian and Japanese manufacturers are retrofitting facilities with industrial-scale freeze-dryers to capture margin pools in veterinary-exclusive distribution. The technology is compressing batch processing times while preserving heat-sensitive probiotic cultures that extrusion destroys.
Australia's Department of Agriculture biosecurity clearance mandates are reshaping raw material sourcing flexibility. The regulations require documented chain-of-custody for all animal-derived inputs entering treat manufacturing. Freeze-dried meat segments face the steepest compliance costs, driving consolidation toward vertically integrated suppliers with captive protein supply.
Urban Chinese dog owners are abandoning bulk retail purchases for curated subscription boxes with personalized portion algorithms. Direct-to-consumer platforms in Shanghai and Beijing disintermediate traditional pet specialty stores. The shift is most visible among millennial households in tier-one cities, where convenience premiums outweigh per-unit cost comparisons.
Asia-Pacific Pet Treats Market Segmentation
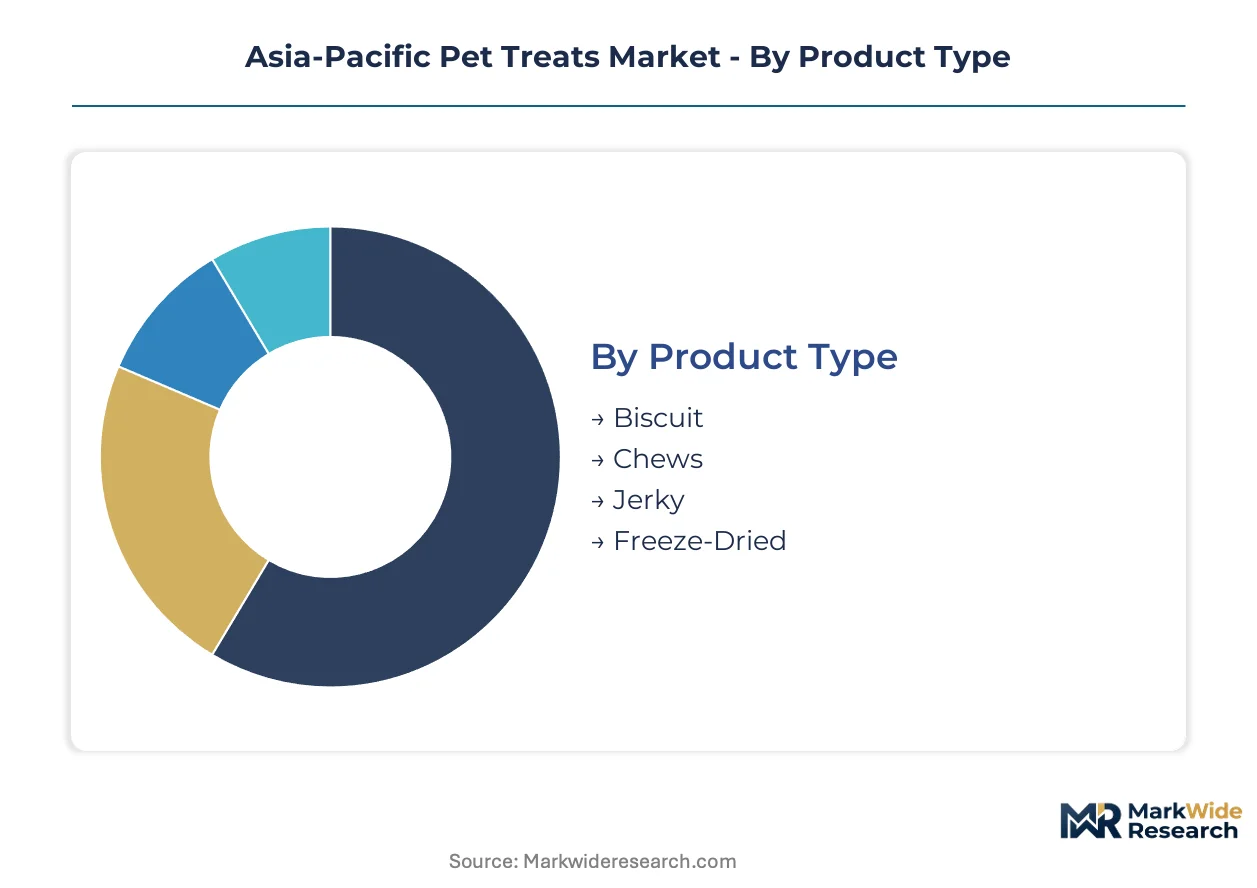
Asia-Pacific pet treat segmentation reveals divergent margin structures across processing technologies and channel access tiers. Manufacturers optimize formulation investments by matching product architecture to purchasing behavior in China's tier-one cities versus Southeast Asian emerging markets.
Product Type:
Freeze-dried formats command premium shelf positioning while extruded biscuits maintain volume dominance across mass retail channels.
- Freeze-Dried:Lyophilization preserves enzymatic activity in functional formulations, enabling veterinary channel placement in Australia and South Korea. Japanese apartment-dwelling pet owners absorb per-gram premiums for odor-controlled, single-serve convenience.
- Chews:Extended consumption duration supports dental hygiene positioning and higher per-unit pricing in China's subscription box channels. Australian biosecurity clearance requirements for animal-derived inputs constrain raw material sourcing flexibility for imported collagen and rawhide alternatives.
- Biscuit:Extrusion manufacturing achieves lowest unit costs for mass-market distribution through Indonesian and Vietnamese supermarkets.
- Jerky:Dehydrated meat strips face FSSAI contaminant threshold scrutiny in India, accelerating domestic manufacturing capacity investments.
Today's leader: Biscuit. Tomorrow's challenger: Freeze-Dried.
End User:
Channel control and purchasing authority fragment across companion animal species and professional intermediaries.
- Dog Owners:Urban Chinese millennials in Shanghai and Beijing drive subscription box adoption with personalized portion algorithms and direct-to-consumer replenishment models.
- Veterinarians:Australian and South Korean clinics incorporate functional treats into wellness protocols, prescribing probiotic and joint-support formulations as adjuncts to therapeutic diets.
- Cat Owners:Tokyo and Seoul apartment dwellers prioritize odor-controlled, single-serve formats for space-constrained households.
- Retailers:Indonesian and Vietnamese pet specialty stores bundle mass-market treats with grooming services to capture emerging middle-class pet adoption.
Channel power concentrates with Dog Owners. Professional gatekeepers in Veterinarians represent the steepest expansion trajectory.
Distribution Channel:
Direct access models are displacing traditional retail markups in premium segments while supermarkets defend volume share in price-sensitive markets.
- Online Retail:Mars and Nestle deploy direct-to-consumer infrastructure to lock in recurring revenue across Southeast Asian metros, bypassing veterinary and retail intermediaries.
- Pet Stores:Japanese specialty retailers emphasize functional ingredient transparency and freeze-dried premium positioning for aging pet demographics.
- Supermarkets:Mass-market biscuit and jerky formats dominate Indonesian and Vietnamese retail penetration before regulatory frameworks mature.
- Specialty Shops:Australian independent retailers curate biosecurity-certified freeze-dried imports for discerning pet owners in Sydney and Melbourne.
Scale advantage sits with Online Retail. Specialty Shops capture margin expansion.
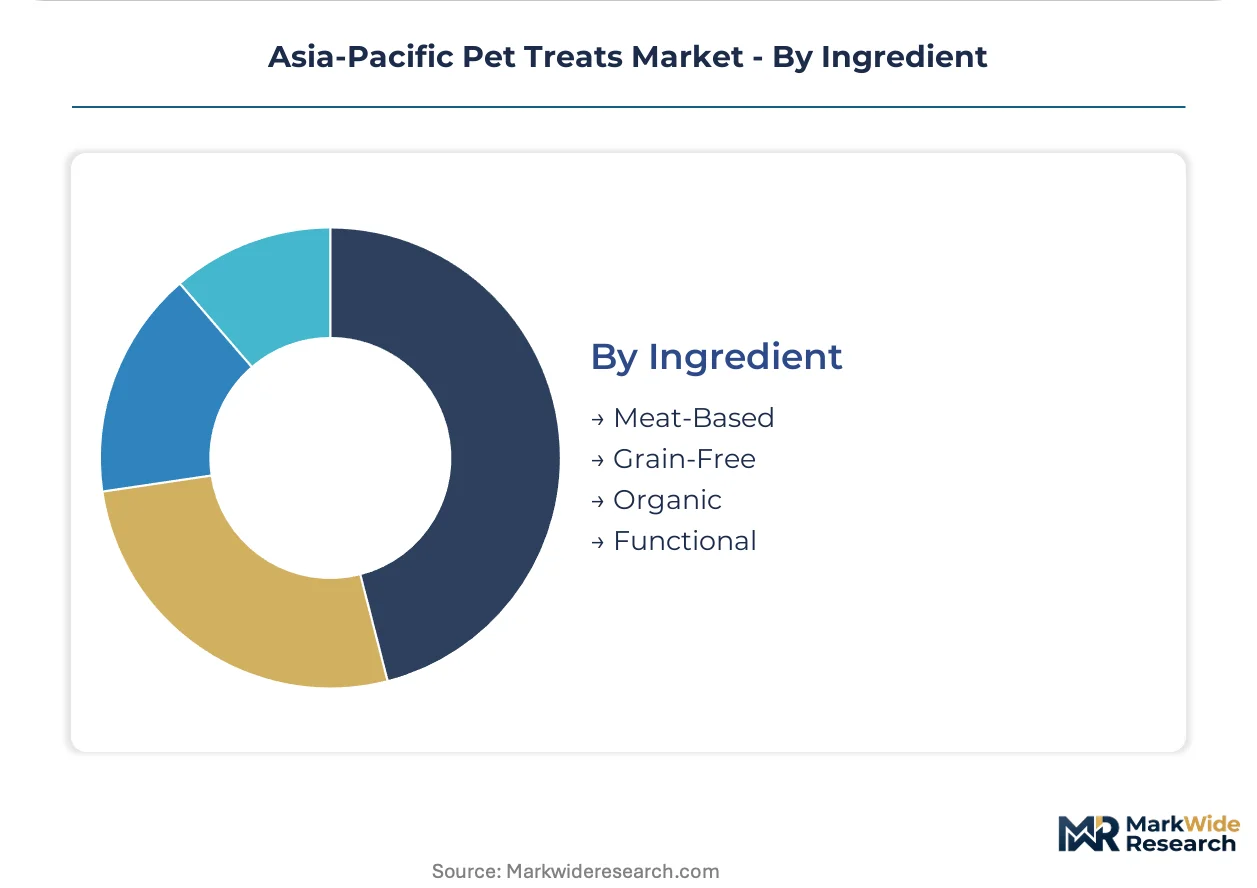
Ingredient:
Formulation claims differentiate across protein sourcing transparency and functional efficacy verification.
- Functional:Dual-function probiotic-joint health convergence addresses aging pet populations in Japan and Australia with single-SKU solutions validated for veterinary channel placement.
- Meat-Based:Beef and poultry meal inputs tie pricing to Australian livestock export cycles and regional feed grain cost volatility.
- Grain-Free:Labeling claims attract premium positioning in China's tier-one cities where ingredient transparency expectations compress purchase cycles.
- Organic:Certification requirements limit supply base concentration, constraining volume scalability across Southeast Asian emerging markets.
Margin capture favors Functional. Volume accessibility runs through Meat-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's subscription-driven premiumization contrasts sharply with India's mass-market volume expansion, illustrating how divergent income trajectories fragment regional opportunity across the Asia-Pacific pet treats landscape.
China
Shanghai and Beijing millennials compress purchase cycles through curated direct-to-consumer subscription boxes with algorithmic portion personalization. The Ministry of Agriculture and Rural Affairs tightens pet food registration rules, constraining foreign brand market access. Manufacturing investment concentrates in Zhejiang and Jiangsu provinces where freeze-drying capacity scales to serve veterinary channel demand.
Japan
Tokyo apartment dwellers absorb per-gram premiums for odor-controlled single-serve formats suited to space-constrained households. The Ministry of Agriculture, Forestry and Fisheries enforces quarantine inspection protocols that delay raw material sourcing from non-approved origins. Osaka-Kansai industrial clusters host specialized lyophilization equipment operators with concentrated technical expertise.
Australia
Sydney and Melbourne pet owners drive veterinary-exclusive distribution of functional probiotic and joint-support formulations. The Department of Agriculture mandates biosecurity clearance with documented chain-of-custody for all animal-derived inputs. Domestic manufacturers retrofit facilities with industrial-scale freeze-dryers to capture margin pools in premium segments.
South Korea
Seoul clinics incorporate functional treats into wellness protocols for aging companion animal populations. The Ministry of Food and Drug Safety (MFDS) oversees functional ingredient labeling standards that constrain formulation flexibility. Busan-Ulsan manufacturing corridors develop captive protein supply to reduce import dependency for freeze-dried meat inputs.
India
Mumbai and Delhi emerging middle-class households expand mass-market biscuit and jerky consumption through supermarket channels. The Food Safety and Standards Authority of India (FSSAI) enforces contaminant thresholds for imported products, accelerating domestic manufacturing capacity buildout. Gujarat and Maharashtra industrial zones attract investment in extrusion manufacturing for price-sensitive volume segments.
Asia-Pacific Pet Treats Market Competitive Landscape
Top-tier vendors anchor premium functional and subscription channels, while mid-scale regional specialists defend mass-market retail penetration through price-competitive extruded formats. The competitive structure stratifies across three archetypes: multinational conglomerates with veterinary channel partnerships, Asia-Pacific specialists in single-serve portion innovation, and domestic champions leveraging regulatory compliance advantages. Capacity expansion and direct-to-consumer infrastructure deployment constitute the dominant competitive moves reshaping regional positioning.
Within the multinational tier, Mars, Incorporated and Nestle (Purina) exemplify scale-driven channel control through recurring revenue infrastructure and veterinary bundling strategies. Unicharm Corp. occupies a specialist position representing Japanese precision in portion-format innovation. Among domestic champions, IB Group (Drools Pet Food Pvt. Ltd.) anchors Indian manufacturing expansion responding to FSSAI enforcement patterns.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.) |
| General Mills Inc. |
| ADM |
| EBOS Group Limited |
| Nestle (Purina) |
| Unicharm Corp. |
| Perfect Companion Group |
| IB Group (Drools Pet Food Pvt. Ltd.) |
| Others |
Pricing and Supply Chain Analysis
Australia's biosecurity clearance mandates gate qualified supply for freeze-dried premium tiers while compressing margin pools for non-compliant imports. Japan's quarantine inspection protocols further constrain raw material sourcing flexibility, elevating per-unit costs for veterinary-channel functional formulations.
Pricing Analysis
Capacity additions in China's Zhejiang and Jiangsu provinces are reshaping price floors for lyophilization equipment operation. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-exclusive functional treats from mass-market extruded biscuits and entry-level jerky formats. Cost compression in the biscuit segment is intensifying because Indonesian and Vietnamese supermarket buyers prioritize volume scale over ingredient transparency. China's tier-one city millennials exhibit least price sensitivity for subscription-box curation, while Indian mass-market consumers through Mumbai and Delhi supermarkets remain most responsive to per-unit cost comparisons.
Supply Chain Analysis
India's domestic-content mandates under FSSAI enforcement are reshaping sourcing patterns for imported meat-based inputs. Protein supply concentrates in Australia, China, and South Korea for freeze-dried manufacturing, with beef and poultry meal sourcing anchored in Australian livestock export cycles. Raw material procurement draws from regional feed grain markets, collagen derivatives, and probiotic culture suppliers. Single-source vulnerability runs through Japan's approved-origin quarantine lists for non-approved protein inputs. Distribution runs through direct-to-consumer platforms in Chinese tier-one cities, veterinary-exclusive channels in Australia and South Korea, and supermarket retail in Southeast Asian emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Urban Chinese millennials have shifted demand toward algorithmically personalized subscription specifications that prioritize ingredient transparency over per-unit economics.
For Market Incumbents: Hedge against therapeutic diet substitution by deepening captive protein supply through backward integration into Australian biosecurity-certified rendering facilities. Lock in veterinary channel control through probiotic-joint health formulation bundling that resists standalone treat displacement.
For New Entrants and Emerging Players: Vietnam's emerging middle-class pet owners in Ho Chi Minh City represent the most penetrable buyer archetype before regulatory frameworks mature. Capture first-mover positioning through mass-market biscuit distribution bundled with grooming services, then ladder toward freeze-dried premium tiers as income trajectories rise.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale domestic champions with FSSAI compliance infrastructure because India's enforcement patterns create acquisition currency for compliant manufacturers. Monitor freeze-drying technician scarcity in Japan and South Korea as the inflection signal for margin compression in premium functional segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Captures margin pools in Australia's veterinary-exclusive distribution channels. |
| Direct-to-Consumer Platform Launch | Locks recurring revenue from Shanghai and Beijing millennial subscribers. |
| Biosecurity Certification Investment | Secures Australia's Department of Agriculture clearance for novel protein sourcing. |
| Functional Ingredient R&D Partnership | Develops dual-function probiotic-joint health formulations for aging pet demographics. |
| Southeast Asian Distribution Expansion | Establishes supermarket presence in Jakarta before regulatory frameworks mature. |
Research Methodology
Bottom-up pet owner purchasing modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with veterinary clinic procurement managers, pet specialty retail category buyers, freeze-drying equipment operators, and FSSAI regulatory compliance officers combined with secondary validation from customs trade records, Ministry of Agriculture registration filings, and Nielsen retail audit data. The approach triangulates demand-side behavioral signals against supply-side investment patterns.
Historical trendline analysis of segment growth trajectories across the projection horizon informs the forecast framework. Segmentation dimensions modeled include processing technology, distribution channel tier, companion animal species, and functional ingredient claim density. CAGRs derive from slope-adjusted extrapolation of observed adoption curves, with specific inputs from lyophilization equipment deployment schedules and veterinary protocol integration rates for wellness adjuncts.
Underlying measurement precision varies by segment; freeze-dried functional formats carry tighter precision than mass-market extruded biscuits due to concentrated manufacturer disclosure. Forecasts reflect documented assumptions about regulatory enforcement intensity and protein input cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Brush Market
Pet Care Products
Pet Beds Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
North America Pet Food Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Pet Food Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Pet Supplement Market
Pet Care Products
United States Organic and Natural Pet Food Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Vegan Dog Food Market