
 Smart Pet Leash Market | 2026-2036
Smart Pet Leash Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pet Leash Market Insights
Bluetooth Low Energy integration with smartphone ecosystems is reshaping how smart pet leashes communicate location and behavioral data to owners. Garmin Ltd. leverages its GPS heritage to anchor premium positioning in geofencing-capable units. Whistle Labs competes through subscription-backed health analytics that extend beyond simple tracking. Tractive differentiates via aggressive channel control across European online retail platforms.
A smart pet leash is a tethering device incorporating embedded sensors, wireless connectivity modules, and rechargeable power systems to transmit real-time location, activity, or environmental data to paired mobile applications. These units typically integrate GPS receivers, accelerometers, and lithium-polymer cells rated for 4-7 days of operation, serving commercial purposes ranging from lost-pet recovery to behavioral training oversight. GPS leash variants capture the deepest margin pools due to hardware complexity and recurring subscription revenue models. Smart tracking features lead unit economics across the feature dimension, while LED light integration shows fastest uptake among urban evening walkers. Pet care services represent the most concentrated end-user growth vector as commercial dog-walking operations standardize on fleet-management visibility.
FCC certification requirements govern wireless transmission protocols for devices sold in the United States, while CE marking under EU radio equipment directives shapes market access across European distribution channels. Japan's Ministry of Economy, Trade and Industry enforces radio law compliance that filters non-conforming imports from direct-to-consumer channels. Stakeholders must monitor evolving battery transport regulations and emerging right-to-repair mandates that could alter hardware serviceability requirements and subscription attachment rates.
Market Dynamics
Bluetooth Low Energy integration with smartphone ecosystems is compressing development cycles and forcing hardware-software co-design investments across the supplier base. This connectivity shift is redefining how location data monetizes through recurring subscription architectures rather than one-time hardware sales.
Growth Catalysts
- Urban Pet Ownership Concentration:Millennial households in dense metropolitan corridors across Germany, the United Kingdom, and Japan are standardizing on connected pet accessories. Premium corridor density accelerates word-of-mouth adoption velocity.
- FCC Certification Pathway:Streamlined wireless equipment authorization in the United States reduces time-to-market for GPS-enabled units. Hardware vendors leverage this regulatory clarity to prioritize North American launch sequencing.
- Pet Care Service Fleet Standardization:Commercial dog-walking operations are mandating real-time visibility tools for liability and route optimization. Fleet procurement concentrates demand into multi-unit contracts with integrated software dashboards.
Market Restraints
- Lithium-Polymer Cell Supply Concentration:Battery cell production clusters in East Asian manufacturing hubs expose hardware vendors to shipping volatility and raw material price swings. Extended lead times constrain inventory flexibility for seasonal demand spikes.
- Radio Law Compliance Friction:Japan's Ministry of Economy, Trade and Industry enforces strict radio equipment certification that filters non-conforming imports from direct-to-consumer channels. Market entry requires localized testing partnerships and distributor relationships.
- Subscription Fatigue Threshold:Consumer resistance to accumulating monthly fees for single-function hardware limits attach rates for premium GPS tracking services. Churn pressure compresses lifetime value calculations for recurring revenue models.
Strategic Opportunities
- Right-to-Repair Mandate Alignment:Emerging European Union directives on hardware serviceability create openings for modular leash designs with swappable battery and sensor components. Vendors that front-run repair-friendly architectures capture sustainability-conscious urban buyers.
- Behavioral Training Application Expansion:Accelerometer data integration with veterinary behavioral protocols opens clinical endorsement channels. Partnerships with certified animal behaviorists differentiate hardware beyond basic location tracking.
- LED Safety Feature Bundling:Urban evening walking patterns in Japanese and German cities drive fastest uptake for illumination-integrated units. Hardware vendors can capture incremental margin through lighting module tiering without GPS complexity.
Industry Challenges
- RF Engineering Talent Scarcity:Bluetooth Low Energy optimization for extended battery life requires specialized firmware expertise that concentrates in consumer electronics hubs. Recruitment competition with smartphone and wearable manufacturers inflates compensation costs.
- CE Marking Timeline Variability:EU radio equipment directive compliance testing durations fluctuate across notified bodies, creating launch date uncertainty. Vendors must maintain parallel certification tracks to hedge approval delays.
- Mobile OS Fragmentation:iOS and Android ecosystem updates force continuous application maintenance and compatibility testing. Development resource allocation splits between feature innovation and platform sustainment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pet Leash Market |
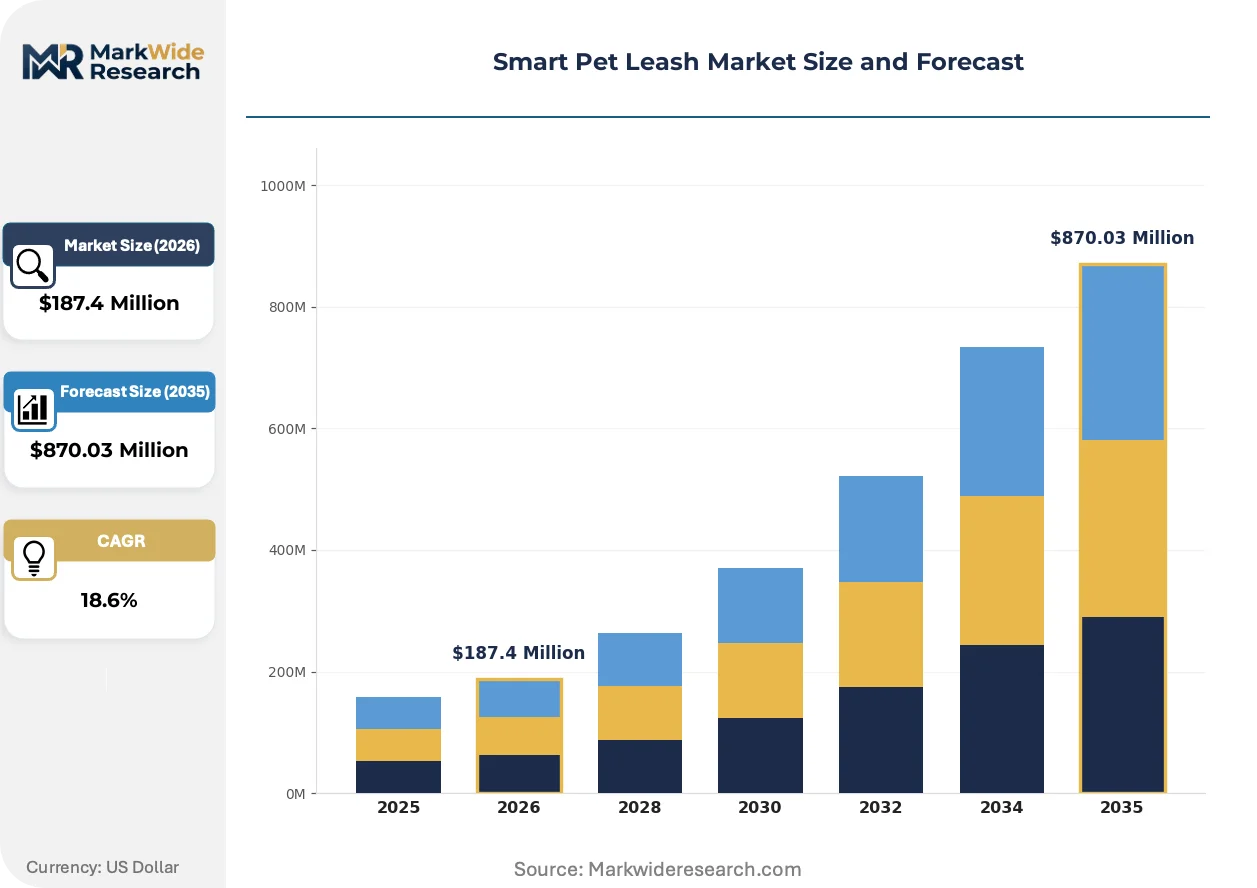
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Leash, Retractable Leash, Training Leash, GPS Leash Feature: Smart Tracking, LED Light, Shock Absorption, Voice Control End User: Pet Owners, Dog Walkers, Trainers, Pet Care Services Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | Whistle Labs, FitBark, Garmin Ltd., Link AKC, PetSafe, Tractive, PetPace, Wagz Inc., SpotOn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pet Leash Market Trends and Innovations
Embedded sensor miniaturization and cloud-native mobile architectures are converging to transform how pet owners interact with location and behavioral data. Hardware vendors are racing to own the software layer that mediates this data exchange.
Ultra-wideband positioning chips are digitizing spatial accuracy for indoor pet tracking where GPS signals attenuate. High-rise apartment dwellers in Tokyo and London are adopting these units for elevator lobby and hallway monitoring. The technology is digitizing competitive positioning by enabling centimeter-level proximity alerts that Bluetooth Low Energy cannot match.
The EU's Corporate Sustainability Reporting Directive is mandating supply chain carbon disclosure for electronics importers. Hardware vendors must now document battery cell provenance and assembly facility energy sources. GPS leash manufacturers with Asian contract manufacturing footprints are accelerating supplier audits to maintain European retail channel access.
Direct-to-consumer subscription bundling is displacing retail box sales as the dominant commercial model. Urban millennial buyers prefer integrated hardware-plus-service pricing over upfront capital outlays. This pattern concentrates in United States and Western European markets where credit-based consumption norms support recurring billing relationships.
Smart Pet Leash Market Segmentation
Smart pet leash segmentation reveals how hardware specifications, connectivity features, and procurement channels fragment demand across distinct buyer workflows. Manufacturers optimize SKU portfolios by matching technical configurations to the operational requirements of individual owners versus commercial fleet operators.
Product Type:
Use-case spectrum spans casual urban walking to professional training environments, with each leash architecture addressing specific control, range, and data capture needs.
- GPS Leash:Embedded GPS receivers and cellular modems transmit real-time location data to smartphone applications. Commercial dog-walking operations in Germany and the United Kingdom standardize on these units for liability documentation and route optimization.
- Automatic Leash:Motorized tension management systems adjust slack based on pet movement patterns detected via accelerometer. Urban millennial owners in Japanese metropolitan corridors favor these for hands-free navigation of crowded sidewalks.
- Retractable Leash:Mechanical cord extension mechanisms with optional brake locks provide variable range control. Pet stores in the United States stock these as entry-level smart leash introductions.
- Training Leash:Integrated vibration or tone modules sync with mobile application command sequences. Certified animal behaviorists in France recommend these for reactive dog rehabilitation protocols.
Established volume favors Retractable Leash; emerging adoption favors GPS Leash.
Feature:
Cost tier stratification separates premium subscription-backed capabilities from single-purchase hardware enhancements.
- Smart Tracking:Cloud-connected location history and geofencing alerts generate recurring subscription revenue. FCC-certified units dominate United States direct-to-consumer channels due to streamlined equipment authorization pathways.
- LED Light:Programmable illumination arrays improve visibility during evening walks in high-rise districts. Tokyo and London apartment dwellers drive steepest expansion trajectory for this safety module.
- Shock Absorption:Elastomer dampening systems reduce handler strain during sudden pet lunges. Veterinary physiotherapists in Germany endorse these for owners managing large-breed dogs.
- Voice Control:Hands-free command integration with smartphone virtual assistants enables leash operation during multitasking. Early adoption concentrates among tech-forward owners in San Francisco and Seattle.
Smart Tracking commands premium pricing; LED Light captures fastest volume growth.
End User:
Customer type determines whether procurement emphasizes individual convenience or fleet-scale operational visibility.
- Pet Care Services:Multi-unit contracts require centralized dashboard oversight of walker locations and pet status. These commercial accounts in the United Kingdom negotiate enterprise pricing with integrated insurance documentation.
- Pet Owners:Individual purchasers prioritize smartphone ecosystem compatibility and aesthetic design. Urban corridors across Germany show highest per-capita adoption density.
- Dog Walkers:Independent contractors seek lightweight hardware with all-day battery endurance. Japanese metropolitan markets support specialized retail channels for this professional segment.
- Trainers:Behavioral specialists demand precise stimulus timing and data logging for client progress reports. Certification bodies in France influence hardware selection through endorsed equipment lists.
Pet Owners generate baseline volume; Pet Care Services drive margin expansion.
Distribution Channel:
Supply concentration varies between platform-controlled digital commerce and relationship-dependent physical retail.
- Online Retail:Direct-to-consumer platforms enable subscription bundling and firmware update delivery. European vendors leverage these channels to bypass CE marking delays at physical import points.
- Pet Stores:Staff-assisted demonstrations clarify technical differentiation for first-time buyers. Independent retailers in Japan maintain inventory depth for immediate replacement of failed units.
- Supermarkets:Mass-market placement reaches occasional purchasers through impulse adjacency to pet food categories. United States big-box chains experiment with locked-display security for higher-priced GPS models.
- Specialty Shops:Curated assortments serve breed-specific communities and competitive show participants. German equestrian and pet supply hybrids stock premium training leash configurations.
Online Retail is displacing physical channels for GPS-enabled units; Pet Stores retain dominance for entry-level retractable systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial households in dense metropolitan corridors concentrate demand across three continents, with commercial pet care services amplifying procurement volumes in premium city clusters. Regulatory clarity in wireless equipment certification and fleet-standardization mandates shape go-to-market sequencing.
United States
Commercial dog-walking operations in New York and Los Angeles mandate real-time visibility tools for liability documentation. FCC certification pathways streamline equipment authorization for GPS-enabled units entering direct-to-consumer channels. San Francisco and Seattle anchor early voice-control feature adoption among tech-forward owners.
Germany
Veterinary physiotherapists in Munich and Hamburg endorse shock-absorption modules for large-breed management. CE marking under EU radio equipment directives governs market access across European distribution channels. The Rhine-Ruhr metropolitan corridor concentrates premium corridor density for word-of-mouth adoption velocity.
United Kingdom
Pet care services in London negotiate enterprise pricing with integrated insurance documentation and centralized dashboard oversight. The EU's Corporate Sustainability Reporting Directive mandates supply chain carbon disclosure for electronics importers. Birmingham and Manchester support specialized retail channels for trainer-endorsed equipment configurations.
Japan
Automatic leash motorized tension systems attract urban millennial owners navigating crowded Tokyo and Osaka sidewalks. METI enforces strict radio law compliance that filters non-conforming imports from direct-to-consumer channels. Yokohama and Nagoya apartment dwellers drive steepest LED safety module expansion for evening walking patterns.
Smart Pet Leash Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where subscription-backed analytics vendors face off against hardware-centric manufacturers. The vendor base splits between GPS heritage specialists leveraging geofencing capabilities and connectivity-native entrants prioritizing smartphone ecosystem integration. Two strategic archetypes dominate: integrated platform owners capturing recurring revenue through service bundling, and component-optimized fabricators competing on hardware margin. Competitive moves concentrate on firmware update delivery infrastructure and fleet-management software partnerships.
Within the integrated platform tier, Whistle Labs and Garmin Ltd. exemplify contrasting heritage paths—one from subscription-backed health analytics, the other from GPS navigation systems—while Tractive anchors European channel control through aggressive online retail positioning. These three occupy distinct competitive spaces without direct product overlap, allowing parallel expansion across geographies and buyer segments.
| Leading Market Players |
|---|
| Whistle Labs |
| FitBark |
| Garmin Ltd. |
| Link AKC |
| PetSafe |
| Tractive |
| PetPace |
| Wagz Inc. |
| SpotOn |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer cell supply concentration in East Asian manufacturing hubs exposes hardware vendors to shipping volatility and raw material price swings, compressing margin spreads between GPS-enabled premium tiers and entry-level retractable units while forcing inventory positioning decisions ahead of seasonal demand spikes.
Pricing Analysis
Cost-plus contracts with lithium-polymer cell suppliers indexed to cobalt and lithium carbonate spot markets dominate component procurement. Three-tier pricing structure across premium, standard, and economy levels separates GPS-enabled subscription bundles from LED-integrated mid-tier units and basic retractable systems. Pricing pressure stems from subscription fatigue thresholds limiting attach rates for recurring revenue models. Pet care services demonstrate lowest price sensitivity due to fleet-scale procurement and insurance documentation requirements, while individual urban millennial owners exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and Chinese EMS providers holding capacity for Bluetooth Low Energy module integration and GPS receiver assembly. Battery cell production draws from South Korean and Japanese suppliers, while accelerometer sensors source from German and Japanese component specialists. Single-source vulnerability concentrates in lithium-polymer cell supply channels. Distribution runs through direct-to-consumer online platforms for GPS-enabled units and pet store networks for entry-level retractable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-native pet tracking applications threaten to displace dedicated hardware as Bluetooth Low Energy integration deepens, forcing incumbents to defend attach rates through service bundling and firmware differentiation.
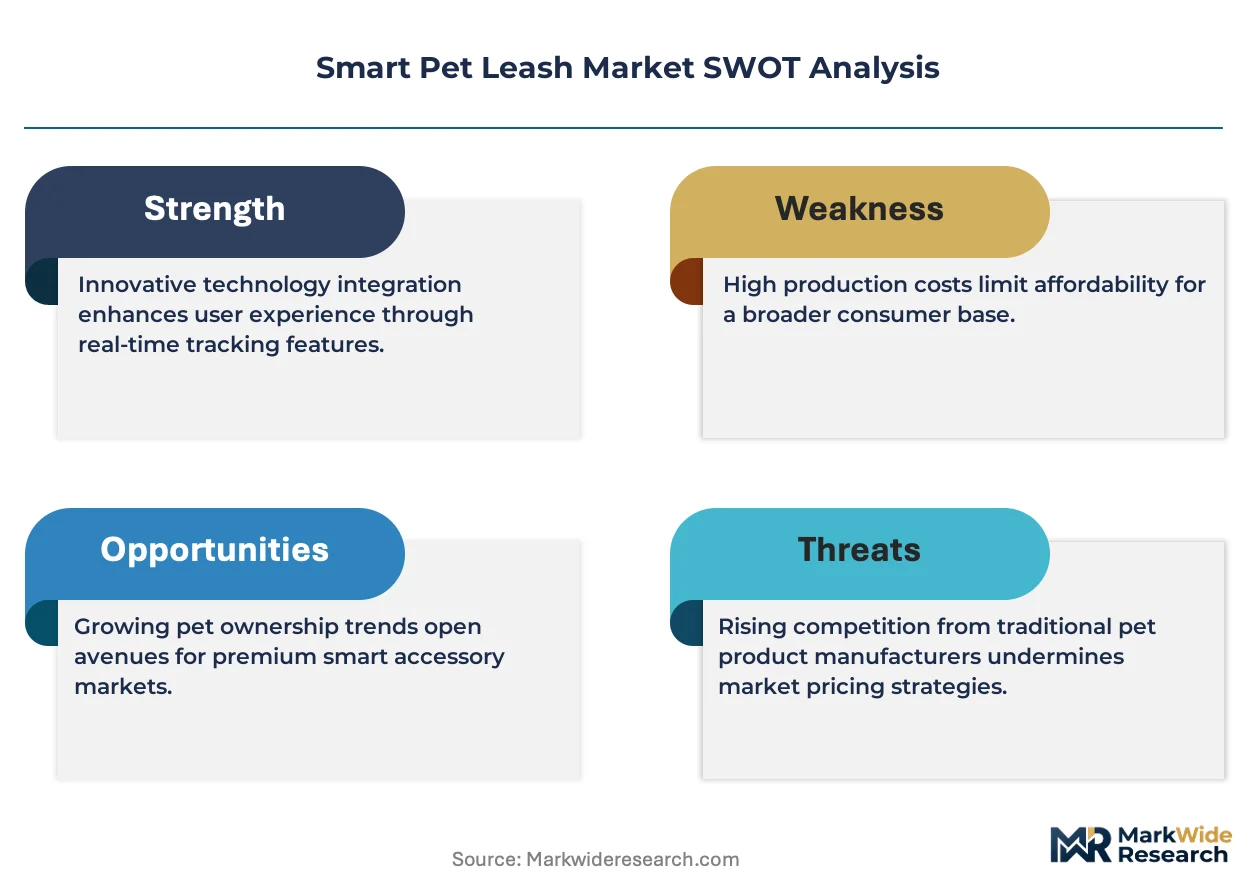
For Market Incumbents: Insulate subscription revenue streams by accelerating backward integration into battery cell supply channels and securing exclusive veterinary endorsement partnerships. Counter smartphone-native tracking substitutes through geofencing algorithm patents and fleet-management software lock-in with commercial dog-walking operations. For New Entrants and Emerging Players: Mid-market automatic leash segments in Japanese metropolitan corridors represent the most penetrable entry point, with motorized tension systems capturing urban millennial demand for hands-free sidewalk navigation. LED safety module tiering for evening walking patterns offers lowest technical barrier to hardware differentiation. Pursue direct-to-consumer launch with integrated subscription pricing to bypass retail margin extraction. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors integrated hardware-software vendors with established recurring revenue architectures. Five-to-ten-year viability hinges on subscription attach rate sustainability and right-to-repair mandate compliance positioning. Target acquisition archetype: European online retail channel controllers with METI certification pathways. Watch for FCC equipment authorization timeline compression as inflection signal for North American expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Bundling Migration | Direct-to-consumer pricing displaces retail box economics in United States and Western European urban corridors. |
| Right-to-Repair Alignment | Modular battery and sensor designs capture sustainability-conscious buyers under emerging EU directives. |
| Fleet-Management Partnership | Commercial dog-walking operations in London and Los Angeles mandate centralized dashboard visibility tools. |
| Ultra-Wideband Integration | Centimeter-level indoor positioning chips differentiate high-rise apartment offerings in Tokyo and London. |
| Veterinary Endorsement Channel | Certified animal behaviorists in France influence hardware selection through endorsed equipment protocols. |
Research Methodology
The analysis maps GPS-enabled, automatic, retractable, and training leash sub-sectors, each validated through product managers at connectivity-native entrants, procurement leads at commercial pet care services, firmware engineers at GPS heritage specialists, and category buyers at European online retail platforms. Primary interview insights triangulate against FCC equipment authorization databases, METI radio law compliance filings, EU CE marking directive records, and lithium-polymer cell import customs data. Bottom-up SKU-level volume builds reconcile with top-down pet ownership demographic projections across the analysis window.
Assumption sets held wireless protocol standards and regulatory certification timelines fixed while varying urban millennial household formation rates and commercial pet care service fleet expansion trajectories. The modeling framework segments by product architecture, connectivity feature tier, end-user procurement scale, and distribution channel control. CAGRs derive from logistic adoption curve fitting against smartphone ecosystem penetration benchmarks and subscription service attach rate elasticities observed in adjacent connected wearable categories.
Practitioners should monitor lithium carbonate spot price volatility, METI radio law enforcement intensity, and right-to-repair directive implementation pace for early signals of margin compression or channel access restriction. Quarterly review of FCC equipment authorization queue depth and European online retail platform search ranking algorithms is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
South America Pet Treats Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Cat Diets Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Netherlands Pet Food Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Aquarium Market
Pet Care Products
Raw Pet Food Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
DTC Pet Food Market