
 France Data Center Rack Market | 2026-2036
France Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Rack Market Insights
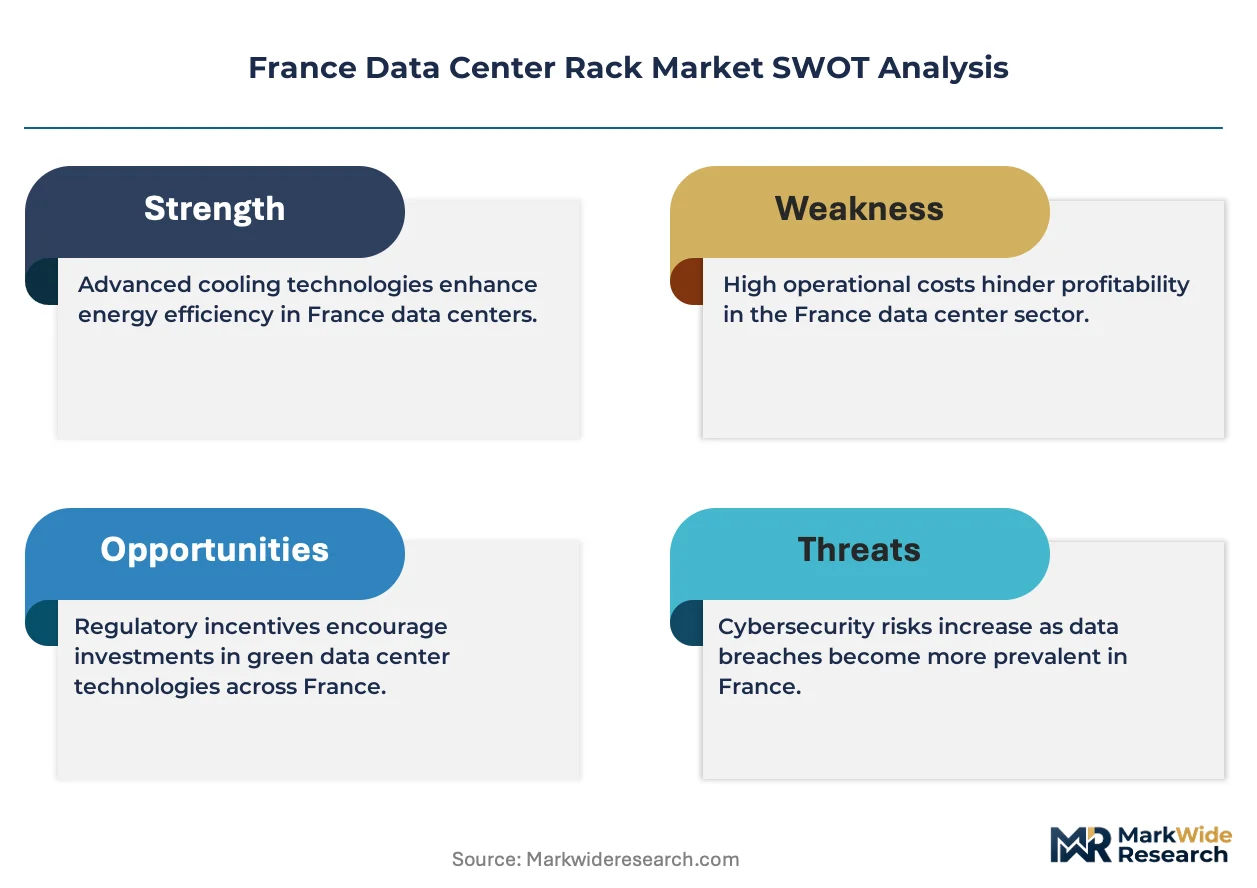
High-density liquid cooling integration is rewriting rack architecture requirements across French facilities. Schneider Electric SE leverages its Grenoble engineering base to sustain thermal management leadership in enclosures rated beyond 30 kW per rack. Vertiv Group Corp. anchors its position through precision cooling systems that compete directly with air-cooled legacy designs. Legrand S.A. differentiates via power distribution integration, controlling cable management and busway connectivity within the same frame envelope.
A data center rack is a standardized metal frame—typically 19 inches wide, with rack units (U) measured in 1.75-inch vertical increments—engineered to mount servers, switches, and power equipment in organized, serviceable configurations. Steel construction dominates French procurement, though aluminum variants gain traction where weight constraints affect raised-floor loading or seismic bracing specifications. Enclosed rack formats with integrated containment capture margin pools as RE2020 compliance tightens airflow management requirements. Modular rack segments expand fastest among cloud providers seeking factory-integrated, hot-swappable infrastructure for rapid Paris and Marseille deployments.
France's RE2020 regulation, enforced by the country's environmental and building agencies, mandates energy performance disclosures that push buyers toward thermally efficient rack configurations. CE marking and EU RoHS compliance filter import access, favoring European manufacturers with established conformity assessment pathways. Stakeholders must monitor how the EU AI Act's infrastructure disclosure rules reshape procurement specifications for racks housing GPU-intensive training clusters.
Market Dynamics
High-density liquid cooling integration is compressing rack architecture cycles across French facilities, forcing enclosure suppliers to redesign thermal pathways before legacy air-cooled inventories fully depreciate. This technology shift intersects with RE2020 energy mandates to accelerate replacement demand.
Growth Catalysts
- Hyperscale cloud expansion:Providers are deploying factory-integrated modular racks across the Paris-Saclay corridor and Marseille landing zones, creating concentrated procurement pull for hot-swappable infrastructure.
- RE2020 environmental mandates:France's building energy performance regulations compel operators to disclose thermal efficiency metrics, favoring enclosed rack formats with integrated containment and precision airflow management.
- AI training cluster buildouts:GPU-intensive workloads are driving demand for racks rated beyond 30 kW per enclosure, requiring advanced busway power distribution and liquid cooling compatibility.
Market Restraints
- Steel input cost volatility:Raw material price swings for cold-rolled steel directly compress margin pools on standard rack enclosures, pressuring mid-tier fabricators without long-term supply agreements.
- CE marking compliance friction:EU conformity assessment pathways filter import access, creating timeline delays for non-European manufacturers seeking market entry.
- Seismic bracing specifications:Raised-floor loading constraints in older Île-de-France facilities limit aluminum rack adoption despite weight advantages, preserving steel dominance.
Strategic Opportunities
- Secondary French regions:Lyon and Lille data center corridors remain underpenetrated relative to Paris, offering first-mover positioning for modular rack suppliers with localized assembly capacity.
- EU AI Act infrastructure disclosures:Emerging transparency requirements for training cluster energy consumption create specification pull for racks with embedded metering and thermal monitoring.
- Busway-cooling convergence:Integration of power distribution and liquid cooling manifolds within single frame envelopes opens premium positioning beyond commodity enclosure sales.
Industry Challenges
- Thermal engineering talent scarcity:Specialized skills in computational fluid dynamics and two-phase cooling design remain concentrated among Grenoble and Toulouse engineering clusters, constraining supplier scaling.
- Legacy air-cooled integration:Operators face complex retrofit pathways when mixing liquid-cooled high-density racks with existing aisle containment architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Rack Market |
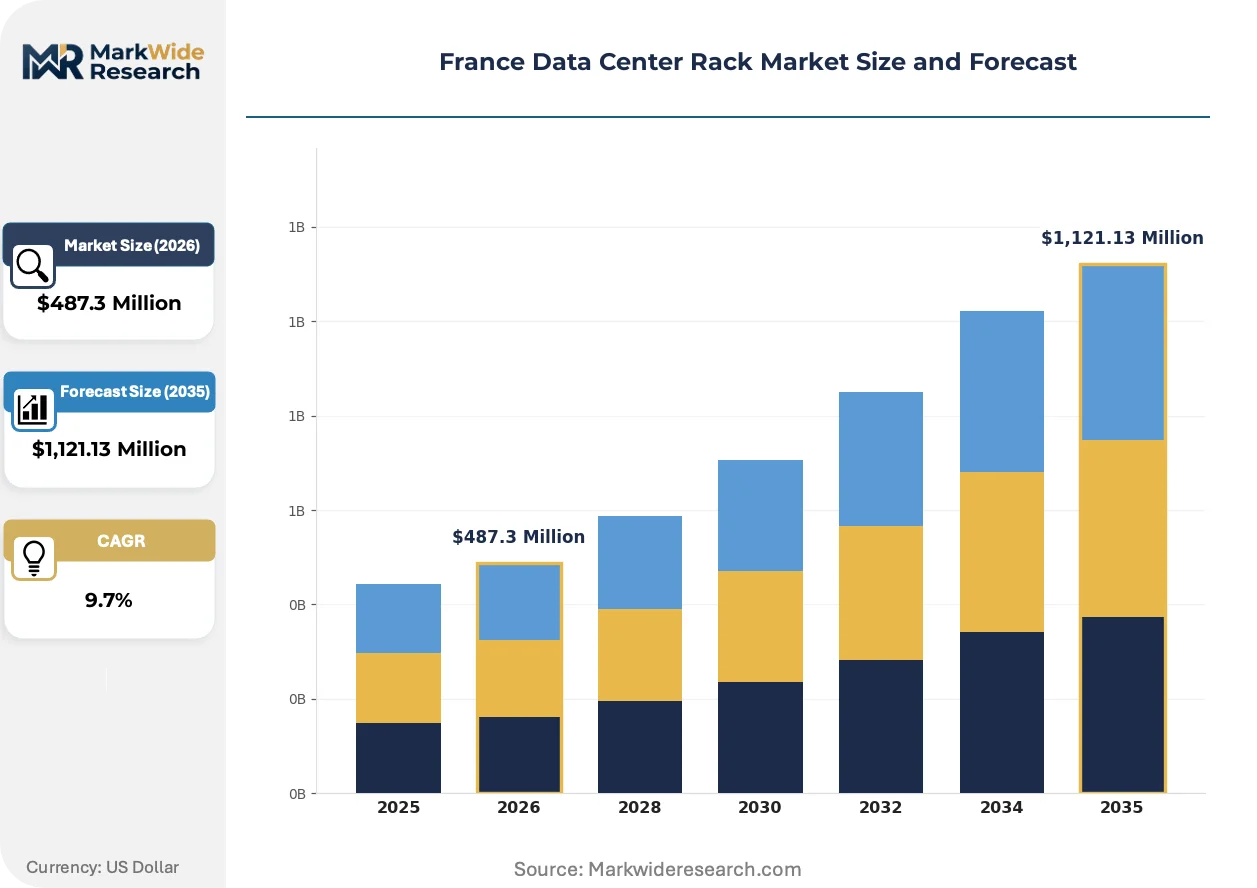
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed, Modular, Custom Installation Type: Wall-Mount, Free-Standing, Rack-Mounted, Integrated Material: Steel, Aluminum, Plastic, Composite End User: Telecommunications, Cloud Providers, Enterprises, Research Institutions |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Legrand S.A., Eaton Corporation, Rittal GmbH and Co. KG, Dell Inc., Hewlett Packard Enterprise, nVent Electric PLC, Minkels B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Rack Market Trends and Innovations
Liquid cooling technologies are compressing traditional rack design cycles, forcing simultaneous evolution of power distribution, thermal management, and structural load specifications. This convergence is redrawing competitive boundaries among enclosure specialists.
Direct-to-chip liquid cooling is collapsing the separation between server-level and facility-level thermal management. Hyperscale operators in the Paris region are adopting factory-sealed coolant distribution units integrated at the rack base. This architecture is collapsing the historical three-tier supply chain—server vendor, rack integrator, cooling specialist—into single-source procurement relationships.
France's RE2020 regulation, enforced by environmental and building agencies, mandates granular energy performance disclosures for data center infrastructure. Operators must now document thermal efficiency at the rack level, accelerating replacement of open-frame designs. Colocation providers in Île-de-France are responding by specifying enclosed containment racks with integrated airflow monitoring to satisfy audit requirements.
Specification authority is migrating from general contractors to cloud operators' engineering teams, compressing traditional distribution channels. Direct manufacturer relationships now dominate hyperscale procurement, while value-added resellers retain position only in mid-market enterprise segments. This pattern is most visible in Marseille, where submarine cable landing zones attract operator-led infrastructure builds bypassing conventional specification chains.
France Data Center Rack Market Segmentation
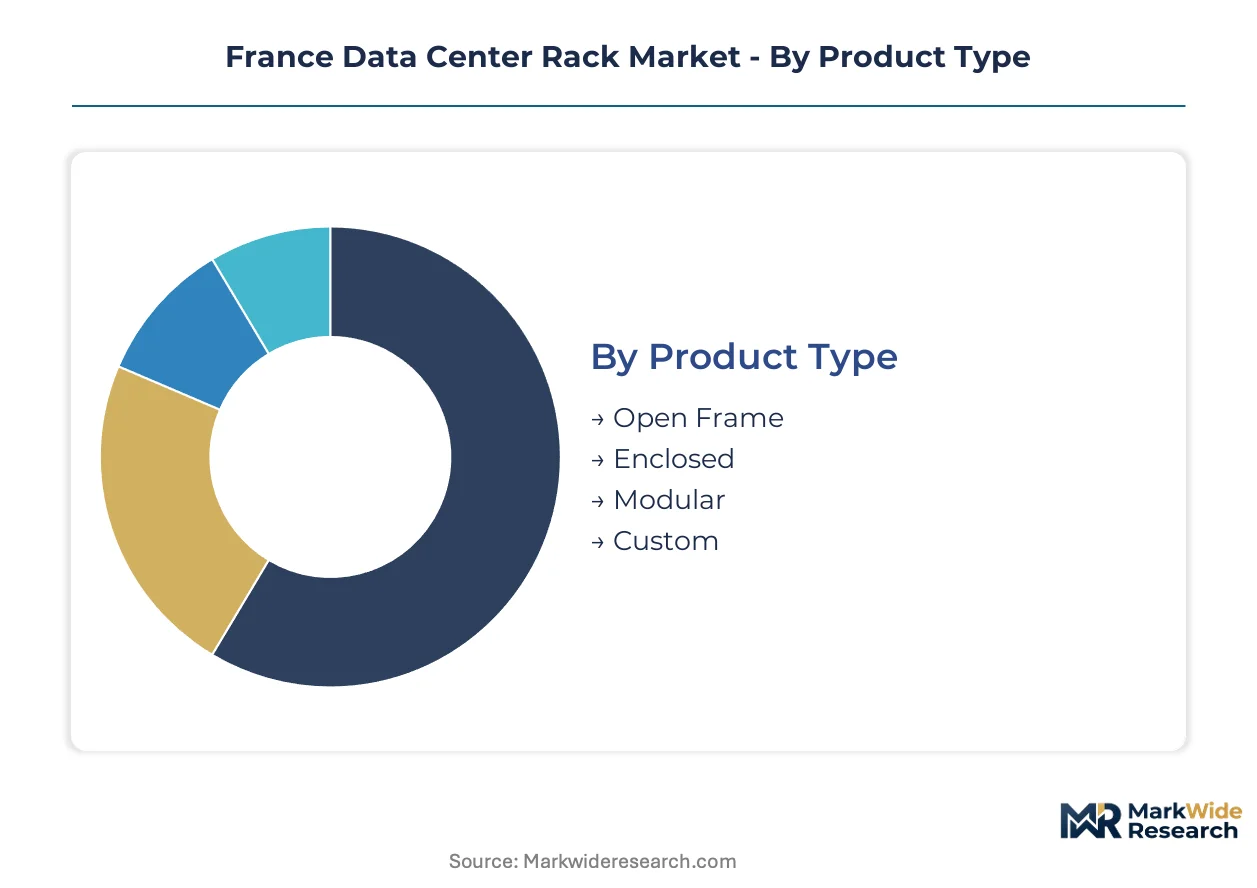
Data center rack procurement in France fragments across four distinct category axes, each commanding different specification authority and replacement cadences. Procurement cycles vary from months for modular cloud deployments to years for enterprise steel infrastructure. Understanding these segment dynamics clarifies where vendor relationships concentrate versus where price competition intensifies.
Product Type:
Replacement velocity diverges sharply across rack formats, with modular units turning over fastest as hyperscale operators refresh factory-integrated infrastructure on compressed timelines.
- Enclosed:Factory-sealed containment systems with integrated airflow management dominate RE2020-compliant builds across the Île-de-France corridor. Paris-Saclay colocation providers specify these units to satisfy thermal efficiency audit requirements mandated by France's building energy agencies.
- Modular:Hot-swappable, factory-integrated segments support rapid deployment cycles for cloud providers establishing Paris and Marseille landing zones. These units compress procurement-to-commissioning timelines through pre-tested power and cooling integration.
- Open Frame:Standard 19-inch steel frames without side panels persist in legacy enterprise facilities where RE2020 retrofit pressure remains lower.
- Custom:Bespoke configurations serve research institutions with non-standard equipment dimensions or seismic bracing requirements.
Enclosed racks dominate installed base. Modular is where expansion concentrates.
Installation Type:
Cost tier stratification separates premium integrated systems from commodity mounting formats, with price multiples widening as power density requirements escalate.
- Free-Standing:Floor-mounted enclosures rated for 30+ kW loads anchor hyperscale deployments across the Paris region. These units integrate liquid cooling manifolds and busway power distribution within single structural frames.
- Integrated:Pre-engineered systems combining rack, cooling, and power distribution command premium positioning. Cloud operators in Marseille submarine cable landing zones specify these to bypass conventional multi-vendor integration.
- Wall-Mount:Compact units serve edge computing nodes and telecommunications distribution points with constrained floor space.
- Rack-Mounted:Sub-enclosures for blade server chassis persist in enterprise refresh cycles with moderate density requirements.
Free-standing units capture volume share. Integrated formats are climbing the fastest.
Material:
Application context drives material selection, with weight-critical raised-floor environments favoring alternatives despite steel's structural dominance.
- Steel:Cold-rolled carbon steel construction commands procurement majority due to load-bearing capacity and cost efficiency. RE2020-compliant facilities across Île-de-France specify powder-coated steel enclosures with integrated containment.
- Aluminum:Lightweight variants gain traction in seismic-sensitive zones and raised-floor environments where loading constraints limit steel adoption. Weight advantages compete against higher material costs and reduced electromagnetic shielding.
- Composite:Fiber-reinforced polymer panels serve specialized corrosion-resistant requirements in coastal Marseille facilities.
- Plastic:Polycarbonate components appear in non-structural elements such as cable management channels and airflow baffles.
Steel dominates installed base. Aluminum is gaining share fastest.
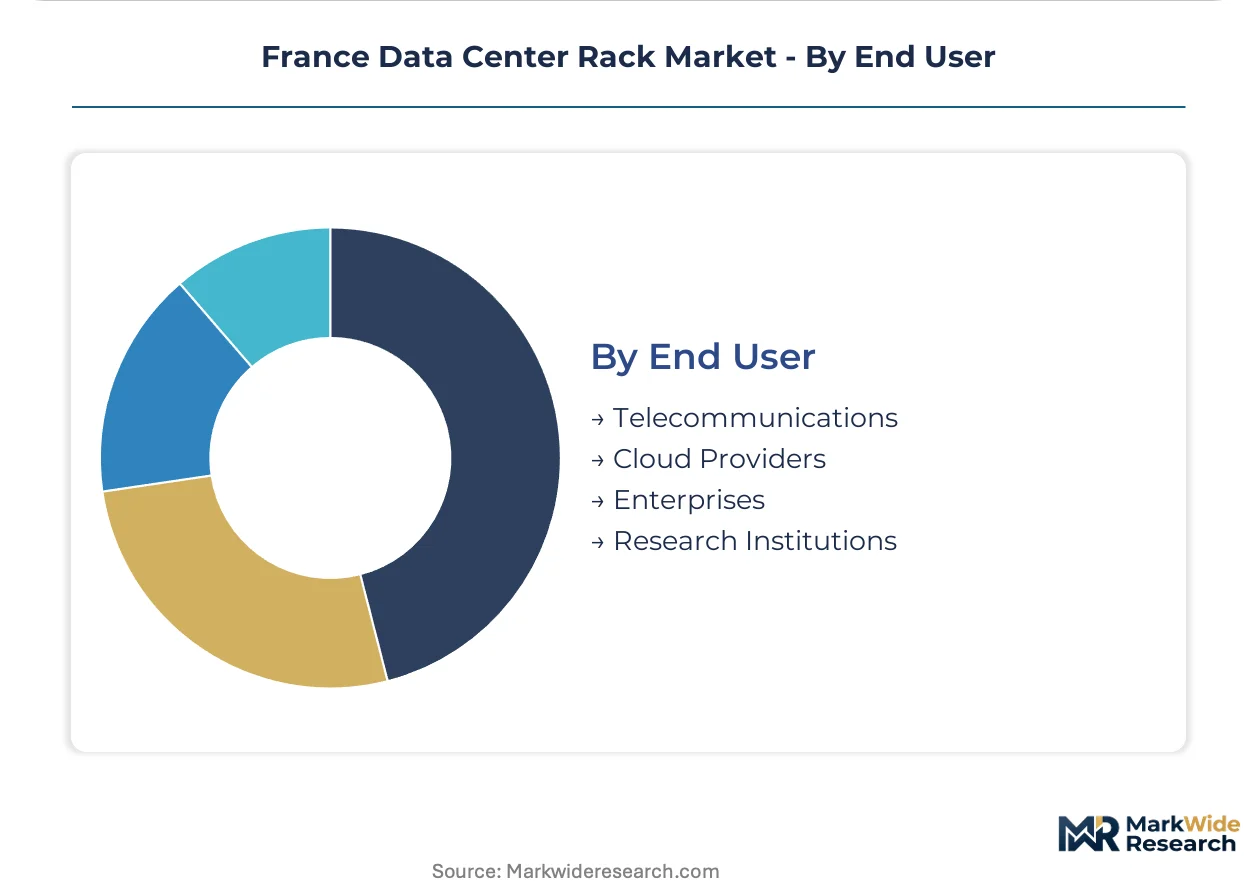
End User:
Customer type determines specification authority, with cloud operators displacing traditional contractor-led procurement through direct manufacturer relationships.
- Cloud Providers:Hyperscale operators command rack specification directly, bypassing distribution channels through factory-integrated procurement. Paris-Saclay corridor deployments concentrate demand for liquid-cooled, high-density enclosures rated beyond 30 kW.
- Telecommunications:Carrier-neutral facilities and 5G edge nodes drive demand for compact, wall-mount and free-standing configurations with standardized power interfaces.
- Enterprises:Corporate data centers exhibit slower refresh cycles, preserving open-frame steel racks amid gradual RE2020 compliance timelines.
- Research Institutions:CEA and university computing centers specify custom configurations for GPU-intensive workloads with non-standard dimensions.
Enterprises dominate installed base. Cloud providers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud operators and colocation providers concentrate procurement authority across French metropolitan corridors, with hyperscale deployments driving specification standards that cascade through regional supply chains.
Île-de-France
Paris-Saclay corridor deployments anchor national demand for liquid-cooled, high-density enclosures. RE2020 mandates enforced by ANSM and environmental agencies compel thermal efficiency disclosures at the rack level. Saint-Denis and Aubervilliers colocation clusters specify factory-integrated modular units with embedded metering to satisfy audit requirements.
Provence-Alpes-Côte d'Azur
Marseille submarine cable landing zones attract operator-led infrastructure builds bypassing conventional distribution channels. CE marking compliance filters import access, favoring European manufacturers with established conformity pathways. Fos-sur-Mer and Vitrolles facilities concentrate demand for corrosion-resistant composite rack panels in coastal environments.
Auvergne-Rhône-Alpes
Grenoble engineering clusters supply specialized thermal management talent for computational fluid dynamics and two-phase cooling design. Regional technical universities feed supplier R&D pipelines. Lyon corridor data centers remain underpenetrated relative to Paris, offering first-mover positioning for modular suppliers with localized assembly.
Hauts-de-France
Lille metropolitan area presents secondary market expansion opportunities as fiber connectivity improves. RE2020 compliance timelines lag Île-de-France, preserving open-frame steel racks in legacy enterprise facilities. Roubaix and Villeneuve-d'Ascq industrial zones support steel fabrication inputs for standard enclosure production.
Occitanie
Toulouse aerospace and defense computing centers specify custom rack configurations for non-standard equipment dimensions. Regional research institutions drive demand for seismic-braced enclosures in seismic-sensitive zones. Montpellier emerging data center corridor attracts edge computing node deployments with compact wall-mount requirements.
France Data Center Rack Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement hierarchies, with direct manufacturer relationships displacing traditional distribution in hyperscale segments. The vendor base stratifies into three tiers: integrated infrastructure providers, thermal management specialists, and commodity enclosure fabricators. Dominant competitive moves include capacity expansion in secondary French regions and technology licensing for liquid cooling integration.
Among France-based electrical infrastructure groups, Schneider Electric SE and Legrand S.A. exemplify the integrated provider archetype, anchoring positions through domestic engineering presence and RE2020 compliance pathways. Vertiv Group Corp. occupies a position within the thermal management specialist tier, representing precision cooling convergence with rack architecture. Rittal GmbH and Co. KG sits within the German-origin enclosure fabricator segment, serving standardized procurement requirements across European markets.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Legrand S.A. |
| Eaton Corporation |
| Rittal GmbH and Co. KG |
| Dell Inc. |
| Hewlett Packard Enterprise |
| nVent Electric PLC |
| Minkels B.V. |
| Others |
Pricing and Supply Chain Analysis
Roubaix steel fabrication clusters anchor enclosure supply capacity, translating raw material proximity into pricing leverage for domestic fabricators serving Île-de-France hyperscale deployments. Cold-rolled steel input volatility feeds directly through to rack quotations, compressing margin pools for mid-tier suppliers without long-term mill agreements or backward integration into metal forming.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between colocation providers and enclosure fabricators. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy open-frame levels reflects certification grade and thermal density ratings. Pricing pressure stems from GPU cluster demand outstripping specialized engineering capacity, forcing buyers toward premium tiers. Cloud providers exhibit lowest price sensitivity given specification authority, while enterprise refresh cycles remain most vulnerable to steel cost pass-through.
Supply Chain Analysis
Contract manufacturing concentrates among Grenoble-area precision metalwork specialists and German-origin enclosure integrators with French assembly footprints. Cold-rolled steel draws from ArcelorMittal European mills, while aluminum extrusions source from Norwegian smelters and Chinese semi-finished suppliers. Single-source vulnerability sits with liquid cooling manifold suppliers serving 30+ kW rack configurations. Distribution runs through direct manufacturer relationships for hyperscale accounts, with regional distributors retaining position in mid-market enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery driven by hyperscale cloud expansion accelerating replacement demand ahead of legacy depreciation schedules. Rack procurement cycles compress as liquid cooling integration forces premature refresh of air-cooled infrastructure.
For Market Incumbents: Entrench thermal engineering leadership by acquiring Grenoble-area CFD talent pools before competitors lock specialist capacity. Expand modular assembly presence in Lyon corridor to capture underpenetrated demand before regional connectivity improvements attract new entrants. Defend against busway-cooling convergence threats by deepening in-house production of integrated power distribution manifolds. For New Entrants and Emerging Players: Lille metropolitan area offers white-space positioning as fiber backbone investments lag Paris-Saclay density. Target wall-mount edge computing configurations for 5G telecommunications nodes where specification barriers sit lower than hyperscale direct procurement. Pursue CE marking compliance partnerships with established conformity assessment bodies to bypass timeline delays filtering non-European import access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors thermal management specialists with liquid cooling IP and established RE2020 compliance pathways. Long-term viability hinges on rack-level energy disclosure mandates expanding across EU member states. Watch for EU AI Act infrastructure disclosure implementation as inflection signal triggering specification pull for embedded metering capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Licensing | Schneider Electric and Vertiv thermal IP partnerships accelerate two-phase cooling adoption across Paris-Saclay facilities. |
| Secondary Region Capacity Expansion | Localized Lyon assembly reduces logistics costs for Auvergne-Rhône-Alpes data center corridors underserved by incumbent distribution. |
| RE2020 Compliance Certification Investment | ANSM audit pathway acceleration positions enclosed rack formats for mandatory thermal efficiency disclosure requirements. |
| Busway-Cooling Integration Partnership | Legrand power distribution convergence with liquid cooling manifolds captures premium positioning beyond commodity enclosure sales. |
| Seismic Bracing Specification Development | Toulouse aerospace computing demand for custom seismic-rated enclosures opens specialized fabrication revenue pools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center engineering directors, colocation procurement managers, thermal systems architects, and facility construction contractors; alongside secondary validation through hyperscaler capex disclosures, ANSM regulatory filings, CE marking conformity databases, and EU AI Act implementation drafts. Bottom-up rack shipment estimates triangulated against top-down facility power capacity expansion across the analysis window.
Forecast inputs considered rack density evolution, RE2020 compliance timeline acceleration, and GPU cluster deployment patterns. Segmentation dimensions modeled include product format, installation type, material construction, and end-user category with regional procurement authority weighting. CAGRs derived from installed base replacement cycles and expansion capacity pipelines throughout the forecast period, with liquid cooling penetration rates and steel cost trajectory assumptions as sensitivity variables.
Practitioners should monitor RE2020 enforcement tightening and EU AI Act infrastructure disclosure finalization for early signals of specification shift toward embedded metering requirements. Forecasts reflect assumptions regarding hyperscale cloud commitment continuity and aluminum supply chain stability. Quarterly review of LME steel pricing and CE marking processing timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Next Generation Data Center Market