
 Sri Lanka Used Car Market | 2026-2036
Sri Lanka Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Used Car Market Insights
Multi-source inventory aggregation from Japan, Thailand, and Singapore is hardening as the dominant procurement pattern among Colombo-based dealers. Ikman leverages its classifieds platform to sustain nationwide seller reach beyond traditional auction houses. Riyasewana anchors its position through deep penetration of Sinhala-language digital channels, while Indra Traders competes via established physical showrooms in urban corridors.
A used car denotes a previously registered motor vehicle transferred through resale, typically assessed by odometer reading, service history verification, and structural integrity inspection before re-registration. The primary commercial purpose centers on affordable mobility for price-sensitive consumers excluded from new-vehicle financing. Hatchback and sedan categories dominate transaction volume given their alignment with narrow urban roads and fuel efficiency priorities in Sri Lankan cities. SUV and MPV segments attract premium pricing among family buyers and tourism operators, though electric fuel type penetration remains constrained by charging infrastructure gaps in provincial areas.
The Central Environmental Authority enforces emission standards on imported pre-owned units, while Sri Lanka Customs applies tariff classifications that shape landed cost structures for Japanese and Korean models. The country's national automotive regulator mandates roadworthiness certification, creating compliance barriers for damaged-condition imports that filter substandard inventory from formal channels. Stakeholders must monitor potential revisions to import age restrictions and emission testing protocols that could reshape supply availability.

Market Dynamics
The Central Environmental Authority's emission screening protocols are compressing import eligibility windows and forcing Colombo dealers to diversify sourcing beyond Japanese auction houses toward Thailand and Singapore channels.
Growth Catalysts
- Ride-hailing fleet expansion:Colombo and Galle drivers are creating sustained demand for affordable automatic hatchbacks and sedans as app-based mobility platforms scale driver recruitment.
- Fuel efficiency prioritization:Urban congestion and elevated fuel costs in Western Province cities are redirecting buyers toward compact Japanese models with proven consumption metrics.
- Digital platform penetration:Sinhala-language classifieds and mobile-first listing services are collapsing information asymmetry between Colombo dealers and provincial buyers.
Market Restraints
- Import age restrictions:Sri Lanka Customs tariff classifications on pre-owned vehicles create landed cost volatility that prices out budget segments in peripheral districts.
- Charging infrastructure gaps:Provincial areas outside Colombo lack reliable electric vehicle charging networks, constraining hybrid and battery-electric model uptake despite emission incentives.
- Structural supply concentration:Dependence on Japanese auction houses for quality-assured inventory exposes dealers to yen exchange rate fluctuations and shipping bottlenecks.
Strategic Opportunities
- Tourism operator fleet renewal:SUV and MPV categories serving coastal resort corridors in Galle and Negombo present premium pricing potential for low-mileage imports.
- Provincial digital access:Underpenetrated districts in Central and Southern provinces await mobile-enabled financing integration to unlock deferred demand.
- Roadworthiness certification streamlining:The national automotive regulator's testing protocols could accelerate if third-party inspection partnerships expand beyond Colombo.
Industry Challenges
- Skilled inspection technician scarcity:Structural integrity assessment and odometer verification expertise concentrates in Colombo, limiting quality assurance capacity in emerging dealer networks.
- Service history authentication:Fragmented documentation standards across Japanese, Thai, and Singaporean export channels complicate buyer trust-building and warranty underwriting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Used Car Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Hatchback, Sedan, SUV, MPV Fuel Type: Petrol, Diesel, LPG, Electric Transmission: Automatic, Manual, CVT, Semi-Automatic Condition: New, Pre-Owned, Certified Pre-Owned, Damaged |
| Companies Covered | Ikman, Riyasewana, Patpat, Autodirect, Careka, Indra Traders, AutoLanka, AutoMe, Automachan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Used Car Market Trends and Innovations
Digital verification tools and platform-based financing are compressing transaction cycles and collapsing traditional information advantages held by physical showroom operators in urban corridors.
Telematics-enabled condition reporting is expanding into pre-purchase assessment workflows. Japanese export yards now transmit real-time engine diagnostic data to Colombo dealers prior to vessel loading. Ride-hailing fleet managers in Western Province districts are adopting these verified-condition imports to minimize downtime risk and accelerate driver onboarding.
The Central Environmental Authority's tighter emission screening is reshaping import eligibility categories. Vehicles failing Euro 4-equivalent thresholds face detention at Colombo port pending remediation or re-export. Thai-sourced inventory with factory-certified emission compliance is gaining preference among dealers seeking predictable customs clearance timelines.
Platform-based vehicle financing is displacing cash-dominant transactions in Colombo and Galle urban corridors. Fintech integrations within classifieds marketplaces enable real-time credit scoring against driver earnings data from ride-hailing apps. Younger buyers in Western Province districts demonstrate higher willingness to accept digital-only documentation in exchange for same-day approval velocity.
Sri Lanka Used Car Market Segmentation
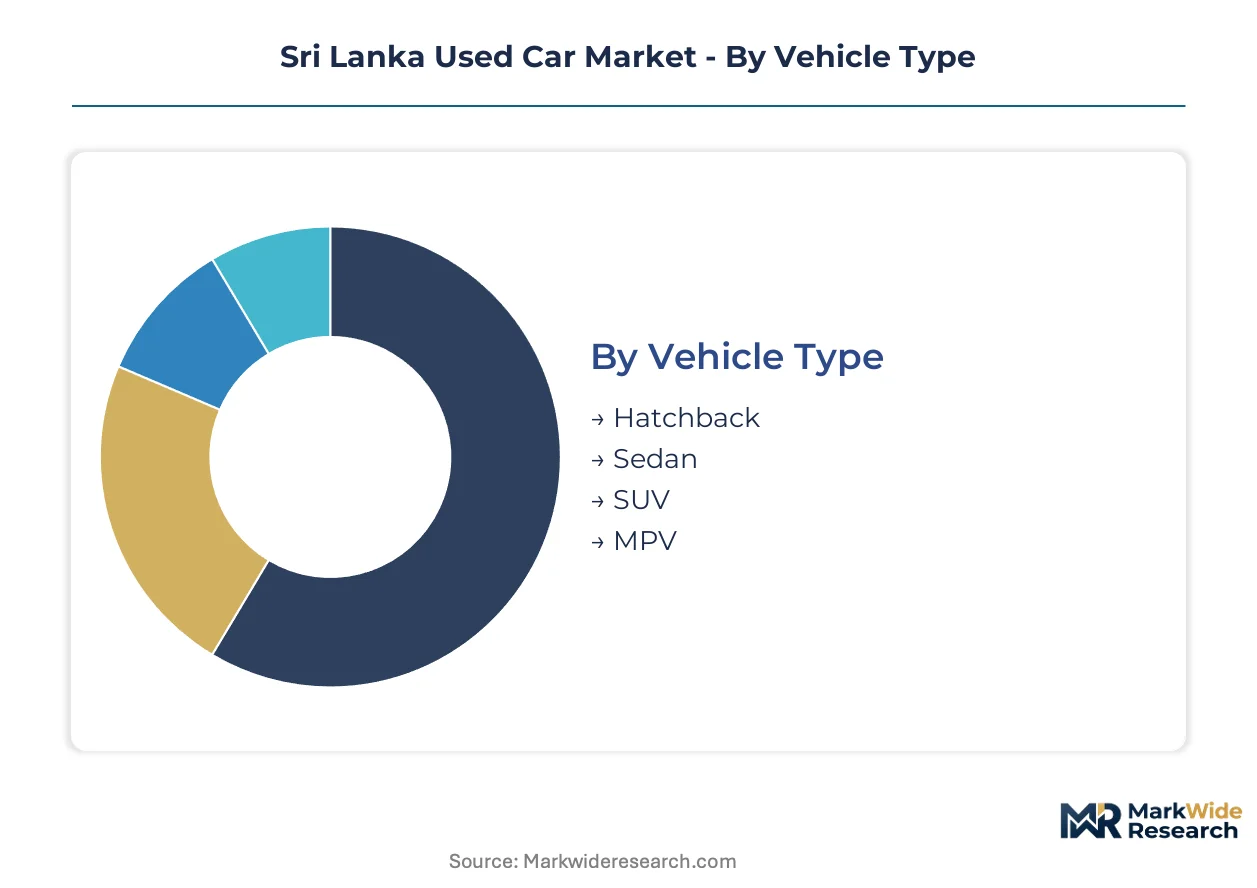
Segmentation in the Sri Lankan used car market reflects distinct buyer priorities shaped by urban congestion, fuel costs, and financing access. Colombo-based dealers structure inventory procurement around these divides to match Western Province demand density against provincial purchasing constraints.
Vehicle Type:
Buyers in Colombo and Galle prioritize maneuverability and operating cost over cabin volume or prestige signaling.
- Hatchback:Compact wheelbase under 4 meters dominates narrow urban corridors. Ride-hailing drivers in Colombo district favor automatic variants for stop-start traffic efficiency, with Toyota Vitz and Suzuki Swift units commanding shortest listing durations.
- Sedan:Three-box configuration attracts family buyers seeking separate luggage compartments for inter-city travel. Toyota Corolla and Honda Civic imports from Japanese auction houses sustain premium pricing in Galle and Negombo corridors where tourism operators source fleet replacements.
- SUV:Higher ride height and all-wheel-drive capability serve coastal resort operators in Southern Province. Landed cost volatility from yen exchange fluctuations constrains volume in budget segments.
- MPV:Seven-seat configurations target multi-generational households and hotel shuttle services. Narrow import eligibility windows from Central Environmental Authority screening limit supply predictability.
Hatchback leads on scale; SUV leads on momentum.
Fuel Type:
Operating economics and refueling infrastructure availability determine fuel selection across buyer segments.
- Petrol:Widest service network coverage and lower upfront vehicle cost sustain dominance in Western Province urban corridors. 1000-1500cc displacement brackets align with Central Environmental Authority emission thresholds.
- Diesel:Higher thermal efficiency attracts commercial operators with high annual mileage. Sri Lanka Customs tariff classifications create landed cost premiums that filter private buyers toward petrol alternatives.
- LPG:Retrofit conversion kits enable operating cost reduction for existing petrol inventory. Safety certification requirements from the national automotive regulator constrain aftermarket installation quality.
- Electric:Battery-electric models face charging infrastructure gaps outside Colombo metropolitan area. Provincial buyers in Central and Southern districts defer adoption pending grid reliability improvements.
Petrol leads on scale; electric leads on momentum.
Transmission:
Traffic density and driver recruitment patterns in ride-hailing platforms reshape transmission preferences.
- Automatic:Torque converter and dual-clutch variants minimize driver fatigue in Colombo congestion. Fleet managers at app-based mobility platforms specify automatic-only procurement to accelerate onboarding of new drivers.
- Manual:Lower purchase price and maintenance simplicity retain foothold in provincial districts where skilled technician scarcity limits automatic repair access. Central Province buyers accept manual operation for cost containment.
- CVT:Continuously variable ratios optimize fuel consumption across urban speed ranges. Japanese-sourced Toyota and Honda inventory dominates certified pre-owned channels.
- Semi-Automatic:Automated manual transmissions offer cost midpoint between full automatic and manual systems. Limited model availability constrains penetration in formal dealer networks.
Automatic leads on scale; CVT leads on momentum.
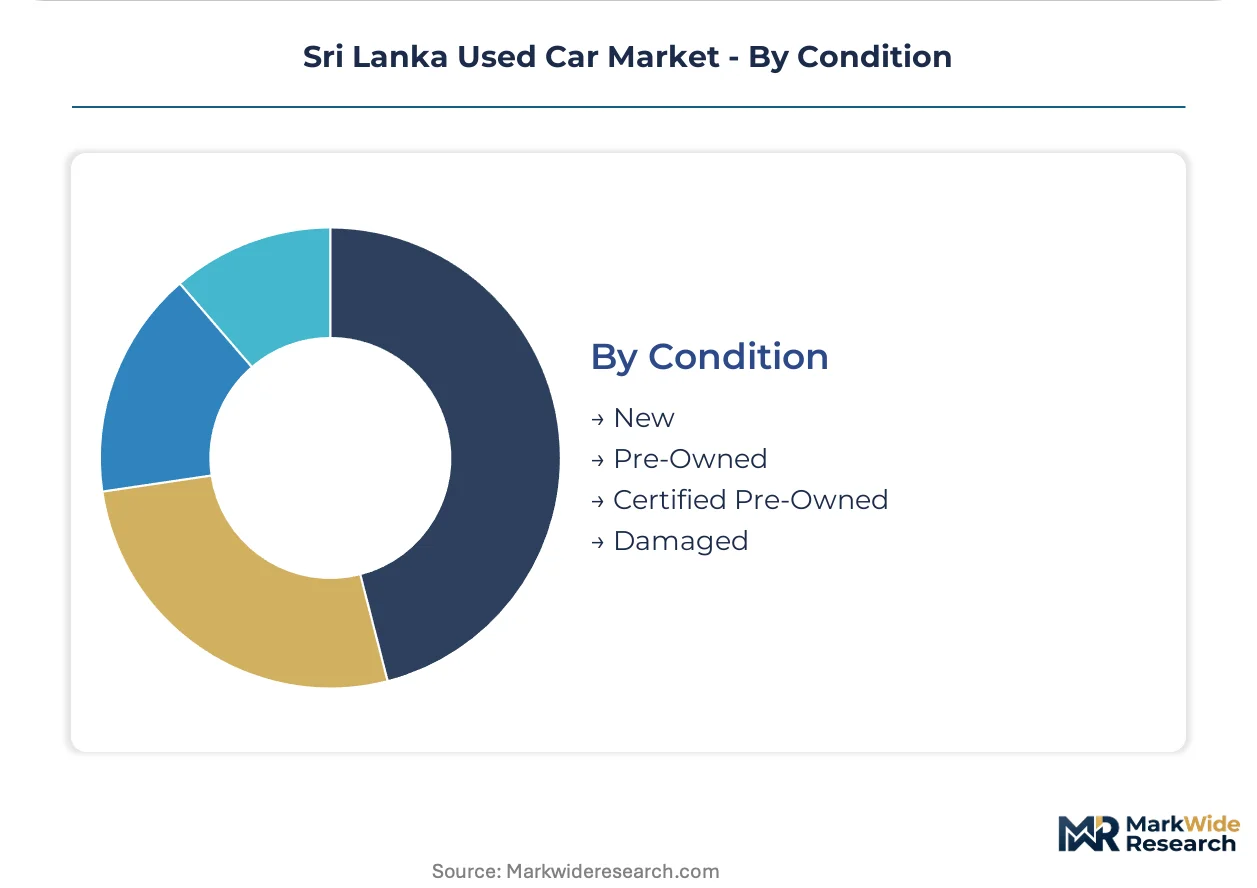
Condition:
Documentation integrity and warranty backing separate formal channel inventory from informal roadside transactions.
- Pre-Owned:Previously registered units with verified service history constitute core transaction volume. Colombo dealers aggregate Japanese auction inventory with telematics-enabled condition reporting prior to vessel loading.
- Certified Pre-Owned:Third-party inspection partnerships with the national automotive regulator create quality differentiation. Roadworthiness certification streamlines re-registration for buyers seeking financing access.
- New:Dealer demonstration units and short-term lease returns offer near-zero odometer readings. Premium pricing limits addressable market to corporate fleet operators and expatriate buyers.
- Damaged:Structural integrity compromises from auction-grade classification face detention at Colombo port pending remediation. Substandard inventory filters toward informal channels lacking regulatory oversight.
Pre-Owned leads on scale; Certified Pre-Owned leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in vehicle sourcing are compressing import eligibility windows and forcing procurement migration toward Thailand and Singapore channels with more predictable emission compliance frameworks.
Western Province
Colombo district concentrates the highest transaction density as ride-hailing fleet managers source automatic hatchbacks for driver recruitment. The Central Environmental Authority enforces Euro 4-equivalent emission screening at Colombo port, detaining non-compliant inventory. Negombo corridor dealers aggregate Japanese auction supply with telematics-enabled condition verification prior to vessel loading.
Southern Province
Galle urban center generates sustained demand from tourism operators renewing SUV and MPV shuttle fleets for coastal resort access. Sri Lanka Customs tariff classifications on larger displacement vehicles create landed cost premiums that filter budget buyers toward compact alternatives. Matara district shows emerging dealer network expansion as mobile financing platforms penetrate provincial buyer segments.
Central Province
Kandy metropolitan area exhibits deferred demand for certified pre-owned inventory as roadworthiness certification capacity concentrates in Colombo. The national automotive regulator mandates third-party inspection partnerships that remain underdeveloped outside Western Province. Nuwara Eliya sub-region attracts premium pricing for low-mileage Japanese imports serving hill-country tourism routes.
North Western Province
Kurunegala district represents an underpenetrated market awaiting digital platform integration for seller-buyer matching. Charging infrastructure gaps constrain battery-electric model uptake despite emission incentives available in Colombo. Puttalam corridor dealers rely on informal sourcing channels due to distance from certified inspection facilities.
Sri Lanka Used Car Market Competitive Landscape
Established classifieds platforms occupy the standard tier; emerging entrants pursue physical-digital hybrid models and specialized fleet servicing. The vendor base distributes across three functional layers: horizontal classifieds aggregators, vertical automotive specialists, and physical showroom operators with import licensing. Three strategic archetypes dominate: platform-first marketplaces collapsing information asymmetry, inspection-integrated dealers offering certified pre-owned backing, and fleet-focused suppliers serving ride-hailing recruitment. Competitive moves concentrate on Sinhala-language mobile interface development and third-party financing integration.
Within the platform-aggregator tier, Ikman leverages its horizontal classifieds infrastructure to sustain nationwide seller reach beyond traditional auction house relationships. Riyasewana anchors the vertical automotive specialist position through deep penetration of Sinhala-language digital channels. Indra Traders exemplifies the physical showroom archetype with established import licensing and urban corridor presence.
| Leading Market Players |
|---|
| Ikman |
| Riyasewana |
| Patpat |
| Autodirect |
| Careka |
| Indra Traders |
| AutoLanka |
| AutoMe |
| Automachan |
| Others |
Pricing and Supply Chain Analysis
Telematics-enabled condition verification is compressing information asymmetry between Japanese auction houses and Colombo dealers while simultaneously raising procurement costs and concentrating quality-assured supply among inspection-integrated distributors. This dual effect reshapes margin distribution across formal dealer networks and informal roadside channels.
Pricing Analysis
Importer markup layers dominate transaction economics, with Colombo-based dealers commanding 12-18% margins on certified pre-owned inventory against 5-8% for uncertified roadside sales. Price differentiation rests on roadworthiness certification status and telematics-verified service history, with Central Environmental Authority compliance tiers creating additional stratification. Cost compression in economy segments intensifies as yen exchange volatility elevates landed costs for Japanese auction sourcing. Ride-hailing fleet managers demonstrate lowest price sensitivity due to financing access through app-integrated fintech platforms, while provincial cash buyers in Central Province exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for emission-non-compliant vehicles detained at Colombo port create secondary refurbishment channels feeding informal provincial markets. Primary supply concentrates in Japan, Thailand, and Singapore, with Thai-sourced inventory gaining preference for predictable customs clearance. Component dependencies span torque converter assemblies, engine control modules, and catalytic converter systems. Single-source vulnerability to Japanese auction house concentration exposes dealers to shipping bottlenecks and currency fluctuations. Distribution runs through platform-aggregator marketplaces collapsing traditional showroom intermediation in Western Province urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
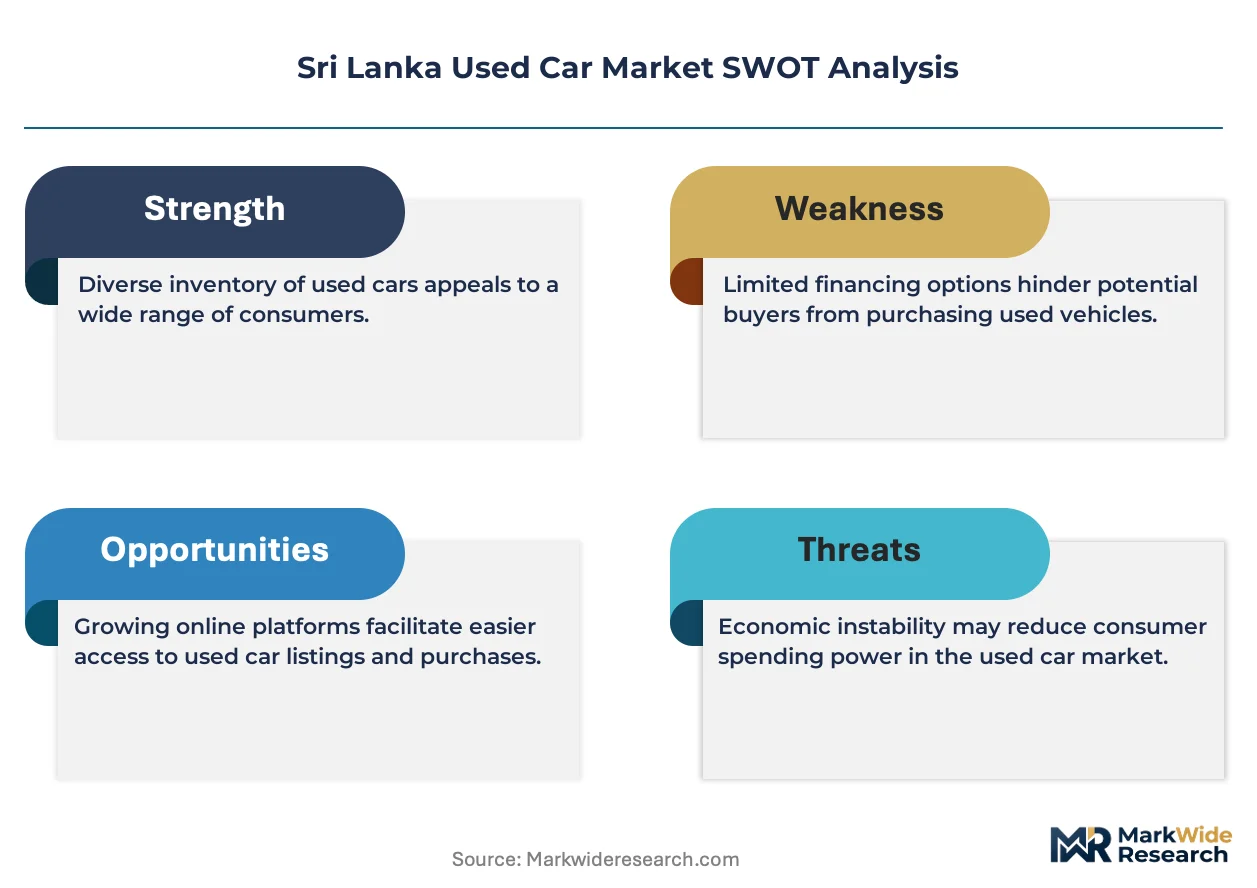
The Sri Lanka used car market functions as a stable compounder anchored by structural ride-hailing fleet expansion generating sustained replacement demand for affordable automatic transmissions.
For Market Incumbents: Extend inspection-integrated service capabilities into Central and Southern provinces before third-party certification partnerships mature. Consolidate procurement scale through multi-source aggregation from Thailand and Singapore to offset yen volatility exposure. Lock in exclusive telematics data partnerships with Japanese export yards to defend information advantages against platform competitors. For New Entrants and Emerging Players: Central Environmental Authority emission screening tightening opens a window for specialized compliance-remediation services at Colombo port. Target underpenetrated districts in North Western Province with mobile-first financing integration unlocking deferred demand among cash-constrained buyers. Pursue white-label inspection partnerships with the national automotive regulator to bypass capital-intensive physical showroom requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among provincial dealer networks lacking digital platform integration but holding established seller relationships. Long-term viability favors inspection-integrated operators with certified pre-owned capabilities and fintech partnerships over pure classifieds aggregators. Monitor Central Environmental Authority import age restriction revisions as the critical inflection signal for supply availability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Partnership Expansion | Real-time engine diagnostic transmission from Japanese export yards accelerates Colombo dealer procurement velocity. |
| Provincial Inspection Network Buildout | Third-party roadworthiness certification partnerships beyond Western Province unlock Central Province demand. |
| Fintech-Platform Integration | Ride-hailing driver earnings data enables same-day credit scoring displacing cash-dominant transactions. |
| Thai-Sourcing Channel Diversification | Factory-certified emission compliance from Thailand reduces Colombo port detention risk versus Japanese auctions. |
| Sinhala-Language Mobile Interface Development | Deep penetration of local-language digital channels collapses information asymmetry with provincial buyers. |
Research Methodology
Bottom-up ride-hailing fleet and tourism operator demand modeling reconciled against top-down Japanese auction house and Thai export yard supply tracking forms the analytical core. Primary interviews with Colombo dealer principals, Central Environmental Authority compliance officers, platform marketplace operators, and ride-hailing fleet managers combined with secondary validation against Sri Lanka Customs tariff classifications, vehicle registration databases, and classifieds marketplace transaction records. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map vehicle type, fuel category, transmission architecture, and condition grade against regional demand density and import eligibility constraints across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by pricing tier and regional penetration rates. Forecast inputs incorporate Central Environmental Authority emission threshold revisions, yen exchange rate assumptions, and ride-hailing platform driver recruitment targets.
Revisions become necessary when Central Environmental Authority import age restrictions tighten, charging infrastructure investments accelerate in provincial districts, or Sri Lanka Customs tariff classifications shift. Practitioners should monitor regulatory gazette notifications and grid reliability improvements in Central and Southern provinces for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Used Semi Truck Market