
 Belgium Used Car Market | 2026-2036
Belgium Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Used Car Market Insights
Belgian dealer networks is consolidating as independent operators face margin pressure from digital marketplaces and manufacturer-certified programs. D'Ieteren Group leverages its multi-brand distribution infrastructure to control premium used vehicle flows through official channels. CarNext specializes in direct-to-consumer online remarketing, bypassing traditional auction layers. AutoScout24 dominates classified listing aggregation, capturing search traffic across language boundaries in Brussels and Flanders.
A used car comprises a pre-owned passenger vehicle evaluated by age, mileage, mechanical condition, and ownership history prior to resale; units undergo inspection, reconditioning, and documentation transfer to meet roadworthiness standards for secondary ownership. The Belgium Used Car Market serves consumers and fleet operators seeking depreciated assets with verified service records. SUV and hatchback segments lead transaction volumes, reflecting Belgian preferences for compact urban mobility and family-oriented versatility. Electric and hybrid fuel types represent the fastest-growing structural category, driven by LEZ compliance deadlines and residual value uncertainty in older diesel stock. The 4-6 year age bracket anchors margin pools, balancing depreciation curves against remaining manufacturer warranty coverage.
Flanders enforces Low Emission Zone standards through regional environmental agencies, while Brussels and Wallonia maintain parallel but distinct urban access restrictions, creating a fragmented compliance map for cross-border vehicle movement. Belgium's federal Vehicle Inspection Service (GOCA) mandates periodic technical controls that filter unfit inventory from circulation, elevating certified pre-owned programs. BCA Belgium and Arval Belgium navigate this regulatory mosaic by centralizing remarketing operations with embedded compliance documentation. Stakeholders must monitor divergence between regional LEZ timelines and federal tax treatment of used electric vehicles to anticipate arbitrage opportunities in inter-regional pricing.
Market Dynamics
Fleet renewal cycles among corporate leasing clients are compressing trade-in intervals while Low Emission Zone expansion in Brussels, Antwerp, and Ghent mechanically filters older diesel inventory from urban circulation, reshaping supply composition and residual value curves.
Growth Catalysts
- Corporate Fleet Renewal:Accelerated replacement schedules among leasing operators generate consistent trade-in volumes into certified pre-owned channels.
- LEZ Expansion:Brussels, Antwerp, and Ghent urban access restrictions mechanically retire non-compliant diesel stock, redirecting demand toward newer powertrains.
- Digital Platform Penetration:Online remarketing infrastructure in Flanders reduces inventory holding periods and expands buyer access beyond traditional dealer catchments.
Market Restraints
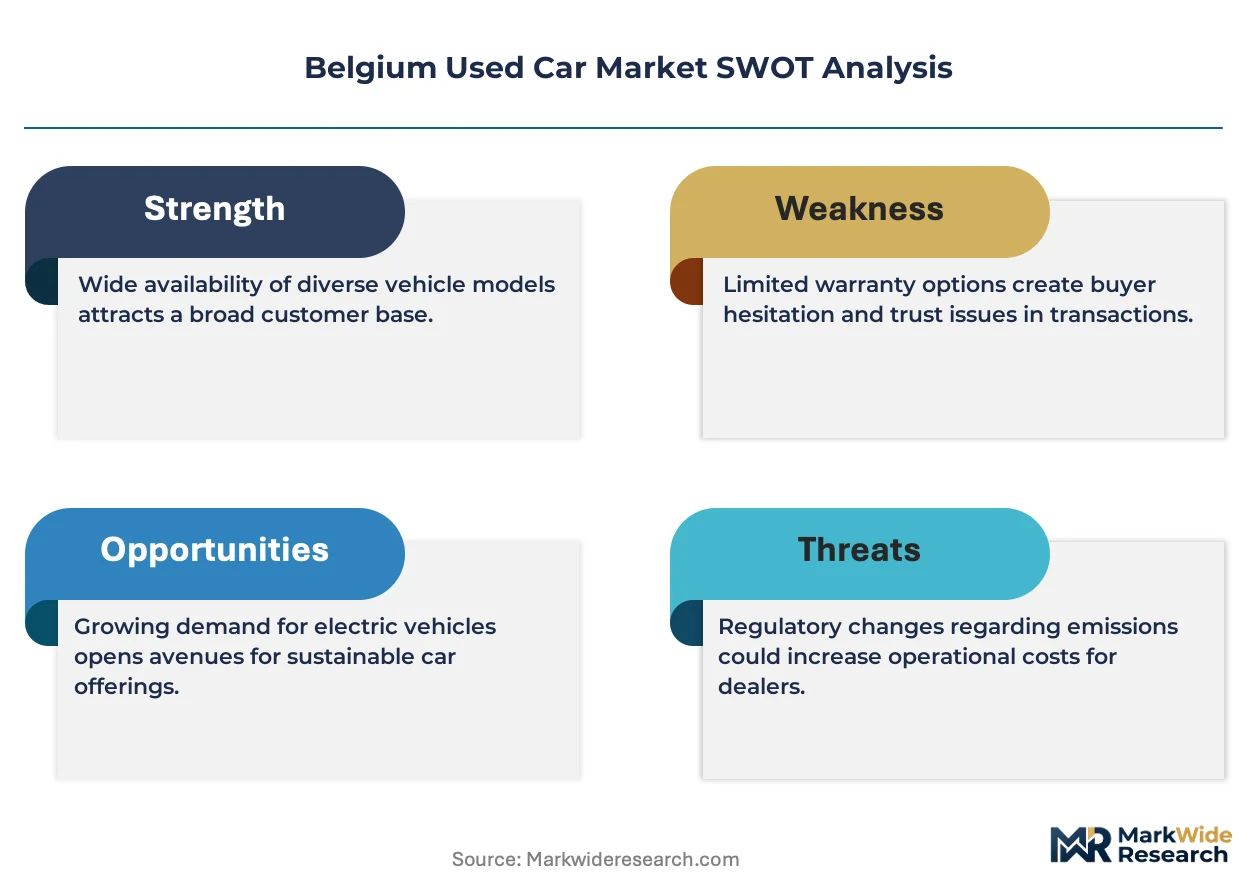
- Residual Value Volatility:Policy uncertainty around diesel taxation and LEZ phase-out timelines compresses pricing visibility for vehicles aged 6-10 years.
- Supply Concentration:Premium used vehicle flows concentrate through manufacturer-certified programs, limiting independent dealer access to desirable inventory.
- Technical Compliance Costs:GOCA inspection standards and regional LEZ documentation requirements elevate reconditioning expenses for cross-border remarketing.
Strategic Opportunities
- Electric Vehicle Arbitrage:Federal tax treatment of used electric vehicles creates inter-regional pricing gaps between Flanders, Brussels, and Wallonia.
- Embedded Compliance Services:Remarketing platforms can differentiate by bundling LEZ certification documentation and transfer assistance.
- Subscription-to-Ownership Pathways:Short-term mobility subscriptions serve as customer acquisition funnels for eventual used vehicle purchase.
Industry Challenges
- Technical Assessment Standardization:Variability in condition grading across digital marketplaces erodes buyer confidence and extends transaction cycles.
- Legacy System Integration:Independent dealers struggle to synchronize inventory feeds with dominant classified aggregators while maintaining pricing autonomy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Used Car Market |
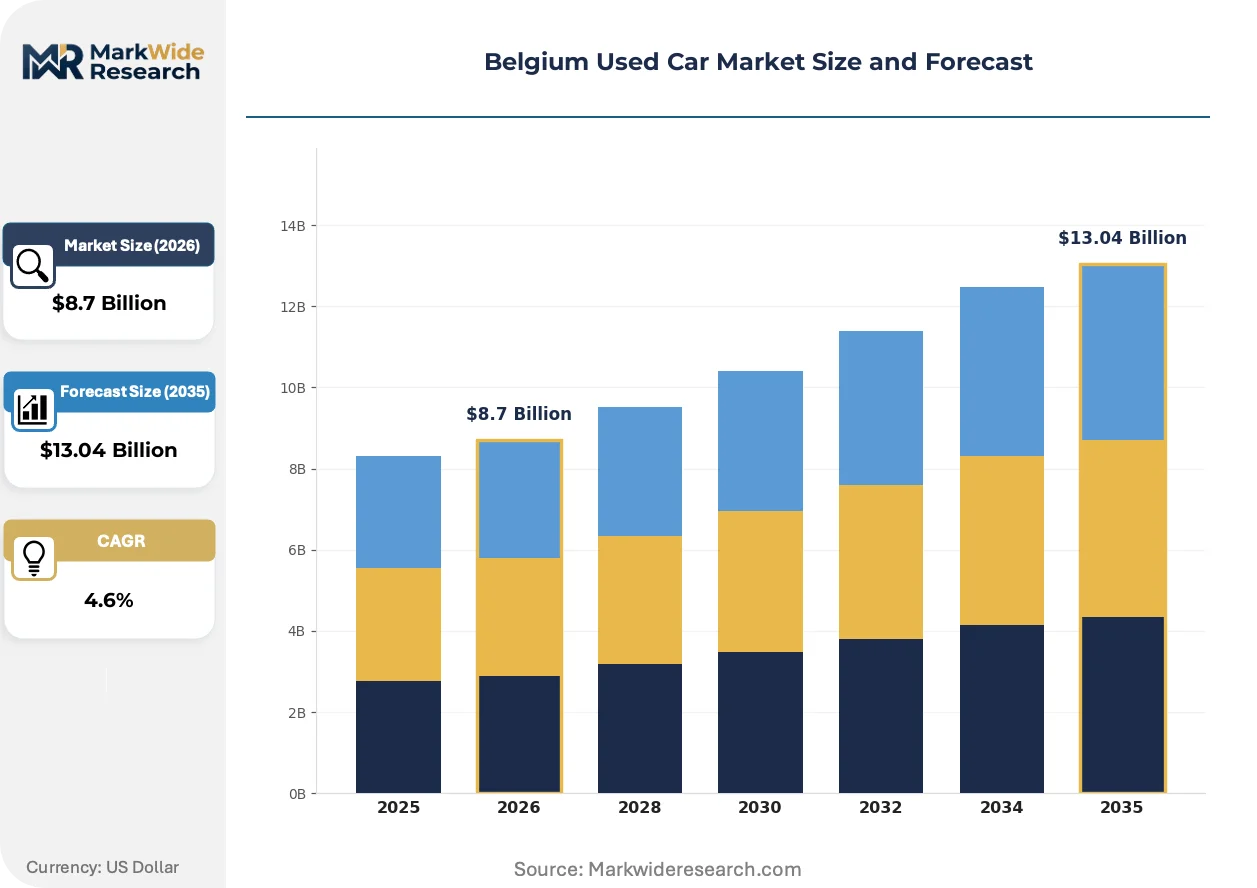
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Age: 0-3 Years, 4-6 Years, 7-10 Years, 10+ Years Condition: Excellent, Good, Fair, Poor |
| Companies Covered | D'Ieteren Group, AutoScout24, CarNext, Vroom.be, BCA Belgium, Gocar.be, Cardoen, Arval Belgium, LeasePlan Belgium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Used Car Market Trends and Innovations
Digital infrastructure is compressing traditional auction layers while regulatory compliance requirements reshape vehicle eligibility and certification workflows across Belgium's three regions.
Blockchain-based vehicle history verification is consolidating trust infrastructure in online transactions. Flemish digital platforms deploy distributed ledger systems to immutably record ownership chains, service intervals, and accident history. Corporate fleet buyers and retail consumers alike demand this transparency layer, compressing due diligence timelines and reducing information asymmetry penalties in remote purchases.
Belgium's federal Vehicle Inspection Service mandates periodic technical controls that elevate documentation burdens for cross-regional transfers. The GOCA inspection regime filters unfit inventory while creating compliance documentation requirements that favor centralized remarketing operations. Independent operators in Wallonia face particular friction navigating divergent Brussels and Flanders LEZ standards.
Direct-to-consumer online remarketing is displacing traditional dealer auction intermediation. CarNext and similar platforms enable fleet operators to reach end buyers without wholesale markups, compressing margin stacks. This channel shift concentrates in Flanders where population density supports efficient logistics, while Wallonia's dispersed geography sustains dealer network relevance for physical inspection and local service bundling.
Belgium Used Car Market Segmentation
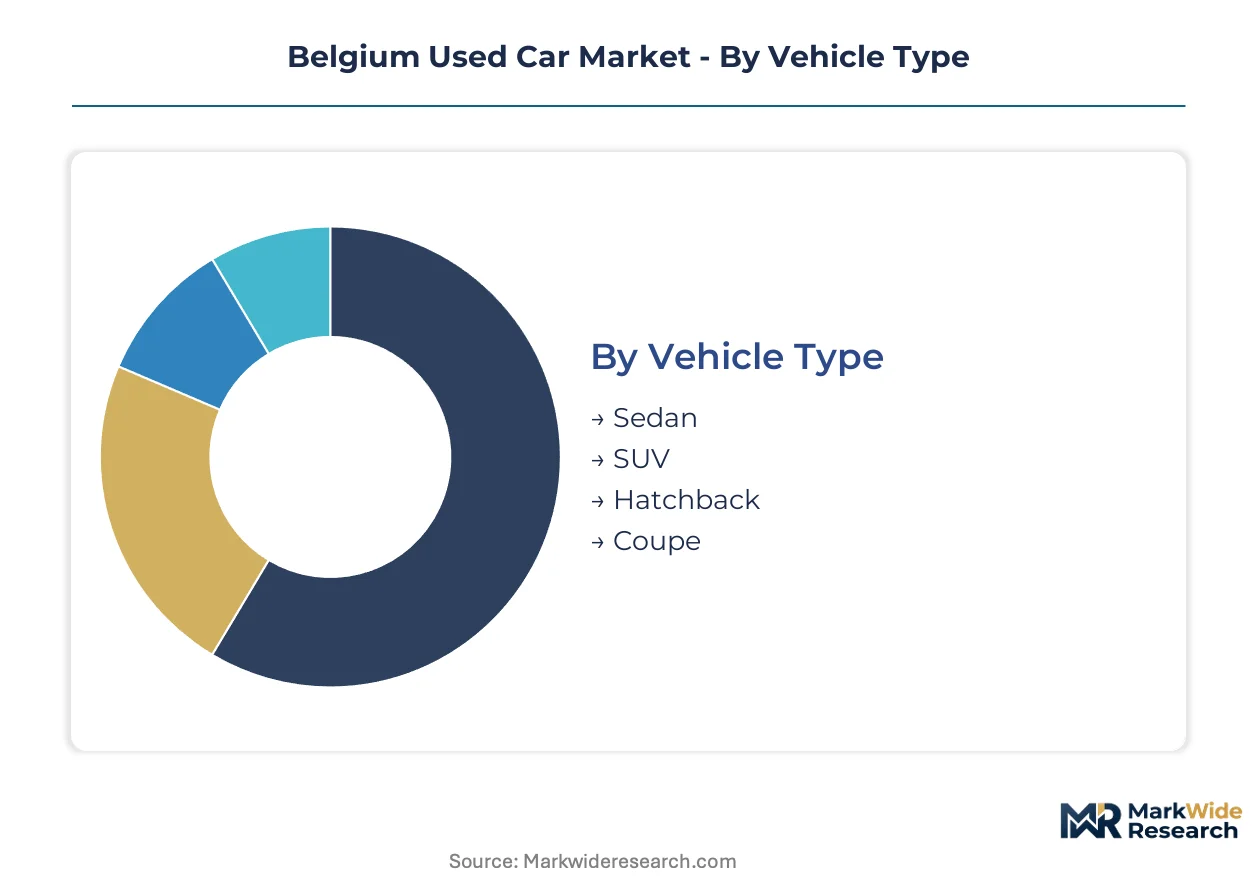
Belgian buyers navigate a multi-dimensional selection matrix where Low Emission Zone compliance intersects with warranty coverage and depreciation curves. Segmentation clarity enables fleet operators and retail consumers to align purchase decisions with regional access restrictions and total cost of ownership calculations.
Vehicle Type:
Body style selection in Belgium tracks urban parking constraints, family size requirements, and LEZ maneuverability needs across Brussels, Antwerp, and Ghent.
- SUV:Higher seating position and cargo flexibility attract family buyers in Flemish suburbs. Demand clusters around compact crossover dimensions that balance interior volume with narrow street navigability in historic city centers.
- Hatchback:Rear cargo access and truncated overhangs optimize parking efficiency in dense Brussels and Antwerp districts. Young professionals and empty-nesters prioritize this format for daily commuting flexibility.
- Sedan:Three-box architecture retains corporate fleet preference for executive transport protocols. Trunk separation appeals to sales representatives requiring secure luggage storage.
- Coupe:Two-door styling commands niche enthusiast demand with steep depreciation curves. Limited rear accessibility restricts utility for primary family vehicles.
Volume sits with Hatchback; growth tilts toward SUV.
Fuel Type:
Powertrain selection in Belgium now functions as a compliance instrument first, with operating cost and resale value calculations secondary to urban access rights.
- Electric:Zero-emission certification guarantees unrestricted Brussels, Antwerp, and Ghent LEZ access. Federal tax treatment creates inter-regional arbitrage opportunities between Flanders and Wallonia.
- Hybrid:Dual-powertrain redundancy addresses range anxiety while satisfying Euro 6 emission thresholds. Corporate leasing fleets accelerate hybrid adoption to preempt diesel phase-out timelines.
- Petrol:Lower particulate output than diesel maintains urban circulation rights for older model years. Independent dealers in Wallonia rely on petrol inventory for buyers priced out of electrified alternatives.
- Diesel:Compression-ignition efficiency retains highway economy advantages for long-distance commuters. LEZ expansion mechanically filters pre-2015 diesel stock from urban remarketing channels.
Volume sits with Petrol; growth tilts toward Electric.
Age:
Vehicle age brackets determine warranty overlap, financing eligibility, and residual value predictability in Belgian remarketing workflows.
- 4-6 Years:Depreciation curves flatten while manufacturer warranty coverage often extends, creating optimal risk-adjusted value propositions. Fleet renewal cycles concentrate trade-in supply in this bracket.
- 0-3 Years:Near-new inventory flows through manufacturer-certified channels with embedded service contracts. Premium pricing limits volume but attracts risk-averse corporate procurement.
- 7-10 Years:Pricing transparency degrades as LEZ compliance status varies by Euro emission standard. Technical compliance costs escalate for cross-border transfers.
- 10+ Years:Minimal residual value concentrates demand in budget-constrained segments and export markets. GOCA inspection failure rates rise substantially in this cohort.
Volume sits with 4-6 Years; growth tilts toward 0-3 Years.
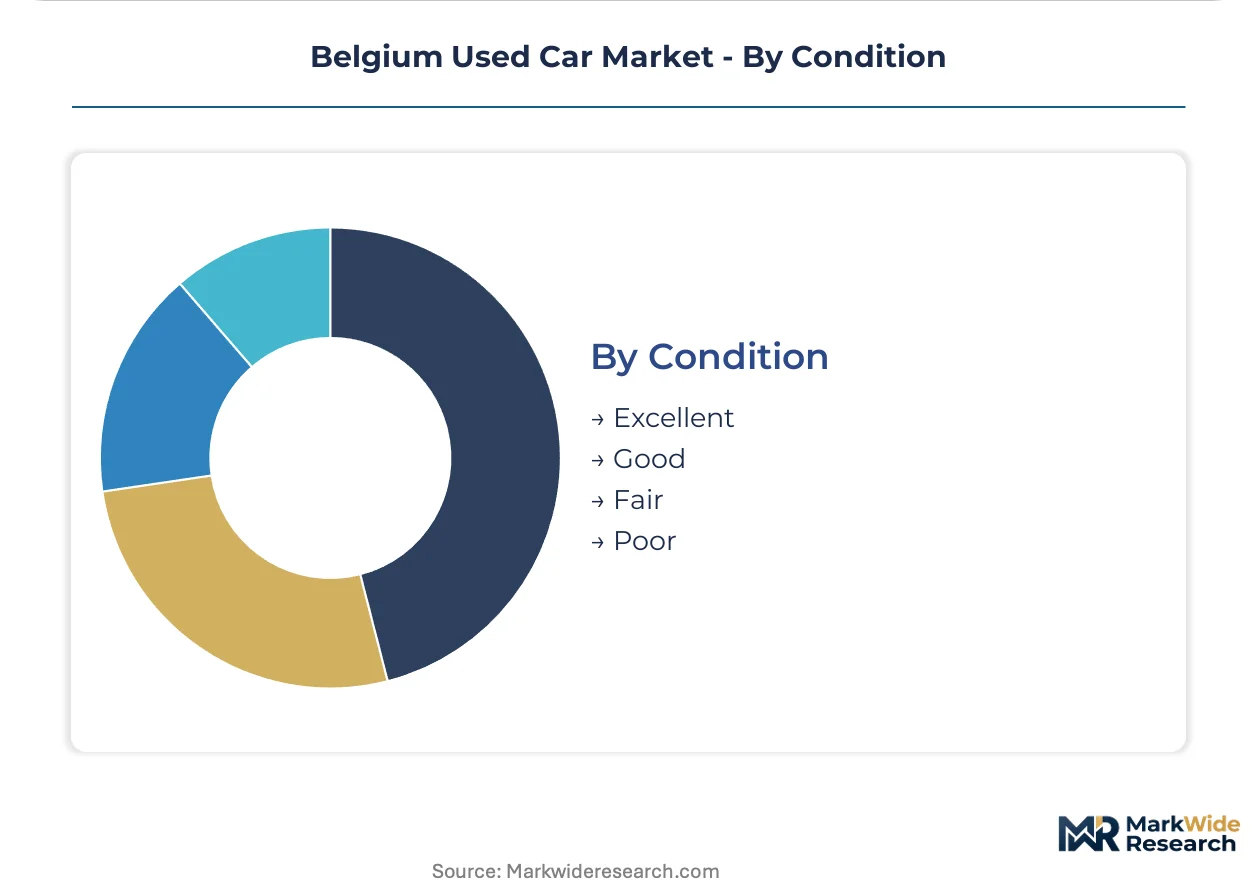
Condition:
Grading standardization across digital platforms remains incomplete, creating information asymmetry that certified programs exploit.
- Excellent:Documented single-ownership history with complete service records and original paint. Manufacturer-certified programs filter inventory to this tier for premium channel placement.
- Good:Minor cosmetic wear acceptable with verified mechanical integrity. Independent dealers in Flanders concentrate procurement here for margin optimization.
- Fair:Visible deterioration requiring reconditioning investment before retail placement. Auction volumes concentrate in this grade for dealer arbitrage.
- Poor:Significant mechanical or structural compromise limiting buyer pool to export operators and parts dismantlers. GOCA inspection failures often terminal for roadworthiness certification.
Volume sits with Good; growth tilts toward Excellent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antwerp's port infrastructure anchors Belgium's vehicle import and distribution networks, channeling used car flows through Flanders into Brussels and Wallonia. Regional regulatory divergence creates distinct operating environments across the country's three linguistic zones.
Flanders
Corporate fleet renewal cycles concentrate trade-in volumes in Antwerp and Ghent metropolitan corridors. The Flemish Environment Agency enforces Low Emission Zone standards that mechanically filter pre-Euro 6 diesel inventory from urban circulation. Digital platform penetration reaches highest density here, with online remarketing infrastructure compressing inventory holding periods in the Antwerp-Brussels corridor.
Brussels-Capital Region
Urban access restrictions create strictest powertrain compliance requirements among Belgian regions. The Brussels Environment administration operates parallel LEZ frameworks distinct from Flemish and Walloon systems. Premium used electric vehicle demand concentrates in the capital's dense residential districts where parking scarcity favors compact hatchback formats.
Wallonia
Independent dealer networks retain stronger relevance where dispersed geography sustains physical inspection requirements. The Walloon Agency for Air and Climate maintains separate LEZ implementation timelines from Brussels and Flanders. Liège and Namur serve as secondary remarketing nodes handling cross-border flows from Luxembourg and French border regions.
Antwerp Port Zone
Vehicle processing and reconditioning infrastructure clusters around Belgium's primary maritime gateway. Customs and federal Vehicle Inspection Service coordination creates documentation bottlenecks that centralized remarketing operations navigate more efficiently than independent operators. Right-hand drive conversion facilities and export preparation services concentrate in this logistics corridor.
Belgium Used Car Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer digital channels. Belgian dealer networks consolidate under margin pressure from manufacturer-certified programs and online marketplaces. Three strategic archetypes dominate: multi-brand distribution groups controlling premium flows, specialized online remarketing platforms bypassing auction layers, and independent operators surviving through local service bundling. Competitive moves concentrate on digital infrastructure investment and embedded compliance service differentiation.
Within the distribution group tier, D'Ieteren Group represents multi-brand infrastructure control, while CarNext exemplifies direct-to-consumer online remarketing specialization. AutoScout24 anchors classified listing aggregation across Belgium's linguistic boundaries. These three occupy positions reflecting distinct channel strategies—official distribution, digital-native remarketing, and search traffic aggregation—rather than direct product competition.
| Leading Market Players |
|---|
| D'Ieteren Group |
| AutoScout24 |
| CarNext |
| Vroom.be |
| BCA Belgium |
| Gocar.be |
| Cardoen |
| Arval Belgium |
| LeasePlan Belgium |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum commodity benchmarks cascade through Belgian used vehicle reconditioning costs, compressing margin pools for independent dealers while manufacturer-certified programs absorb volatility through captive parts networks. This input cost structure stratifies pricing power across warranty-bundled premium tiers and unbundled economy inventory.
Pricing Analysis
Warranty coverage bundling separates manufacturer-certified premium tiers from independent dealer standard inventory. Price differentiation hinges on GOCA inspection certification grade and embedded LEZ compliance documentation, with Brussels buyers least sensitive due to urban access scarcity. Cost compression in the 7-10 year diesel segment intensifies as Euro 5 phase-out timelines harden, while Flemish corporate procurement shows lowest price sensitivity for hybrid powertrains with verified service records.
Supply Chain Analysis
Direct-to-consumer online channels handle fleet-originated volume bypassing traditional auction layers. Geographic supply concentration centers on Belgium, the Netherlands, and Germany for near-new corporate lease returns. Battery and semiconductor component dependencies from Asian manufacturing clusters create single-source vulnerability for electric vehicle refurbishment. Distribution runs through Antwerp port logistics corridors into Flanders-based reconditioning facilities serving Brussels and Wallonia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Belgium Used Car Market functions as a cost-of-compliance arena where GOCA inspection standards and divergent regional LEZ frameworks erect regulatory moats favoring centralized remarketing operators with embedded documentation capabilities.
For Market Incumbents: Deploy blockchain-based vehicle history verification to defend against information asymmetry erosion from digital-native entrants. Consolidate procurement relationships with Arval Belgium and LeasePlan Belgium to lock fleet-originated supply flows. Prioritize backward integration into Antwerp port reconditioning infrastructure to control throughput costs against margin compression. For New Entrants and Emerging Players: Embedded compliance-as-a-service technology offers white-space penetration against legacy dealer documentation gaps. Target Wallonia's dispersed geography where physical inspection requirements sustain independent operator relevance. Pursue subscription-to-ownership pathway models to acquire customers ahead of purchase conversion. For Investors and Strategic Acquirers: The window for entry favors digital remarketing platforms with LEZ certification bundling capabilities. Long-term viability rests on federal-regional regulatory convergence arbitrage rather than pure volume scale. Monitor Brussels Environment administration timeline announcements for diesel phase-out acceleration as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| LEZ Compliance Documentation Bundling | Embedded certification services differentiate platforms as Brussels tightens urban access standards. |
| Fleet Supply Agreement Consolidation | Direct procurement relationships with leasing operators secure premium inventory flows bypassing auction layers. |
| Blockchain Vehicle History Verification | Distributed ledger transparency compresses due diligence timelines for remote Flemish digital transactions. |
| Antwerp Port Reconditioning Integration | Upstream control over customs and GOCA coordination reduces documentation bottlenecks for cross-border remarketing. |
| Subscription-to-Ownership Pathway Launch | Short-term mobility customer acquisition funnels convert to used vehicle purchase in dense Brussels districts. |
Research Methodology
Independent corroboration across fleet operator procurement directors, GOCA inspection station managers, and digital platform operations executives underwrites the qualitative findings. Secondary validation draws from federal Vehicle Inspection Service regulatory filings, regional environmental agency LEZ implementation schedules, and corporate leasing contract disclosure patterns. Bottom-up trade volume estimates triangulate against top-down macroeconomic vehicle stock data.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon. Segmentation modeling incorporates vehicle age bracket, fuel type compliance tier, body format preference, and regional LEZ restriction intensity. CAGRs derive from fleet renewal cycle compression analysis and electrification substitution elasticity. Forecast inputs include corporate lease contract maturity profiles and Euro emission standard phase-out schedules.
Several conditions sit outside the modeled scope, including abrupt federal tax treatment revisions for used electric vehicles and unilateral LEZ timeline acceleration by individual regional administrations. Forecasts reflect assumptions about regulatory coordination stability and logistics cost normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Japan Used Car Market