
 Japan Used Car Market | 2026-2036
Japan Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Used Car Market Outlook
The capital-intensity divergence between auction-based wholesalers and digital exporters is unwinding competitive dynamics across the Japanese secondhand vehicle trade. USS anchors the physical auction layer with proprietary inspection halls in Yokohama and Nagoya, sustaining volume throughput that smaller platforms cannot replicate. Be Forward leverages direct container-shipping logistics to dominate East African and Caribbean export corridors, while SBT Japan competes through multilingual digital storefronts that bypass traditional dealership networks entirely.
A used car in Japan denotes a previously registered vehicle that has undergone the country's mandatory shaken inspection, a biennial roadworthiness examination covering emissions, brakes, and structural integrity. The primary commercial purpose centers on extending vehicle utility through auction-mediated redistribution to domestic buyers and export markets requiring right-hand-drive compatibility. Sedan and hybrid powertrain segments command structural premium positions, as aging corporate fleets and taxi operators rotate gasoline units toward Southeast Asian destinations. Online platforms represent the fastest-growing sales channel, though dealerships retain margin concentration through certified pre-owned programs backed by manufacturer warranty extensions.
METI enforces fuel economy benchmarks that compress residual values for non-compliant engine types, while the Japan Automobile Standards Internationalization Center administers export certification protocols that determine market access eligibility. JIS inspection standards for odometer verification and accident history disclosure shape buyer trust mechanisms across both domestic and cross-border transactions. Stakeholders must monitor regulatory adjustments to shaken fee structures and hybrid battery end-of-life protocols as these will determine which vehicle cohorts retain liquidity in the secondary market.
Market Dynamics
METI's tightening fuel economy benchmarks are compressing residual values for non-compliant gasoline vehicles while accelerating rotation toward hybrid powertrains across corporate fleet portfolios. This regulatory pressure is restructuring auction flows and export corridor destinations simultaneously.
Growth Catalysts
- Corporate Fleet Electrification Mandates:Sustainability targets from Tokyo and Osaka-based operators are expanding procurement volumes for certified pre-owned hybrid sedans. These buyers prioritize auction-grade inspection documentation over price minimization.
- East African Export Demand:Right-hand-drive compatibility requirements in Kenya, Tanzania, and Uganda are sustaining premium pricing for Japanese auction-sourced vehicles. Container logistics integration enables direct port-to-dealer delivery.
- Shaken Inspection Standardization:JIS odometer verification and accident history disclosure protocols are building cross-border buyer trust mechanisms. This transparency infrastructure reduces transaction friction in digital export channels.
Market Restraints
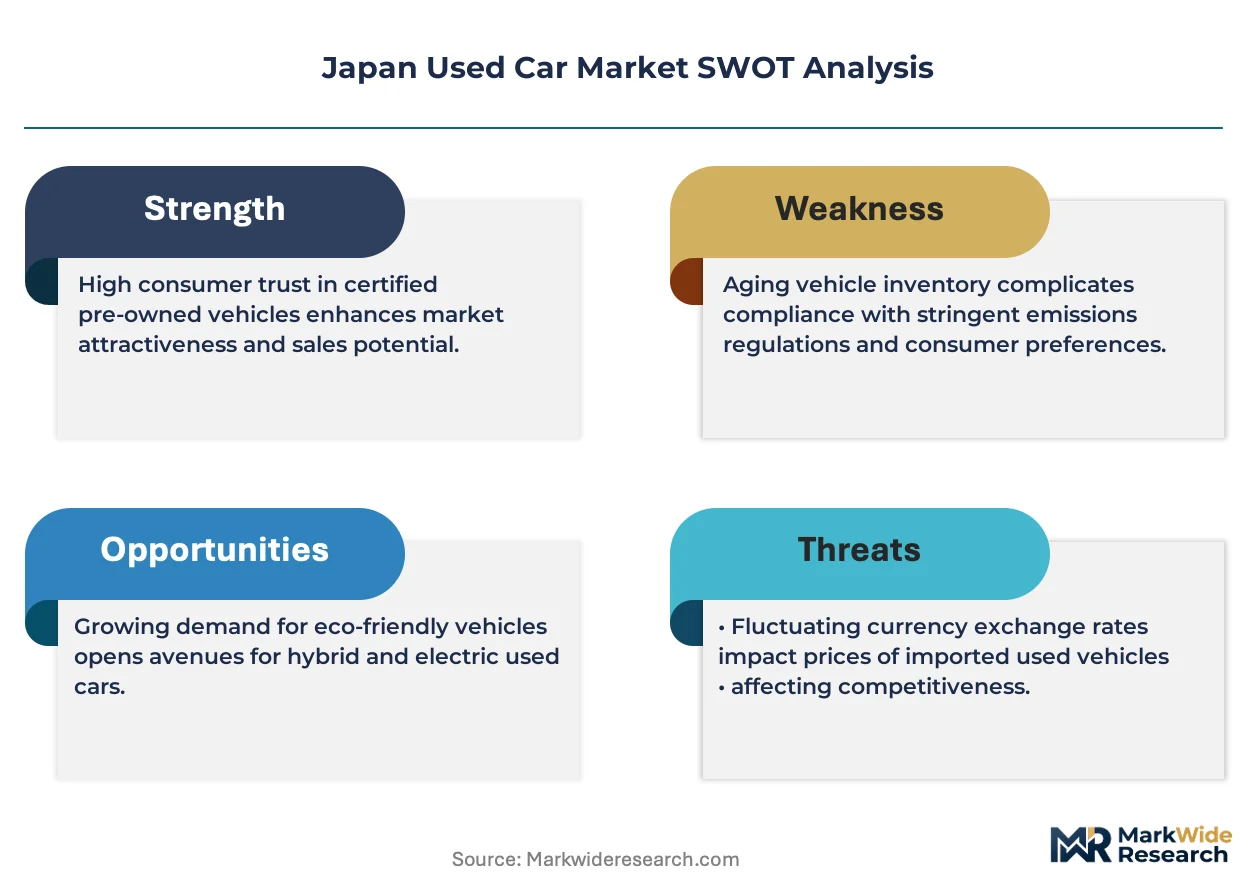
- Hybrid Battery Replacement Cost Volatility:Lithium-ion cell prices and rare earth supply concentration create residual value uncertainty for aging hybrid units approaching second ownership cycles.
- Auction Infrastructure Concentration:Physical inspection hall capacity clusters in Yokohama and Nagoya corridors, limiting price discovery efficiency for rural-sourced inventory and peripheral prefecture sellers.
- Gasoline Depreciation Acceleration:METI fuel efficiency benchmarks penalize older internal combustion engines, forcing faster write-downs that compress wholesale margins for non-hybrid inventory.
Strategic Opportunities
- Caribbean Island Markets:Smaller right-hand-drive territories with limited new vehicle access represent underpenetrated export destinations beyond dominant East African corridors.
- Digital Auction Platform Convergence:Integration of real-time bidding systems with container-shipping logistics APIs enables end-to-end transaction completion without physical dealership intermediation.
- Battery End-of-Life Regulatory Tailwinds:Anticipated METI protocols for hybrid battery recycling and second-life applications will create certified refurbishment revenue streams for specialized reconditioners.
Industry Challenges
- Certified Inspector Talent Scarcity:JIS-accredited shaken examination requires specialized technical training that auction operators struggle to scale across regional inspection halls.
- Multilingual Documentation Complexity:Export certification protocols demand accurate translation across Arabic, Swahili, and Spanish variants, creating compliance timeline delays and customs clearance friction.
- Legacy Dealer Network Disintermediation Resistance:Established physical retailers are deploying warranty extension bundling to defend margin positions against direct-to-buyer digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Used Car Market |
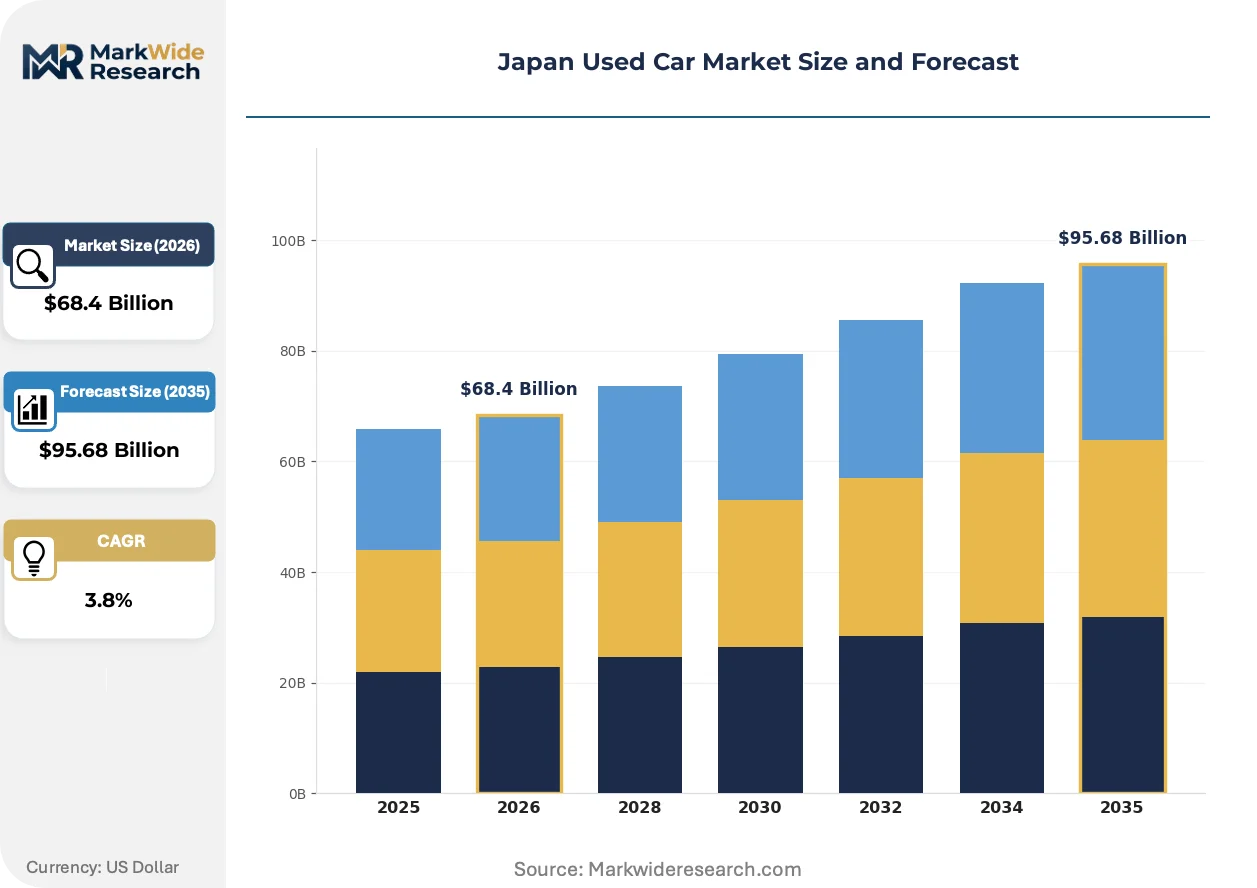
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $95.68 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Engine Type: Gasoline, Diesel, Electric, Hybrid Condition: Like New, Used, Certified Pre-Owned, Salvage Sales Channel: Dealerships, Private Sellers, Auctions, Online Platforms |
| Companies Covered | ATC Japan, Car From Japan, USS, Tokyo Carz, Japan Partner, Be Forward, JuNKaiMa, Autocom Japan, SBT Japan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Used Car Market Strategic Shifts
Digital infrastructure is restructuring how Japanese used vehicles reach end-buyers, with platform-based transaction completion replacing traditional auction-dealer-export hierarchies. Three developments are compressing legacy intermediation layers.
Blockchain-based odometer verification is supplanting paper-based shaken documentation for cross-border transactions. East African import authorities are piloting distributed ledger integration to authenticate Japanese auction records. This technology is enabling direct container-shipping contracts between auction houses and destination-country dealers, bypassing traditional export agency markups.
METI's phased fuel economy benchmarks are forcing accelerated retirement of gasoline-powered corporate fleet vehicles. Taxi operators in Tokyo must rotate non-compliant sedans toward export markets before residual values collapse. Southeast Asian buyers are absorbing this inventory flow despite higher per-unit shipping costs relative to hybrid alternatives.
Container-sharing logistics platforms are fragmenting procurement patterns among smaller Caribbean and Pacific island importers. Individual buyers now aggregate fractional container space through digital freight marketplaces rather than purchasing through consolidated dealer shipments. Kenya and Tanzania remain the dominant volume corridors, but emerging demand from Samoa and Fiji is visible in port throughput data.
Japan Used Car Market Segmentation
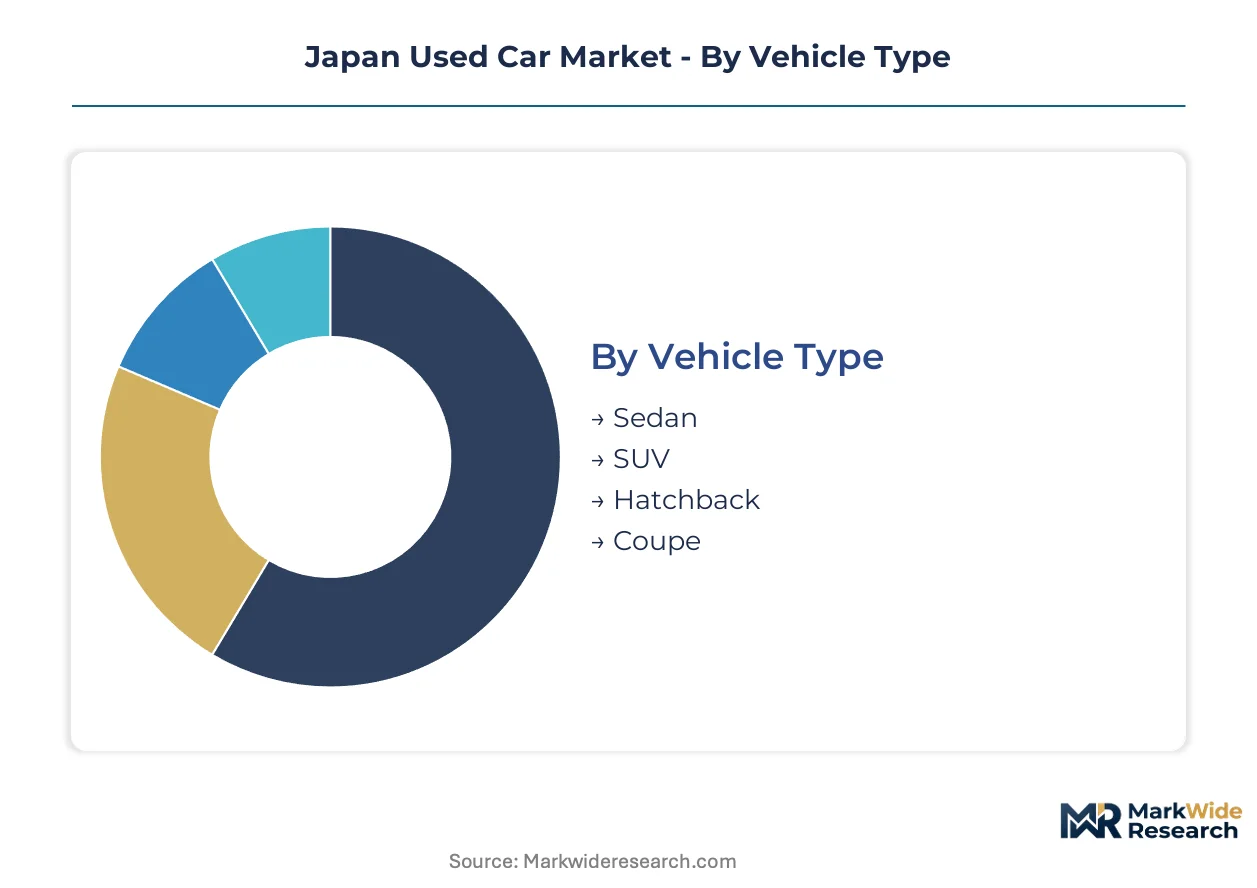
Segmentation in the Japanese used car trade reveals how auction infrastructure, export corridor requirements, and shaken certification tiers concentrate margin capture. Understanding these divisions clarifies which vehicle cohorts retain liquidity under METI's tightening fuel economy mandates.
Vehicle Type:
Sedans command the deepest margin pools within this category, driven by corporate fleet rotation and taxi operator replacement cycles in Tokyo and Osaka.
- Sedan:Three-box configurations dominate auction volume through USS Yokohama and Nagoya halls. Corporate sustainability mandates from Kanto-based fleet operators are accelerating hybrid sedan procurement, with auction-grade inspection documentation commanding price premiums over private-sale alternatives.
- SUV:Higher ground-clearance platforms attract rural prefecture buyers and East African export destinations requiring durability on unpaved infrastructure. Kenyan and Tanzanian import regulations favor these units for commercial passenger transport despite elevated per-unit shipping costs.
- Hatchback:Compact two-box designs concentrate in urban Kanto commuter markets. Kei-class derivatives face compressed residual values as METI fuel efficiency benchmarks penalize older gasoline powertrains.
- Coupe:Two-door specialty configurations occupy niche auction slots with limited export corridor viability. Domestic enthusiast collectors sustain thin liquidity pools outside certified pre-owned dealership networks.
Sedan holds installed capacity. SUV is rotating up the share rankings.
Engine Type:
Powertrain segmentation determines depreciation velocity under METI guidance, with hybrid units retaining structural premium positions against accelerating gasoline write-downs.
- Hybrid:Dual-mode gasoline-electric systems command auction price premiums from corporate buyers prioritizing shaken compliance. Battery end-of-life uncertainty creates residual value volatility for units approaching second ownership cycles.
- Gasoline:Internal combustion engines face compressed wholesale margins as fuel efficiency benchmarks force faster fleet rotation. Southeast Asian buyers absorb this inventory flow despite higher depreciation rates relative to hybrid alternatives.
- Electric:Battery-electric platforms remain thinly traded in secondary markets due to charging infrastructure gaps and range anxiety among domestic buyers. Limited auction volume constrains price discovery mechanisms.
- Diesel:Compression-ignition engines occupy narrow commercial vehicle niches with minimal passenger car penetration. Stricter emissions protocols in destination export markets limit corridor viability beyond specific industrial applications.
Hybrid maintains pricing power. Electric is climbing the fastest as OEM fleet mandates expand supply.
Condition:
Certification tier directly maps to buyer trust infrastructure, with JIS-accredited inspection documentation unlocking cross-border transaction completion.
- Certified Pre-Owned:Manufacturer-backed warranty extensions defend dealership margin positions against digital platform disintermediation. Tokyo and Osaka operators prioritize these units for fleet procurement under sustainability compliance requirements.
- Like New:Low-mileage recent model years with minimal ownership history concentrate in premium auction lanes. Corporate lease returns supply this tier through USS proprietary inspection halls.
- Used:Standard secondary market vehicles with complete shaken documentation form the volume base for East African export corridors. JIS odometer verification protocols reduce transaction friction in direct container-shipping arrangements.
- Salvage:Structural damage or accident-history units face restricted domestic registration options. Parts harvesting and specialist reconditioning operations absorb limited volumes before export certification barriers.
Certified Pre-Owned captures margin concentration. Like New is gaining share fastest as lease return volumes expand.
Sales Channel:
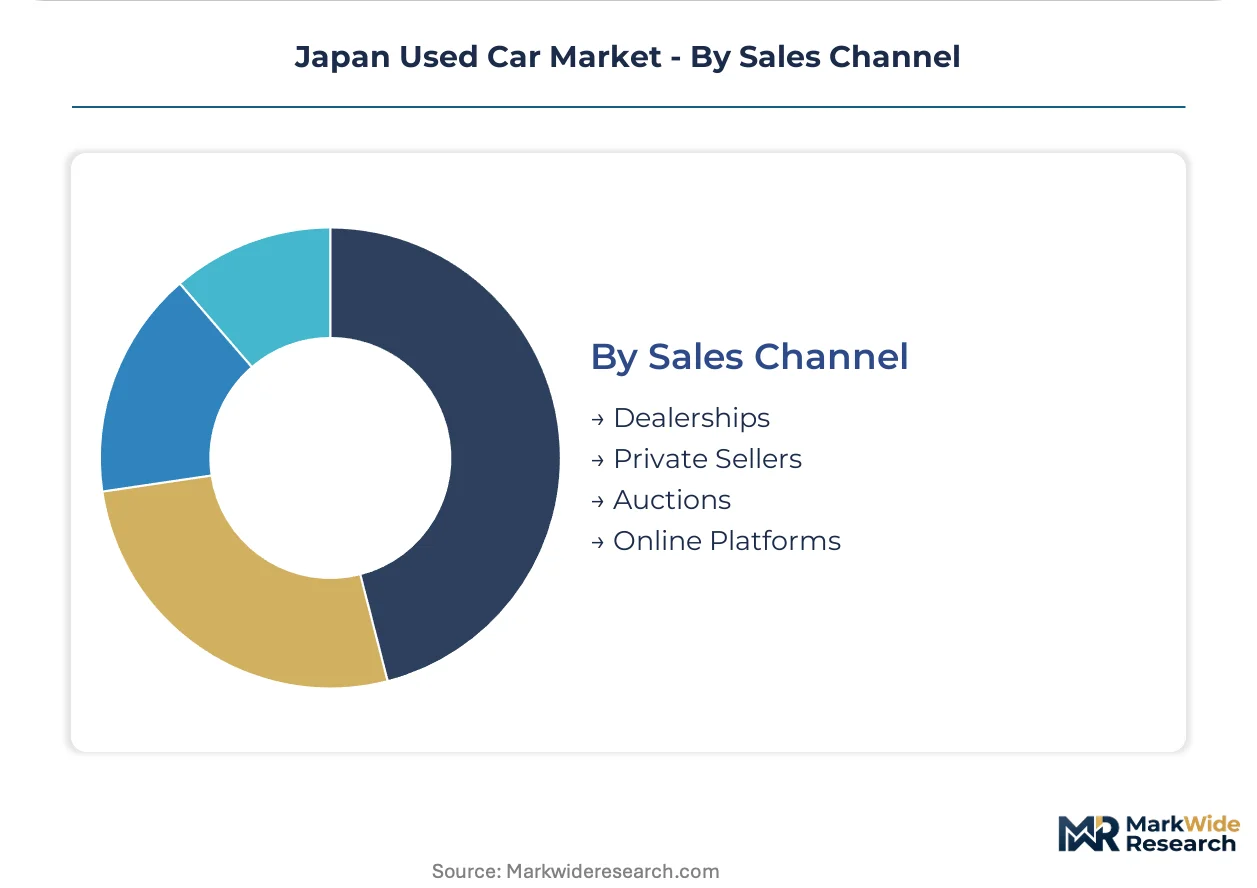
Channel segmentation tracks the unwinding of traditional auction-dealer hierarchies as digital infrastructure enables direct export transaction completion.
- Auctions:Physical inspection hall infrastructure anchors price discovery, with USS Yokohama and Nagoya sustaining throughput volumes smaller platforms cannot replicate. Real-time bidding systems are integrating with container-shipping logistics APIs.
- Online Platforms:Multilingual digital storefronts bypass traditional dealership networks entirely, expanding fastest among East African and Caribbean export buyers. Blockchain-based odometer verification is supplanting paper shaken documentation.
- Dealerships:Physical retailers retain margin concentration through warranty extension bundling and certified pre-owned programs. Legacy networks deploy service bundling to defend positions against direct-to-buyer digital channels.
- Private Sellers:Individual transaction volume concentrates in rural prefectures lacking auction infrastructure access. Price discovery inefficiencies and documentation gaps limit cross-border export viability.
Auctions hold physical infrastructure dominance. Online Platforms is expanding most quickly as container logistics digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export buyers in East African corridors demonstrate high price elasticity, absorbing accelerated depreciation of gasoline units. Caribbean island territories exhibit lower sensitivity, prioritizing right-hand-drive compatibility over acquisition cost. Domestic fleet operators in Tokyo and Osaka show the least elasticity, paying premiums for hybrid sedans with certified inspection documentation.
Kanto/Tokyo
Corporate fleet electrification mandates from Tokyo-based operators are expanding certified pre-owned hybrid procurement. METI fuel efficiency benchmarks under the Energy Conservation Act compress residual values for non-compliant gasoline vehicles. USS Yokohama inspection halls anchor auction throughput, with real-time bidding systems integrating container-shipping logistics for direct export completion.
Kansai/Osaka
Sustainability compliance requirements from Osaka-headquartered logistics operators are accelerating sedan rotation toward hybrid powertrains. The Osaka Prefecture green procurement guidelines tighten emission thresholds for fleet registration renewal. Port infrastructure at Osaka and Kobe sustains bulk container consolidation for East African export corridors.
Chubu/Nagoya
Automotive supplier cluster proximity enables rapid parts availability for reconditioning operations serving export markets. Aichi Prefecture industrial standards align with JIS certification protocols for odometer verification and accident history disclosure. Nagoya inspection halls process volume from central Japan prefectures lacking independent auction infrastructure.
Kyushu
Rural prefecture sellers face price discovery inefficiencies due to distance from concentrated inspection hall capacity. Fukuoka port authorities are piloting direct container-shipping contracts with Caribbean destination dealers. Local inventory concentrates in hatchback and kei-class segments penalized by METI fuel economy benchmarks.
Hokkaido
Severe winter operating conditions sustain demand for SUV platforms with all-wheel-drive capability. Sapporo-based dealers rely on digital platforms to access auction liquidity concentrated in southern corridors. Export viability remains limited by shipping distance to major container consolidation points.
Japan Used Car Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Japanese secondhand vehicle trade. Physical auction infrastructure operators sustain volume throughput that digital platforms cannot replicate at scale. Three archetypes dominate: inspection-hall anchors with proprietary logistics, direct-to-export digital storefronts with multilingual capabilities, and hybrid platform operators integrating bidding systems with container freight APIs. Competitive moves concentrate on API integration partnerships and certified inspector talent acquisition.
Among auction-based operators, USS anchors physical infrastructure with proprietary inspection capacity. Be Forward and SBT Japan occupy positions within the digital export tier, leveraging direct container-shipping logistics and multilingual storefronts respectively to bypass traditional dealership intermediation. These three exemplify how capital-intensity divergence between physical and digital channels is restructuring competitive dynamics across domestic and cross-border transaction completion.
| Leading Market Players |
|---|
| ATC Japan |
| Car From Japan |
| USS |
| Tokyo Carz |
| Japan Partner |
| Be Forward |
| JuNKaiMa |
| Autocom Japan |
| SBT Japan |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day container consolidation cycles at Yokohama and Nagoya anchor pricing power for auction-grade inventory, compressing margin capture for rural prefecture sellers lacking direct port access. This lead-time stratification concentrates hybrid sedan premiums in Kanto corridor transactions while accelerating gasoline depreciation for distant sellers.
Pricing Analysis
Extended warranty and battery refurbishment service contracts drive lifetime value for certified pre-owned units. Three-tier pricing structure across certified pre-owned, auction-grade, and private-sale tiers separates buyers by documentation requirements and after-sales bundling. Pricing pressure stems from METI fuel efficiency benchmarks forcing faster gasoline write-downs. East African export buyers demonstrate highest price sensitivity, absorbing depreciation-accelerated gasoline inventory; Tokyo fleet operators show lowest sensitivity, paying premiums for hybrid sedans with JIS-accredited shaken documentation.
Supply Chain Analysis
Container capacity chokepoints at Yokohama and Nagoya underwrite auction infrastructure concentration, limiting price discovery for peripheral prefecture inventory. Vehicle sourcing draws from Tokyo-Osaka corporate fleet rotation, rural prefecture private sales, and lease return channels. Single-source vulnerability rests on USS inspection hall dominance in physical certification. Distribution runs through auction-to-dealer hierarchies, with digital platforms fragmenting direct export completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where API-integrated bidding and container logistics APIs are collapsing traditional auction-dealer-export hierarchies into end-to-end digital completion.
For Market Incumbents: Shield auction-grade certification authority by embedding blockchain-based odometer verification into shaken documentation workflows. Deepen proprietary inspector talent pipelines through JIS-accredited training partnerships before digital platforms replicate remote inspection protocols. Threat: Direct-to-buyer digital exporters bypassing dealership intermediation entirely. For New Entrants and Emerging Players: Differentiate on multilingual documentation automation for Caribbean and Pacific island corridors underserved by incumbent East African focus. Target fractional container-sharing logistics for individual buyers in Samoa, Fiji, and smaller right-hand-drive territories. Go-to-market: API integration with freight marketplaces enabling port-to-dealer delivery without consolidated dealer shipments. For Investors and Strategic Acquirers: Long-term, this sits as a logistics-technology play because container-shipping digitization and inspection automation will determine which platforms capture margin compression from disintermediation. Acquisition archetype: Hybrid platform operators with proprietary bidding systems and freight API partnerships. Signal to watch: METI protocols for hybrid battery recycling certification creating second-life refurbishment revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Odometer Verification Integration | East African import authorities pilot distributed ledger authentication, reducing transaction friction for direct auction-to-dealer contracts. |
| Container-Shipping Logistics API Partnership | Real-time bidding systems connecting with freight marketplaces enable end-to-end transaction completion without physical dealership intermediation. |
| JIS-Accredited Inspector Training Scale-Up | Certified talent scarcity constrains auction operator expansion into regional inspection halls beyond Yokohama and Nagoya corridors. |
| Hybrid Battery Refurbishment Certification | Anticipated METI recycling protocols will create certified second-life revenue streams for specialized reconditioners. |
| Multilingual Documentation Automation | Accurate translation across Arabic, Swahili, and Spanish variants reduces customs clearance delays in export certification workflows. |
Study Parameters
A standing panel of auction operations directors, container logistics coordinators, export dealership principals, and METI regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from vehicle registration databases, port throughput statistics, JIS certification records, and customs export documentation. Bottom-up volume modeling triangulated with top-down market sizing across the Japanese secondhand vehicle trade.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework segmented by vehicle type, powertrain architecture, certification tier, and sales channel, with hybrid battery end-of-life protocols and shaken fee structure adjustments as industry-specific forecast inputs. CAGRs derived from regression analysis of historical auction volume and export corridor flow data.
The analysis sits within stated boundaries; outcomes outside METI fuel efficiency benchmark trajectories or hybrid battery recycling protocol timelines would require recalibration. Practitioners should keep alternative scenarios live as East African import regulation shifts and Caribbean market penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Used E-Scooter Market
Used Vehicles
North America Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
France Used Car Market