
 Switzerland Used Car Market | 2026-2036
Switzerland Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Used Car Market Insights
Swiss automotive dealerships is recalibrating inventory strategies around electrified pre-owned stock. Emil Frey AG leverages its nationwide showroom network to dominate certified pre-owned volume. AutoScout24 AG anchors digital discovery for used vehicle transactions across German-speaking cantons. AMAG Automobil und Motoren AG competes through manufacturer-backed warranty programs on second-hand imports.
A used car denotes a previously registered passenger vehicle resold through formal or informal channels, typically assessed via odometer reading, service history verification, and structural integrity inspection before re-entry to commerce. Its primary purpose is to extend vehicle utility life while lowering capital outlay for subsequent owners. SUV and sedan listings still occupy the largest share of Swiss resale volume, though electric and hybrid fuel types are gaining fastest as charging infrastructure expands. Online marketplaces now capture margin pools that once accrued solely to physical dealerships, while certified pre-owned programs extract premium pricing through inspection standardization.
Swissmedic does not regulate vehicles directly, but the Federal Roads Office (FEDRO) enforces periodic motor vehicle inspection requirements that shape roadworthiness standards for used car eligibility. The Swiss Federal Council's CO2 ordinance imposes fleet emission targets that push dealers toward cleaner pre-owned inventory. The EU Green Deal's cross-border influence filters into Swiss import regulations through bilateral agreements. Stakeholders must monitor how FEDRO inspection digitization and evolving carbon pricing affect residual value forecasting for internal combustion models.
Market Dynamics
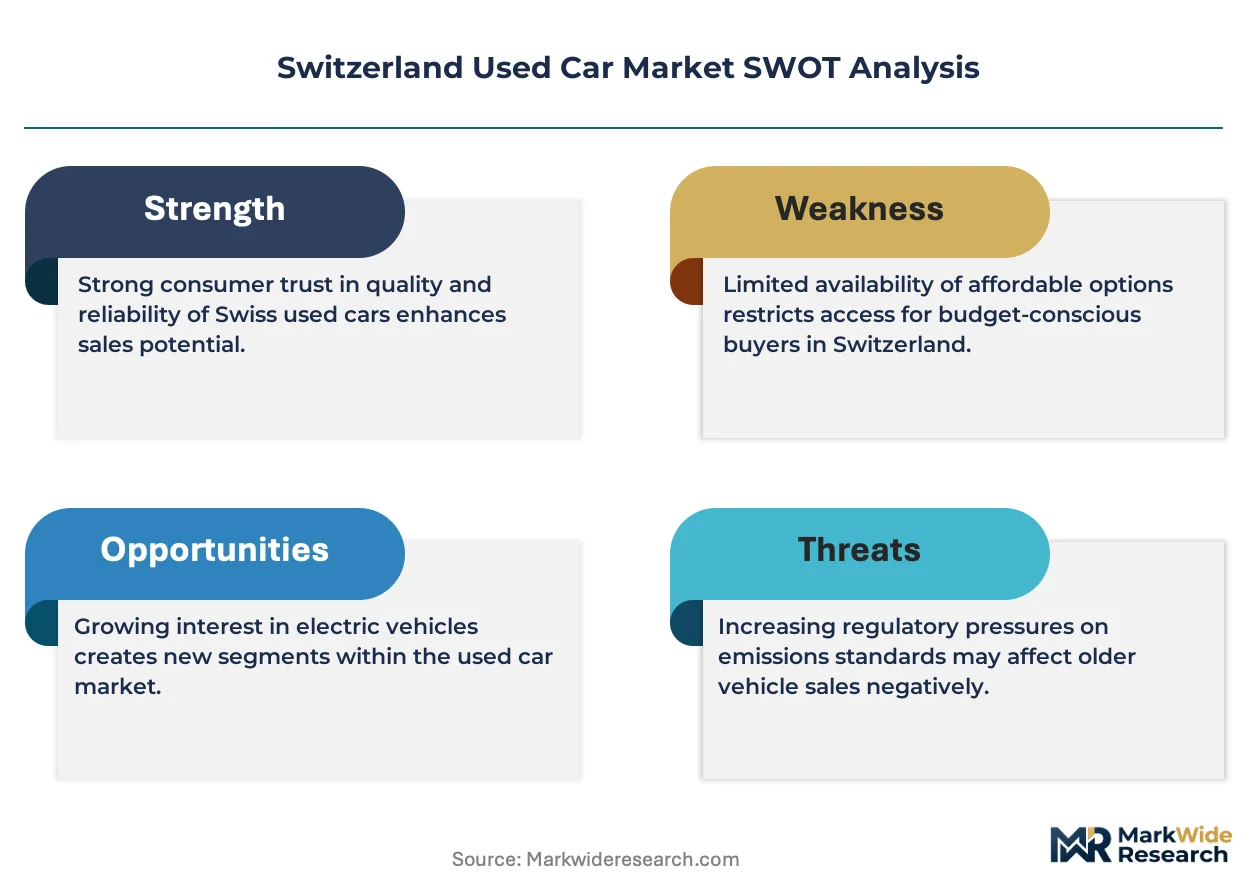
The Swiss used car market pivots on regulatory pressure from the Federal Council's CO2 ordinance, which compresses residual values for combustion-engine inventory while elevating demand for electrified pre-owned stock. Dealers recalibrate procurement toward battery-electric and hybrid vehicles as emission thresholds tighten across cantonal vehicle registration systems.
Growth Catalysts
- FEDRO inspection digitization:The Federal Roads Office accelerates vehicle history verification through digital inspection records, reducing transaction friction for certified pre-owned programs and expanding buyer confidence in secondary markets.
- Urban canton electrification:Zurich and Geneva concentrate charging infrastructure deployment, enabling private buyers to operationalize used electric vehicles without range anxiety constraints.
- EU Green Deal bilateral influence:Cross-border import regulations align Swiss dealer sourcing with cleaner European fleet rotations, expanding available supply of low-emission pre-owned inventory.
Market Restraints
- Lithium-ion battery degradation uncertainty:Buyers lack standardized tools to assess remaining battery capacity in used electric vehicles, depressing price realization for older electrified stock.
- Cantonal registration tax fragmentation:Varying CO2-based taxation schemes across 26 cantons create arbitrage complexity that constrains inter-canton price transparency and inventory fluidity.
- Swiss franc currency appreciation:Import-heavy dealer sourcing from eurozone markets faces margin compression when franc strength elevates acquisition costs relative to domestic pricing power.
Strategic Opportunities
- Basel-Stadt hybrid specialization:Rising demand for certified pre-owned hybrid models in this northwestern canton creates whitespace for inspection-standardized inventory programs targeting commuter segments.
- AutoScout24 digital marketplace expansion:Online transaction platforms capture margin pools historically retained by physical dealerships, enabling direct-to-consumer warranty bundling and financing integration.
- AMAG manufacturer-backed warranty extension:Second-hand import certification programs leverage original equipment service networks to extract premium pricing through standardized structural integrity guarantees.
Industry Challenges
- Residual value forecasting complexity:Dealers struggle to model depreciation curves for internal combustion models as FEDRO inspection criteria and carbon pricing evolve unpredictably.
- Service technician electrification training:Maintenance capacity for battery-electric and hybrid powertrains lags sales growth, constraining after-sales revenue capture on electrified pre-owned inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Used Car Market |
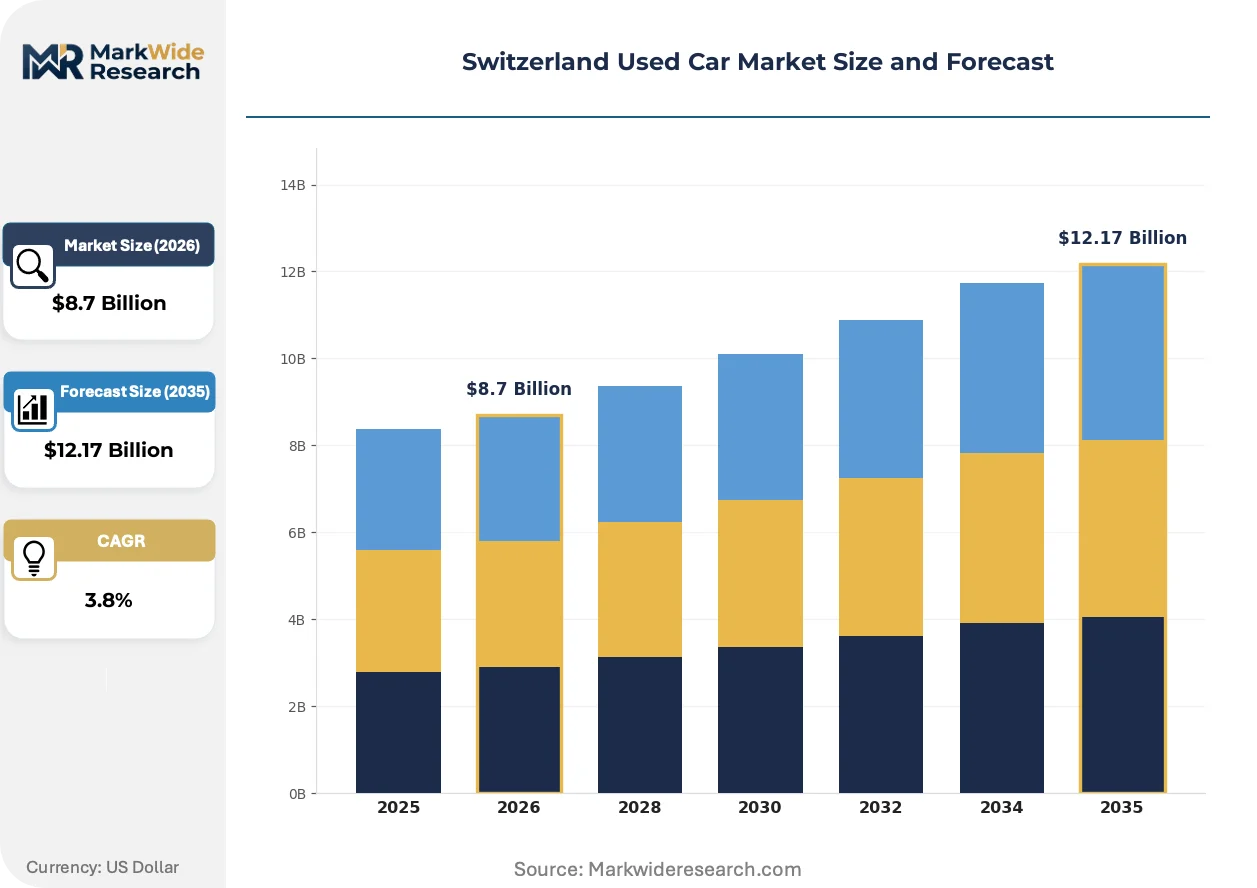
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Coupe, Hatchback Fuel Type: Petrol, Diesel, Electric, Hybrid Condition: New, Like-New, Certified Pre-Owned, Used Sales Channel: Dealerships, Online Marketplaces, Private Sales, Auctions |
| Companies Covered | Carvolution, Auto Kunz AG, Emil Frey AG, Comparis, Auto Lang AG, AMAG Automobil und Motoren AG, CAR FOR YOU AG, Leapmotor, AutoScout24 AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Used Car Market Trends and Innovations
Swiss automotive retail is consolidating around digital transaction infrastructure and electrified inventory sourcing. Technology deployment, regulatory compliance automation, and buyer behavior transformation now determine competitive position.
Telematics-enabled vehicle condition monitoring is consolidating trust formation in remote used car transactions. Swiss buyers in German-speaking cantons now expect real-time battery health data and service history verification before committing to unseen purchases. This capability compression is consolidating market share toward platforms that integrate FEDRO inspection records with predictive maintenance analytics.
The Swiss Federal Council's CO2 ordinance enforcement tightens fleet emission accountability for dealers holding multi-brand inventory. Commercial registrants face escalating penalties for combustion-engine-heavy portfolios, accelerating write-downs of older diesel and gasoline stock. Urban dealerships in Zurich and Geneva respond by prioritizing battery-electric acquisitions from corporate fleet rotations.
Buyer preference is fragmenting across channel type rather than consolidating on single transaction modes. Younger demographics in Basel-Stadt and Lausanne favor fully digital discovery with physical delivery, while older segments in rural cantons retain showroom-dependent evaluation. This bifurcation forces dealers to maintain dual cost structures without full economies of scale in either channel.
Switzerland Used Car Market Segmentation
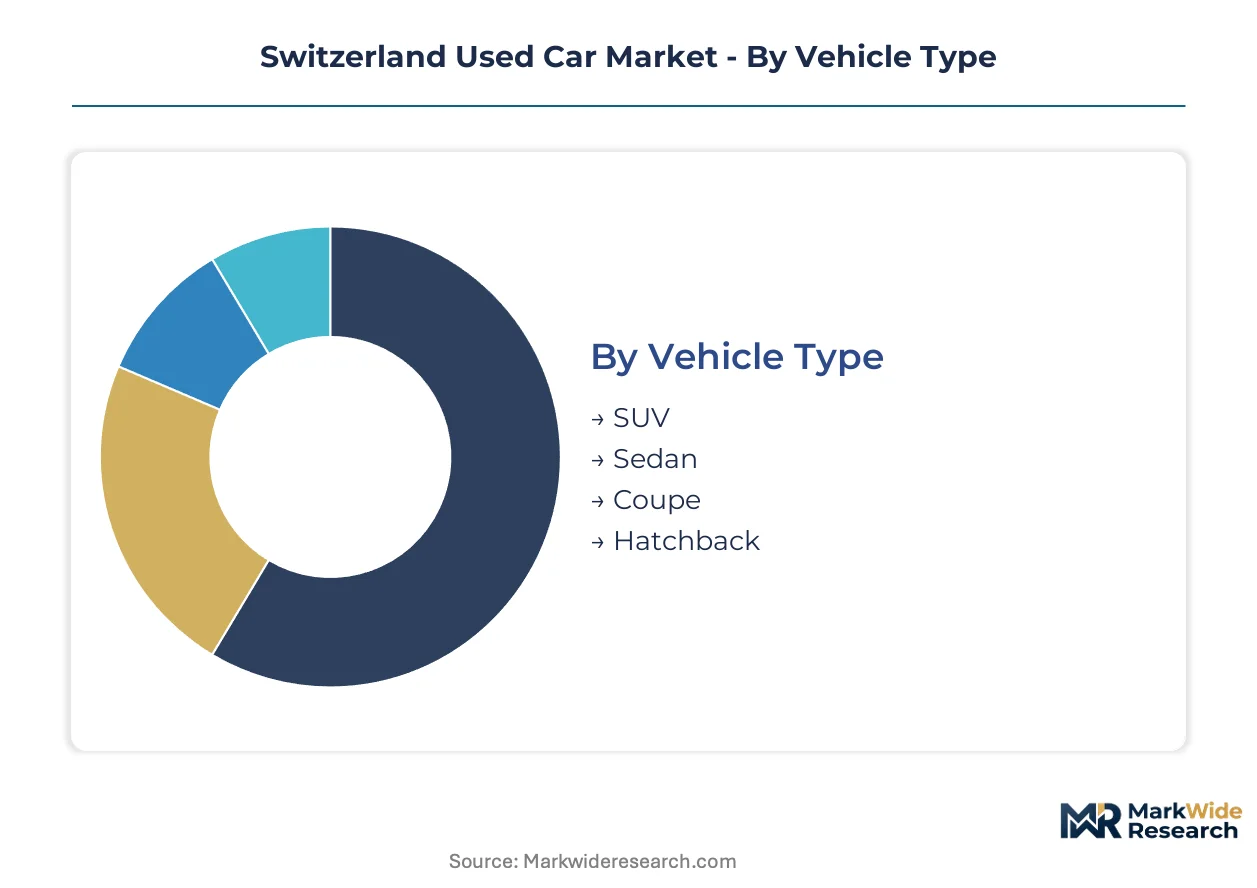
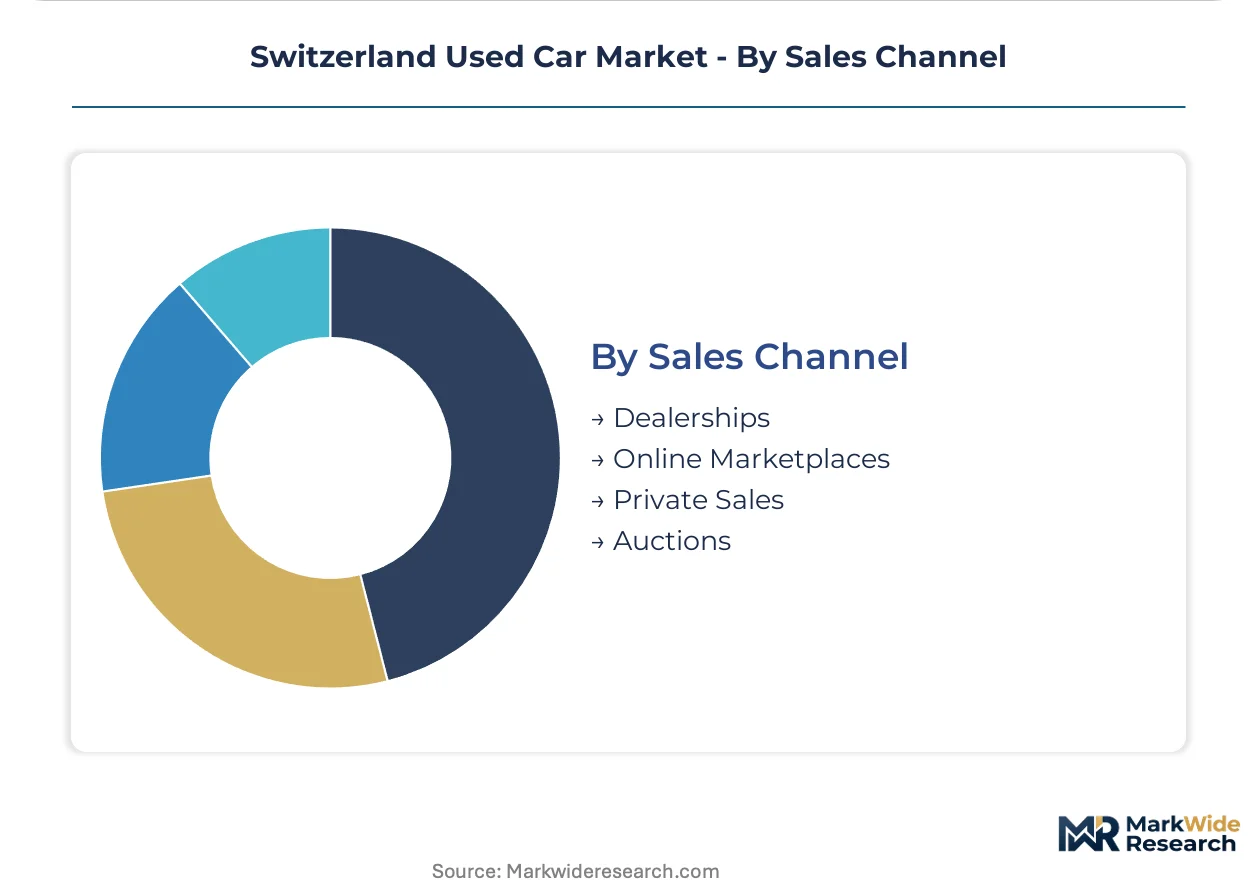
Swiss used car segmentation reveals how regulatory pressure and channel digitization fragment buyer behavior across vehicle categories. Dealers must align inventory procurement with cantonal emission enforcement while capturing margin from emerging transaction platforms.
Vehicle Type:
The customization-vs-standardization spectrum spans from configurable SUV platforms to specification-locked coupe architectures.
- SUV:Higher ground clearance and modular seating configurations dominate family-oriented procurement in Zurich and Geneva cantons. Demand concentrates where FEDRO roadworthiness standards favor vehicles with enhanced structural integrity ratings for alpine terrain navigation.
- Sedan:Three-box body styles with fixed rooflines and separated cargo compartments retain preference among corporate fleet rotations. Basel-Stadt commuter corridors drive volume for mid-size executive sedans with hybrid powertrain compatibility.
- Coupe:Two-door fixed-roof configurations with sport-tuned suspensions appeal to discretionary buyers seeking driving dynamics over utility.
- Hatchback:Compact two-box designs with integrated cargo access suit urban parking constraints in dense Geneva and Lausanne districts.
Leading the category by volume: SUV. Growing fastest: Hatchback configurations in electrified variants.
Fuel Type:
Cost tier stratification separates premium electrified acquisitions from depreciation-pressured combustion inventory.
- Electric:Battery-electric powertrains with zero tailpipe emissions command residual value premiums in Zurich canton where charging density enables operational viability. Geneva buyers operationalize these vehicles through corporate sustainability mandates that offset acquisition premiums against CO2 tax avoidance.
- Hybrid:Dual powertrain architectures combining internal combustion with electric assist dominate Basel-Stadt demand where moderate-range electric operation satisfies commuter patterns without full infrastructure dependency.
- Petrol:Spark-ignition engines face accelerating residual value compression as FEDRO inspection criteria tighten emission thresholds.
- Diesel:Compression-ignition powertrains encounter cantonal registration restrictions that constrain liquidity in secondary markets.
Volume leadership: Hybrid configurations bridging infrastructure gaps. Steepest expansion trajectory: Battery-electric as charging networks mature.
Condition:
Application intensity separates warranty-backed commercial transactions from informal private transfers.
- Certified Pre-Owned:Dealer-inspected vehicles with standardized structural integrity verification and extended warranty coverage extract pricing premiums from risk-averse buyers. Zurich dealerships leverage manufacturer service networks to bundle financing with condition guarantees.
- Used:As-is transactions without formal inspection documentation dominate price-sensitive segments in rural cantons where buyer technical competence substitutes for institutional verification.
- Like-New:Low-mileage recent model year vehicles with minimal wear indicators attract buyers seeking new-vehicle aesthetics without depreciation absorption.
- New:Zero-mile unregistered inventory occupies the boundary of used market definition, typically comprising dealer demonstrator units or canceled orders.
Margin concentration: Certified Pre-Owned programs. Fastest channel shift: Like-New inventory from corporate fleet rotations.
Sales Channel:
Customer type bifurcation splits between digitally native discovery and showroom-dependent evaluation.
- Online Marketplaces:Digital transaction platforms with integrated FEDRO record verification and predictive maintenance analytics consolidate share among German-speaking canton buyers. AutoScout24 anchors discovery for younger demographics seeking remote transaction completion with physical delivery.
- Dealerships:Physical showroom networks with manufacturer-backed warranty programs retain older segment loyalty in rural areas where tactile evaluation precedes commitment.
- Private Sales:Direct owner-to-buyer transfers without intermediary margin extraction persist where social trust networks substitute for institutional verification.
- Auctions:Wholesale disposal channels for fleet operators and lease termination inventory supply dealer procurement pipelines.
Transaction volume leader: Dealership networks. Fastest share gain: Online Marketplaces with telematics integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss automotive commerce concentrates where alpine transit corridors intersect with metropolitan purchasing power. The country's 26 cantons fragment regulatory enforcement while federal standards unify minimum roadworthiness thresholds.
Zurich
Corporate fleet rotations and dense charging infrastructure drive battery-electric pre-owned transactions. The Federal Roads Office digitizes inspection records here first, compressing transaction timelines for certified programs. Zurich dealerships extract premium pricing through telematics-verified battery health guarantees.
Geneva
Cross-border commuters from France and Italy sustain demand for compact electrified hatchbacks. Cantonal CO2-based registration taxes favor zero-emission acquisitions from EU Green Deal-aligned import channels. Geneva showrooms specialize in low-mileage corporate lease returns with manufacturer warranty extensions.
Basel-Stadt
Pharmaceutical sector employees prioritize plug-in hybrid sedans for Rhine corridor commuting. The canton's moderate-density charging network suits dual-powertrain operational patterns without full infrastructure dependency. Basel dealerships cultivate certified pre-owned hybrid programs targeting this professional demographic.
Bern
Federal administrative employment stabilizes demand for conservative sedan and SUV configurations. FEDRO headquarters proximity accelerates regulatory compliance verification for dealership inventory. Bern's dealer networks emphasize structural integrity documentation for alpine terrain suitability.
Vaud
Lausanne's younger demographic favors digital discovery platforms with physical delivery integration. The canton's university and hospitality sectors generate consistent turnover in compact urban vehicles. Vaud marketplaces capture margin through integrated financing and remote inspection technologies.
Switzerland Used Car Market Competitive Landscape
Global automotive groups compete with regional dealership networks across inventory sourcing and warranty standardization. Market structure tilts toward consolidated multi-brand operators with manufacturer service agreements. Three archetypes dominate: nationwide showroom networks with certified pre-owned programs, digital transaction platforms with telematics integration, and specialized import certification services. Competitive moves concentrate on strategic partnerships for charging infrastructure access and portfolio diversification into electrified stock.
Within the nationwide network tier, Emil Frey AG and AMAG Automobil und Motoren AG exemplify scale-driven operators leveraging manufacturer relationships. AutoScout24 AG occupies a distinct position anchoring digital discovery across German-speaking cantons. These three entities represent the spectrum from physical showroom dominance to platform-mediated transactions, each capturing margin through different verification and trust-formation mechanisms.
| Leading Market Players |
|---|
| Carvolution |
| Auto Kunz AG |
| Emil Frey AG |
| Comparis |
| Auto Lang AG |
| AMAG Automobil und Motoren AG |
| CAR FOR YOU AG |
| Leapmotor |
| AutoScout24 AG |
| Others |
Pricing and Supply Chain Analysis
Cantonal CO2-based registration tax fragmentation forces dealers to recalibrate sourcing strategies around emission-compliant inventory, compressing margins on combustion-engine stock while elevating acquisition premiums for electrified pre-owned vehicles. This demand-side pressure reshapes procurement toward battery-electric and hybrid supply channels from corporate fleet rotations and EU import pipelines.
Pricing Analysis
Warranty bundling separates certified pre-owned premiums from as-is transaction discounts. Three-tier pricing structure across certified, inspected, and unverified condition levels extracts margin through FEDRO inspection documentation and manufacturer-backed service guarantees. Price differentiation hinges on battery health certification and structural integrity verification. Pricing pressure stems from Swiss franc appreciation elevating eurozone import costs. Private buyers in rural cantons exhibit highest price sensitivity; Zurich corporate fleet purchasers show lowest.
Supply Chain Analysis
FEDRO roadworthiness certification gates inventory eligibility before secondary market entry. Supply concentrates in Germany, France, and Italy as primary sourcing markets for low-mileage corporate lease returns. Dealer procurement draws from lithium-ion battery packs, catalytic converters, and telematics hardware as critical component dependencies. Single-source vulnerability runs through German OEM service networks for warranty-backed certification. Distribution runs through multi-brand showroom networks with manufacturer service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swiss used car retail is consolidating around backward integration into charging infrastructure access and telematics-enabled verification capabilities. Players securing upstream control over battery health assessment tools and downstream service network partnerships will capture margin from electrified inventory turnover.
For Market Incumbents: Extend manufacturer-backed warranty programs to cover battery capacity guarantees on electrified pre-owned stock. Deepen service technician training pipelines for hybrid powertrain maintenance to capture after-sales revenue. Defend against digital marketplace encroachment by integrating FEDRO inspection records with real-time telematics verification. For New Entrants and Emerging Players: Digital-native financing platforms offer the most penetrable channel wedge for Basel-Stadt and Vaud commuter segments seeking subscription-based vehicle access. Target plug-in hybrid procurement from pharmaceutical sector fleet rotations. Deploy remote inspection technologies with physical delivery integration to bypass showroom infrastructure costs. For Investors and Strategic Acquirers: The window for entry favors vertically integrated dealership networks with captive service capacity and manufacturer certification rights. Long-term viability centers on electrified inventory turnover velocity rather than transaction volume scale. Watch FEDRO inspection digitization rollout timing as inflection signal for certified pre-owned margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Program | Standardized capacity verification builds buyer confidence in electrified pre-owned transactions. |
| Charging Infrastructure Partnership | Dealer network access to FEDRO-aligned charging corridors enables electric vehicle operational viability. |
| Telematics Integration Platform | Real-time vehicle condition monitoring compresses transaction friction for remote purchases. |
| Service Technician Electrification Training | Maintenance capacity expansion captures after-sales revenue from hybrid and battery-electric inventory. |
| Corporate Fleet Rotation Sourcing Agreement | Direct procurement pipelines from pharmaceutical and banking sectors secure low-mileage hybrid supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dealership operations managers, FEDRO inspection officials, OEM fleet sales directors, and telematics platform engineers combined with Swiss Federal Council CO2 ordinance documentation and vehicle registration databases. Bottom-up transaction volume estimates triangulated against top-down cantonal fleet composition data.
Segmentation-level modeling addressed vehicle type, fuel architecture, condition tier, and sales channel across the analysis window. CAGRs derived from regression analysis of historical transaction volumes against regulatory enforcement timelines and charging infrastructure deployment curves. Forecast inputs incorporated FEDRO inspection digitization rollout schedules and EU Green Deal bilateral agreement implementation.
Caveats apply where FEDRO emission threshold revisions or lithium-ion battery degradation assessment standardization could materially shift the outlook. Forecasts reflect assumptions around cantonal tax harmonization and franc-euro exchange rate stability. A model refresh is warranted upon material change in Federal Council CO2 ordinance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Nigeria Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Netherlands Used Car Market