
 Two Wheeler Tire Market | 2026-2036
Two Wheeler Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Tire Market Analysis
Last-mile delivery fleet operators are broadening the end-use vertical mix for two-wheeler tires beyond traditional personal mobility. Bridgestone Corporation leverages its manufacturing scale across Asian production hubs to serve this expanding commercial segment. MRF Limited anchors its position through deep distribution networks in India's replacement market. Michelin Group differentiates via R&D intensity focused on high-performance radial compounds for premium motorcycles.
Two-wheeler tires are pneumatic or solid elastomer structures mounted on motorcycle, scooter, and moped wheels, typically constructed from layered rubber compounds reinforced with steel or aramid belting to provide traction, load-bearing capacity, and shock absorption across varied road surfaces. Tubeless tire configurations are capturing margin pools as OEM fitment rates rise, while bias ply constructions retain volume dominance in emerging-market replacement cycles. Specialty blends in material segmentation command premium positioning as thermal stability and wet-grip performance become critical purchase criteria for performance-oriented riders.
India's BIS mandates and the EU's REACH chemical restrictions are reshaping compound formulation requirements and cross-border market access conditions for tire manufacturers. The US DOT FMVSS 109 standard governs tire endurance and dimensional stability for imported two-wheeler tires entering North American distribution channels. Stakeholders must monitor evolving labeling and sustainability disclosure frameworks as regulatory convergence between Asian manufacturing bases and Western import jurisdictions accelerates.
Market Dynamics
Tubeless radial configurations are displacing bias-ply constructions across premium motorcycle segments, compressing replacement cycles while elevating thermal performance thresholds for compound formulations.
Growth Catalysts
- Last-mile delivery fleet expansion:E-commerce logistics operators in Indonesia, Vietnam, and India are accelerating commercial two-wheeler utilization rates, driving accelerated tire wear and replacement frequency.
- BIS certification mandates:India's Bureau of Indian Standards labeling and safety requirements are elevating product quality baselines, squeezing substandard imports while rewarding compliant domestic manufacturers.
- Aramid belting adoption:High-performance motorcycles are incorporating aramid-reinforced carcass structures to reduce unsprung mass and improve high-speed stability.
Market Restraints
- Natural rubber price volatility:Southeast Asian rubber supply concentration exposes manufacturers to weather-driven input cost swings and plantation yield fluctuations.
- Steel cord supply concentration:Specialty tire cord manufacturing clusters in China and South Korea create single-source dependency risks for radial construction expansion.
- REACH chemical restrictions:The European Chemicals Agency's substance authorization requirements are constraining traditional plasticizer and accelerator chemistries in export-bound compounds.
Strategic Opportunities
- Electric two-wheeler OEM fitment:Battery-powered motorcycles and scooters present greenfield specification opportunities with distinct load, torque, and noise-dampening requirements versus internal combustion counterparts.
- Rural replacement market penetration:India's tier-3 and tier-4 towns exhibit underdeveloped organized retail tire distribution, creating whitespace for branded network expansion.
- Digital tire monitoring integration:Pressure and temperature sensor embedding is converging with connected vehicle platforms, enabling predictive maintenance service bundling.
Industry Challenges
- Compound formulation talent scarcity:Specialized rubber chemists capable of balancing wet-grip, wear resistance, and rolling efficiency across climate zones command premium compensation and limited availability.
- Homologation timeline compression:India's BIS type-approval testing queues and EU E-mark certification backlogs are extending new product introduction cycles.
- Radial production capex intensity:Greenfield radial tire capacity requires specialized building drum and curing press investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Tire Market |
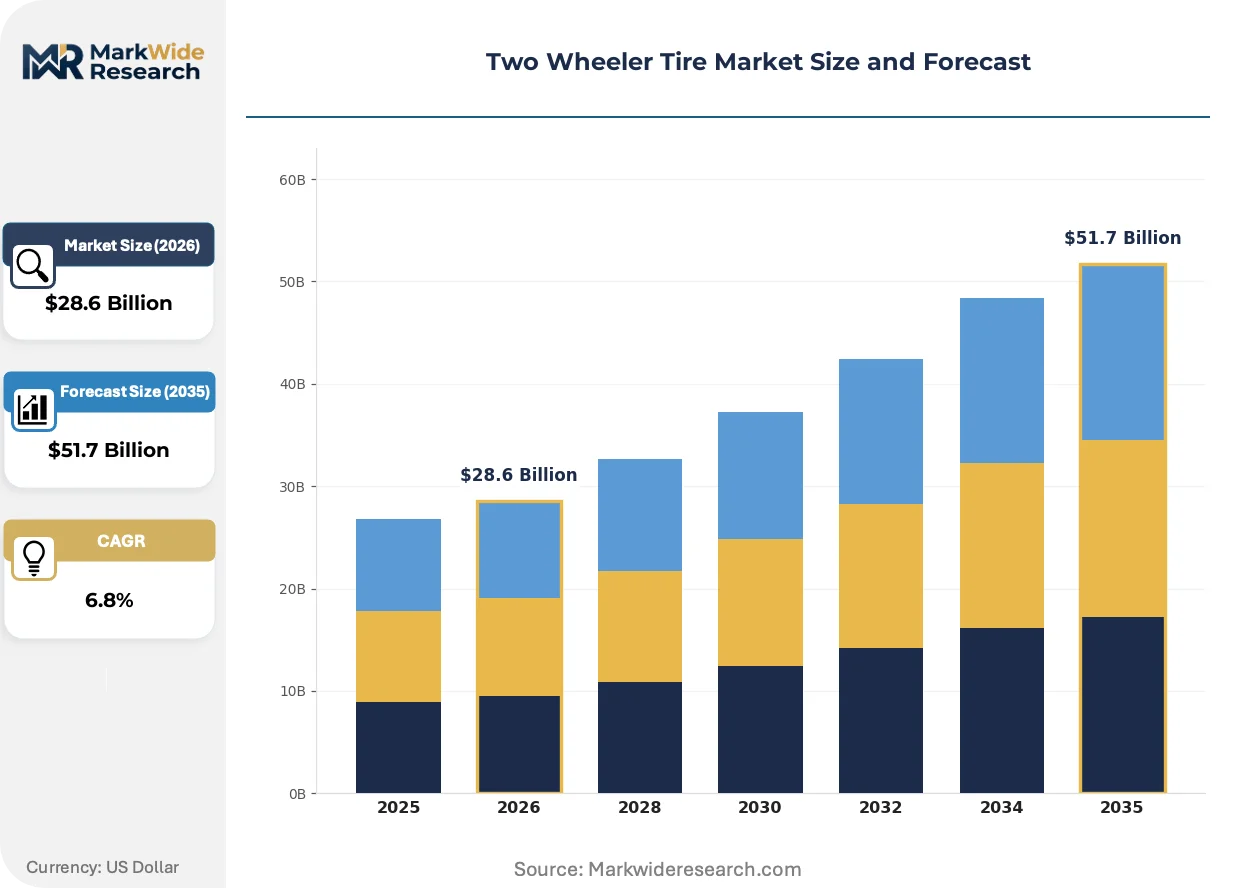
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube Type, Tubeless, Solid, Bias Ply End User: Manufacturers, Repair Shops, Retailers, Individual Consumers Material: Rubber, Synthetic Compound, Natural Rubber, Specialty Blends Size: 14 Inch, 15 Inch, 16 Inch, 17 Inch |
| Companies Covered | Pirelli & C. S.p.A, Yokohama Rubber Co., Ltd., Bridgestone Corporation, MRF Limited, Sumitomo Rubber Industries, Michelin Group, The Goodyear Tire & Rubber Company, CEAT Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Tire Market Emerging Trajectories
Material science advances and regulatory chemical restrictions are jointly rewriting compound formulation protocols, while digital distribution channels are fragmenting traditional replacement tire procurement pathways.
Silica-silane coupling systems are integrating into tread compounds to reduce rolling resistance without sacrificing wet traction. Premium touring motorcycle manufacturers are specifying these formulations for OEM fitment. The technology is integrating energy efficiency benchmarks into product differentiation, compressing market share for conventional carbon-black-dominant constructions.
India's BIS tire safety and labeling regulations are mandating standardized performance disclosures and minimum endurance thresholds. Domestic manufacturers are reconfiguring production lines to meet certification requirements. The two-wheeler replacement segment is absorbing compliance costs through premium-tier pricing stratification while informal imports face market access barriers.
Fleet operators are consolidating procurement through direct manufacturer relationships and digital B2B platforms, bypassing traditional multi-tier distribution. Last-mile delivery companies in Jakarta, Ho Chi Minh City, and Mumbai are negotiating volume-based service contracts with predictive replacement scheduling. This channel compression is most visible in commercial mobility verticals where uptime metrics override brand loyalty considerations.
Two Wheeler Tire Market Segmentation
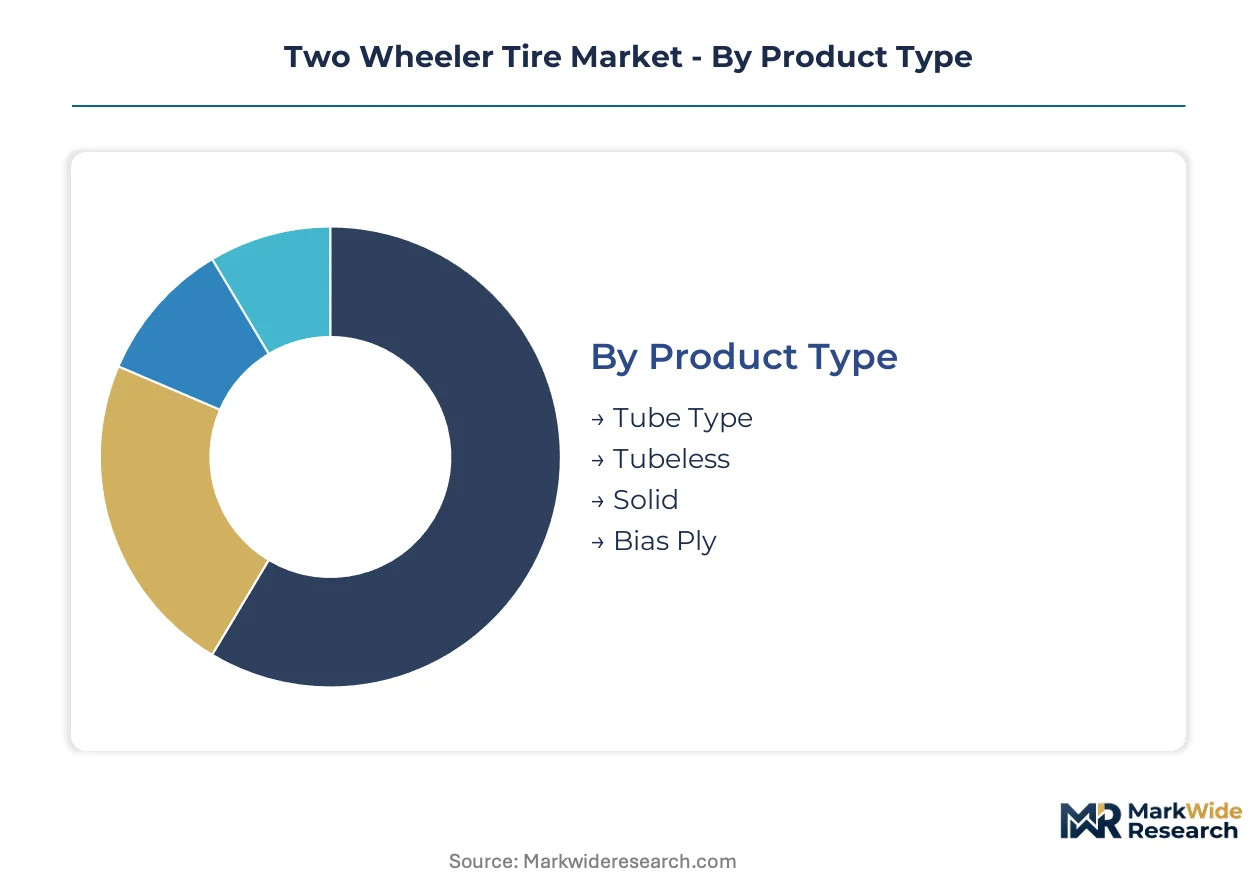
Two-wheeler tire demand fragments across construction methods, procurement channels, compound formulations, and wheel dimensions. Each dimension carries distinct margin profiles and technical certification requirements that shape manufacturer portfolio priorities.
Product Type:
Customization intensity spans from standardized bias-ply replacements to precision-engineered tubeless radials requiring OEM-specific homologation.
- Tubeless:Bead-sealed construction eliminates inner tubes, reducing unsprung weight and enabling lower inflation pressures for improved ride quality. Demand concentrates in Indonesia and Vietnam where premium motorcycle OEM fitment rates climb; BIS certification timelines compress replacement market access for uncertified imports.
- Bias Ply:Cross-ply nylon or polyester cord layers create flexible sidewalls suited to uneven road surfaces. India's tier-3 towns and rural repair shops drive volume; natural rubber price volatility squeezes compound cost structures for this price-sensitive segment.
- Tube Type:Conventional tubed construction retains dominance in legacy motorcycle fleets and commercial three-wheeler applications across South Asian replacement cycles.
- Solid:Non-pneumatic elastomer structures eliminate puncture risk for industrial and commercial utility vehicles operating in debris-heavy environments.
Most installed capacity flows through Bias Ply. Expansion is steepest in Tubeless.
End User:
Procurement scale varies from individual replacement transactions to fleet-level annual contracts with predictive scheduling clauses.
- Individual Consumers:Riders purchasing single or paired replacements through independent tire shops, authorized dealer networks, or emerging e-commerce platforms. India's organized retail penetration in tier-2 cities creates whitespace for branded network expansion.
- Repair Shops:Small and mid-sized service centers stocking fast-moving SKUs for immediate installation; credit terms and same-day delivery capabilities determine supplier relationships.
- Retailers:Multi-brand outlets and exclusive brand stores managing inventory depth across seasonal demand fluctuations.
- Manufacturers:OEM fitment contracts with motorcycle assemblers in Thailand, India, and Indonesia specifying compound performance thresholds and volume commitments.
Volume concentrates with Individual Consumers. Margin expansion is fastest among Manufacturers.
Material:
Compound sophistication determines thermal stability, wet-grip coefficients, and rolling resistance benchmarks across climate zones.
- Specialty Blends:Silica-silane coupled formulations and aramid-reinforced carcass structures deliver high-speed stability and reduced rolling resistance. Premium touring motorcycle OEMs in Europe and Japan specify these compounds; REACH chemical restrictions constrain traditional plasticizer chemistries in export-bound production.
- Natural Rubber:Plantation-sourced polyisoprene provides tear resistance and low heat buildup for tropical operating conditions. Southeast Asian supply concentration exposes formulators to weather-driven yield fluctuations.
- Synthetic Compound:Solution-polymerized styrene-butadiene and polybutadiene blends enhance wear resistance in high-mileage commercial applications.
- Rubber:General-purpose compound categories encompassing carbon-black-dominant tread formulations for economy-tier replacement markets.
Production volume flows through Natural Rubber. Technology investment is concentrating in Specialty Blends.
Size:
Wheel diameter specifications align with motorcycle displacement classes and regional fleet composition patterns.
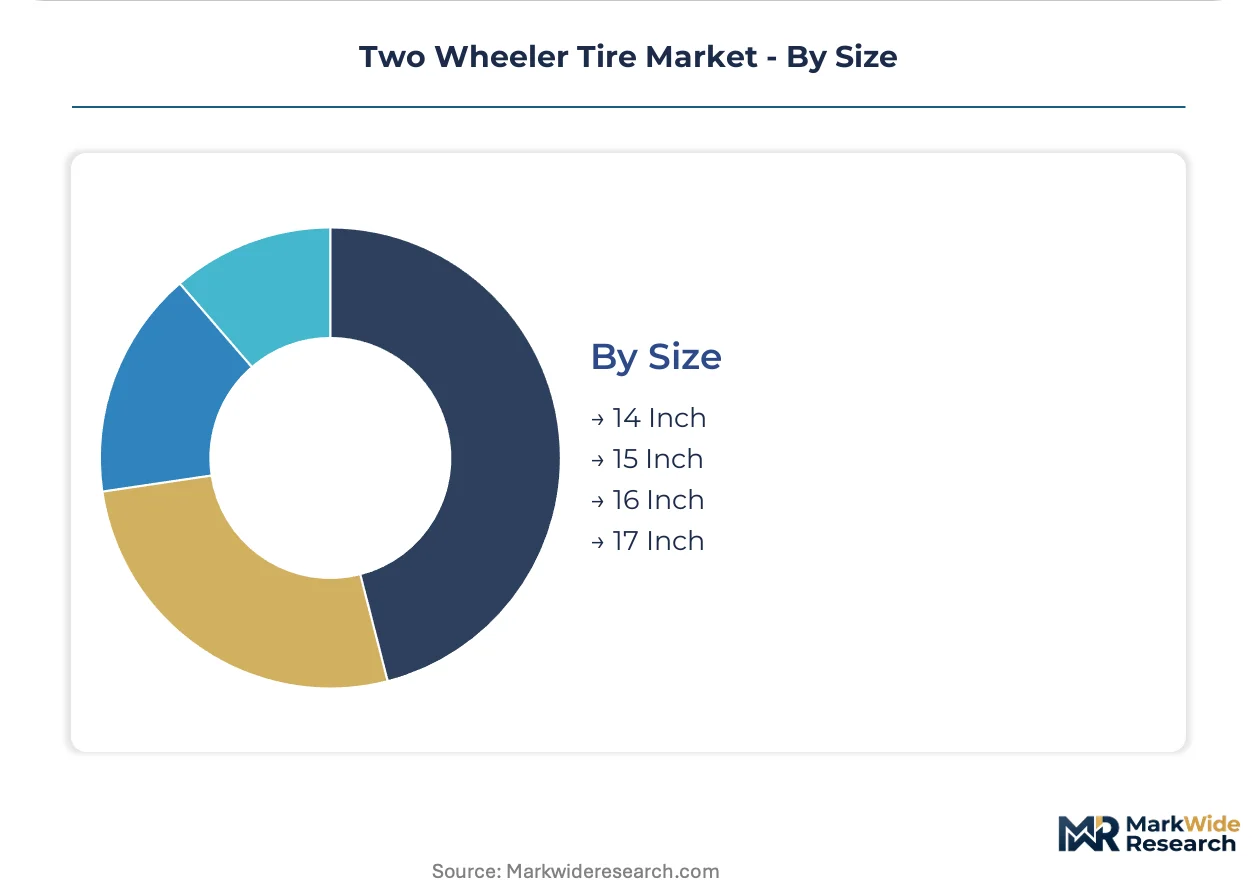
- 17 Inch:Dominant sizing for premium motorcycles and performance-oriented scooters across Indonesian and Vietnamese urban corridors.
- 16 Inch:Mid-displacement commuter motorcycles and maxi-scooters in Indian metropolitan markets.
- 15 Inch:Compact scooter segments and entry-level motorcycles with standardized rim specifications for cost-sensitive procurement.
- 14 Inch:Small-displacement scooters and mopeds concentrated in dense Southeast Asian urban environments with maneuverability priorities.
Replacement frequency peaks at 17 Inch. Penetration growth is strongest in 16 Inch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gurgaon-Manesar industrial corridor anchors two-wheeler tire manufacturing density, with radial production lines serving both domestic replacement cycles and export-bound OEM contracts.
India
Last-mile delivery fleet operators in Mumbai and Bengaluru accelerate commercial tire wear rates, compressing replacement intervals to sub-12-month cycles. BIS certification mandates for tire safety and labeling squeeze substandard imports while rewarding compliant domestic manufacturers. Chennai-Tirupati belt concentrates radial production capacity expansion.
Indonesia
Premium motorcycle OEM fitment rates climb across Jakarta and Surabaya urban corridors, elevating tubeless radial specifications. The national standardization agency enforces SNI labeling requirements that parallel BIS frameworks. Bekasi industrial zone hosts compound formulation facilities serving ASEAN export markets.
Vietnam
Ho Chi Minh City logistics operators consolidate procurement through direct manufacturer relationships, bypassing traditional distribution tiers. Ministry of Transport directives on commercial vehicle safety tighten tire endurance testing protocols. Binh Duong province attracts greenfield radial capacity from regional tire makers.
Thailand
Rayong-Chonburi Eastern Economic Corridor concentrates motorcycle assembly plants, driving synchronized OEM tire demand. Board of Investment incentives favor advanced rubber processing and tire cord manufacturing investments. Bangkok metropolitan replacement market absorbs premium touring motorcycle radial imports.
China
Qingdao and Dongying rubber industry clusters supply specialty tire cord and compound additives across Southeast Asian manufacturing bases. GB standards on tire labeling and rolling resistance disclosure reshape export-bound production specifications. Yangtze River Delta logistics hubs test digital tire monitoring integration for fleet applications.
Two Wheeler Tire Market Vendor Landscape
Capacity expansion dominates the current landscape, with manufacturers adding radial production lines to capture premium motorcycle OEM fitment contracts. The vendor base stratifies across three tiers: integrated rubber conglomerates with captive raw material sourcing, mid-scale regional specialists serving replacement markets, and niche performance-focused compound innovators. Strategic archetypes include scale-driven radial producers, distribution-heavy domestic incumbents, and R&D-intensive premium specialists. Geographic expansion into tier-3 towns and technology licensing for electric two-wheeler specifications represent parallel competitive vectors.
Among Asia-Pacific integrated producers, Bridgestone Corporation and Sumitomo Rubber Industries occupy positions exemplifying scale-driven radial manufacturing archetypes. MRF Limited anchors the distribution-intensive domestic incumbent tier through deep replacement network penetration. Michelin Group represents the R&D-focused premium specialist archetype, with compound innovation capabilities concentrated in high-performance radial segments.
| Leading Market Players |
|---|
| Pirelli & C. S.p.A |
| Yokohama Rubber Co., Ltd. |
| Bridgestone Corporation |
| MRF Limited |
| Sumitomo Rubber Industries |
| Michelin Group |
| The Goodyear Tire & Rubber Company |
| CEAT Ltd. |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Natural rubber futures volatility on the Tokyo Commodity Exchange cascades through compound formulation costs into three distinct pricing tiers: BIS-certified premium radials, standard bias-ply replacements, and uncertified economy imports. Indonesian and Vietnamese fleet operators absorb cost pass-throughs through annual volume contracts, while India's tier-3 retail channels resist price adjustments beyond single-digit ranges.
Pricing Analysis
Input-cost pass-through from aramid cord and silica-silane additives stratifies pricing across certification grades. BIS-compliant manufacturers command 15-25% premiums over uncertified imports through labeled performance guarantees. Price erosion runs through the economy bias-ply segment as natural rubber spot markets soften. Individual consumers in rural India exhibit highest price sensitivity; OEM fitment contracts with Thai and Indonesian assemblers show lowest elasticity due to homologation lock-in.
Supply Chain Analysis
Regional distribution centers in Mumbai, Jakarta, and Ho Chi Minh City operate hub-and-spoke patterns feeding tier-2 and tier-3 repair shops. Manufacturing concentrates in Thailand, India, and Indonesia, with compound additives sourcing from China's Qingdao chemical clusters. Steel cord supply rests on South Korean and Chinese tire cord specialists, creating single-source vulnerability for radial expansion programs. Distribution runs through manufacturer-direct fleet contracts and multi-tier wholesale networks serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in BIS-certified premium tiers where compliance costs filter out informal competitors, and in radial production where technology barriers protect pricing power.
For Market Incumbents: Cement replacement market dominance through captive control over natural rubber sourcing from Southeast Asian plantation networks. Expand radial capacity in the Chennai-Tirupati belt to capture OEM fitment contracts with Indonesian and Vietnamese motorcycle assemblers. BIS certification backlogs threaten new product introductions—invest in dedicated homologation teams to compress approval timelines. For New Entrants and Emerging Players: India's BIS tire safety mandates open a window for domestic compound specialists to displace uncertified imports in tier-3 and tier-4 towns. Target fleet procurement consolidation in Ho Chi Minh City and Jakarta through predictive replacement scheduling platforms. Enter via white-label manufacturing partnerships with established Thai or Indonesian radial producers to bypass greenfield capex requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale bias-ply specialists face radial conversion capex burdens and BIS compliance cost escalation. Five-to-ten-year viability favors manufacturers with captive raw material positions and OEM homologation track records. Monitor BIS type-approval queue lengths as an inflection indicator—backlog compression signals accelerated market share shifts toward compliant domestic producers.| Strategic Initiative | Industry Significance |
|---|---|
| Radial Capacity Expansion | Captures premium motorcycle OEM fitment contracts in Thailand and Indonesia. |
| Backward Integration into Natural Rubber | Insulates compound costs from Tokyo Commodity Exchange volatility. |
| BIS Certification Investment | Creates market access barriers against uncertified import competition. |
| Fleet Direct Procurement Platforms | Bypasses multi-tier distribution compression in commercial segments. |
| Silica-Silane Compound Development | Meets REACH restrictions while delivering rolling resistance benchmarks. |
Methodological Framework
Bottom-up motorcycle fleet modeling reconciled against top-down tire production tracking forms the analytical core. Primary interviews with compound formulation directors, BIS certification officers, fleet procurement managers, and tier-2 distribution operators combined with secondary validation from customs trade records, BIS registration databases, motorcycle production disclosures, and ASEAN automotive federation reports. Triangulation across supply-side capacity announcements and demand-side replacement cycle surveys calibrated volume estimates.
Historical trendline analysis of replacement frequency by motorcycle displacement class informed projection frameworks across the analysis window. Segmentation dimensions encompass construction method, end-user procurement scale, compound sophistication tier, and wheel diameter specification. CAGRs derived from elasticity modeling of fleet expansion rates against per-vehicle tire consumption coefficients. Electric two-wheeler adoption curves and last-mile delivery fleet growth trajectories served as industry-specific demand inputs.
Revisions become necessary when BIS regulatory timelines shift, natural rubber supply disruptions exceed seasonal patterns, or radial capacity additions outpace premium motorcycle OEM fitment demand. Forecasts reflect documented assumptions regarding fleet operator procurement consolidation rates and REACH chemical restriction implementation scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Global Tires Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Connected Tire Market