
 Asia Pacific 2-Wheeler Tire Market | 2026-2036
Asia Pacific 2-Wheeler Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific 2-Wheeler Tire Market Outlook
Software-defined tire monitoring and predictive maintenance subscriptions is shifting how manufacturers monetize the aftermarket. CEAT Limited leverages its India-centric manufacturing footprint to dominate replacement cycles for commuter motorcycles. Michelin anchors premium positioning through sustained R&D intensity in silica-compound formulations for tropical climates.
Asia Pacific 2-wheeler tires are pneumatic structures engineered with nylon or rayon casings, tread compounds blending natural and synthetic rubber, and steel-bead reinforcement, designed to withstand monsoon hydroplaning and sustained urban braking cycles on asphalt and unpaved roads. Tubeless configurations lead volume across Southeast Asian scooter parc due to puncture resistance and lower rolling resistance, while electric bike applications represent the fastest-growing segment as torque-delivery profiles demand specialized tread patterns and load ratings. Racing and off-road categories occupy narrow but high-margin pools concentrated in Japan and Australia's enthusiast markets.
BIS mandates in India, Indonesia's SNI standards, and Thailand's TISI framework collectively shape minimum tread-wear indicators, wet-grip coefficients, and labeling requirements that filter import eligibility and OEM supply qualifications. China's GB standards and MIIT energy-efficiency directives further constrain compound formulations for tires sold into electric two-wheeler platforms. Stakeholders must monitor how battery-weight redistribution on electric frames alters load-index specifications and whether ASEAN mutual recognition agreements harmonize testing protocols across national borders.
Market Dynamics
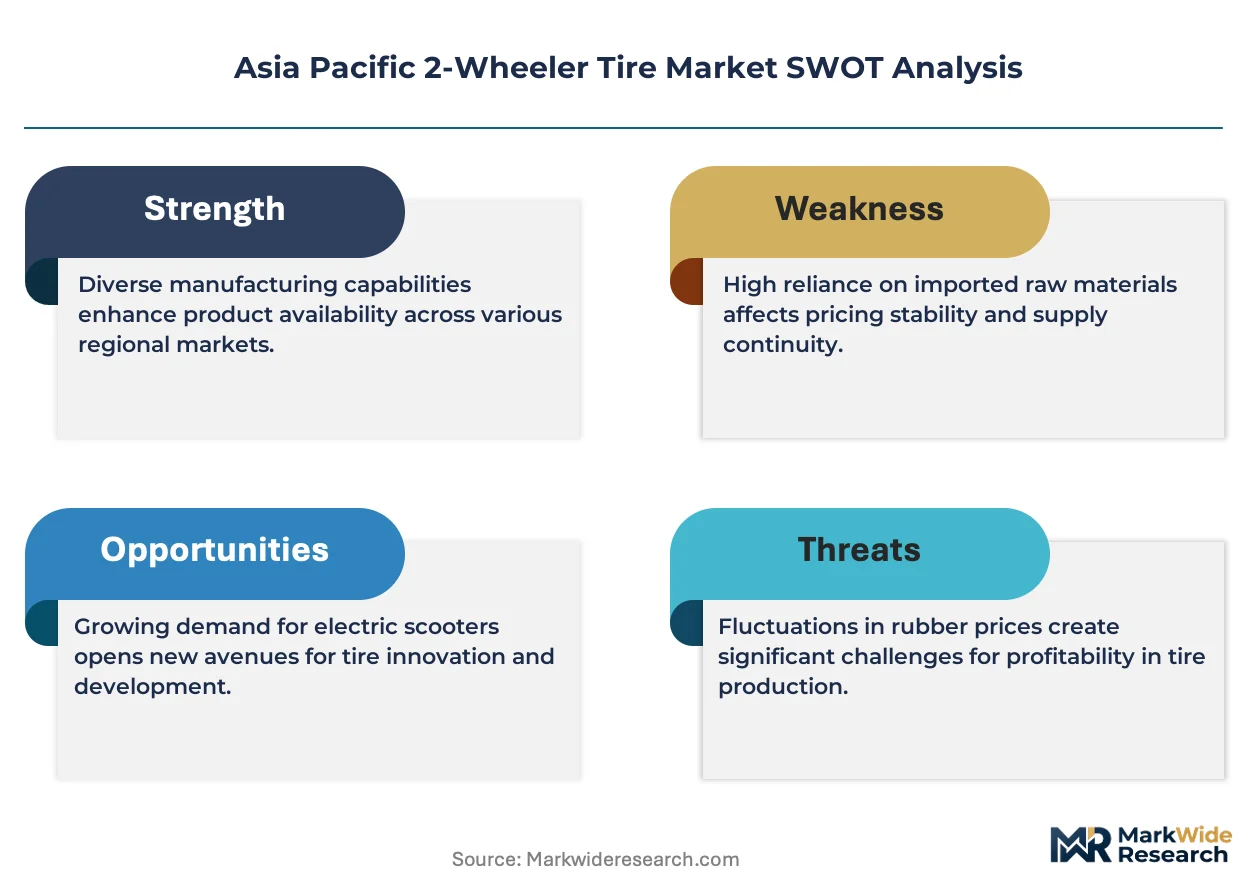
India's BIS certification mandates and Indonesia's SNI standards are compressing product qualification timelines while forcing compound reformulation investments that reshape competitive economics across Southeast Asian manufacturing.
Growth Catalysts
- Urban delivery fleet expansion:Indonesia's motorcycle-based logistics sector generates replacement tire demand through high-frequency braking cycles and monsoon-season wear patterns.
- MIIT energy-efficiency directives:China's GB standards for electric two-wheeler tires mandate specialized load-index specifications that create captive demand for certified suppliers.
- Software-defined monitoring:Predictive maintenance subscriptions monetize aftermarket relationships through real-time tread-wear telemetry and automated reorder triggers.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian plantation output fluctuations transmit directly to compound cost structures without hedging mechanisms for mid-tier manufacturers.
- Import qualification friction:Thailand's TISI framework and Vietnam's QCVN standards impose redundant testing protocols that extend time-to-market for regional suppliers.
- Steel-bead reinforcement dependency:Concentrated sourcing from Chinese metallurgical suppliers creates input vulnerability during trade policy shifts.
Strategic Opportunities
- Electric bike torque profiles:Battery-weight redistribution demands specialized tread patterns and load ratings that incumbent suppliers must develop from blank-slate specifications.
- ASEAN mutual recognition:Harmonized testing protocols across national borders would collapse redundant certification costs for cross-border tire distribution.
- Racing enthusiast segments:Japan and Australia's premium off-road categories sustain high-margin pools underserved by volume-focused manufacturers.
Industry Challenges
- Silica-compound R&D talent scarcity:Tropical-climate formulation expertise concentrates among Japanese and European suppliers, constraining local capability building.
- Tubeless retrofit complexity:Legacy rim specifications across Southeast Asia's installed parc complicate upgrade paths and service training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific 2-Wheeler Tire Market |
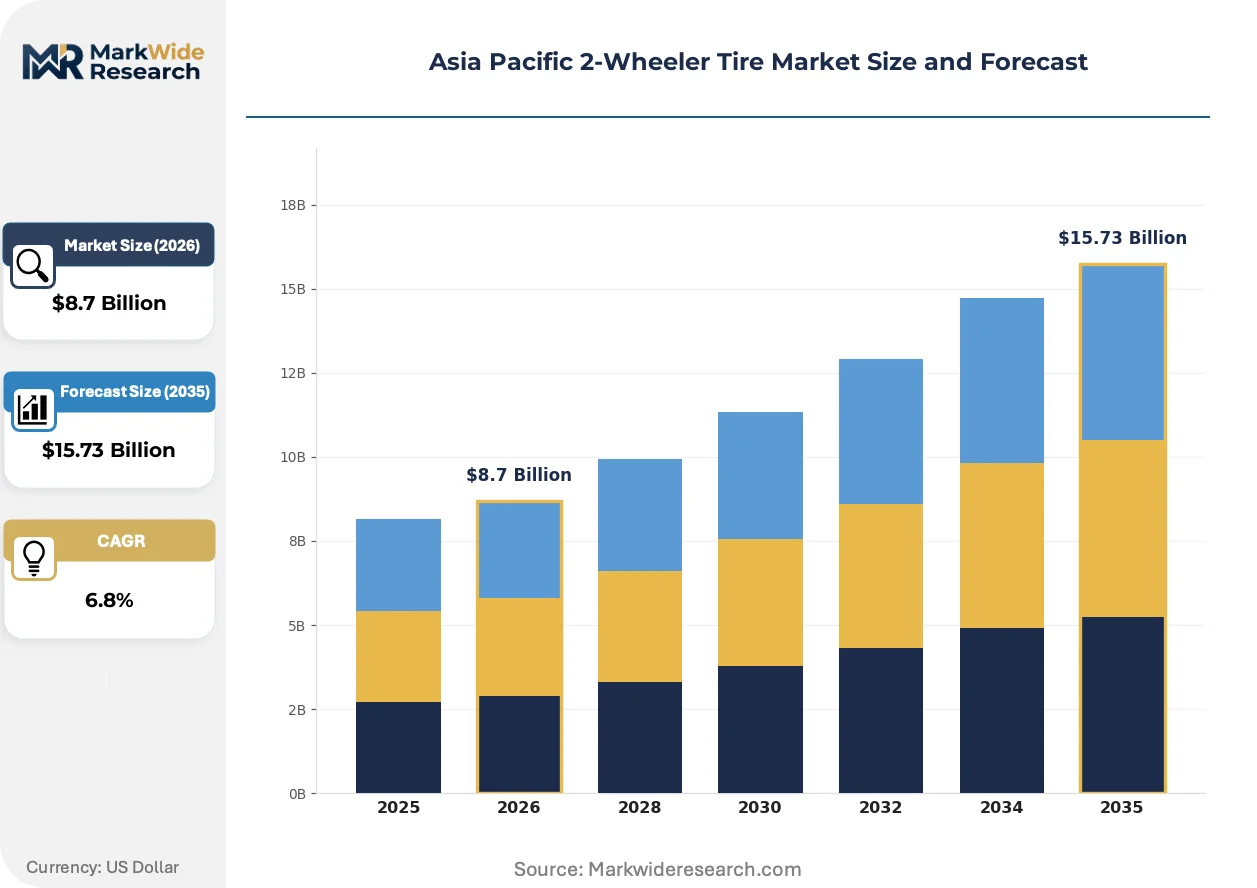
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubeless, Tube-type, Off-road, Racing Application: Motorcycles, Scooters, Electric Bikes, Mopeds Distribution Channel: Online, Retail Stores, Distributors, OEMs Customer Type: Individual Consumers, Fleet Owners, Dealers, Aftermarket Providers |
| Companies Covered | CEAT Limited, Hangzhou Zhongce Rubber, Michelin, JK Tyre & Industries, TVS Srichakra Limited, Bridgestone, Apollo Tyres, Cheng Shin Rubber, MRF Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific 2-Wheeler Tire Market Strategic Shifts
Material science convergence with connected tire architectures is redefining how manufacturers capture value beyond the initial equipment sale. Three developments dominate strategic planning.
Silica-enhanced tread compounds engineered for wet-grip coefficients in monsoon conditions are expanding into Indonesia's urban delivery sector. Fleet operators in Jakarta and Surabaya specify these formulations for hydroplaning resistance during sustained braking cycles. The technology is expanding into premium replacement segments as commuter riders upgrade from conventional natural-rubber blends.
BIS mandates in India now require standardized tread-wear indicators and labeling disclosures that filter both import eligibility and OEM supply qualifications. Tire manufacturers must redesign testing protocols to meet wet-grip coefficient floors before market entry. Electric two-wheeler platforms face additional scrutiny as battery-weight redistribution alters load-index specifications under draft notification rules.
Fleet procurement teams now bundle tire subscriptions with predictive maintenance software rather than transacting on unit price alone. Motorcycle logistics operators in Vietnam and the Philippines negotiate outcome-based contracts where suppliers guarantee minimum mileage thresholds. This restructuring concentrates purchasing power among large fleet aggregators while compressing margins for spot-market distributors.
Asia Pacific 2-Wheeler Tire Market Segmentation
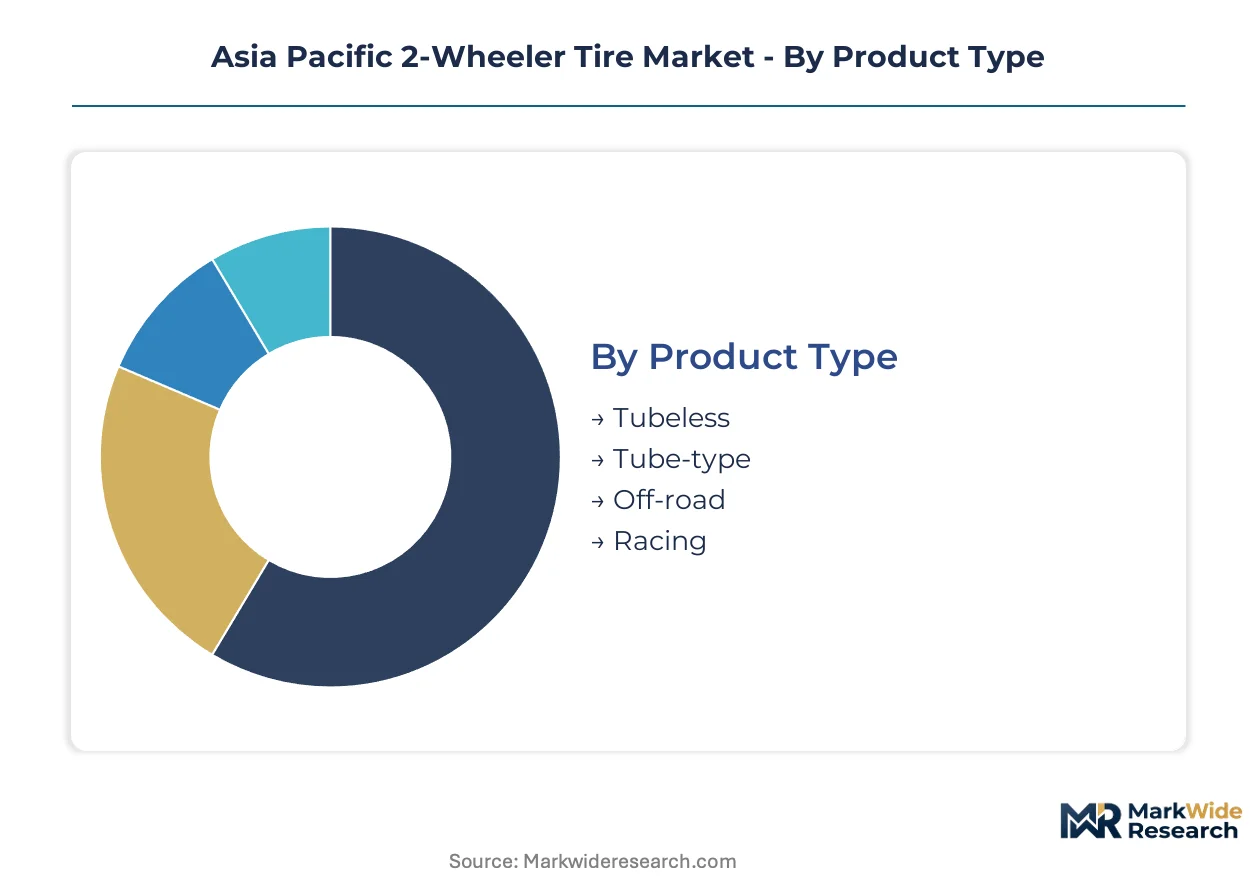
Segmentation in the Asia Pacific 2-wheeler tire market reveals how product specifications, application requirements, and procurement channels create distinct competitive arenas. Each dimension carries unique margin structures and regulatory exposure that manufacturers must navigate across Southeast Asian and South Asian markets.
Product Type:
Supply concentration in tubeless manufacturing clusters around Thai and Indonesian production hubs, while specialty categories remain import-dependent.
- Tubeless:Nylon or rayon casings with steel-bead reinforcement eliminate inner tubes for puncture resistance and lower rolling resistance. Demand concentrates in Indonesia's urban scooter parc and Vietnam's delivery fleet replacement cycles driven by monsoon hydroplaning requirements.
- Tube-type:Conventional construction with separate inner tubes persists across legacy motorcycle populations in rural India and the Philippines where rim specifications complicate retrofit. Cost-sensitive commuter segments sustain volume despite gradual displacement.
- Off-road:Reinforced sidewalls and aggressive tread blocks serve Australia's recreational trail riding and Japan's enthusiast markets.
- Racing:Specialized silica-compound formulations for tropical track conditions occupy narrow premium pools in Malaysia and Thailand.
Today's leader: Tubeless. Tomorrow's challenger: Racing.
Application:
Volume distribution tracks electrification policy intensity and last-mile logistics density across national markets.
- Electric Bikes:Battery-weight redistribution demands specialized load-index specifications and torque-optimized tread patterns. China's MIIT energy-efficiency directives create captive demand for certified suppliers as the application climbs fastest in procurement priority.
- Scooters:Automatic transmission platforms dominate Southeast Asian urban mobility with tubeless configurations preferred for stop-and-go braking cycles.
- Motorcycles:Manual transmission workhorses sustain replacement demand across India's BIS-regulated aftermarket and Indonesia's SNI-compliant OEM supply.
- Mopeds:Sub-50cc segments retain niche presence in Philippines and Vietnam rural access roads.
Electric Bikes command strategic attention. Scooters defend volume dominance.
Distribution Channel:
Channel economics diverge sharply between subscription-based fleet contracts and spot-market retail transactions.
- OEMs:Direct supply to two-wheeler manufacturers requires BIS, SNI, or TISI pre-qualification with long-term contract structures.
- Distributors:Regional warehousing networks bridge import qualification friction across ASEAN border testing protocols.
- Retail Stores:Neighborhood fitters handle tubeless retrofit complexity and legacy rim service requirements.
- Online:Platform-based procurement gains traction among fleet aggregators negotiating predictive maintenance bundles.
OEMs anchor margin stability. Online channels reshape purchasing power.
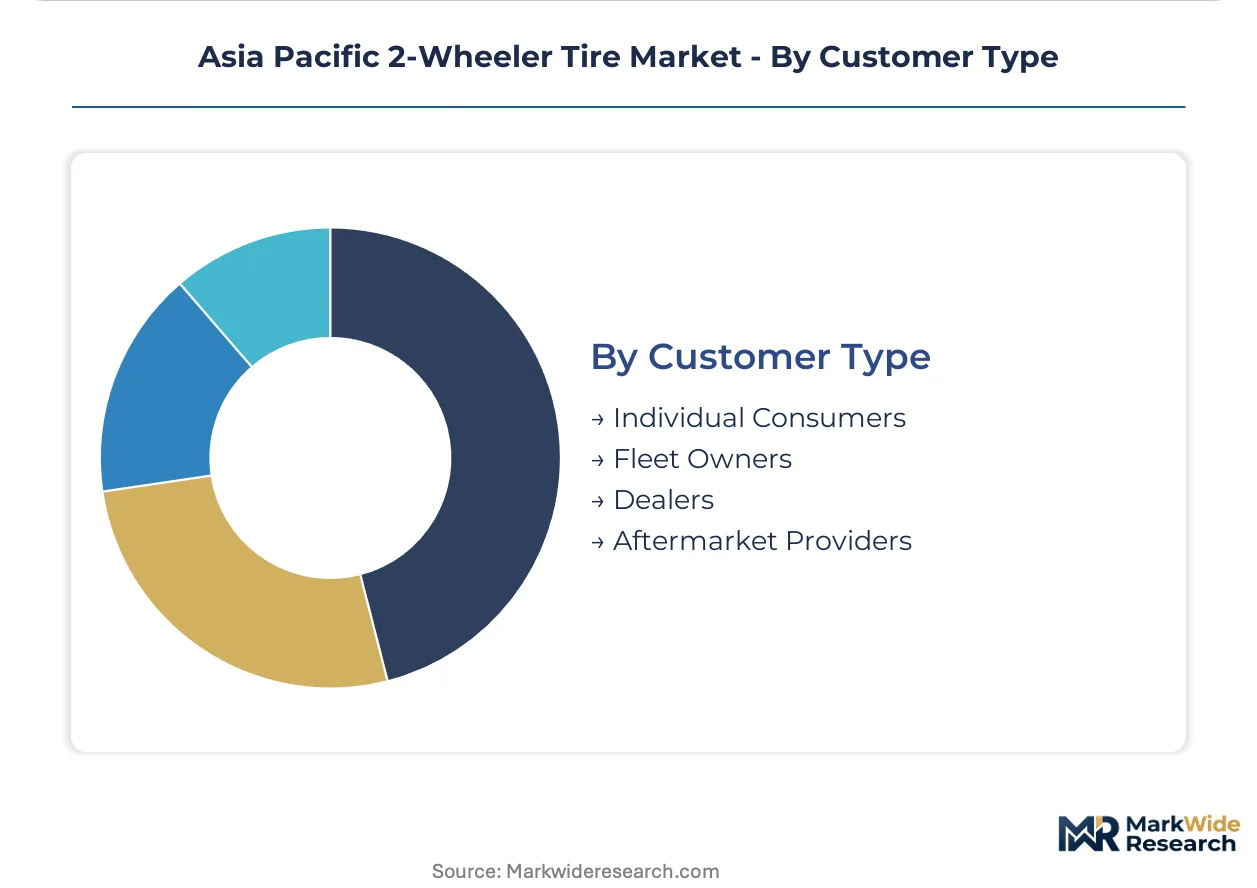
Customer Type:
Procurement sophistication separates outcome-based fleet contracts from price-driven individual replacement.
- Fleet Owners:Motorcycle logistics operators in Jakarta, Surabaya, and Ho Chi Minh City negotiate mileage-guarantee contracts with telemetry-enabled reorder triggers.
- Individual Consumers:Commuter riders in India and Indonesia select based on wet-grip labeling and tread-wear indicator visibility.
- Aftermarket Providers:Independent service chains aggregate demand across multiple brands while navigating tubeless retrofit training requirements.
- Dealers:Authorized networks manage warranty claims and OEM loyalty programs with inventory financing support.
Fleet Owners concentrate purchasing leverage. Individual Consumers fragment price discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates compress qualification timelines faster than Indonesia's SNI standards, yet both frameworks reshape compound investments across South and Southeast Asian manufacturing bases.
India
Commuter motorcycle replacement cycles and electric two-wheeler fleet procurement dominate demand. BIS mandates on tread-wear indicators and wet-grip coefficients filter both import eligibility and OEM supply qualifications. Manufacturing clusters in Chennai and Pune concentrate tubeless production for domestic aftermarket distribution.
Indonesia
Jakarta and Surabaya motorcycle logistics operators generate high-frequency replacement demand through monsoon-season braking cycles. SNI standards impose minimum wet-grip coefficients that force compound reformulation investments. Urban delivery fleet expansion in Java's northern corridor sustains premium silica-compound procurement.
China
MIIT energy-efficiency directives for electric two-wheeler tires create captive demand for certified suppliers with specialized load-index specifications. GB standards constrain compound formulations for battery-weight redistribution platforms. Manufacturing gravity centers on Shandong and Jiangsu provinces serving domestic and export electric bike OEMs.
Vietnam
QCVN standards impose redundant testing protocols that extend time-to-market for regional suppliers navigating import qualification friction. Ho Chi Minh City motorcycle logistics operators negotiate predictive maintenance bundles with telemetry-enabled reorder triggers. Southern industrial zones concentrate tubeless retrofit service capacity.
Thailand
TISI framework requirements shape minimum labeling disclosures and tread-wear indicators for both domestic and export-bound production. Bangkok-based fleet aggregators concentrate purchasing power through outcome-based mileage guarantee contracts. Eastern seaboard manufacturing hubs serve ASEAN cross-border distribution networks.
Asia Pacific 2-Wheeler Tire Market Competitive Environment
Top-tier vendors anchor premium positioning through sustained R&D intensity, while mid-tier manufacturers defend volume share through India-centric and Southeast Asian production footprints. The vendor base stratifies across three archetypes: multinational compound specialists, regional scale producers, and domestic aftermarket distributors. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping supply qualifications.
Within the multinational specialist tier, Michelin and Bridgestone exemplify premium positioning through tropical-climate formulation expertise. Among India-based manufacturers, CEAT Limited, MRF Limited, and Apollo Tyres occupy positions defending replacement cycle dominance for commuter motorcycles. Hangzhou Zhongce Rubber and Cheng Shin Rubber represent Chinese scale producers capturing electric two-wheeler platform demand under MIIT directives. These archetypes illustrate how regulatory compliance investments and geographic manufacturing footprints determine competitive economics across the region.
| Leading Market Players |
|---|
| CEAT Limited |
| Hangzhou Zhongce Rubber |
| Michelin |
| JK Tyre & Industries |
| TVS Srichakra Limited |
| Bridgestone |
| Apollo Tyres |
| Cheng Shin Rubber |
| MRF Limited |
| Others |
Value Chain & Pricing Dynamics
Tubeless manufacturing migration across Thai and Indonesian production hubs simultaneously compresses unit cost economics and concentrates supply-side leverage among certified compounders. This dual restructuring forces mid-tier manufacturers to absorb natural rubber volatility without pricing power, while fleet aggregators exploit telemetry-enabled procurement to collapse spot-market premiums.
Pricing Analysis
Capacity additions in Indonesia and Thailand are reshaping price floors for standard-grade tires even as premium silica-compound segments defend margin. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified OEM supply from aftermarket replacement and gray-market imports. Cost compression in economy tiers intensifies because Thai plantation output fluctuations transmit directly to compound costs. Fleet owners in Jakarta and Surabaya exhibit lowest price sensitivity due to outcome-based mileage guarantees, while rural Indian commuter riders drive maximum spot-market price elasticity.
Supply Chain Analysis
Import qualification gating through India's BIS, Indonesia's SNI, and Thailand's TISI frameworks fragments regional supply into nationally siloed certification pools. Manufacturing concentrates in Thailand, Indonesia, and India, with each hub serving distinct regulatory jurisdictions. Raw material sourcing draws from Thai and Indonesian natural rubber plantations, Chinese steel-bead metallurgical suppliers, and Japanese silica-compound formulators. Single-source vulnerability concentrates in Chinese steel-bead reinforcement during trade policy shifts. Distribution runs through authorized dealer networks and fleet-aggregator platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where India's BIS tread-wear mandates and Indonesia's SNI wet-grip standards continuously force compound reformulation investments that filter supplier viability.
For Market Incumbents: Acquire silica-compound R&D capabilities to defend against Japanese and European formulation specialists. Secure backward integration into Thai natural rubber plantation assets to hedge input volatility. Anchor OEM supply contracts through BIS and SNI pre-qualification investments that raise rival entry costs. For New Entrants and Emerging Players: Fleet procurement teams represent the most penetrable channel partner type for outcome-based subscription models. Target Vietnam's QCVN qualification friction as a white-space entry point where redundant testing protocols delay incumbent responses. Pursue electric two-wheeler platform certification under China's MIIT directives as the fastest-growing application segment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking BIS or SNI certification assets. Long-term viability favors compound specialists with tropical-climate formulation IP and captive fleet-aggregator relationships. Watch ASEAN mutual recognition agreement progress as the signal indicating cross-border margin expansion or continued national fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Compound R&D Acquisition | Secures wet-grip formulation expertise for monsoon braking cycles in Jakarta and Surabaya. |
| Backward Integration into Rubber Plantations | Captures Thai and Indonesian natural rubber supply to hedge plantation output volatility. |
| Fleet-Aggregator Platform Partnership | Locks telemetry-enabled predictive maintenance subscriptions with mileage-guarantee contracts. |
| Electric Two-Wheeler Certification Investment | Qualifies for China's MIIT load-index specifications under battery-weight redistribution standards. |
| ASEAN Mutual Recognition Lobbying | Collapses redundant BIS-SNI-TISI testing costs for cross-border tire distribution networks. |
Study Parameters
Bottom-up fleet procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with tire compound R&D directors, fleet logistics procurement heads, BIS certification auditors, and ASEAN trade policy specialists combined with secondary validation from customs import records, BIS notification databases, MIIT energy-efficiency filings, and plantation output statistics. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Input-output matrices map natural rubber feedstock costs, steel-bead reinforcement pricing, and silica-compound formulation premiums against tubeless and tube-type production volumes across the analysis window. Segmentation dimensions include product construction, application platform, distribution channel, and customer procurement sophistication. CAGRs derive from fitted growth curves incorporating electrification policy intensity and fleet replacement cycle acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN regulatory harmonization progress and electric two-wheeler platform standardization. Forecasts reflect documented assumptions on raw material cost trajectories and certification timeline compression. A model refresh is warranted upon material change in BIS draft notification rules for electric two-wheeler load-index specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
GCC Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Elastic Polyurethane Wheels Market
Tires and Wheels
Specialty Tire Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
Global Tires Market