
 Automotive Surface Coated Brake Market | 2026-2036
Automotive Surface Coated Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Surface Coated Brake Market Outlook
Premium corrosion-resistance specifications is rotating through the supply chain as OEMs extend brake warranty periods beyond 100,000 miles. Bosch leverages in-house coating chemistry expertise to sustain dual supply lines across European and Asian assembly plants. Akebono Brake Corporation anchors North American production through specialized zinc-flake coating operations in Kentucky and Tennessee. Brembo S.p.A. dominates motorsport-derived coating transfers into road-car performance brake programs.
Automotive surface coated brakes are friction components treated with protective layers—typically zinc, zinc-nickel alloys, or ceramic-based formulations applied through electroplating or thermal spraying—to prevent corrosion, reduce initial brake squeal, and extend service life in salt-exposed environments. The coating thickness typically ranges from 8 to 25 micrometers, with salt-spray resistance requirements exceeding 240 hours under ASTM B117 protocols. Disc brake applications command the largest volume share among product types, though electric brake systems are gaining structural importance as EV regenerative braking reduces traditional friction event frequency and shifts coating durability expectations. Ceramic material coatings sustain premium pricing power in high-performance segments where thermal fade resistance determines specification approval.
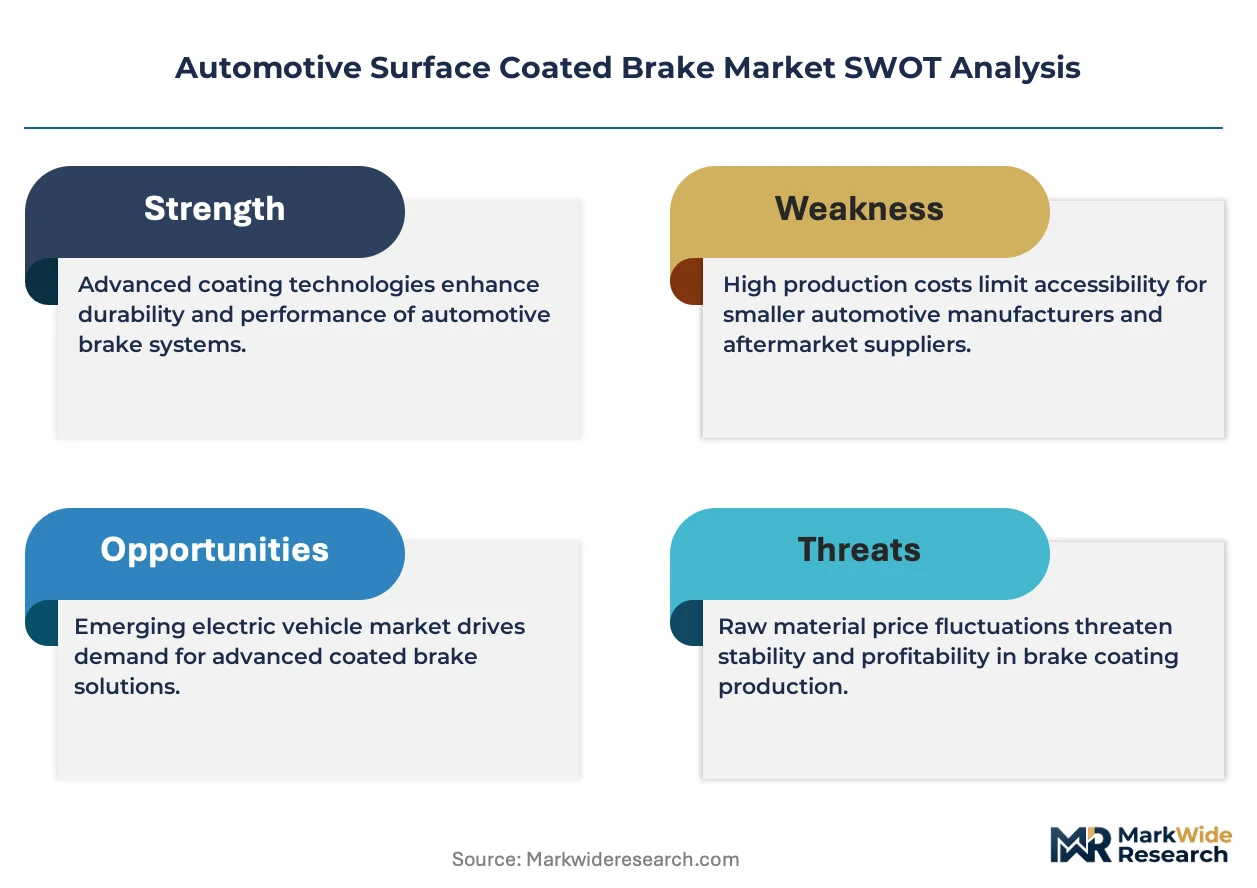
NHTSA's Federal Motor Vehicle Safety Standards govern brake performance and corrosion thresholds for US-market vehicles, while EPA oversight of hexavalent chromium emissions restricts coating chemistry choices at domestic production facilities. Europe's REACH regulation and RoHS directives phase out hazardous substances in brake component surface treatments, forcing reformulation investments across supplier networks. ECE R90 homologation requirements for replacement brake linings further tighten coating consistency standards for aftermarket entry. Stakeholders must monitor evolving battery-electric vehicle brake duty cycles and assess whether reduced friction wear invalidates current coating investment models or creates new specification tiers for low-utilization braking systems.
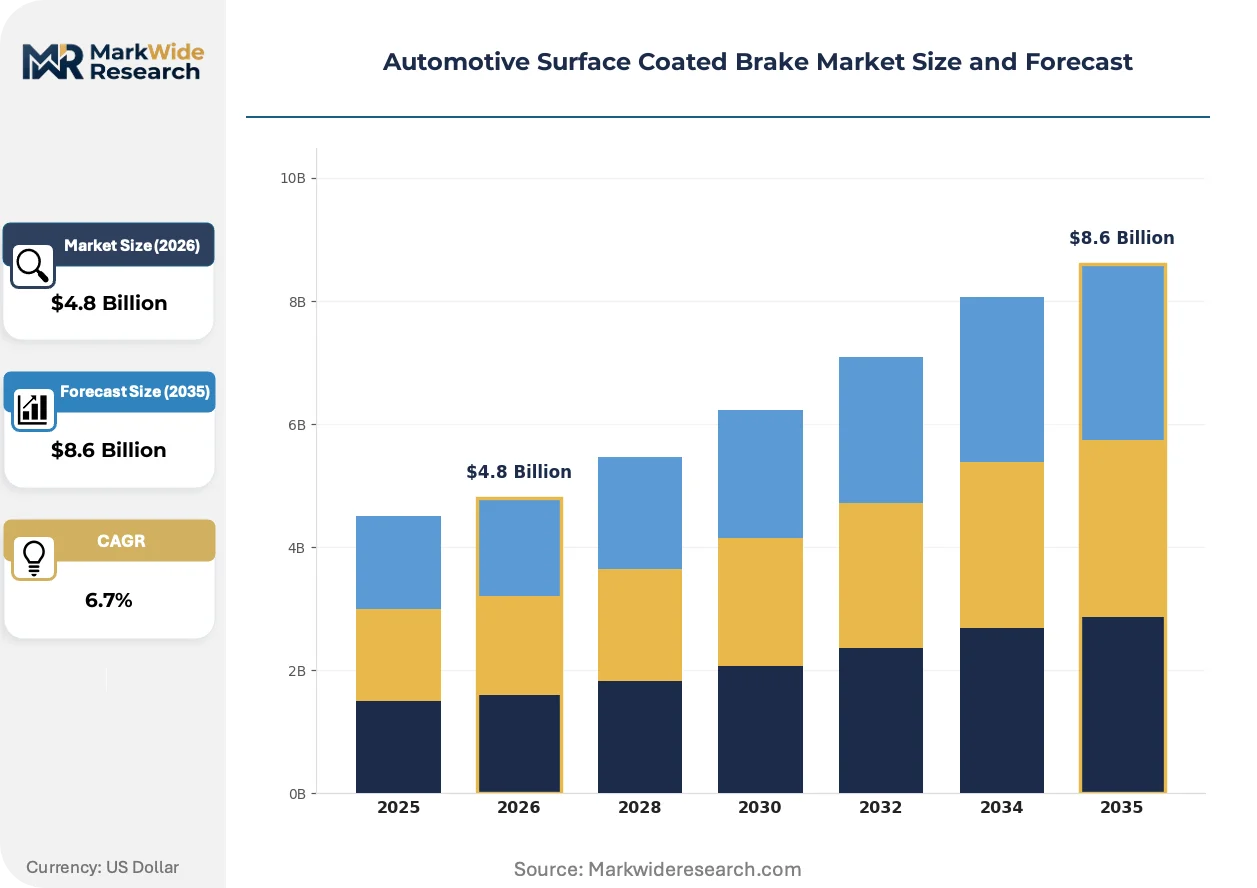
Market Dynamics
Extended warranty coverage requirements are forcing coating specification upgrades across passenger vehicle OEM supply chains as corrosion performance guarantees stretch beyond 100,000 miles.
Growth Catalysts
- REACH Phase-Out Mandates:Europe's ban on hexavalent chromium in surface treatments compels reformulation investments that favor advanced zinc-nickel and ceramic coating chemistries.
- EV Brake Duty Cycle Compression:Regenerative braking systems reduce friction event frequency, extending coating durability requirements and creating specification tiers for low-utilization braking systems.
- German Premium Manufacturing Concentration:Stuttgart and Munich corridor OEMs anchor procurement of high-performance coated brake systems for extended corrosion warranty programs.
Market Restraints
- Zinc-Nickel Alloy Input Volatility:Nickel price fluctuations and supply concentration in Indonesian mining operations compress coating chemistry margins.
- Electroplating Capacity Bottlenecks:Qualified thermal spraying and electroplating facilities cluster in Germany, Japan, and South Korea, limiting supply flexibility.
- ASTM B117 Test Duration Standards:Salt-spray resistance requirements exceeding 240 hours extend qualification timelines and freeze out smaller coating applicators.
Strategic Opportunities
- Indian Commercial Vehicle Expansion:BIS certification requirements for brake components create entry pathways for corrosion-resistant coating suppliers as domestic OEMs upgrade export specifications.
- Digital Twin Integration:Convergence of coating thickness monitoring sensors with predictive maintenance platforms enables service-life guarantees and outcome-based component pricing.
- Aftermarket E-Commerce Penetration:Direct-to-installer channels bypass traditional distributor markups for replacement coated brake discs in fragmented European repair networks.
Industry Challenges
- Electroplating Chemistry Expertise Scarcity:Qualified process engineers for zinc-flake and ceramic thermal spray application command premium compensation in Kentucky and Tennessee manufacturing clusters.
- ECE R90 Homologation Complexity:Replacement brake lining certification timelines delay aftermarket entry for coated disc programs by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Surface Coated Brake Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brake, Drum Brake, Racing Brake, Electric Brake Material: Composite, Ceramic, Steel, Aluminum End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | Brembo S.p.A., Bosch (Robert Bosch GmbH), Akebono Brake Corporation, ZF Friedrichshafen AG, Aisin Corporation, Tenneco Inc., Nisshinbo Holdings Inc., Brake Parts Inc., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Surface Coated Brake Market Strategic Shifts
Coating application technologies are pivoting toward precision thickness control and real-time quality verification as OEMs tighten corrosion warranty terms and EV brake architectures reduce friction wear predictability.
Laser cladding deposition systems are miniaturizing from industrial-scale installations to cell-based modular units suitable for just-in-sequence brake disc production lines. Tier-1 suppliers in Germany and Japan are piloting these compact systems to eliminate batch processing delays. The technology is miniaturizing quality control loops, compressing coating thickness variance from ±5 micrometers to ±1.5 micrometers and reducing scrap rates in high-volume disc manufacturing.
EPA oversight of hexavalent chromium emissions at US production facilities is tightening discharge permits and accelerating capital expenditure cycles for coating line upgrades. Domestic brake component manufacturers face facility-specific emission caps that favor aqueous-based zinc-nickel chemistries over solvent-borne alternatives. The regulatory pressure concentrates investment in Michigan and Ohio assembly corridors where NHTSA corrosion thresholds intersect with state-level air quality enforcement.
Fleet procurement departments are consolidating brake component sourcing through multi-year total cost of ownership agreements that internalize coating durability risk. Large commercial vehicle operators in North America are displacing spot-buying patterns with integrated maintenance contracts covering disc replacement intervals. This concentration is most visible in long-haul trucking segments where salt-exposure severity varies dramatically by route geography and seasonal operating patterns.
Automotive Surface Coated Brake Market Segmentation
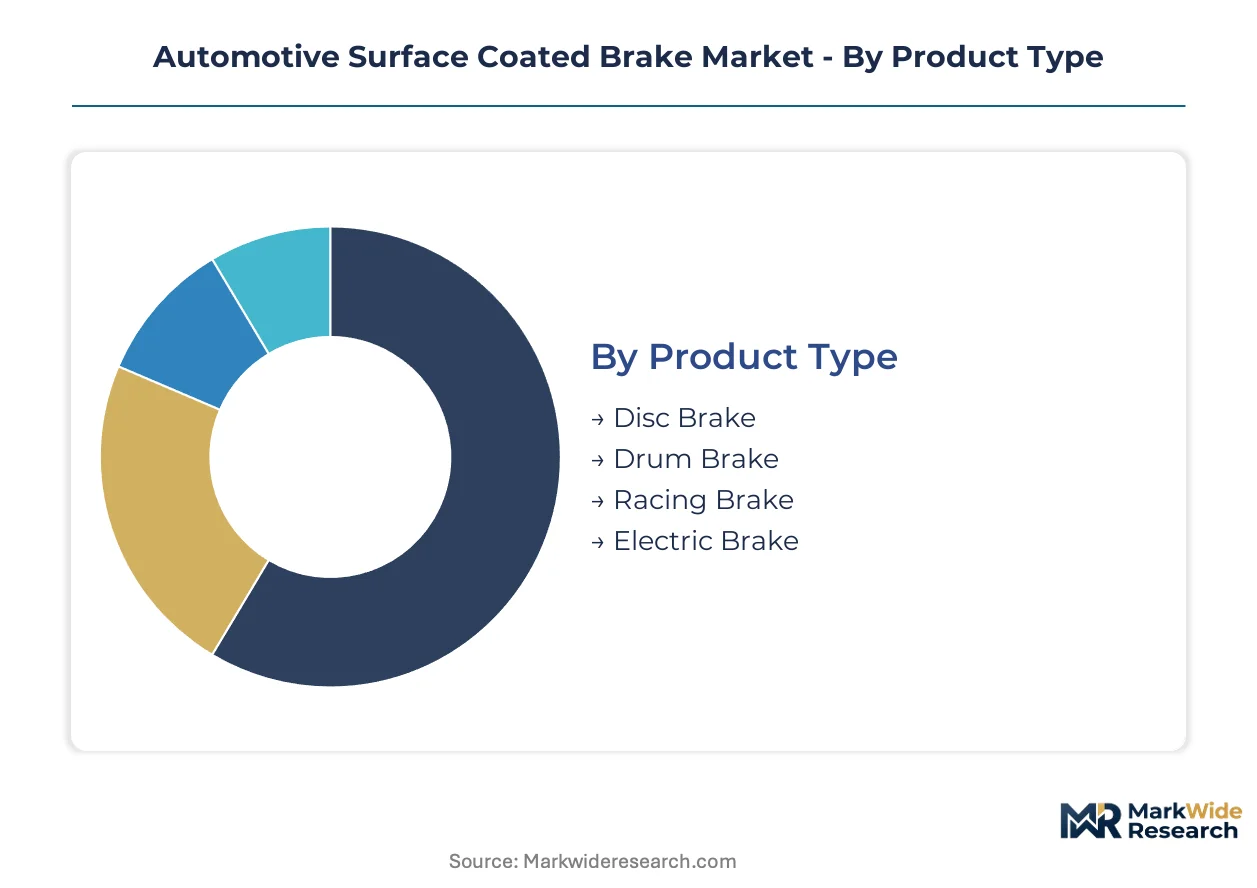
Segmentation in the automotive surface coated brake market reveals how coating chemistry investments align with diverging durability requirements across brake architectures. Product type and material selections determine whether suppliers pursue zinc-nickel electroplating or ceramic thermal spray capabilities.
Product Type:
Electric brake systems face the most acute substitution pressure as regenerative braking architectures reduce friction component utilization rates.
- Disc Brake:Flattened rotors treated with zinc-flake or zinc-nickel coatings dominate passenger vehicle specifications. German premium OEMs in Stuttgart and Munich corridors specify 240+ hour ASTM B117 salt-spray resistance for extended warranty programs.
- Electric Brake:Low-utilization friction systems in battery-electric vehicles require reformulated coating durability expectations. NHTSA corrosion thresholds still apply, but reduced thermal cycling shifts specification priorities toward static corrosion resistance rather than fade-performance tradeoffs.
- Drum Brake:Retains cost-sensitive commercial vehicle applications with simpler zinc coating protocols.
- Racing Brake:Motorsport-derived ceramic coatings command premium thermal performance specifications.
Disc brake retains volume leadership; electric brake holds the steepest expansion curve.
Material:
Cost tier positioning separates ceramic formulations at the premium extreme from commodity steel substrates.
- Steel:Ferrous substrates anchor high-volume disc production with electroplated zinc-nickel protection. Michigan and Ohio assembly corridors concentrate capacity where EPA discharge permits favor aqueous coating chemistries.
- Ceramic:Silicon carbide and carbon-ceramic composites sustain premium pricing in performance brake programs. Brembo transfers motorsport coating protocols into road-car specifications for thermal fade resistance.
- Composite:Multi-material laminates serve mid-tier applications with hybrid coating requirements.
- Aluminum:Lightweight substrates gain traction in unsprung mass reduction programs for electric vehicles.
Steel dominates production volumes; ceramic commands the widest margin spreads.
End User:
Customer type determines whether coating specifications flow through warranty-backed OEM contracts or price-driven aftermarket channels.
- OEMs:Original equipment manufacturers impose 100,000+ mile corrosion guarantees that force coating chemistry upgrades. Bosch sustains dual supply lines across European and Asian assembly plants through in-house coating expertise.
- Fleet Operators:Long-haul trucking consolidators internalize coating durability risk through multi-year total cost of ownership agreements. Salt-exposure severity varies by route geography, concentrating procurement among operators with transcontinental lane structures.
- Aftermarket Providers:ECE R90 homologation requirements delay coated disc entry by 12-18 months.
- Vehicle Assemblers:Contract manufacturers rely on Tier-1 suppliers for pre-coated brake module integration.
OEMs anchor specification authority; fleet operators are consolidating fastest.
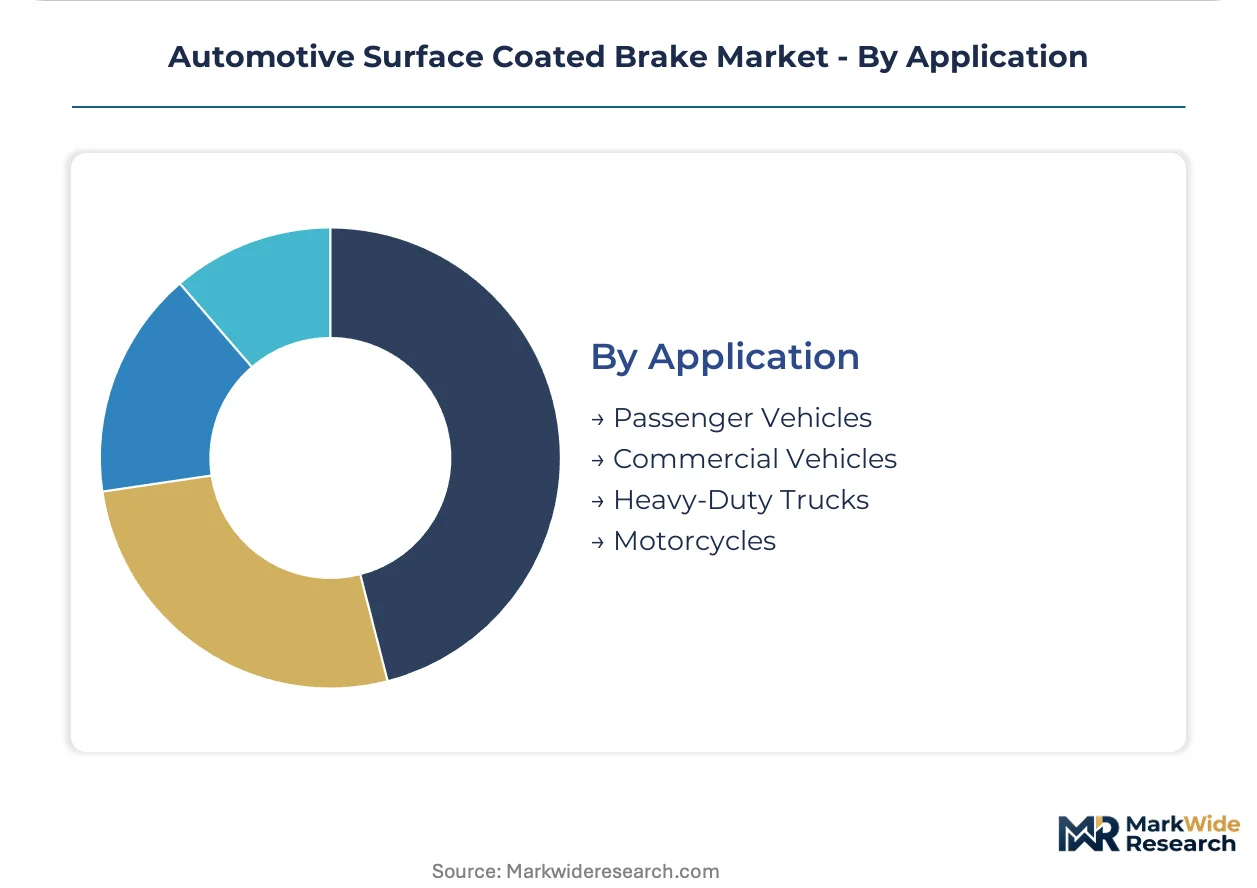
Application:
Vehicle duty cycle intensity creates diverging coating performance thresholds across transportation modes.
- Passenger Vehicles:Light-duty applications drive volume demand for corrosion-resistant disc brakes. REACH mandates on hexavalent chromium alternatives reshape European material specifications.
- Heavy-Duty Trucks:Severe-service braking cycles and salt-exposure concentrate demand for enhanced zinc-nickel formulations. Fleet procurement departments displace spot-buying with integrated maintenance contracts.
- Commercial Vehicles:Mid-duty segments balance coating cost against warranty exposure.
- Motorcycles:Exposed brake architectures prioritize cosmetic corrosion resistance over thermal performance.
Passenger vehicles retain the largest addressable base; heavy-duty trucks generate the highest coating value per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural export surplus in coated brake systems while the United States and China balance import dependency against domestic coating capacity expansion. Japanese suppliers anchor Asian supply networks through specialized electroplating operations concentrated in industrial corridors.
Germany
Stuttgart and Munich corridor OEMs drive procurement of high-performance coated brake systems for extended corrosion warranty programs. ECHA's REACH enforcement on hexavalent chromium alternatives forces zinc-nickel chemistry investments across Baden-Württemberg manufacturing clusters. ZF Friedrichshafen anchors coating R&D in Friedrichshafen while supplying dual assembly lines across European and Asian plants.
United States
NHTSA corrosion thresholds intersect with EPA discharge permit tightening to reshape Michigan and Ohio assembly corridor investments. Kentucky and Tennessee manufacturing clusters concentrate qualified process engineers for zinc-flake thermal spray operations. Fleet procurement departments in long-haul trucking displace spot-buying with multi-year total cost of ownership agreements internalizing coating durability risk.
China
GB standards on brake emissions and MIIT industrial upgrading directives accelerate domestic coating chemistry reformulation. Yangtze River Delta automotive clusters absorb technology transfers from German and Japanese joint ventures for zinc-nickel electroplating scale-up. BYD and CATL supply chain integration creates captive demand for EV-specific low-utilization brake coating specifications.
Japan
METI carbon neutrality roadmaps and JIS quality standards pressure brake component suppliers toward aqueous coating chemistries. Aichi Prefecture manufacturing corridors concentrate thermal spraying expertise serving Toyota and Honda assembly networks. Akebono Brake Corporation maintains process engineering dominance through specialized zinc-flake operations feeding North American transplant facilities.
India
BIS certification requirements for brake components create entry pathways for corrosion-resistant coating suppliers as domestic OEMs upgrade export specifications. Tamil Nadu and Maharashtra automotive corridors attract zinc-nickel electroplating investments from European Tier-1 suppliers. Mahindra and Tata Motors procurement teams extend warranty coverage to 100,000 kilometers, forcing coating specification upgrades across supplier networks.
Automotive Surface Coated Brake Market Competitive Environment
Listed leaders compete with private specialists across coating chemistry expertise and regional supply line density. The vendor base concentrates around brake system integrators with captive electroplating capabilities and independent coating applicators serving aftermarket channels. Three archetypes dominate: diversified automotive suppliers with in-house chemistry divisions, specialized brake component manufacturers with regional coating facilities, and independent surface treatment providers selling into fragmented aftermarket networks. Capacity expansion and strategic technology licensing represent the dominant competitive moves as qualification timelines stretch beyond 18 months.
Among diversified automotive suppliers, Bosch and Continental AG exemplify the integrated-chemistry archetype through captive coating formulation expertise sustaining dual supply lines across multiple continents. Brembo S.p.A. occupies a distinct position transferring motorsport-derived thermal spray protocols into road-car performance programs. Akebono Brake Corporation anchors the regional-specialist tier through concentrated zinc-flake operations in Kentucky and Tennessee serving North American OEM transplant networks.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| Bosch (Robert Bosch GmbH) |
| Akebono Brake Corporation |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| Tenneco Inc. |
| Nisshinbo Holdings Inc. |
| Brake Parts Inc. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Long-term total cost of ownership agreements lock in coating chemistry supply access and price visibility for fleet operators while transferring corrosion durability risk from OEM procurement departments to Tier-1 suppliers across Michigan and Ohio assembly corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium ceramic thermal spray, standard zinc-nickel electroplating, and economy zinc-flake formulations. Price differentiation hinges on ASTM B117 salt-spray certification tiers and volume scale commitments from German premium vehicle producers. Cost compression in commodity steel substrates is intensifying because Indonesian nickel supply concentration feeds through to zinc-nickel alloy input costs. Fleet procurement departments show lowest price sensitivity due to internalized durability risk, while fragmented European aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Germany and Japan anchor qualified electroplating capacity for zinc-nickel and ceramic thermal spray operations serving global OEM assembly networks. Raw material flows draw from Indonesian nickel mining operations, Chinese zinc refining complexes, and specialized ceramic powder producers in Aichi Prefecture. Single-source vulnerability concentrates in qualified process engineering talent clusters across Kentucky and Tennessee manufacturing corridors. Distribution runs through Tier-1 brake system integrators with captive coating capabilities rather than independent surface treatment providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating chemistry reformulation services and predictive maintenance platform subscriptions expand faster than hardware as fleet operators internalize brake disc replacement intervals and outcome-based component pricing gains traction.
For Market Incumbents: Shield market position by deepening captive electroplating expertise in aqueous zinc-nickel chemistries ahead of EPA discharge permit tightening in Michigan and Ohio corridors. Lock in long-term offtake agreements with German premium OEMs extending corrosion warranties beyond 100,000 miles to freeze out smaller coating applicators facing ASTM B117 qualification timeline barriers.
For New Entrants and Emerging Players: Lead with laser cladding deposition system miniaturization for just-in-sequence brake disc production lines, targeting the Indian commercial vehicle aftermarket where BIS certification requirements create entry pathways for corrosion-resistant coating suppliers. Capture share through direct-to-installer e-commerce channels bypassing traditional distributor markups in fragmented European repair networks.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized brake component manufacturers with regional coating facilities and established ECE R90 homologation pathways, given five-to-ten year viability windows tied to EV brake duty cycle compression and low-utilization coating specification tier emergence. Monitor fleet procurement department consolidation patterns as the inflection signal for outcome-based pricing adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation Investment | REACH hexavalent chromium phase-out forces zinc-nickel and ceramic thermal spray capability expansion across European supplier networks. |
| Laser Cladding Deposition Scale-Up | German and Japanese Tier-1 suppliers pilot compact systems to compress coating thickness variance from ±5 micrometers to ±1.5 micrometers. |
| Digital Twin Integration Partnership | Convergence of coating thickness monitoring sensors with predictive maintenance platforms enables service-life guarantees for fleet operators. |
| Aftermarket E-Commerce Channel Development | Direct-to-installer penetration bypasses distributor markups for replacement coated brake discs in fragmented European repair networks. |
| Indian Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra automotive corridors attract zinc-nickel electroplating investments from European Tier-1 suppliers seeking BIS certification pathways. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and coating process engineering specialists. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, ECHA REACH substance restriction databases, vehicle production databases, and SEC 10-K disclosures from listed brake component manufacturers. Bottom-up coating chemistry demand estimates triangulated against top-down automotive production forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning vehicle propulsion architecture, coating material chemistry, OEM tier positioning, and regional regulatory cluster alignment. CAGRs were derived through regression analysis of historical coating specification adoption curves and forward projection of EV brake duty cycle compression effects. Forecast inputs incorporated REACH enforcement timelines, EPA discharge permit tightening trajectories, and fleet procurement contract structure evolution.
The analysis sits within stated boundaries; outcomes outside sustained German premium manufacturing concentration or accelerated EV penetration rates would require recalibration. Forecasts reflect assumptions regarding nickel price volatility corridors and qualified electroplating capacity expansion feasibility. Recalibration cycles align with material shifts in regulatory enforcement intensity and battery-electric vehicle brake utilization pattern emergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Wind Shield Washer Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Gear Box and Gear Motors Market