
 Twin Screw Pumps Market | 2026-2036
Twin Screw Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Twin Screw Pumps Market Analytics
API 676 qualification cycles for rotary positive displacement pumps is collapsing the vendor pool eligible for upstream oil and gas contracts. Flowserve Corporation leverages its API-certified manufacturing footprint across multiple continents to sustain premium positioning. NETZSCH Pumps LLC anchors its competitive stance through specialized elastomer and metal rotor geometries for abrasive media. ITT Bornemann GmbH dominates the European marine and offshore segment with deep vertical integration in precision screw machining.
Twin screw pumps are positive displacement machines employing two intermeshing helical rotors within a close-tolerance housing to convey fluids with minimal pulsation, typically achieving volumetric efficiencies above 90% across viscosity ranges from 1 cP to 1,000,000 cP. Their primary purpose centers on transferring multiphase fluids, non-Newtonian liquids, and shear-sensitive products without emulsification or degradation. Positive displacement configurations command the deepest installed base due to their versatility across hydrocarbon, chemical, and food-grade duties, while horizontal arrangements lead capital spending in refinery and terminal applications where floor-space optimization governs layout. Stainless steel material specifications capture the highest margin pools in pharmaceutical and hygienic food processing, where surface finish requirements and traceability documentation justify substantial price premiums over cast iron alternatives.
API 676 and ISO 13709 standards govern mechanical and performance specifications for critical service pumps in petroleum and natural gas applications, effectively filtering market access to vendors with certified quality management systems and witnessed factory testing capabilities. The EU F-Gas Regulation and REACH compliance frameworks are redirecting material selection toward fluoropolymer-free sealing systems and low-leakage pump designs in European chemical processing. Stakeholders must monitor evolving methane emissions protocols and carbon border adjustment mechanisms, as these will increasingly determine total cost of ownership calculations and supplier qualification criteria across energy-intensive industries.
Market Dynamics
API 676 compliance timelines are compressing vendor qualification windows while chemical processing expansion in Germany pulls premium-capacity allocation toward high-viscosity applications.
Growth Catalysts
- REACH and F-Gas Regulation:European chemical processors are replacing legacy sealing systems with fluoropolymer-free designs, forcing pump replacement cycles that favor twin screw architectures.
- Marine bunkering infrastructure:Hamburg and Rotterdam port authorities are mandating low-shear fuel oil transfer systems for IMO 2020-compliant very low sulfur fuel handling.
- Multiphase fluid technology:Upstream operators are deploying twin screw pumps for wet-gas compression duties previously reserved for centrifugal units, opening subsea application scope.
Market Restraints
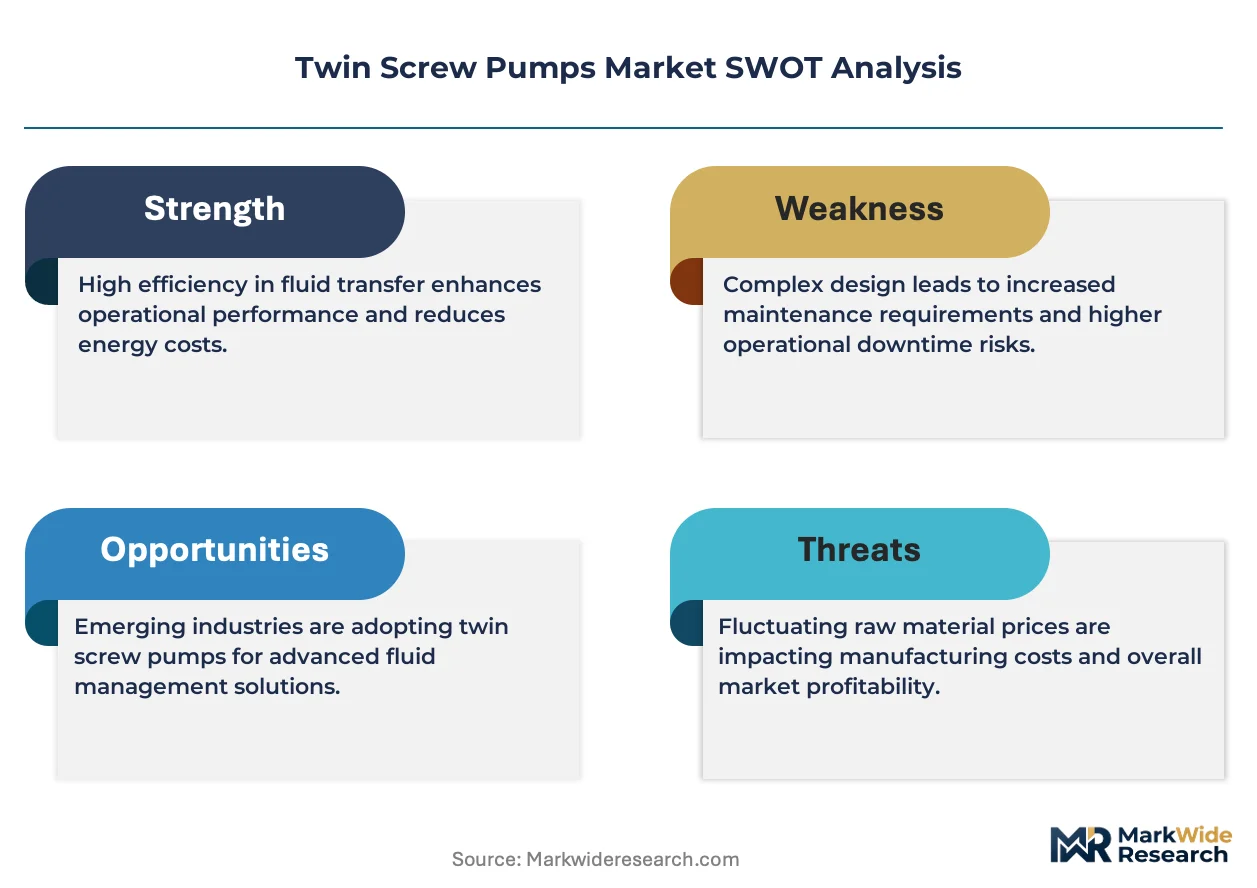
- Nickel and specialty alloy volatility:Stainless steel rotor material costs fluctuate with Indonesian ore export policies, compressing margin buffers for precision-machined components.
- API 676 witnessed testing bottlenecks:Only three North American test facilities maintain third-party accreditation for full-load mechanical run verification, creating queue delays.
- Progressive cavity substitution:Single-rotor progressing cavity pumps capture sub-$50K project budgets in low-pressure crude oil transfer, squeezing twin screw positioning at the specification stage.
Strategic Opportunities
- India PLI scheme for specialty chemicals:Gujarat and Maharashtra state governments are incentivizing integrated petrochemical complexes that require API-compliant positive displacement pumps for polymer slurry duty.
- Carbon border adjustment mechanism:EU importers are sourcing low-carbon-footprint pump systems, creating first-mover advantage for manufacturers with Scope 3-certified supply chains.
- Digital twin integration:Predictive maintenance algorithms fused with vibration-sensor arrays enable performance-based service contracts that capture lifecycle revenue streams.
Industry Challenges
- Precision screw machining talent scarcity:Master grinding technicians capable of maintaining 5-micron profile tolerances on hardened tool steel rotors command premium wages in Saxony and Baden-Württemberg.
- Legacy DCS integration friction:Brownfield refineries running Honeywell TDC 3000 or Yokogawa CENTUM systems require custom Modbus gateway development for smart pump diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twin Screw Pumps Market |
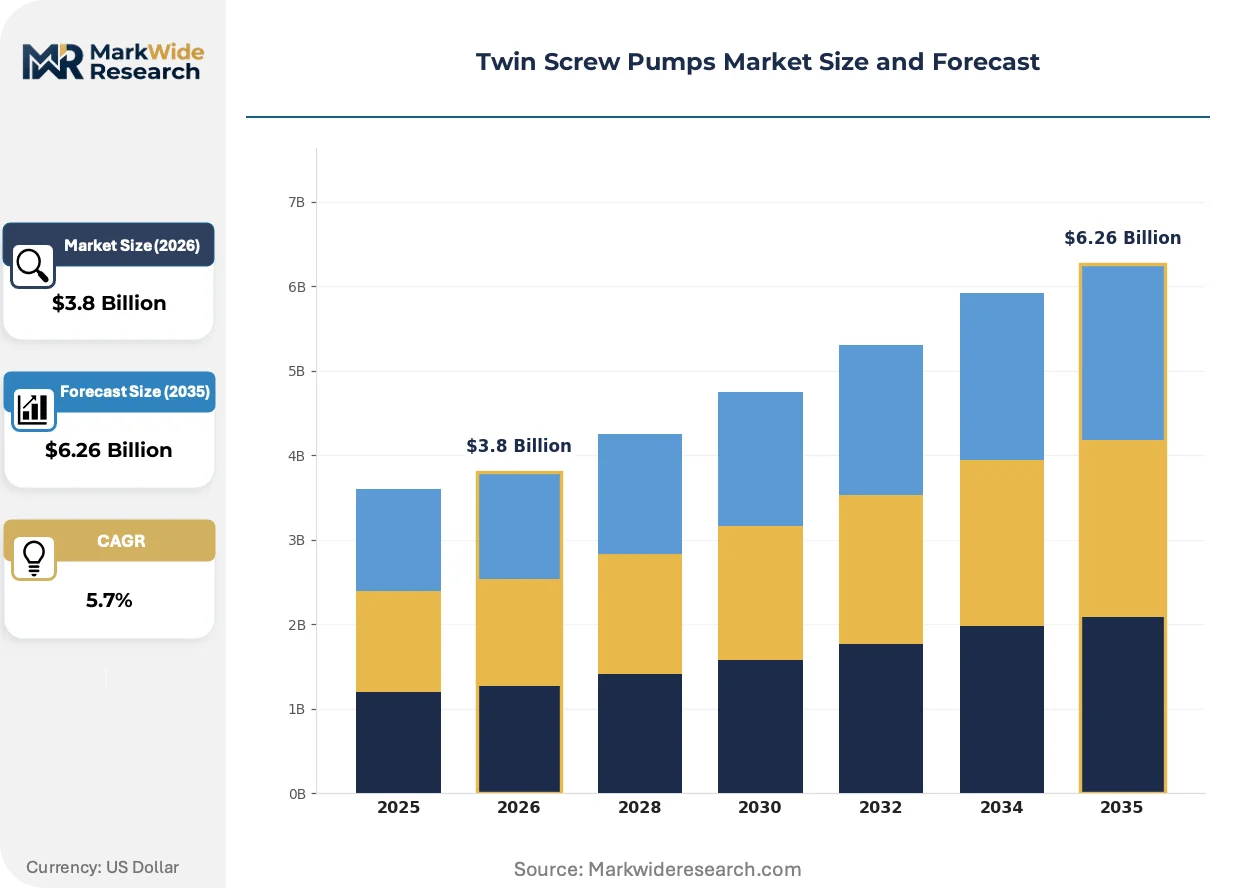
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Vertical, Horizontal, Compact Application: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage End User: Marine, Power Generation, Pulp & Paper, Pharmaceuticals Material: Stainless Steel, Cast Iron, Alloy, Others |
| Companies Covered | Flowserve Corporation, Blackmer, NETZSCH Pumps LLC, Evoqua Water Technologies, NTGD Pump Ltd, Alfa Laval, ITT Bornemann GmbH, Axiflow Technologies, CIRCOR International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twin Screw Pumps Market Evolving Landscape
Material science breakthroughs and digital instrumentation are redefining operational envelopes while regulatory pressure on fugitive emissions accelerates design refresh cycles across petroleum and chemical applications.
Ceramic-coated rotor metallurgy is fragmenting traditional stainless steel dominance in abrasive slurry service. Oil sands operators in Alberta and mining processors in Western Australia are specifying silicon carbide surface treatments that extend wear life by 4-6x in tailings handling. This metallurgical divergence is fragmenting supplier R&D roadmaps into abrasive-resistant versus corrosion-resistant specialization tracks.
The EU F-Gas Regulation is banning hydrofluorocarbon-based sealing systems for pumps handling fluorinated greenhouse gases above 50 bar discharge pressure. German chemical conglomerates are retrofitting existing installations with perfluoroelastomer-free barrier fluid arrangements. Pharmaceutical manufacturers in Basel and Ludwigshafen are absorbing 15-20% capital cost premiums to secure compliance documentation for export shipments.
Refinery procurement teams are unbundling aftermarket service contracts from initial equipment supply, forcing OEMs to compete against independent service providers on spare parts and field overhaul. Middle Eastern national oil companies are segmenting pump supply into capital-only tenders with separate 10-year maintenance agreements. This contractual decomposition is most advanced in Jubail Industrial City and Ruwais refining corridors where operator self-sufficiency mandates dominate.
Twin Screw Pumps Market Segmentation
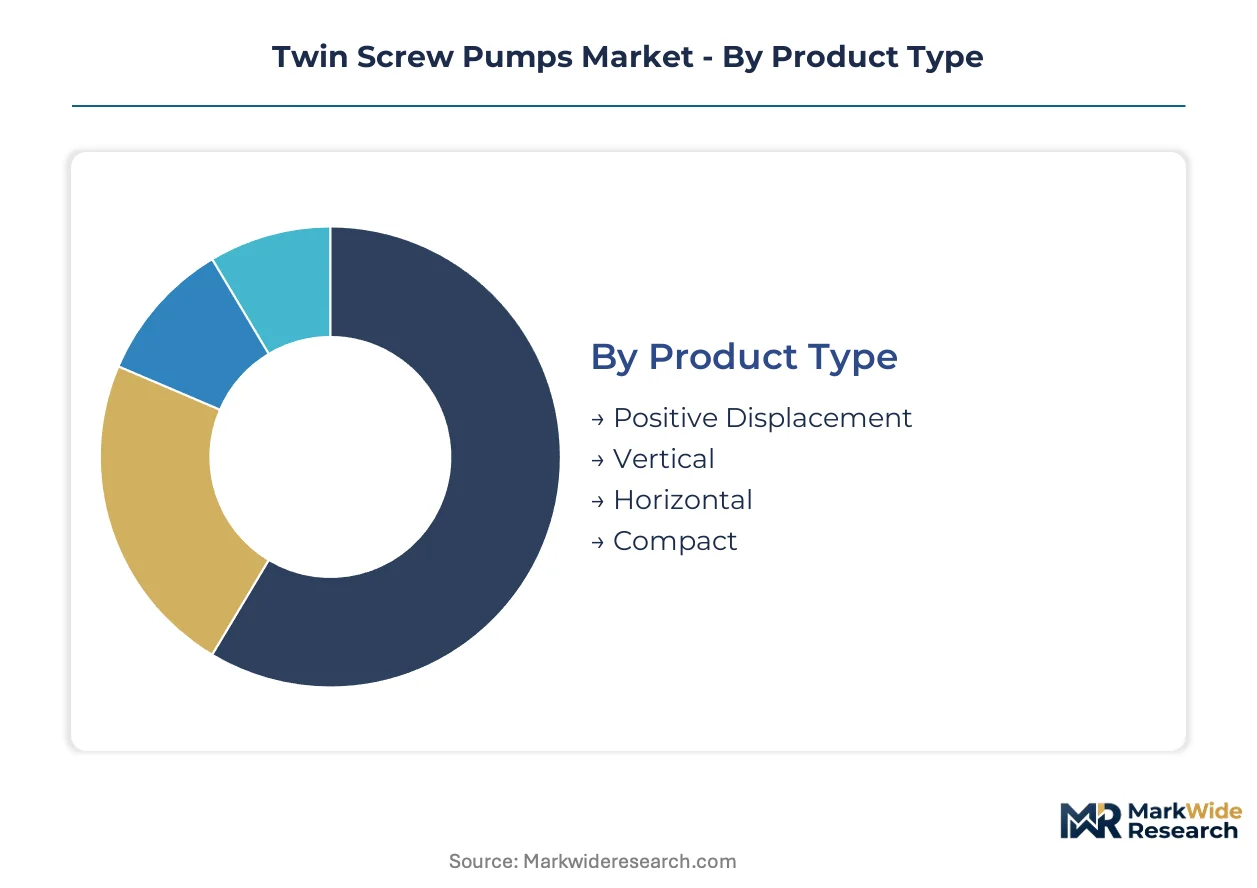
Twin screw pump specification cascades through four critical dimensions that determine performance envelope, regulatory compliance burden, and lifecycle cost structure. Product architecture governs installation footprint and maintenance accessibility. Material selection locks in corrosion resistance and surface finish capabilities for hygienic duties.
Product Type:
Margin pools concentrate in configurations serving high-pressure hydrocarbon transfer and hygienic food processing where API certification and surface documentation command substantial premiums.
- Positive Displacement:These pumps employ intermeshing helical rotors to convey fluids with minimal pulsation across viscosity ranges from 1 cP to 1,000,000 cP. Oil and gas operators in Alberta and the Permian Basin specify these units for multiphase wet-gas compression duties previously reserved for centrifugal alternatives.
- Horizontal:Floor-mounted arrangements dominate refinery and terminal applications where space optimization governs piping layout and maintenance bay design. German chemical processors in Ludwigshafen and Leverkusen favor horizontal configurations for high-viscosity polymer slurry handling.
- Vertical:Space-constrained installations and sump drainage applications drive specification. Offshore platforms in the North Sea deploy vertical pumps for compact skid arrangements.
- Compact:Reduced footprint units serve mobile bunkering and distributed chemical transfer. Port authorities in Rotterdam specify compact designs for IMO 2020-compliant fuel oil handling.
Positive displacement holds installed capacity. Compact is rotating up the share rankings.
Application:
Volume concentration tracks capital expenditure cycles in energy infrastructure and regulatory-driven replacement waves in European chemical processing.
- Oil & Gas:Upstream, midstream, and downstream hydrocarbon handling demands API 676 compliance with witnessed mechanical run testing. Saudi Aramco and ADNOC procurement frameworks segment supply into capital-only tenders with decoupled maintenance agreements.
- Chemical Processing:High-viscosity fluid handling and shear-sensitive product transfer dominate. REACH and EU F-Gas Regulation are forcing fluoropolymer-free sealing retrofits across BASF and Covestro facilities.
- Water Treatment:Sludge handling and polymer dosing applications specify abrasion-resistant rotor geometries. Australian mining processors deploy ceramic-coated units for tailings duty.
- Food & Beverage:Hygienic surface finish requirements and traceability documentation justify substantial price premiums. Swiss and Danish dairy processors mandate 3-A sanitary standards.
Chemical processing is climbing the fastest as European regulatory deadlines compress replacement cycles. Oil and gas retains the deepest installed base.
End User:
Customer-type profitability diverges sharply between specification-intensive marine contracts and price-sensitive pulp applications.
- Marine:IMO 2020 compliance and low-shear fuel oil transfer requirements dominate procurement. Hamburg port authority mandates twin screw architectures for very low sulfur fuel handling.
- Pharmaceuticals:Surface finish documentation and batch traceability command premium positioning. Basel manufacturers absorb capital cost premiums for export compliance.
- Power Generation:Fuel oil forwarding and lubrication systems drive specification. Indian state electricity boards under PLI scheme incentives are expanding procurement.
- Pulp & Paper:Black liquor and stock handling applications favor abrasion-resistant metallurgy. Finnish and Swedish mills specify hardened tool steel rotors.
Marine holds installed capacity. Pharmaceuticals is rotating up the share rankings.
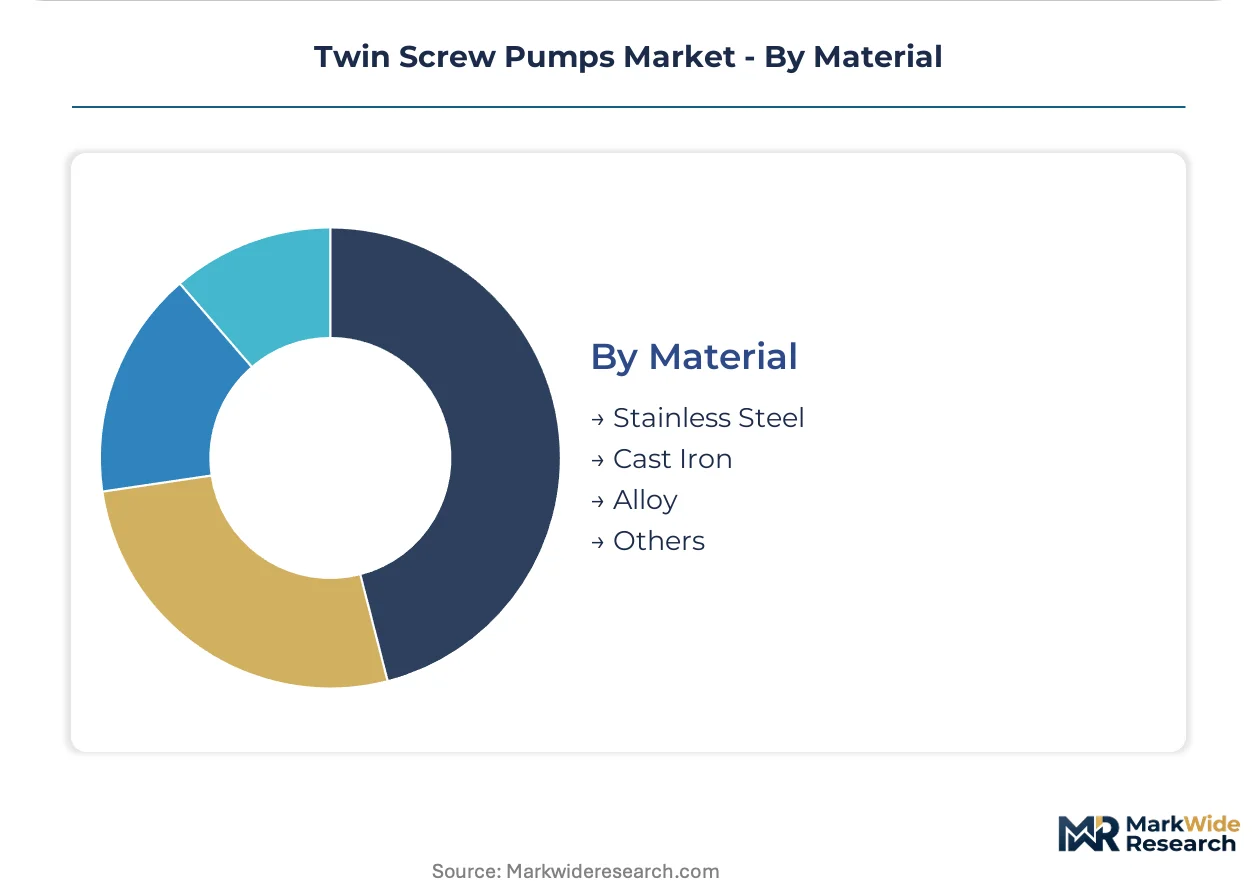
Material:
Cost tier stratification follows corrosion resistance requirements and machining complexity for precision screw profiles.
- Stainless Steel:Austenitic and duplex grades dominate pharmaceutical and hygienic food processing. Surface finish requirements and traceability documentation justify substantial premiums over cast iron alternatives.
- Alloy:Nickel-based and specialty alloys serve high-temperature hydrocarbon and corrosive chemical duties. Indonesian ore export policies generate raw material cost volatility.
- Cast Iron:Standard-duty water treatment and low-pressure transfer applications favor grey iron construction. Cost-sensitive pulp and paper procurement teams specify cast iron for black liquor handling.
- Others:Ceramic coatings and composite materials extend wear life in abrasive slurry service. Oil sands operators in Alberta specify silicon carbide surface treatments.
Stainless steel holds installed capacity. Alloy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical processing cluster and India's PLI scheme for specialty chemicals are redirecting procurement flows toward API-compliant positive displacement pumps. Regulatory deadlines in Europe and capacity buildouts in Asia are compressing vendor qualification timelines.
Germany
Ludwigshafen and Leverkusen chemical complexes are expanding high-viscosity polymer slurry handling capacity. The EU F-Gas Regulation is banning hydrofluorocarbon-based sealing systems above 50 bar discharge pressure, forcing fluoropolymer-free retrofits across BASF and Covestro facilities. Hamburg port authority mandates twin screw architectures for IMO 2020-compliant very low sulfur fuel oil bunkering operations.
United States
Permian Basin operators are deploying twin screw pumps for multiphase wet-gas compression duties previously reserved for centrifugal units. EPA methane emissions protocols are tightening fugitive equipment standards for petroleum handling infrastructure. Only three North American test facilities maintain third-party accreditation for API 676 witnessed mechanical run verification, creating qualification bottlenecks.
India
Gujarat and Maharashtra state governments are incentivizing integrated petrochemical complexes under the PLI scheme for specialty chemicals. The Bureau of Indian Standards is aligning pump safety standards with ISO 13709 for critical hydrocarbon service. Reliance Industries' Jamnagar refinery corridor is segmenting procurement into capital-only tenders with decoupled long-term maintenance agreements.
Saudi Arabia
Saudi Aramco and SABIC are expanding polymer slurry and synthetic fuel production capacity at Jubail Industrial City. The Saudi Food and Drug Authority is harmonizing pharmaceutical equipment standards with EU GMP guidelines for export-oriented manufacturing. Ruwais refining corridor operators are mandating operator self-sufficiency through separate 10-year pump maintenance frameworks.
Australia
Western Australian mining processors are specifying ceramic-coated twin screw pumps for tailings handling in iron ore and lithium extraction. The Therapeutic Goods Administration is tightening surface finish documentation requirements for pharmaceutical export equipment. Oil sands operators in Queensland are adopting silicon carbide rotor treatments that extend wear life by 4-6x in abrasive slurry service.
Twin Screw Pumps Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and regional manufacturing footprint. The vendor base stratifies into three tiers: multinational pump houses with API-certified global footprints, European precision machining specialists with marine engineering heritage, and regional fabricators serving price-sensitive water treatment and pulp applications. Strategic moves center on unbundling aftermarket service contracts from initial equipment supply and expanding witnessed testing capacity to compress qualification queues.
Within the multinational tier, Flowserve Corporation and CIRCOR International occupy positions anchored by multi-continent API-certified manufacturing networks. NETZSCH Pumps LLC exemplifies the European specialist archetype through its German GmbH structure and precision rotor geometry capabilities. ITT Bornemann GmbH represents the marine-focused precision machining tradition concentrated in Lower Saxony. These named entities illustrate how competitive positioning diverges between scale-driven certification breadth and application-specific engineering depth.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Blackmer |
| NETZSCH Pumps LLC |
| Evoqua Water Technologies |
| NTGD Pump Ltd |
| Alfa Laval |
| ITT Bornemann GmbH |
| Axiflow Technologies |
| CIRCOR International |
| Others |
Value Network & Pricing Analysis
Capacity utilization at precision screw machining centers in Lower Saxony and Baden-Württemberg shapes both supply concentration and price floors for API-certified twin screw pumps. German chemical processors and Saudi Aramco procurement teams face extended lead times when these facilities approach maximum throughput, compressing margin buffers for precision-machined rotor geometries.
Pricing Analysis
Certification level creates the primary spread between API 676-compliant units and general industrial pumps. Three-tier pricing structure across premium, standard, and economy levels reflects witnessed mechanical run testing depth, material traceability documentation, and aftermarket service bundling. Price erosion runs through the economy tier as Indonesian nickel ore export policies generate raw material cost volatility. Pulp and paper procurement teams exhibit highest price sensitivity, while pharmaceutical manufacturers in Basel absorb capital cost premiums for hygienic surface finish compliance.
Supply Chain Analysis
Container availability constraints on Hamburg-Rotterdam and Shanghai-Antwerp trade lanes extend inbound logistics cycles for specialty alloy castings. Manufacturing concentration centers on Germany, Italy, and India for precision-machined rotor housings, with China supplying standardized cast iron components. The supply chain draws from Indonesian nickel mines, German tool steel foundries, and Japanese ceramic coating specialists. Single-source vulnerability concentrates in third-party witnessed testing facilities, with only three North American sites maintaining full-load mechanical run accreditation. Distribution runs through OEM-direct channels for API-certified units and regional distributors for water treatment applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The twin screw pumps market represents a high-growth disruption as wet-gas compression technology displaces centrifugal alternatives in upstream oil and gas applications. API 676 compliance timelines and REACH-driven sealing retrofits are compressing vendor qualification windows while expanding addressable market scope.
For Market Incumbents: Compound certification depth across multiple continents to sustain premium positioning against emerging regional fabricators. Expand witnessed testing capacity to compress qualification queues that currently bottleneck Saudi Aramco and ADNOC procurement cycles. Deepen backward integration into precision screw machining to offset master technician wage inflation in Saxony and Baden-Württemberg. For New Entrants and Emerging Players: Lead with ceramic-coated rotor metallurgy for abrasive slurry applications in Western Australian mining and Alberta oil sands, where wear life extension justifies specification against established stainless steel vendors. Target India PLI scheme petrochemical complexes in Gujarat and Maharashtra with API-compliant positive displacement architectures. Pursue digital twin integration partnerships to capture performance-based service contract revenue streams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision machining specialists with captive aftermarket service networks. Long-term viability favors vendors with Scope 3-certified supply chains positioned for EU carbon border adjustment mechanism compliance. Monitor API 676 witnessed testing queue lengths as an inflection indicator for pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Additional witnessed testing facilities reduce qualification bottlenecks for Saudi Aramco tenders. |
| Backward Integration | In-house precision screw machining captures margin from master technician scarcity in Germany. |
| Green Manufacturing Transition | Fluoropolymer-free sealing systems align with EU F-Gas Regulation compliance deadlines. |
| Long-term Supply Agreement | Decoupled maintenance contracts match Jubail Industrial City operator self-sufficiency mandates. |
| Joint Venture | Local manufacturing partnerships satisfy India PLI scheme domestic content requirements. |
Research Methodology
A spread of perspectives from plant engineers at BASF and Covestro, procurement leads at Saudi Aramco and ADNOC, aftermarket service heads at Flowserve and NETZSCH, and technical directors at precision machining shops in Lower Saxony converged on the working assumptions. Primary fieldwork combined with secondary validation from customs data on pump imports, SEC filings of listed pump manufacturers, API certification registries, and EU F-Gas Regulation implementation reports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segmentation dimensions modeled include product architecture, material specification, application duty, and end-user industry across the projection horizon. CAGRs derived from regression analysis against capital expenditure cycles in chemical processing and energy infrastructure. Forecast inputs incorporated REACH compliance retrofit timelines, India PLI scheme incentive disbursement patterns, and IMO 2020 bunkering infrastructure buildouts.
The analysis sits within stated boundaries; outcomes outside sustained nickel price volatility, API 676 accreditation capacity expansion, or carbon border adjustment mechanism implementation would require recalibration. Forecasts reflect assumptions on regulatory enforcement intensity and specialty alloy supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Automatic Tank Cleaning Systems Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Circulators Market