
 Automatic Tank Cleaning Systems Market | 2026-2036
Automatic Tank Cleaning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Tank Cleaning Systems Market Analytics
Modular skid-mounted cleaning packages is expanding as buyers favor configurable systems over fixed permanent installations. Alfa Laval leverages its marine equipment heritage to dominate portable system configurations for vessel tank maintenance. Veolia sustains integrated service contracts that bundle cleaning hardware with waste recovery, locking in long-term industrial accounts. Schlumberger anchors its position through upstream oilfield relationships, extending automated tank cleaning into drilling mud and completion fluid storage.
Automatic tank cleaning systems deploy high-pressure rotary jet heads, chemical injection manifolds, or robotic crawler units to remove sludge, scale, and residual product from confined storage vessels without human entry. Operating pressures typically range from 150 to 2,500 bar depending on deposit hardness and tank geometry, with closed-loop designs separating solids and recycling wash fluids to minimize effluent. Fixed systems capture the largest installed base among product configurations, reflecting decades of refinery and terminal infrastructure buildout. Robotic systems represent the fastest-expanding technology category, as magnetic-track crawlers and submersible remotely operated units penetrate hazardous environments previously requiring confined-space human labor.
The US EPA enforces Clean Water Act discharge standards that compel facilities to adopt closed-loop cleaning with zero liquid discharge capabilities. REACH and the EU Industrial Emissions Directive mandate chemical inventory tracking and waste minimization, steering European buyers toward systems with automated dosing and recovery. India's CPCB and state pollution control boards are tightening hazardous waste handling rules for petroleum storage tanks. Stakeholders must weigh capital intensity against regulatory penalty exposure when selecting between retrofit portable units and greenfield fixed installations.
Market Dynamics
Closed-loop zero-liquid-discharge configurations are restructuring capital allocation across petroleum storage infrastructure as EPA enforcement intensifies discharge compliance costs for Gulf Coast terminal operators.
Growth Catalysts
- REACH chemical tracking mandates:European refineries face mandatory inventory documentation under ECHA guidelines, accelerating replacement of manual cleaning with automated dosing systems that generate audit-ready batch records.
- CPCB sludge handling tightening:India's western coastal corridor confronts stricter hazardous waste protocols for tank bottom residues, compelling Mumbai and Gujarat port clusters to install automated separation and solids recovery modules.
- Magnetic-track robotics:Submersible remotely operated units eliminate confined-space human entry in hazardous environments, penetrating previously inaccessible tank geometries in chemical and petrochemical storage.
Market Restraints
- High-pressure pump supply concentration:Precision pump assemblies for 150-2,500 bar operating ranges source from a concentrated German and Italian supplier base, exposing buyers to extended lead times and input cost volatility.
- Skid-mounted system standardization gaps:Absence of unified ISO interface specifications between modular package providers forces costly custom integration engineering at each installation site.
- Fixed installation retrofit economics:Existing refinery infrastructure built around permanent cleaning circuits creates asset-stranding risk that slows adoption of portable configurable alternatives despite operational flexibility advantages.
Strategic Opportunities
- Drilling mud storage automation:Upstream oilfield completion fluid tanks represent an underpenetrated application segment where closed-loop cleaning can extend equipment life and reduce non-productive time during rig mobilization.
- Service contract bundling:Waste recovery integration with hardware provisioning creates recurring revenue streams and locks in long-term industrial accounts through chemical recovery value-sharing arrangements.
- EU Industrial Emissions Directive alignment:Waste minimization scoring in environmental permitting creates preferential treatment for facilities deploying automated dosing and solvent recovery systems.
Industry Challenges
- Confined-space robotics technician scarcity:Magnetic-track crawler maintenance and submersible unit programming require specialized skill sets that outpace vocational training pipeline output in key manufacturing geographies.
- Legacy tank geometry incompatibility:Older storage vessels with non-standard manway configurations and internal obstructions resist retrofit of standardized robotic cleaning packages without costly structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Tank Cleaning Systems Market |
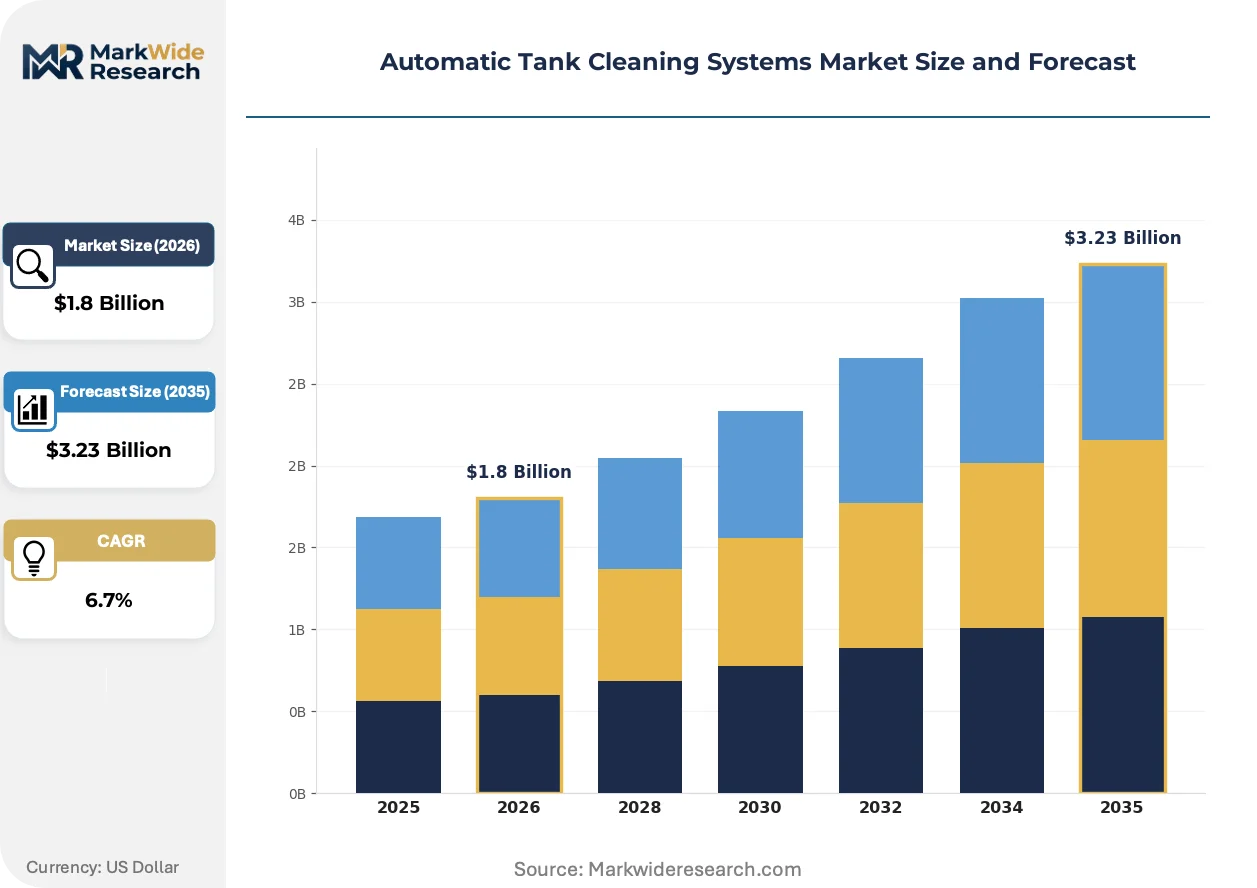
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed System, Portable System, Robotic System, Manual System Technology: Hydro Jetting, Chemical Cleaning, Ultrasonic Cleaning, Foam Cleaning Application: Oil & Gas, Chemical Reservoirs, Water Treatment, Food Processing End User: Industrial Sector, Marine Sector, Agricultural Sector, Waste Management |
| Companies Covered | Veolia, Tradebe, Alfa Laval, Butterworth, Jereh Group, Scanjet Group, ARKOIL Technologies, Clean Harbors, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Tank Cleaning Systems Market Evolving Landscape
Rotary jet head technology is consolidating market position as high-pressure water-based methods displace solvent-dependent cleaning regimes across petroleum and chemical storage applications.
Self-indexing rotary jet head assemblies are consolidating their dominance in crude oil and refined product tank cleaning by delivering 360-degree impingement coverage without mechanical articulation. Midstream terminal operators in the US Gulf Coast are standardizing on 500-1,500 bar configurations for paraffin and asphaltene removal. This hardware simplification is consolidating supplier margins by reducing moving parts count and extending mean time between maintenance events.
REACH authorization requirements for solvent-based cleaning formulations are compressing chemical option sets available to European tank maintenance contractors. ECHA substance evaluation timelines are extending lead times for novel cleaning chemistry approvals. Refinery maintenance planners are responding by accelerating validation of surfactant-free high-pressure water processes that eliminate chemical inventory compliance burdens entirely.
Integrated service contracting is displacing equipment-only procurement as terminal operators seek to transfer operational risk and waste liability to specialized vendors. Bundled agreements covering cleaning hardware deployment, effluent treatment, and recovered product handling are capturing preference among integrated oil companies with complex multi-site tank farms. This arrangement concentrates most visibly in Germany and the Netherlands where extended producer responsibility frameworks impose downstream accountability for cleaning waste streams.
Automatic Tank Cleaning Systems Market Segmentation
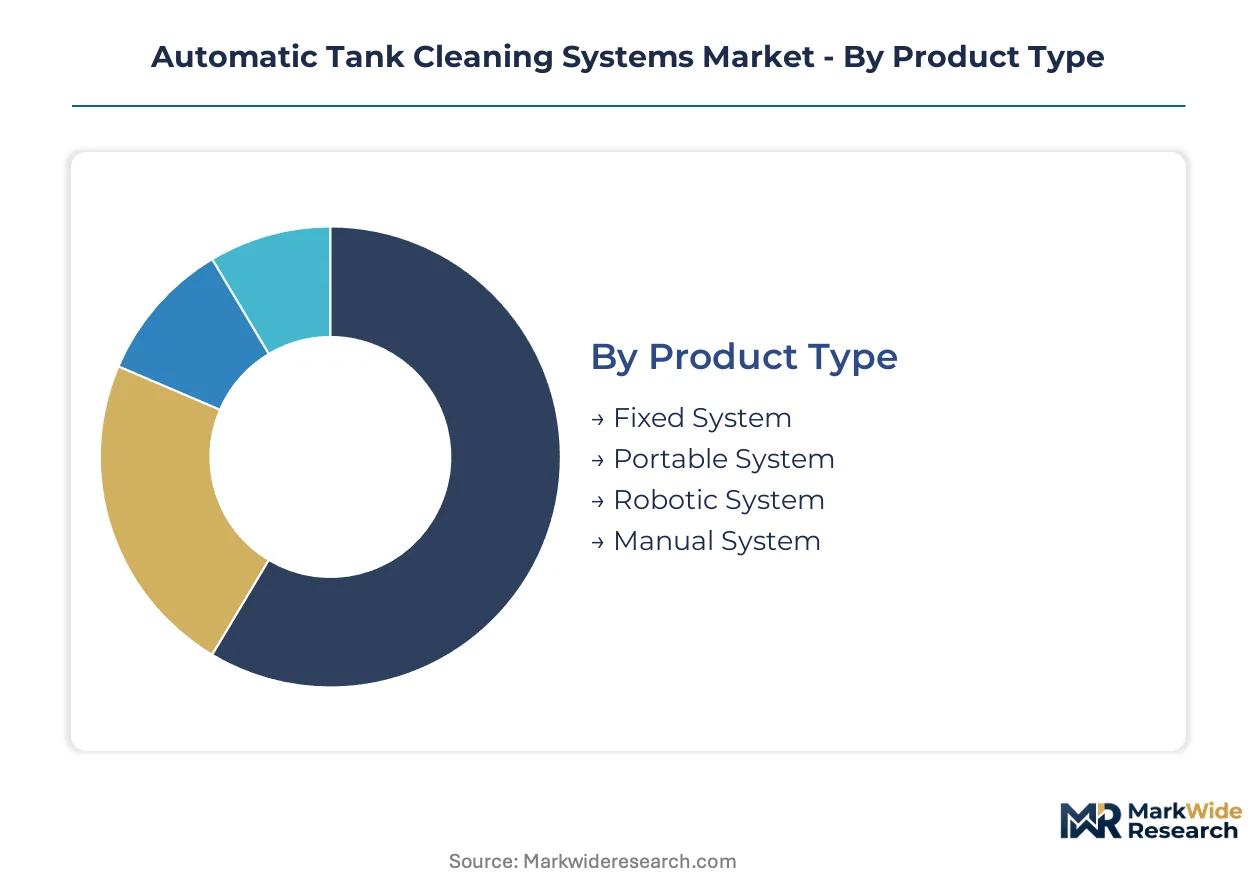
Segmentation in automatic tank cleaning systems reveals how capital intensity, regulatory exposure, and operational risk tolerance shape procurement decisions across petroleum terminals, chemical plants, and marine vessels. Buyers navigate trade-offs between permanent infrastructure investments and flexible service-based arrangements.
Product Type:
Customization spans from fully engineered permanent installations to rapidly deployable modular packages, with standardization concentrated in mid-pressure portable configurations.
- Fixed System:Permanent installations integrate high-pressure pump skids, rotary jet head manifolds, and closed-loop recovery circuits into terminal infrastructure. Demand clusters at US Gulf Coast refineries where EPA Clean Water Act enforcement mandates zero-liquid-discharge compliance and asset owners amortize capital over decades-long operational lifespans.
- Robotic System:Magnetic-track crawlers and submersible remotely operated units eliminate confined-space human entry in hazardous chemical and petroleum storage. Germany's Federal Water Act and REACH obligations are accelerating replacement of manual cleaning methods in European refineries where chemical inventory tracking creates compliance burdens.
- Portable System:Skid-mounted configurable packages serve intermittent cleaning schedules and multi-site operators. India's western coastal corridor ports favor these for CPCB-mandated sludge handling without permanent infrastructure commitment.
- Manual System:Human-entry cleaning persists in legacy food processing and small-scale agricultural storage where deposit volumes and hazard levels remain manageable.
Leading the category by volume: Fixed System. Growing fastest: Robotic System.
Technology:
Cost tiers separate capital-intensive automated methods from labor-dependent chemical applications, with mid-range hydro jetting capturing the broadest addressable base.
- Hydro Jetting:High-pressure water impingement at 150-2,500 bar removes paraffin, asphaltene, and scale without chemical inventory compliance. US Gulf Coast midstream terminals standardize on 500-1,500 bar configurations for crude oil tank maintenance.
- Chemical Cleaning:Solvent and surfactant formulations target hardened deposits in chemical and petrochemical storage. REACH authorization timelines are compressing available chemistry options and extending approval lead times for European contractors.
- Ultrasonic Cleaning:High-frequency acoustic cavitation serves precision cleaning in food processing equipment and pharmaceutical storage vessels where surface integrity demands exceed mechanical methods.
- Foam Cleaning:Low-moisture surfactant foams penetrate complex tank geometries in dairy and beverage processing where water residue creates contamination risk.
Volume concentration: Hydro Jetting. Steepest expansion trajectory: Ultrasonic Cleaning in food and pharmaceutical applications.
Application:
Customer maturity varies sharply, with petroleum infrastructure representing established demand and water treatment emerging from regulatory-driven upgrade cycles.
- Oil & Gas:Crude storage, refined product terminals, and drilling mud tanks constitute the largest installed base. Closed-loop configurations with solids separation and wash fluid recycling dominate where discharge regulations apply.
- Chemical Reservoirs:Aggressive solvents and reactive intermediates demand robotic or remotely operated systems that eliminate human exposure. Magnetic-track crawlers penetrate tanks with internal obstructions and non-standard geometries.
- Water Treatment:Municipal and industrial wastewater storage requires periodic sludge removal. India's CPCB norms are tightening protocols for hazardous waste handling in this segment.
- Food Processing:Dairy, beverage, and edible oil storage prioritizes hygienic design and residue elimination. Foam and ultrasonic methods displace mechanical cleaning in allergen-sensitive production environments.
Dominant revenue share: Oil & Gas. Gaining share fastest: Water Treatment under tightening effluent regulations.
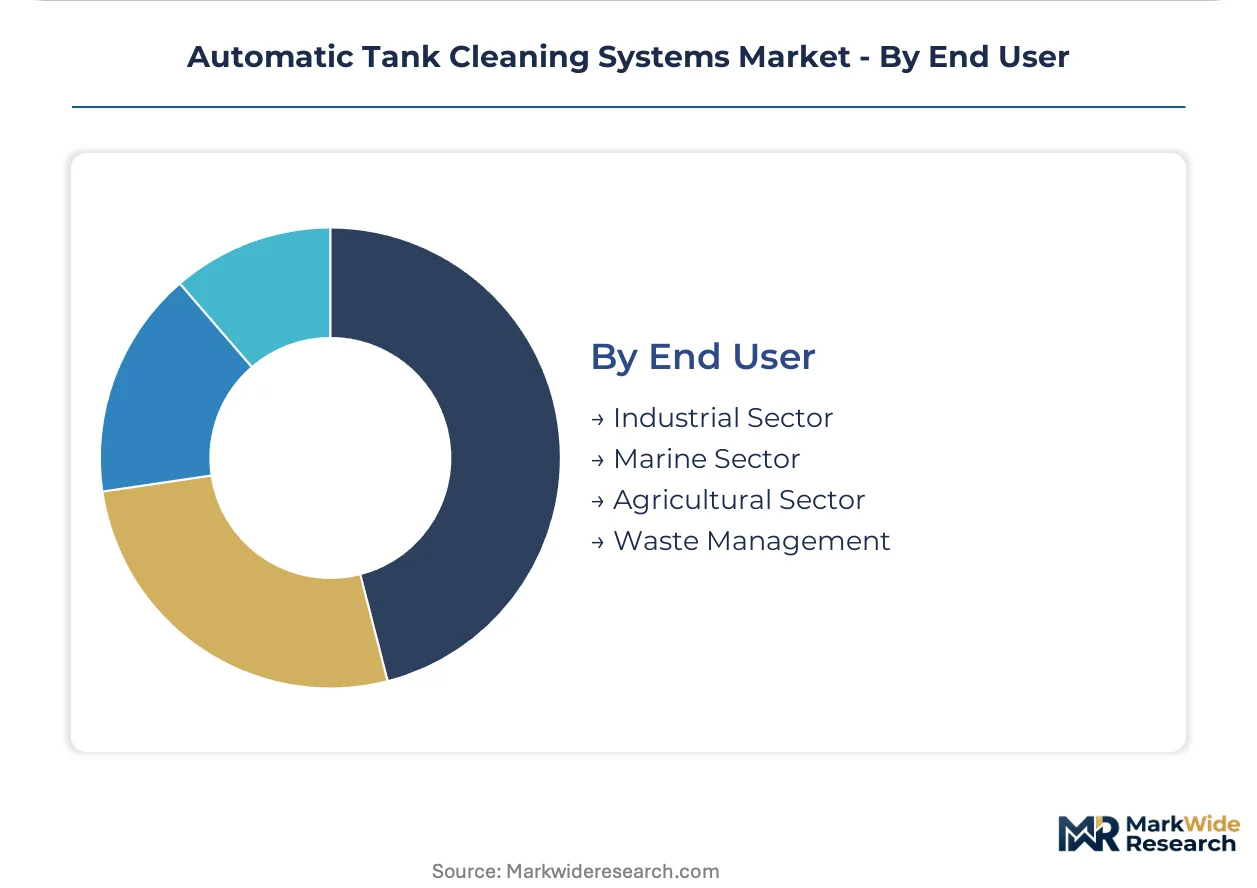
End User:
Supply concentration aligns with sector-specific regulatory frameworks, with industrial petroleum storage commanding premium system configurations.
- Industrial Sector:Petroleum refineries, chemical plants, and bulk liquid terminals drive demand for high-pressure automated systems. Integrated service contracts bundling hardware with waste recovery are displacing equipment-only procurement.
- Marine Sector:Vessel tank maintenance and offshore platform storage require portable configurations compatible with mobilization schedules. Alfa Laval's marine equipment heritage positions portable systems for this segment.
- Agricultural Sector:Fertilizer, pesticide, and grain storage tanks favor lower-cost manual or semi-automated methods where deposit volumes and hazard levels remain limited.
- Waste Management:Hazardous waste storage and landfill leachate tanks face specialized handling requirements. Extended producer responsibility frameworks in Germany and the Netherlands concentrate integrated service contracting here.
Largest addressable base: Industrial Sector. Expanding most quickly: Waste Management under circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the US Gulf Coast concentrate petroleum terminal infrastructure where EPA enforcement drives closed-loop system adoption. India's western coastal corridor and Germany's Rhine-Ruhr industrial belt anchor demand in their respective regulatory jurisdictions.
United States
Gulf Coast terminal operators face intensifying EPA Clean Water Act discharge enforcement that compels zero-liquid-discharge configurations. The Port of Houston and Corpus Christi refining clusters are retrofitting permanent fixed systems to satisfy effluent limits. Closed-loop designs with solids separation now dominate new capital allocation across Texas and Louisiana storage infrastructure.
Germany
REACH chemical inventory tracking and the Federal Water Act push refineries toward automated dosing systems that eliminate manual tank entry. The Rhine-Ruhr industrial corridor hosts concentrated chemical and petrochemical storage where ECHA compliance burdens accelerate robotic system deployment. Extended producer responsibility frameworks concentrate integrated service contracting in the Netherlands-border regions.
India
Mumbai and Gujarat port clusters confront tightening CPCB hazardous waste protocols for tank bottom sludge handling. Jawaharlal Nehru Port Trust operators favor skid-mounted portable configurations to avoid permanent infrastructure commitments. Western coastal petroleum terminals are automating separation and solids recovery modules under state pollution control board mandates.
China
Yangtze River Delta refining hubs are upgrading storage tank maintenance protocols under MEE environmental enforcement tightening. Ningbo and Shanghai port authorities are standardizing on high-pressure hydro jetting configurations to reduce chemical inventory compliance exposure. State-owned refinery operators are piloting magnetic-track robotic units for hazardous chemical storage applications.
Saudi Arabia
Eastern Province hydrocarbon storage infrastructure is expanding automated cleaning capacity to support downstream petrochemical export growth. Jubail Industrial City terminal operators are importing closed-loop European system designs to align with international operator environmental standards. Saudi Aramco-affiliated storage facilities are bundling hardware procurement with long-term maintenance service contracts.
Automatic Tank Cleaning Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across system configuration tiers. The market structure concentrates around three strategic archetypes: integrated environmental service providers bundling hardware with waste recovery, marine equipment specialists leveraging vessel maintenance heritage, and upstream oilfield technology firms extending into storage applications. Competitive moves center on service contract bundling to lock in recurring revenue and geographic expansion through modular portable system offerings.
Within the integrated environmental services tier, Veolia and Clean Harbors exemplify providers that anchor long-term industrial accounts through waste recovery value-sharing arrangements. Alfa Laval occupies a position among marine heritage specialists, while Schlumberger represents upstream oilfield technology extension into drilling mud and completion fluid storage applications. These three companies illustrate how divergent origin points converge on automated tank cleaning through distinct customer relationship and technology pathways.
| Leading Market Players |
|---|
| Veolia |
| Tradebe |
| Alfa Laval |
| Butterworth |
| Jereh Group |
| Scanjet Group |
| ARKOIL Technologies |
| Clean Harbors |
| Schlumberger |
| Others |
Value Network & Pricing Analysis
Specialized robotics technician pools concentrated in Germany's Rhine-Ruhr corridor and northern Italy feed labor-cost differentials that widen pricing-tier spreads between premium automated systems and economy-grade portable configurations. Buyers in India's western coastal corridor face steeper premiums for rapid-deployment robotic units as vocational training pipelines lag deployment timelines.
Pricing Analysis
Short-lead-time premiums for precision pump assemblies from German and Italian suppliers command 15-25% markups over standard-delivery contracts, while spot inventory of skid-mounted portable systems trades at discounts in oversupplied periods. The dominant pricing structure stratifies across premium, standard, and economy tiers differentiated by automation level and after-sales bundling. Price differentiation hinges on certification grade (ISO 3834 welding standards for pressure vessels) and customization depth for legacy tank geometries. Cost compression in economy portable segments is intensifying because Indian and Chinese manufacturers are expanding standard-configured outputs. Midstream terminal operators exhibit highest price sensitivity due to capital allocation constraints, while integrated oil companies with multi-site portfolios prioritize total-cost-of-ownership over upfront equipment spend.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns that position modular cleaning packages within 72-hour mobilization reach of major petroleum terminals. Manufacturing concentrates in Germany, Italy, and China, with precision high-pressure pump assemblies drawing from concentrated Mittelstand suppliers around Stuttgart and Bologna. Critical inputs include specialty steel alloys for pressure-rated components, ceramic nozzles for rotary jet heads, and magnetic-track crawler subsystems. Single-source vulnerability in ceramic nozzle supply from Japanese specialty ceramics producers exposes lead-time volatility. Distribution runs through authorized service partners that bundle installation commissioning with ongoing maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
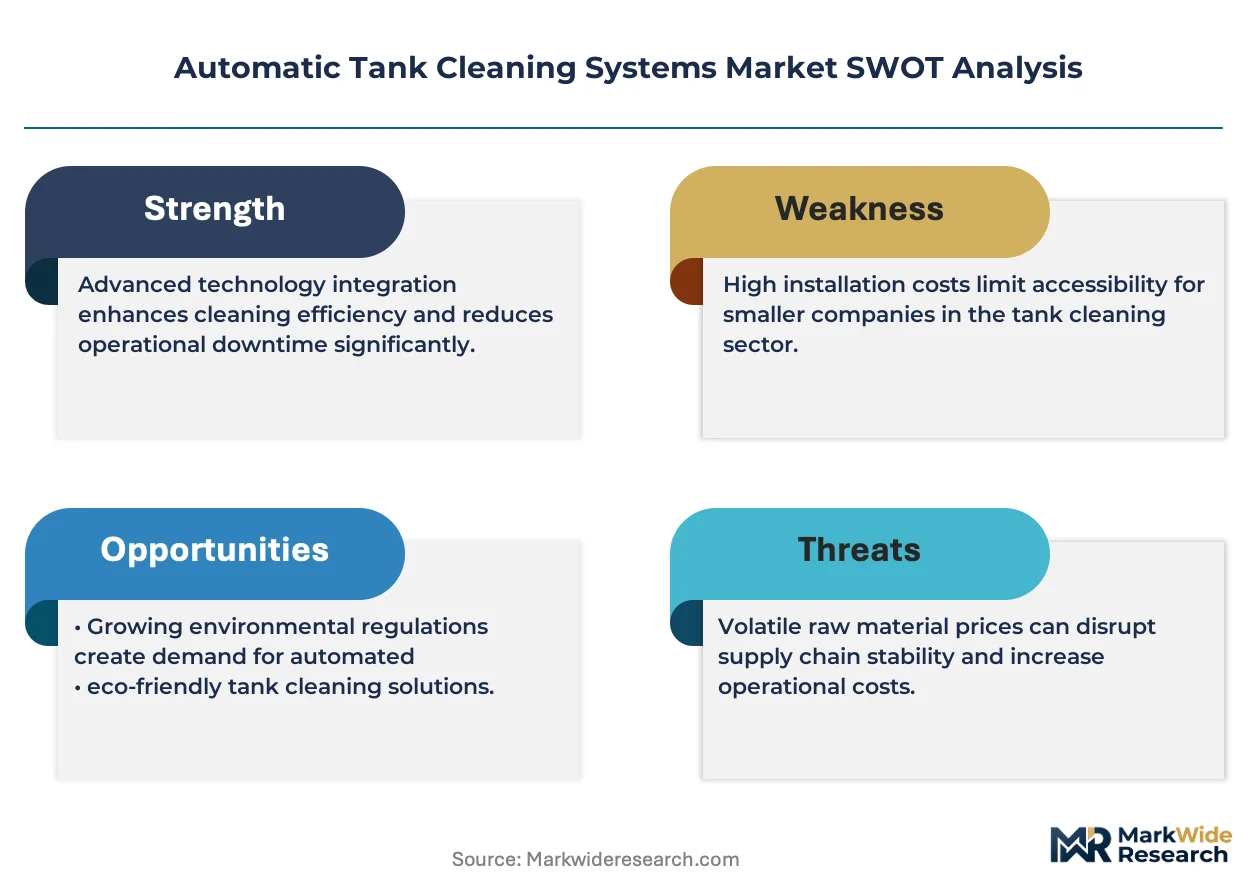
This market represents a consolidation play as REACH compliance burdens and EPA enforcement intensity force capital-constrained regional service providers toward exit or acquisition.
For Market Incumbents: Extend integrated service contract coverage to capture waste recovery value streams and lock in long-term accounts before specialized robotics technician scarcity worsens. Defend position by deepening backward integration into high-pressure pump assembly production to reduce exposure to German-Italian supplier concentration. Prioritize certification investment in ISO 3834 pressure vessel welding standards to maintain premium-tier pricing power against Asian cost competitors. For New Entrants and Emerging Players: Industrial wastewater treatment operators represent the most penetrable channel partner type for co-marketing arrangements that bundle tank cleaning with broader environmental compliance services. Target India's western coastal corridor where CPCB enforcement creates demand acceleration without entrenched incumbent relationships. Pursue white-space in drilling mud storage automation at upstream oilfield sites where Schlumberger's upstream relationships have not fully extended. Go-to-market angle: skid-mounted portable configurations with rapid-deployment guarantees that transfer operational risk from capital-constrained buyers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists possessing captive pump manufacturing and established technician training pipelines given magnetic-track robotics penetration acceleration. Long-term viability favors platforms with waste recovery integration that captures recurring revenue streams beyond equipment cycles. Acquisition target archetype: German or Dutch service contractors with bundled hardware-waste contracts under extended producer responsibility frameworks. Signal to watch: ECHA substance evaluation timelines extending solvent-based cleaning chemistry approvals, which would accelerate high-pressure water process validation and favor capitalized players with R&D bandwidth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Manufacturing | Captive production of 150-2,500 bar assemblies insulates margins from German-Italian supplier concentration. |
| Waste Recovery Value-Sharing Contracts | Integrated service bundling locks in Aramco-affiliated terminals and Rhine-Ruhr chemical storage operators. |
| Magnetic-Track Robotics Certification Programs | Proprietary technician training pipelines address confined-space robotics scarcity in key manufacturing geographies. |
| Skid-Mounted Portable System Standardization | Modular ISO interface development reduces custom integration engineering costs at each installation site. |
| Drilling Mud Storage Automation Partnerships | Upstream oilfield relationships extend equipment life and reduce non-productive time during rig mobilization. |
Research Methodology
Document review covered customs trade data for high-pressure cleaning equipment, EPA enforcement action databases, ECHA substance evaluation timelines, and CPCB hazardous waste handling directives, complemented by interviews with terminal operations managers, refinery maintenance planners, environmental compliance officers, and robotics systems integrators. Secondary validation drew from SEC filings of environmental service providers, EU Industrial Emissions Directive implementation reports, and Indian state pollution control board orders. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts across petroleum storage capacity additions.
Historical deployment patterns for fixed, robotic, and portable configurations were cross-referenced against panel input from procurement directors at integrated oil companies and independent terminal operators. The analytical framework modeled volume and value outputs across product type, technology, application, and end-user dimensions throughout the forecast period. CAGRs were derived from regression analysis of capital expenditure cycles, regulatory enforcement intensity indices, and technician training pipeline outputs. Industry-specific inputs included refinery turnaround schedules, port authority environmental compliance deadlines, and magnetic-track robotics adoption curves in chemical storage applications.
Caveats apply where EPA enforcement intensity recalibration, ECHA authorization timeline acceleration, or ceramic nozzle supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory trajectory and supply chain configuration stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Automatic Tube Cleaning System Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Fire Pump Test Meters Market