
 Pool Heat Pumps Market | 2026-2036
Pool Heat Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Pool Heat Pumps Market Insights
Commercial hospitality operators are bifurcating demand away from traditional residential buyers as hotels and resorts prioritize year-round pool operations. Pentair Plc leverages its distribution network across North American pool service channels. Rheem Manufacturing Company anchors its position through captive production of inverter-driven compressor systems. Hayward Industries Inc. differentiates via integrated automation platforms that pair heat pumps with salt chlorination and filtration controls.
Pool heat pumps are electromechanical systems that extract thermal energy from ambient air, water, or ground sources and transfer it to pool water through refrigerant compression cycles, typically operating with coefficient of performance ratings between four and seven. These units serve the commercial and recreational water heating sector by delivering operational cost advantages over gas-fired boilers in moderate climates. Air source heat pumps dominate installed volume due to simpler site requirements and lower upfront capital outlays, while inverter technology commands expanding share as variable-speed compressors reduce partial-load energy consumption. Geothermal systems occupy a premium niche where stable ground temperatures justify drilling expenditures.
The US Department of Energy enforces minimum efficiency standards under federal appliance regulations, while the EPA's phasedown of hydrofluorocarbon refrigerants is compressing product development timelines for lower-global-warming-potential working fluids. California's Title 24 building energy codes and Florida's statewide pool efficiency guidelines create asymmetric compliance burdens that favor manufacturers with modular refrigerant architectures. Stakeholders must monitor refrigerant transition schedules and regional utility rebate programs to align product portfolios with shifting total-cost-of-ownership calculations.
Market Dynamics
Inverter-driven compressor architectures are compressing product lifecycles as manufacturers race to meet EPA refrigerant phaseout schedules while hospitality operators demand variable-speed efficiency for year-round pool operations.
Growth Catalysts
- Extended Swimming Seasons:Florida, California, and Texas operators justify capital expenditure through twelve-month revenue generation from heated pools.
- Title 24 Compliance:California's building energy codes mandate minimum thermal efficiency thresholds that heat pumps satisfy more readily than gas-fired alternatives.
- Inverter Technology Maturation:Variable-speed compressors reduce partial-load energy consumption by modulating output against ambient temperature fluctuations.
Market Restraints
- Copper and Aluminum Volatility:Heat exchanger materials face price swings that compress manufacturing margins and destabilize quoting cycles.
- Cold Climate Performance Limits:Air-source systems experience coefficient-of-performance degradation below 50°F ambient, restricting addressable markets in northern latitudes.
- Refrigerant Transition Costs:EPA hydrofluorocarbon phasedown forces R&D retooling for lower-global-warming-potential working fluids without immediate price recovery mechanisms.
Strategic Opportunities
- Geothermal Niche Expansion:Stable ground temperatures in the US Mountain West and Northeast justify premium drilling expenditures for commercial installations.
- Utility Rebate Alignment:Regional demand-response programs in Texas and Arizona create channel partnerships for high-efficiency unit deployment.
- Automation Convergence:Integration of heat pump controls with salt chlorination and filtration systems opens bundled service contracts.
Industry Challenges
- Refrigerant Handling Certification:EPA Section 608 technician requirements constrain installer availability and extend project timelines.
- Legacy Control Integration:Proprietary communication protocols between existing pool automation and new inverter systems demand custom programming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pool Heat Pumps Market |
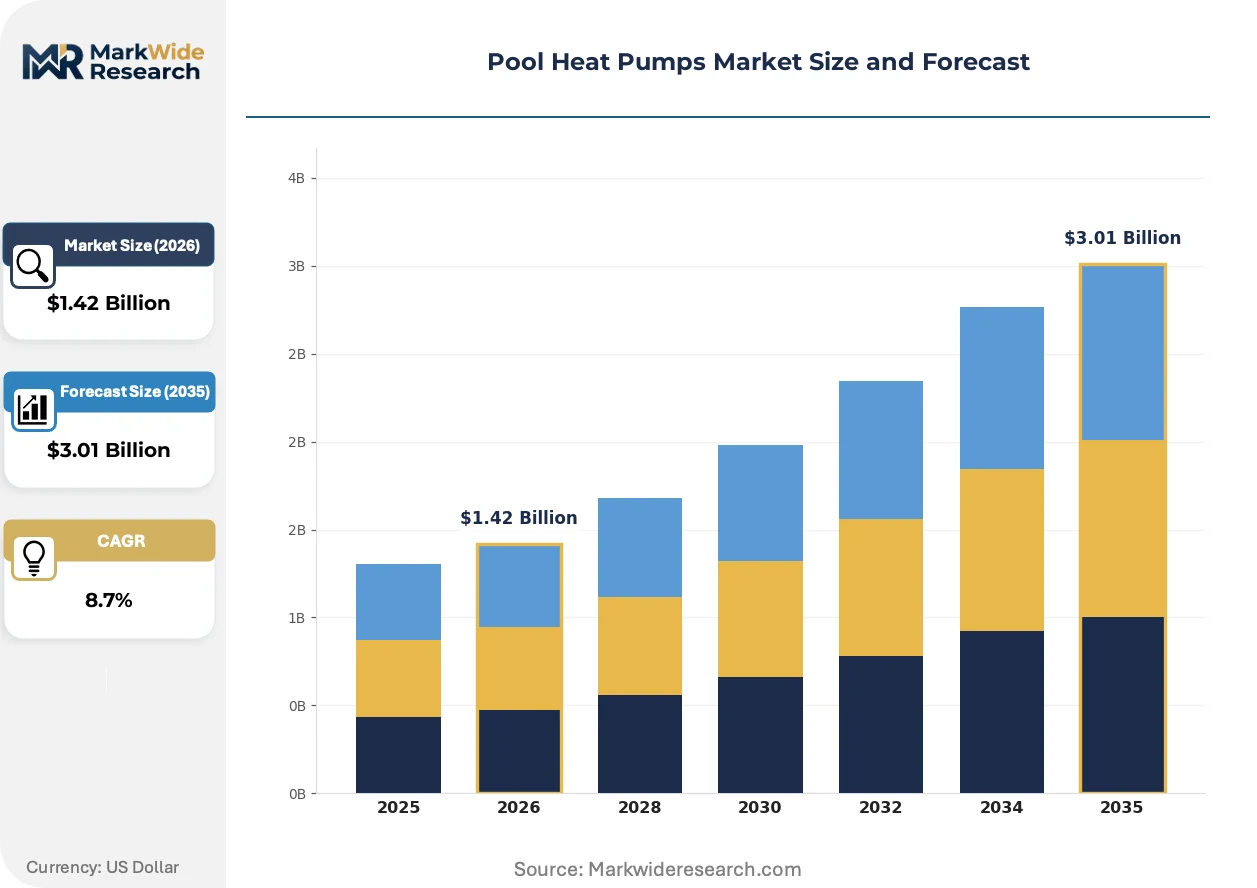
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Geothermal, Solar Source End User: Residential, Commercial, Municipal, Construction Technology: Inverter Technology, Fixed-Speed Technology, Hybrid Technology, Electric Resistance Installation Type: Above Ground, In-Ground, Portable, Permanent |
| Companies Covered | Pentair Plc, Hayward Industries Inc., Rheem Manufacturing Company, EXINDA, Fluidra (Zodiac), AquaCal, Raypak, Madimack, Jandy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pool Heat Pumps Market Trends and Innovations
Refrigerant chemistry and compressor control logic are the primary vectors of product differentiation as efficiency regulations tighten and operator expectations for automation rise.
Inverter-driven variable-speed technology is fragmenting the historical split between single-speed residential units and commercial-grade fixed-speed systems. Mid-market hospitality operators now specify modulating compressors that were previously confined to premium installations. This capability diffusion is compressing price premiums and forcing manufacturers to tier products by control sophistication rather than compressor type alone.
The EPA's hydrofluorocarbon phasedown under the AIM Act is compressing product development timelines for A2L and R-32 refrigerant architectures. Manufacturers must recertify safety systems and pressure ratings while maintaining backward compatibility with existing service infrastructure. Pool equipment suppliers in California face asymmetric compliance burdens as Title 24 amendments accelerate ahead of federal minimums.
Commercial procurement teams are unbundling equipment purchases from installation and maintenance contracts. Large resort operators now source heat pumps through direct manufacturer relationships while contracting regional service providers separately. This disintermediation of traditional pool service channels is most visible in Florida's hospitality corridor, where centralized corporate procurement functions override local dealer preferences.
Pool Heat Pumps Market Segmentation
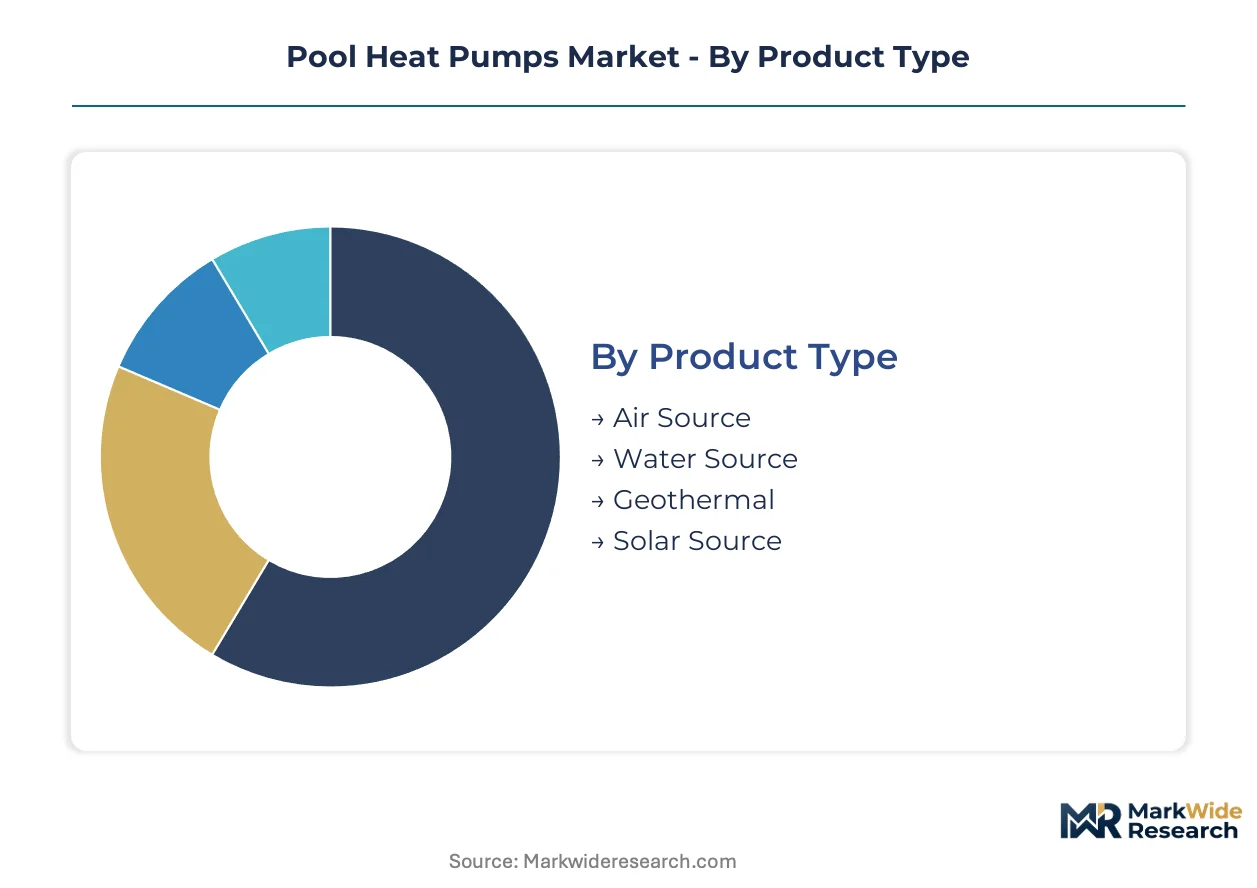
Segmentation in pool heat pumps reveals distinct equipment specifications tied to climate zones, regulatory thresholds, and operational duty cycles. Manufacturers configure product portfolios across these dimensions to capture utility rebate eligibility and hospitality procurement requirements.
Product Type:
Domestic production concentrates on air-source systems for North American moderate climates, while geothermal and water-source variants serve export markets with stricter efficiency mandates or stable ground temperature conditions.
- Air Source:These units extract thermal energy from ambient air through vapor-compression cycles, utilizing finned-tube evaporators and scroll compressors. Demand clusters in Florida, California, and Texas where extended swimming seasons justify capital investment against operating cost savings from coefficient-of-performance ratings between four and seven.
- Geothermal:Ground-coupled systems leverage stable subsurface temperatures through closed-loop heat exchangers, delivering consistent performance independent of seasonal air temperature swings. Commercial installations in the US Mountain West and Northeast justify premium drilling expenditures through year-round operational reliability.
- Water Source:Systems transfer heat to or from adjacent water bodies, requiring proximity to lakes, ponds, or cooling towers. Coastal hospitality properties in California specify these for thermal stability.
- Solar Source:Hybrid configurations pair photovoltaic thermal collectors with electric compression, qualifying for federal investment tax credits. Arizona and Nevada utilities incentivize grid-tied installations.
Air Source holds the largest share; momentum sits with Geothermal as commercial operators prioritize decarbonization commitments.
End User:
Customer type determines equipment sizing protocols, with commercial operators specifying larger tonnage and redundancy requirements than residential buyers.
- Commercial:Hotels and resorts operate units continuously through twelve-month seasons, driving specification of inverter-driven compressors for partial-load efficiency. Procurement teams unbundle equipment from installation contracts, sourcing directly from manufacturers while contracting regional service providers separately.
- Residential:Single-family installations dominate unit volume, with demand concentrated in Sun Belt states where homeowners recover capital costs through extended pool usage windows. EPA Section 608 certification requirements constrain installer availability and extend project timelines.
- Municipal:Public recreation facilities prioritize durability and service accessibility over efficiency premiums, standardizing on fixed-speed architectures with local parts availability.
- Construction:New pool builders specify equipment during project planning phases, creating bundled opportunities with automation and filtration systems.
Residential generates highest unit volume; Commercial commands steepest expansion trajectory as hospitality operators electrify pool heating.
Technology:
Control sophistication now tiers products more than compressor type alone, as variable-speed capability diffuses from premium to mid-market specifications.
- Inverter Technology:Variable-speed compressors modulate refrigerant mass flow against ambient temperature and pool load conditions, reducing partial-load energy consumption by thirty to fifty percent compared to fixed-speed alternatives. California Title 24 compliance mandates accelerate specification in new construction.
- Fixed-Speed Technology:Single-stage compressors cycle on full capacity to maintain setpoints, offering lower capital cost but higher operating expense in variable climates. These units retain share in price-sensitive residential segments and municipal procurement.
- Hybrid Technology:Dual-fuel configurations combine heat pump operation with gas-fired backup for cold-weather performance, addressing coefficient-of-performance degradation below fifty degrees Fahrenheit.
- Electric Resistance:Direct immersion elements provide supplemental heating or standalone operation in small above-ground installations where compressor-based systems prove economically unjustified.
Fixed-Speed retains installed base dominance; Inverter Technology gains share fastest as efficiency regulations tighten and utility rebates reward variable-speed operation.
Installation Type:
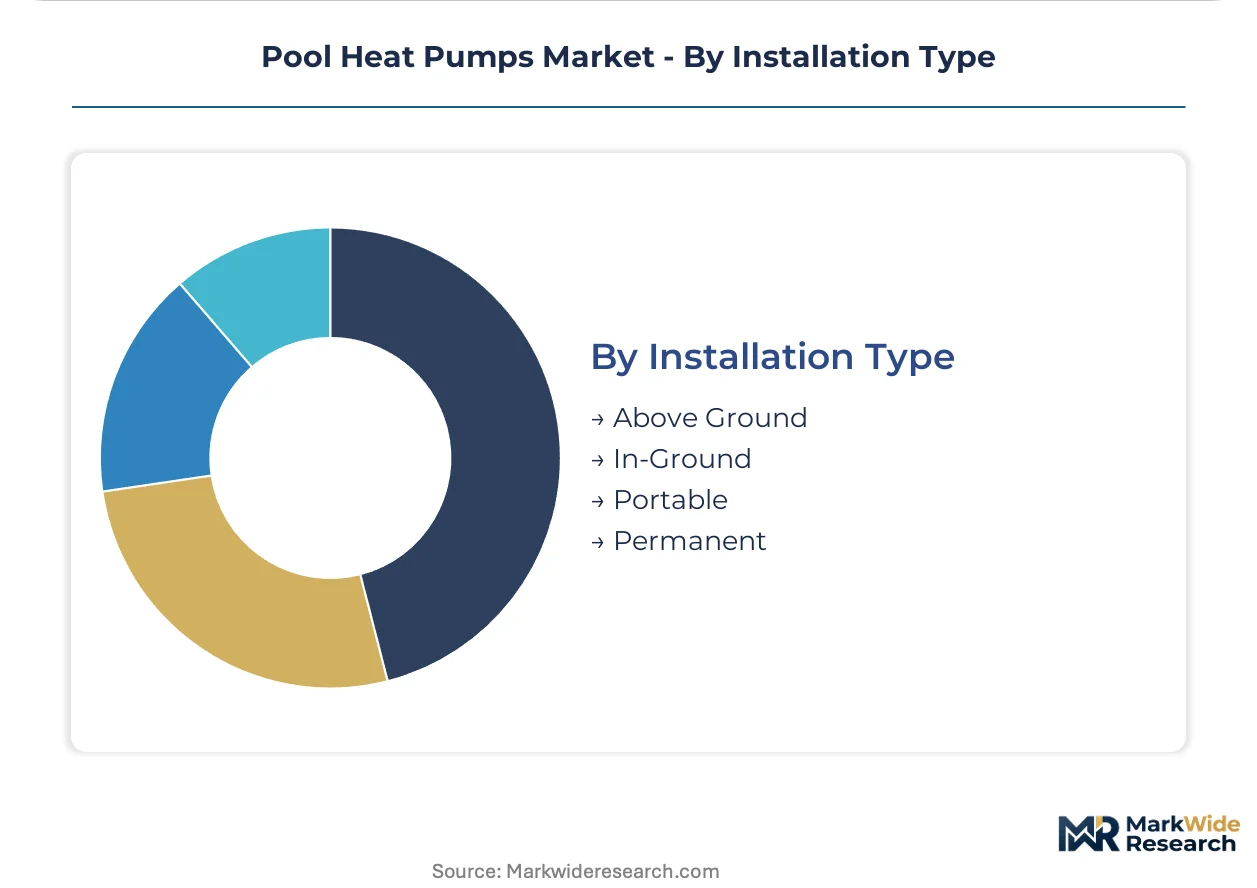
Site configuration dictates equipment form factor and plumbing integration requirements, with permanent installations representing the revenue core and portable units serving niche applications.
- In-Ground:Permanent equipment pads adjacent to buried pool structures accommodate largest tonnage units with dedicated electrical service and hard-piped hydronic connections. These installations dominate commercial hospitality and high-end residential markets.
- Above Ground:Compact packaged units serve elevated pool structures with simplified plumbing and lower total system cost, concentrating demand in seasonal residential markets.
- Permanent:Fixed equipment with weather-rated enclosures and pad-mounted construction represents standard specification for climate zones with freeze risk.
- Portable:Self-contained units with quick-connect hoses serve rental properties and temporary installations, though limited efficiency and durability constrain market penetration.
In-Ground captures greatest value per installation; Above Ground expands most quickly as entry-level pool ownership rises in warm-climate states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers supply heat pump compressors and heat exchangers to North American pool equipment assemblers, while European component specialists export inverter drives and electronic controls to hospitality retrofit projects across the Sun Belt.
United States
Florida, California, and Texas hospitality operators drive demand for year-round pool heating systems. The EPA's hydrofluorocarbon phasedown under the AIM Act compresses product development timelines for lower-global-warming-potential refrigerants. Miami-Dade and Orange County resort corridors concentrate procurement activity as centralized corporate buyers unbundle equipment from installation contracts.
Canada
Ontario and British Columbia pool builders specify hybrid heat pump systems for shortened outdoor swimming seasons. Natural Resources Canada's ENERGY STAR certification program rewards variable-speed compressor installations with utility rebate eligibility. The Greater Toronto Area anchors distribution networks serving seasonal residential markets with cold-climate performance specifications.
Mexico
Baja California and Quintana Roo resort developments import US-assembled heat pump systems for coastal hospitality properties. The country's national energy efficiency regulator maintains alignment with US Department of Energy appliance standards. Cancun and Los Cabos tourism corridors concentrate commercial installations requiring corrosion-resistant coastal specifications.
Germany
Baden-Württemberg and Bavaria manufacturers supply inverter drive technology and electronic control systems to global pool equipment producers. The EU F-Gas Regulation mandates refrigerant transition schedules that accelerate ahead of federal US timelines. Stuttgart industrial clusters specialize in variable-speed compressor controllers for export markets.
Australia
Queensland and New South Wales residential pool owners replace gas-fired heaters with air-source heat pumps amid rising natural gas tariffs. The country's national energy regulator administers state-level rebate programs for high-efficiency pool heating equipment. Sydney and Brisbane metropolitan areas concentrate installer certification programs addressing EPA Section 608 equivalent technician requirements.
Pool Heat Pumps Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive compressor manufacturing and specialized pool equipment pure-plays with integrated automation platforms. Market structure consolidates around three to five vertically integrated assemblers controlling North American distribution channels, while regional fabricators compete on price in replacement markets. Two dominant archetypes emerge: full-line pool equipment suppliers bundling heat pumps with filtration and control systems, and HVAC-origin manufacturers leveraging inverter compressor expertise. Competitive moves center on refrigerant architecture recertification and direct procurement relationships with hospitality chains.
Among diversified industrial suppliers, Pentair Plc and Rheem Manufacturing Company exemplify scale-driven positions, while Hayward Industries Inc. occupies a specialized tier. Pentair leverages established distribution across North American pool service channels. Rheem anchors its position through captive production of compressor systems. Hayward differentiates via integrated automation platforms that pair heating equipment with water treatment controls.
| Leading Market Players |
|---|
| Pentair Plc |
| Hayward Industries Inc. |
| Rheem Manufacturing Company |
| EXINDA |
| Fluidra (Zodiac) |
| AquaCal |
| Raypak |
| Madimack |
| Jandy |
| Others |
Pricing and Supply Chain Analysis
EPA Section 608 certification requirements gate both installer qualification and price differentiation simultaneously, constraining service channel capacity while segmenting the market between certified premium installations and uncertified economy alternatives. This regulatory threshold compresses margins on entry-tier fixed-speed units while protecting pricing power for inverter-driven systems requiring specialized commissioning.
Pricing Analysis
Fixed-speed legacy systems, current inverter-driven architectures, and emerging A2L refrigerant platforms command distinct price bands across the installed base. Pricing stratifies across premium, standard, and economy tiers based on compressor control sophistication and refrigerant architecture maturity. Cost compression in fixed-speed residential segments is intensifying because Chinese component imports and distributor consolidation squeeze quoting flexibility. Municipal procurement teams exhibit highest price sensitivity through competitive bidding mandates, while commercial hospitality operators prioritize total-cost-of-ownership metrics over upfront capital outlay.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on transpacific trade lanes have extended lead times for scroll compressor imports from Chinese foundries. Manufacturing concentration centers on China for compressor castings, Mexico for final assembly serving North American demand, and Germany for inverter drive electronics. Heat exchanger production rests on copper tube mills in Chile and aluminum fin stock from domestic US rolling operations. Single-source vulnerability in rare-earth permanent magnets for high-efficiency compressor motors threatens supply continuity. Distribution runs through captive dealer networks controlled by Pentair, Hayward, and Rheem, with independent pool service contractors handling replacement market fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pool heat pumps market is accelerating through a regulatory-inflected disruption as EPA hydrofluorocarbon phasedown timelines compress product development cycles and force premature obsolescence of R-410A refrigerant architectures.
For Market Incumbents: Secure backward integration into inverter drive controller production to protect margin structure against German electronics supplier pricing power. Anchor dealer loyalty through exclusive refrigerant transition training programs that lock service capacity ahead of A2L certification requirements. Defend against HVAC-origin entrants by accelerating automation platform convergence with salt chlorination and filtration controls. For New Entrants and Emerging Players: Lead with geothermal system specialization targeting Mountain West commercial installations where stable ground temperatures justify premium drilling expenditures and incumbent coverage remains thin. Target municipal recreation facilities in cold-climate states with hybrid heat pump-gas configurations addressing coefficient-of-performance degradation below fifty degrees Fahrenheit. Establish channel partnerships with electrical contractors holding EPA Section 608 credentials rather than competing for limited pool service technician capacity. For Investors and Strategic Acquirers: The EPA's AIM Act refrigerant transition reshapes the acquisition landscape by devaluing R-410A product lineups and privileging A2L-ready manufacturing footprints. Five-to-ten-year viability hinges on captive compressor controller technology and modular refrigerant architectures permitting rapid chemistry pivots. Monitor California Title 24 amendment schedules as the leading indicator of asymmetric compliance burdens that will propagate to other Sun Belt jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| A2L Refrigerant Architecture Certification | EPA AIM Act compliance enables continued market access across all fifty states. |
| Inverter Drive Controller Integration | Captive production of variable-speed electronics reduces dependency on Stuttgart industrial suppliers. |
| Direct Hospitality Procurement Relationships | Corporate unbundling of equipment from installation contracts bypasses traditional dealer markups. |
| Geothermal Loop Installation Capability | Mountain West drilling expertise opens premium commercial niches with limited incumbent presence. |
| Utility Rebate Program Alignment | Texas and Arizona demand-response partnerships create channel preference for high-efficiency specifications. |
Research Methodology
A standing panel of pool equipment distributors, commercial hospitality procurement directors, EPA-certified installation contractors, and inverter drive electronics engineers provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings of publicly traded pool equipment manufacturers, US Department of Energy appliance efficiency rulemaking dockets, and California Energy Commission Title 24 proceeding records. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across the analysis window.
Consistency checks validated volume and value outputs against utility rebate program deployment data and regional building permit databases tracking new pool construction. The analytical framework modeled segmentation across product type, end user category, compressor technology tier, and installation configuration throughout the forecast period. CAGRs derived from regression analysis of historical efficiency standard adoption curves and hospitality capital expenditure cycles. Refrigerant transition schedules and regional utility incentive program budgets served as key exogenous inputs.
Forecasts assume regulatory continuity in EPA AIM Act phasedown timelines and California Title 24 amendment trajectories; material policy shifts would require re-modeling. Commodity price volatility in copper and aluminum, installer certification bottlenecks, and cold-climate performance limitations represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
End Suction Pump Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Flow Back Equipment Market