
 Catalyst Bins Market | 2026-2036
Catalyst Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Catalyst Bins Market Analysis
A capital-intensity divergence between in-house fabrication capabilities and outsourced specialty manufacturing is redrawing competitive boundaries in catalyst containment. Hoover Ferguson Group leverages its integrated steel fabrication and coating operations to sustain pricing power on large-format modular bins. CHEP competes through pooled container networks that reduce capital deployment for downstream chemical operators. Paul Mueller Company anchors its position with ASME-certified pressure-rated designs that dominate high-temperature catalyst regeneration cycles.
Catalyst bins are engineered containment vessels, typically fabricated from carbon steel with internal epoxy or rubber linings, designed to store, transport, and discharge particulate catalysts while preventing contamination, moisture ingress, and hazardous vapor release. Standard bin configurations remain the volume backbone across refinery and chemical plant operations, though custom bins command premium margins where reactor geometry demands non-standard discharge angles or integrated heating jackets. Metal construction, predominantly stainless and carbon steel variants, occupies the dominant share by value due to thermal cycling durability and compatibility with pyrophoric catalyst handling protocols.
EPA Resource Conservation and Recovery Act container requirements and OSHA PSM standards govern material thickness, venting, and secondary containment specifications for catalyst bins used in hazardous service. The Department of Transportation 49 CFR hazmat packaging rules further constrain transportation-oriented designs, particularly for spent catalyst streams classified as regulated wastes. Stakeholders must monitor evolving state-level air quality mandates in Texas and California, where tighter volatile organic compound controls around catalyst changeouts could accelerate demand for sealed, vapor-recovery-integrated bin systems.
Market Dynamics
Refinery expansion cycles along the US Gulf Coast are compressing procurement timelines for corrosion-resistant containment systems, forcing fabricators to reconcile EPA hazardous waste standards with just-in-time delivery commitments.
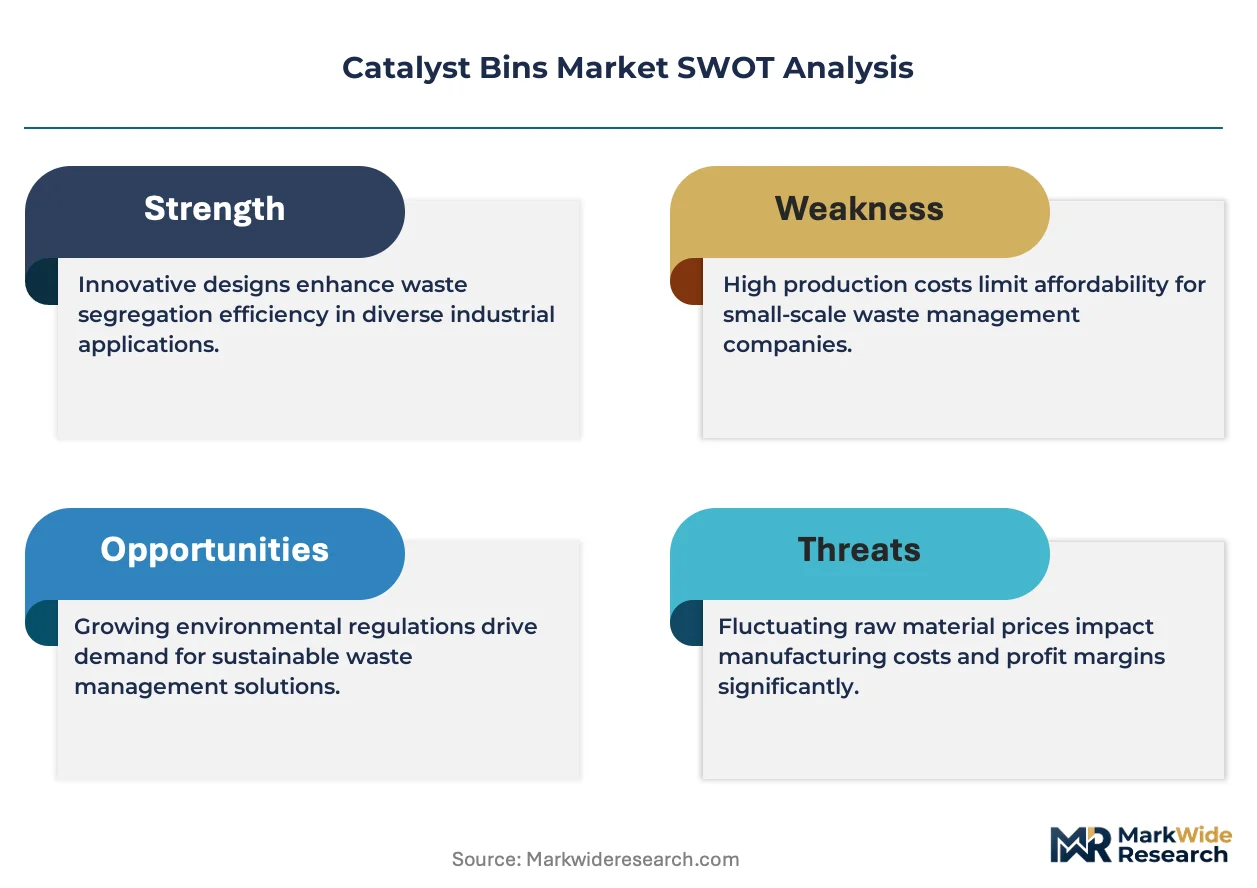
Growth Catalysts
- OSHA Process Safety Management:Tighter vapor containment mandates are accelerating replacement demand for sealed bin systems in Texas and Louisiana petrochemical corridors.
- Hydroprocessing catalyst volumes:Heavy crude upgrading investments are expanding requirements for high-temperature discharge bins with integrated heating jackets.
- Spent catalyst recovery economics:Precious metal reclamation economics are extending bin utilization cycles and driving secondary containment specifications.
Market Restraints
- Specialty steel input volatility:Nickel and molybdenum price swings are compressing margins on ASME-grade pressure vessel fabrications.
- DOT 49 CFR hazmat packaging:Multi-modal certification requirements are extending lead times for transportation-oriented bin designs by four to six weeks.
- Epoxy lining degradation:Thermal cycling limits of standard coatings are constraining service intervals in high-temperature regeneration applications.
Strategic Opportunities
- California CARB VOC controls:Pending volatile organic compound rules around catalyst changeouts will create first-mover advantage for vapor-recovery-integrated bin suppliers.
- Modular rental networks:Pooled container models are penetrating mid-scale refiners seeking to avoid capital deployment on infrequent turnaround cycles.
- Pyrophoric catalyst protocols:Inert gas purge integration represents unmet need in shale-derived light feedstock processing units.
Industry Challenges
- Welder certification scarcity:ASME Section IX qualified pressure vessel welders are concentrated among Gulf Coast fabricators, constraining capacity expansion.
- Legacy coating compatibility:New rubber lining chemistries require validation against decades-old substrate preparation standards, delaying qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalyst Bins Market |
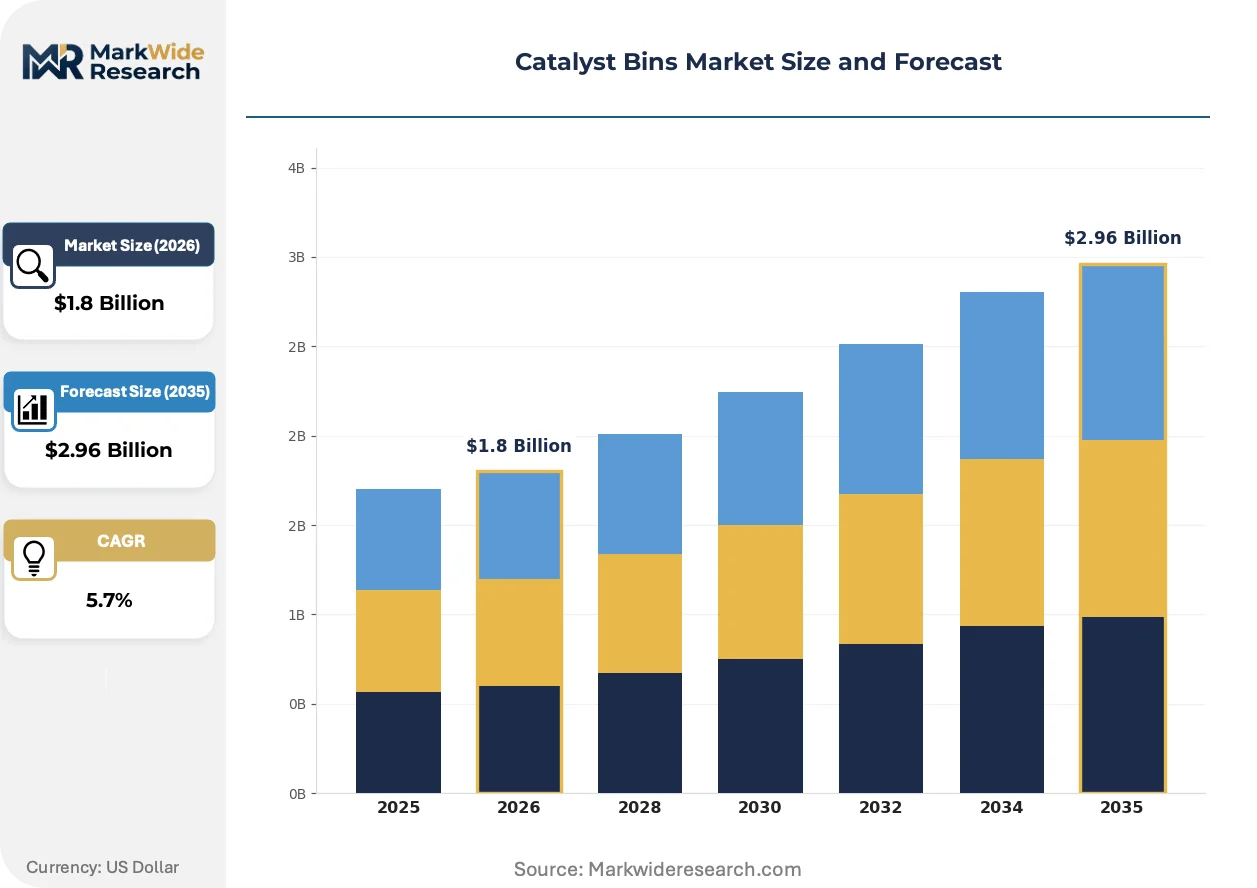
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bins, Modular Bins, Stackable Bins, Custom Bins Material: Plastic, Metal, Composite, Fiberglass End User: Chemical Industry, Oil & Gas, Waste Management, Manufacturing Application: Catalyst Storage, Transportation, Waste Disposal, Chemical Processing |
| Companies Covered | Hoover Ferguson Group, CHEP, Metchem, Briller Troistar Tanks & Containers Pvt. Ltd., Piping Technology & Products, PackGen, Paul Mueller Company, Wessels Company, Zwirner Equipment Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalyst Bins Market Emerging Trajectories
Digital monitoring integration and materials science advances are redefining performance benchmarks for catalyst containment, while regulatory fragmentation is forcing modular design architectures.
Fluoropolymer-lined carbon steel is supplanting traditional epoxy coatings in high-sulfur service environments. Gulf Coast refiners are specifying these systems for hydrocracker turnaround cycles. The shift is compressing maintenance intervals and enabling predictive replacement scheduling based on liner degradation sensors.
EPA Resource Conservation and Recovery Act container standards are tightening secondary containment specifications for spent catalyst streams. Fabricators must now engineer dual-wall configurations with leak detection ports. Texas and Louisiana facilities are retrofitting existing single-wall installations ahead of state enforcement windows.
Refinery procurement teams are unbundling long-term service contracts from equipment purchases. Third-party catalyst management specialists are capturing bin specification authority previously held by engineering contractors. This shift concentrates buying power among Houston-based logistics providers with integrated turnaround planning capabilities.
Catalyst Bins Market Segmentation
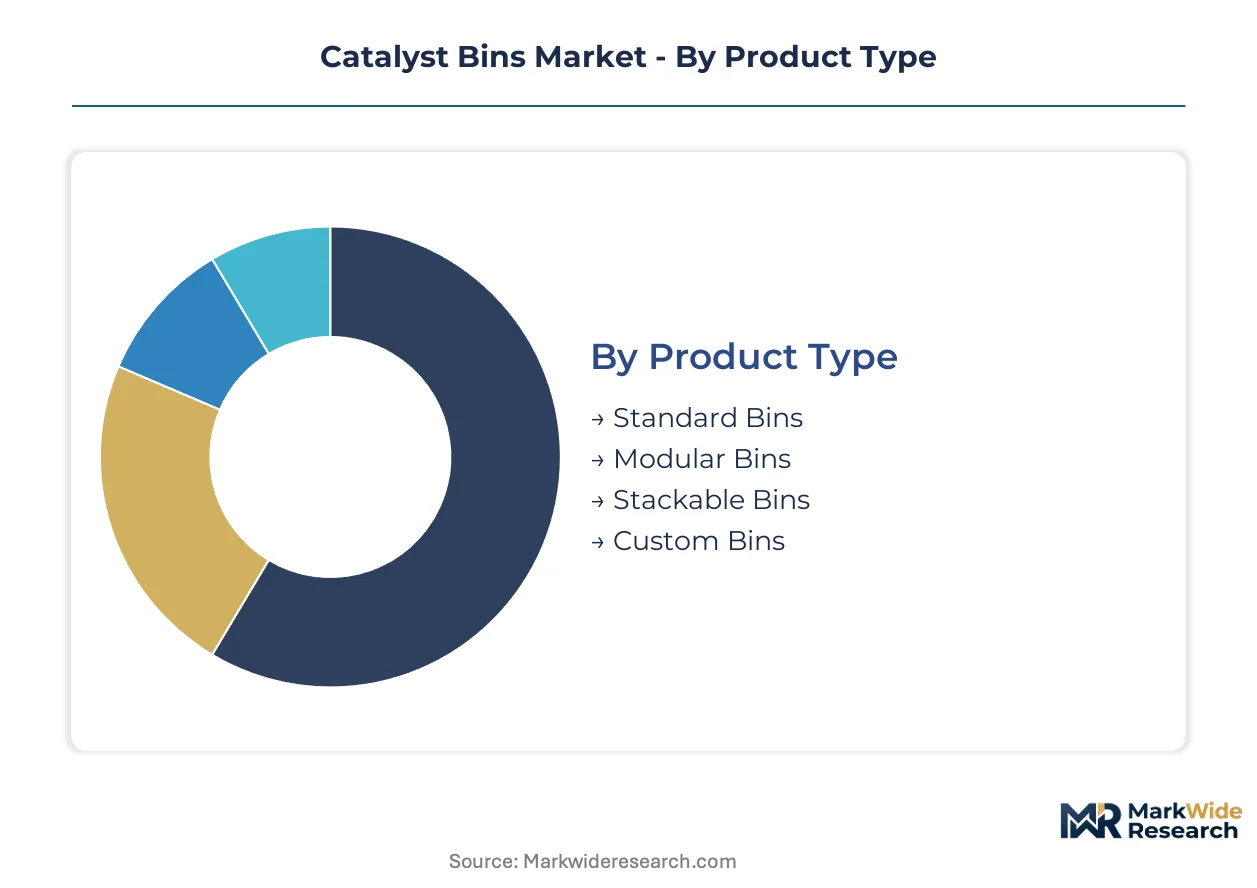
Catalyst bin procurement patterns diverge sharply across material specifications and regulatory exposure levels. Refinery engineering teams segment purchases by turnaround frequency, hazardous service classification, and DOT multimodal requirements rather than unit economics alone.
Product Type:
EPA RCRA container standards and OSHA PSM vapor containment mandates create divergent engineering requirements across bin architectures. DOT 49 CFR certification timelines further differentiate procurement strategies for stationary versus transportable configurations.
- Standard Bins:Fixed-capacity carbon steel vessels with epoxy or rubber linings dominate refinery permanent installations. Gulf Coast petrochemical clusters specify these for hydroprocessing catalyst storage where thermal cycling demands predictable material behavior. EPA hazardous waste container thickness requirements govern wall specifications.
- Modular Bins:Sectional steel assemblies with bolted flange connections enable rapid capacity scaling during turnaround windows. Texas and Louisiana refiners deploy these for hydrocracker catalyst changeouts where compressed schedules conflict with permanent infrastructure lead times. Pooled rental networks are penetrating this segment.
- Stackable Bins:Interlocking footprint designs optimize vertical storage density in constrained tank farm geometries.
- Custom Bins:Engineered-to-order configurations address non-standard reactor discharge angles and integrated heating jacket requirements.
Standard bins handle the majority of throughput; modular bins are the fastest mover on share.
Material:
Cost tier stratification separates commodity procurement from specialty alloy specifications where thermal durability commands premium positioning.
- Metal:Carbon steel and stainless steel variants occupy the dominant value position due to ASME pressure vessel certification compatibility and pyrophoric catalyst handling protocol acceptance. Nickel and molybdenum alloy grades dominate high-temperature regeneration cycles in Gulf Coast facilities.
- Plastic:High-density polyethylene and polypropylene configurations serve non-hazardous catalyst precursors and short-duration storage applications. Lighter tare weights reduce transportation costs for multi-modal logistics providers operating under DOT weight restrictions.
- Composite:Fiberglass-reinforced polymer constructions address moderate chemical resistance requirements with reduced conductive heat transfer.
- Fiberglass:Specialized corrosion-resistant formulations target sulfur-rich service environments where metal fatigue accelerates.
Metal construction commands the installed base; plastic alternatives are expanding most quickly in non-regulated service.
End User:
Application maturity and capital deployment cycles concentrate demand among process-intensive industries with scheduled turnaround obligations.
- Oil & Gas:Integrated refiners and midstream operators generate concentrated demand for ASME-certified pressure-rated bins with vapor recovery integration. Texas and Louisiana petrochemical corridors specify corrosion-resistant systems for hydroprocessing catalyst volumes tied to heavy crude upgrading investments.
- Chemical Industry:Downstream chemical processing clusters require specialized containment for heterogeneous catalyst systems with precise moisture exclusion protocols. Batch process operators favor modular rental models to avoid capital deployment on infrequent changeout cycles.
- Waste Management:Spent catalyst recovery specialists specify dual-wall secondary containment configurations under tightening EPA enforcement windows.
- Manufacturing:Industrial catalyst consumers in polymer and specialty chemical production represent fragmented procurement with standardized specifications.
Oil and gas anchors current demand; chemical industry procurement is climbing the fastest as specialty chemical capacity expands.
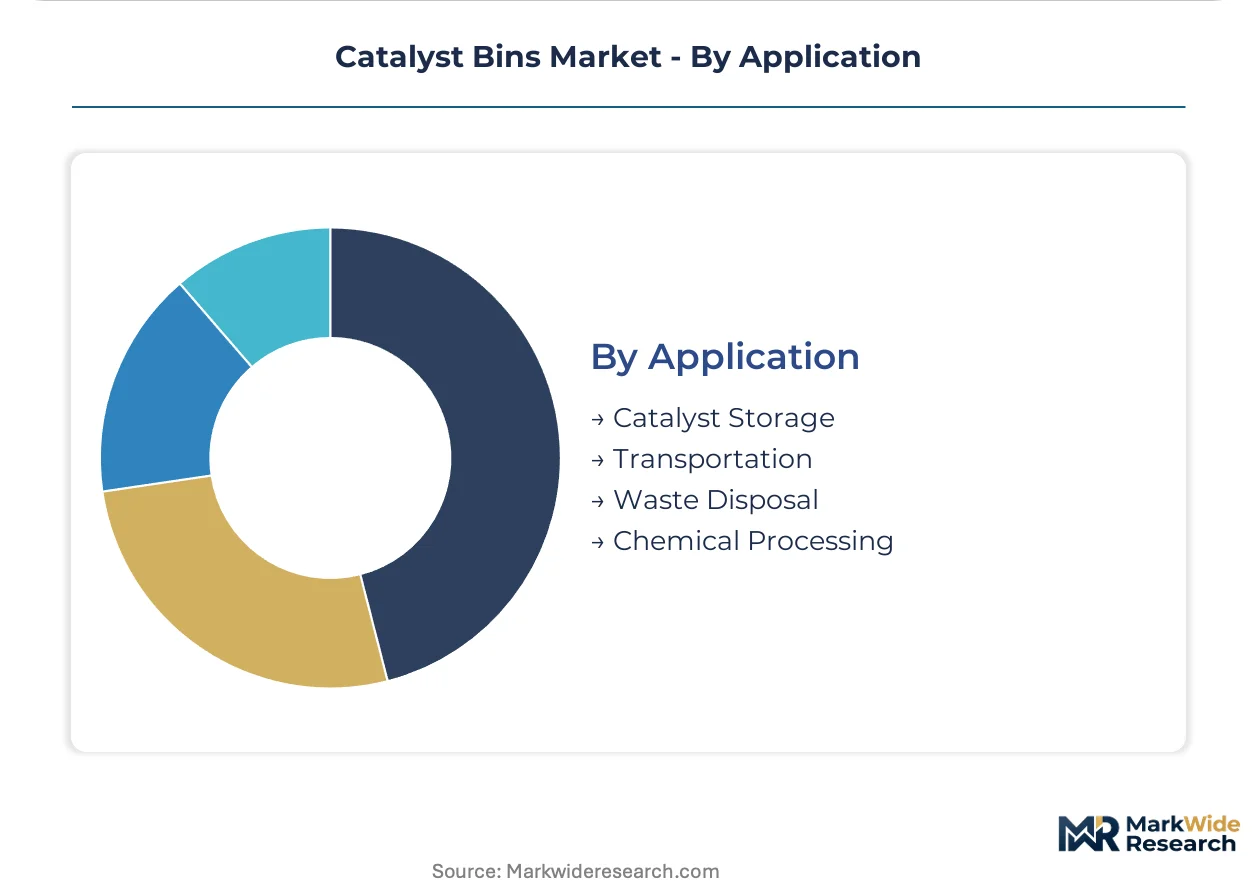
Application:
Supply concentration among Gulf Coast fabricators shapes delivery timelines and qualification requirements across use cases.
- Catalyst Storage:Long-duration containment with moisture and contamination exclusion represents the foundational application. Refinery tank farms specify heated jacket integration for temperature-sensitive catalyst systems in Texas and Louisiana humidity conditions.
- Transportation:DOT 49 CFR hazmat packaging certification constrains design flexibility for spent catalyst streams classified as regulated wastes. Multi-modal certification extends lead times by four to six weeks, compressing turnaround planning windows.
- Waste Disposal:Spent catalyst recovery economics extend bin utilization cycles and drive secondary containment specifications for precious metal reclamation operations.
- Chemical Processing:In-process catalyst handling with integrated discharge mechanisms serves continuous reactor feed systems.
Storage applications dominate installed capacity; transportation configurations are gaining share fastest as regulatory classification tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Gulf Coast refiners prioritize corrosion-resistant specifications over unit cost, while mid-scale chemical operators in fragmented markets negotiate aggressively on rental rates for modular systems.
United States
Heavy crude upgrading investments along the Texas and Louisiana corridors are expanding demand for high-temperature discharge bins with integrated heating jackets. EPA Resource Conservation and Recovery Act container standards and OSHA Process Safety Management rules govern wall thickness and vapor containment specifications. The Houston Ship Channel petrochemical cluster hosts concentrated fabrication capacity, with local suppliers managing compressed turnaround procurement timelines.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr industrial region require precision-engineered containment for moisture-sensitive heterogeneous catalyst systems. ECHA REACH regulations and CE marking requirements constrain material selection and validation protocols for cross-border equipment movement. BASF and Bayer supplier networks in Ludwigshafen and Leverkusen specify ASME-compatible designs for integrated European refinery-chemical complexes.
China
State-backed refinery expansion in Shandong and Zhejiang provinces is scaling catalyst handling infrastructure for hydroprocessing capacity additions. MIIT industrial safety directives and GB standards for pressure vessels are tightening certification requirements for domestic fabricators. The Ningbo-Zhoushan petrochemical base represents the fastest-growing demand concentration, with local operators balancing import substitution against Western certification acceptance.
Saudi Arabia
SABIC and Aramco downstream integration projects in Jubail and Yanbu are driving procurement of large-format modular bins for continuous catalyst changeout operations. The country's national industrial regulator enforces Saudi Aramco engineering standards that exceed baseline ASME requirements in high-temperature service. The King Salman Energy Park manufacturing zone is attracting Gulf fabricators seeking proximity to mega-project procurement offices.
India
Reliance Industries and Indian Oil refinery expansions in Gujarat and Maharashtra are generating demand for corrosion-resistant containment systems adapted to high-sulfur crude processing. BIS pressure vessel certification and state-level pollution control mandates are extending qualification timelines for imported equipment. The Dahej and Hazira chemical corridors concentrate procurement authority among integrated operators with captive engineering capabilities.
Catalyst Bins Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in catalyst bin supply. Consolidated fabrication groups with captive steel processing and coating operations command premium positioning on large-format pressure-rated designs. Specialist fabricators compete through rapid customization for non-standard reactor geometries and pooled rental network deployment. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with fabricators securing ASME-certified welder pools and coating technology licenses to defend positioning.
Within the integrated fabrication tier, Hoover Ferguson Group and Paul Mueller Company exemplify divergent strategic anchoring. Hoover Ferguson leverages Gulf Coast steel fabrication and coating integration to capture large-format modular bin procurement. Paul Mueller Company occupies the pressure-rated design segment with ASME-certified vessel engineering. CHEP represents the pooled rental network archetype, reducing capital deployment burdens for mid-scale chemical operators with infrequent turnaround cycles. These three patterns—captive fabrication integration, certified pressure engineering, and asset-light logistics—define competitive positioning across procurement contexts.
| Leading Market Players |
|---|
| Hoover Ferguson Group |
| CHEP |
| Metchem |
| Briller Troistar Tanks & Containers Pvt. Ltd. |
| Piping Technology & Products |
| PackGen |
| Paul Mueller Company |
| Wessels Company |
| Zwirner Equipment Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Gulf Coast fabricators and integrated refiners lock in both specialty steel supply access and predictable unit pricing across multi-year turnaround cycles. These arrangements insulate procurement teams from nickel and molybdenum volatility while constraining spot-market flexibility for mid-scale operators.
Pricing Analysis
After-market service revenue from liner replacement and recertification drives lifetime value for fabricators beyond initial equipment sales. Three-tier pricing structure across ASME-certified pressure-rated, standard EPA-compliant, and non-regulated economy tiers separates procurement segments by thermal cycling requirements. Cost compression in standard epoxy-lined configurations is intensifying because pooled rental networks are commoditizing modular bin deployment. Mid-scale chemical operators exhibit highest price sensitivity, while Gulf Coast refiners prioritize corrosion-resistant specifications over unit economics.
Supply Chain Analysis
ASME Section IX welder certification scarcity in the Houston Ship Channel creates a chokepoint constraining capacity expansion across domestic fabricators. Specialty steel supply draws from domestic mills, South Korean nickel alloy producers, and European coating chemical suppliers. Single-source vulnerability runs through concentrated Gulf Coast fabrication clusters exposed to hurricane disruption. Distribution feeds from captive fabrication yards through third-party catalyst management specialists with integrated turnaround planning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as EPA hazardous waste container standards and OSHA vapor containment mandates force replacement demand across aging refinery infrastructure.
For Market Incumbents: Secure captive ASME-certified welder pools and coating technology licenses to defend positioning against specialty fabricators encroaching on pressure-rated segments. Expand backward integration into specialty steel processing to buffer margin compression from nickel and molybdenum input volatility. Prioritize dual-wall secondary containment qualification ahead of state enforcement windows in Texas and Louisiana. For New Entrants and Emerging Players: Differentiate on rapid customization for non-standard reactor geometries where integrated leaders sacrifice responsiveness for scale. Target California CARB VOC control compliance as first-mover white space before pending rules crystallize. Penetrate mid-scale chemical operators through modular rental networks that avoid capital deployment burdens on infrequent turnaround cycles. For Investors and Strategic Acquirers: Regional fabrication specialists with EPA certification depth and Gulf Coast logistics integration represent the most defensible acquisition archetype. Monitor California Air Resources Board rulemaking timelines as the critical inflection signal for vapor-recovery-integrated bin demand acceleration. Long-term viability hinges on regulatory enforcement consistency rather than discretionary refinery capital cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Investment | Unlocks pressure-rated design premiums in high-temperature regeneration applications at Gulf Coast facilities. |
| Backward Integration into Coating Operations | Captures fluoropolymer liner margins and accelerates predictive maintenance service revenue streams. |
| Modular Rental Network Expansion | Reduces capital deployment friction for mid-scale refiners with compressed turnaround schedules. |
| Dual-Wall Secondary Containment Development | Pre-positions fabricators ahead of EPA RCRA enforcement windows in Texas and Louisiana corridors. |
| Vapor Recovery Integration Partnership | Addresses California CARB compliance requirements before rule finalization locks in supplier selection. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with refinery maintenance directors, catalyst management specialists, ASME-certified fabrication engineers, and downstream chemical procurement leads. Secondary validation drew from EPA enforcement databases, OSHA process safety incident reports, Department of Transportation hazmat certification records, and SEC filings from integrated refinery operators. Bottom-up unit economics triangulated against top-down capacity expansion announcements across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs by product architecture, material specification tier, end-use industry concentration, and regional regulatory exposure cluster. CAGRs were derived from segmented growth rate reconciliation against macro refinery capital cycle indicators. Forecast inputs incorporated hydroprocessing catalyst volume projections, specialty steel price indices, and state-level air quality mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Coast petrochemical expansion or accelerated EPA enforcement would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation pacing and refinery turnaround frequency patterns. Practitioners should keep alternative scenarios live as California CARB rulemaking and OSHA PSM amendment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Metal Molds Market
Industrial Materials
Tooling Board Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Injection Molding Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Warehouse Drums and Barrels Market