
 Modified Wood Market | 2026-2036
Modified Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Wood Market Analytics
Finnish thermo-treatment facilities is recalibrating output schedules after Nordic energy price shifts. Thermory leverages vertical integration from forest to finished cladding to sustain margin stability across Baltic markets. Stora Enso anchors its position through captive spruce supply and industrial-scale autoclave networks. Lunawood differentiates via proprietary thermal modification protocols that extend product warranties in maritime environments.
Modified wood denotes timber subjected to controlled thermal, chemical, or resin-based processes that alter cell-wall chemistry, typically achieving mass reductions of 10 percent and enhanced dimensional stability for exterior applications. Thermo-treated wood dominates volume flows due to established European production infrastructure and minimal chemical residuals, while acetylated wood commands premium positioning in window and door joinery for its superior moisture resistance. The construction end-use industry absorbs the largest share of modified wood output, though boat building represents the fastest-expanding application niche as yacht builders substitute teak with acetylated alternatives.
REACH compliance in Europe and EPA treated-wood standards in the United States constrain chemical modification pathways and elevate testing burdens for resin-infused products. The EU Green Deal's embodied-carbon thresholds for building materials are redirecting specification decisions toward thermally modified options with lower lifecycle emissions. Stakeholders must monitor evolving ECHA substance evaluations and corresponding building-code adoptions that could disqualify specific chemical treatments from residential applications.
Market Dynamics
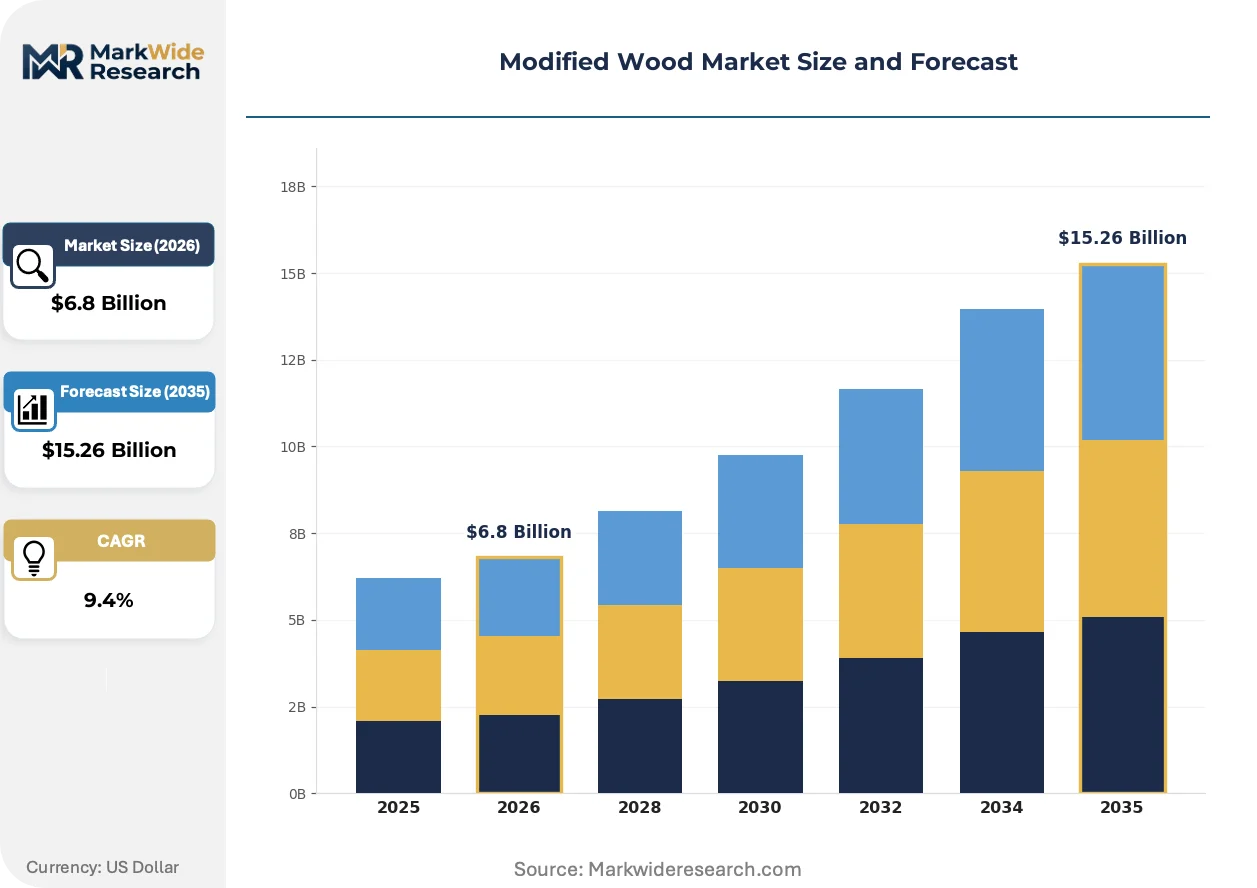
EU Green Deal embodied-carbon thresholds are redirecting specification decisions toward thermally modified wood with lower lifecycle emissions, compressing chemical modification pathways across European construction supply chains.
Growth Catalysts
- EU F-Gas Regulation tightening:Chemical treatment standards for wood preservatives are constraining traditional CCA and creosote applications, accelerating specification migration toward thermo-treated alternatives in exterior decking and cladding.
- German commercial construction absorption:Large-scale office and retail developments are specifying modified wood for facade systems and outdoor installations, pulling volume through centralized procurement channels.
- Acetylation chemistry advancement:Improved industrial-scale acetylation processes are reducing production cycle times and expanding moisture-resistant product availability for window and door joinery applications.
Market Restraints
- Energy input cost volatility:Thermo-treatment kiln operations require sustained high-temperature thermal energy, exposing Nordic and Baltic producers to electricity and biomass price swings that compress operating margins.
- REACH compliance testing burdens:ECHA substance evaluations for resin-infused and chemically modified wood products impose extended certification timelines and elevated analytical costs before market entry.
- Teak substitution ceiling:High-end yacht builders retain preference for genuine teak in superyacht applications despite acetylated alternatives, limiting penetration in the most lucrative maritime segment.
Strategic Opportunities
- US EPA treated-wood standard alignment:Harmonization opportunities exist for European producers to adapt thermo-treatment protocols for US residential decking specifications, accessing the largest single-country construction market.
- Boat building application expansion:Mid-tier yacht and commercial vessel manufacturers are substituting acetylated wood for tropical hardwoods in decking and interior joinery, creating a fast-expanding niche with premium pricing tolerance.
- Digital specification platforms:Building information modeling integration and architect-facing digital tools are shortening the path from material selection to project inclusion, reducing traditional distributor dependence.
Industry Challenges
- Autoclave operator skill scarcity:Industrial-scale thermal modification and acetylation require specialized process control expertise that outpaces current vocational training output in producing regions.
- Multi-jurisdiction certification lag:Divergent building code adoptions across EU member states and US states create fragmented approval pathways that delay product launches and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Wood Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermo-treated Wood, Acetylated Wood, Resin-infused Wood, Chemical-modified Wood Application: Decking, Furniture, Flooring, Siding End Use Industry: Construction, Furniture Manufacturing, Landscaping, Boat Building Distribution Channel: Direct Sales, Retailers, E-commerce, Distributors |
| Companies Covered | Arbor Wood, Thermawood Tech, Thermory, Timura Holzmanufaktur, Cambia by NFP, Stora Enso, SWM-Wood, Novawood, Lunawood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Wood Market Evolving Landscape
Process intensification and digital traceability systems are compressing production cycles while embedding lifecycle carbon data directly into material specifications, altering how architects and contractors evaluate wood modification options.
Continuous thermal modification reactor technology is integrating real-time moisture and temperature monitoring to achieve more uniform cell-wall chemistry alteration across batch volumes. Scandinavian producers are adopting these systems for cladding and decking production. The technology is integrating quality assurance directly into process control, reducing post-treatment grading reject rates and enabling just-in-time delivery commitments to large construction projects.
REACH substance restriction proposals under ECHA evaluation are expanding scrutiny of biocide-treated wood products for residential applications. Industrial consequence includes accelerated R&D investment in thermal and acetylation pathways that bypass chemical preservative classification. Window and door manufacturers in Germany and the Netherlands are responding by pre-qualifying thermo-treated and acetylated alternatives in their supplier matrices ahead of potential restriction enactment.
Specification decisions are compressing traditional distributor influence as architects and contractors access direct-to-designer technical support from modification specialists. Digital channels and technical consultation services are displacing wholesale intermediaries in project origination. This pattern is most visible in Nordic and German markets where sustainability certification requirements drive early-stage material selection involvement from producers rather than distributors.
Modified Wood Market Segmentation
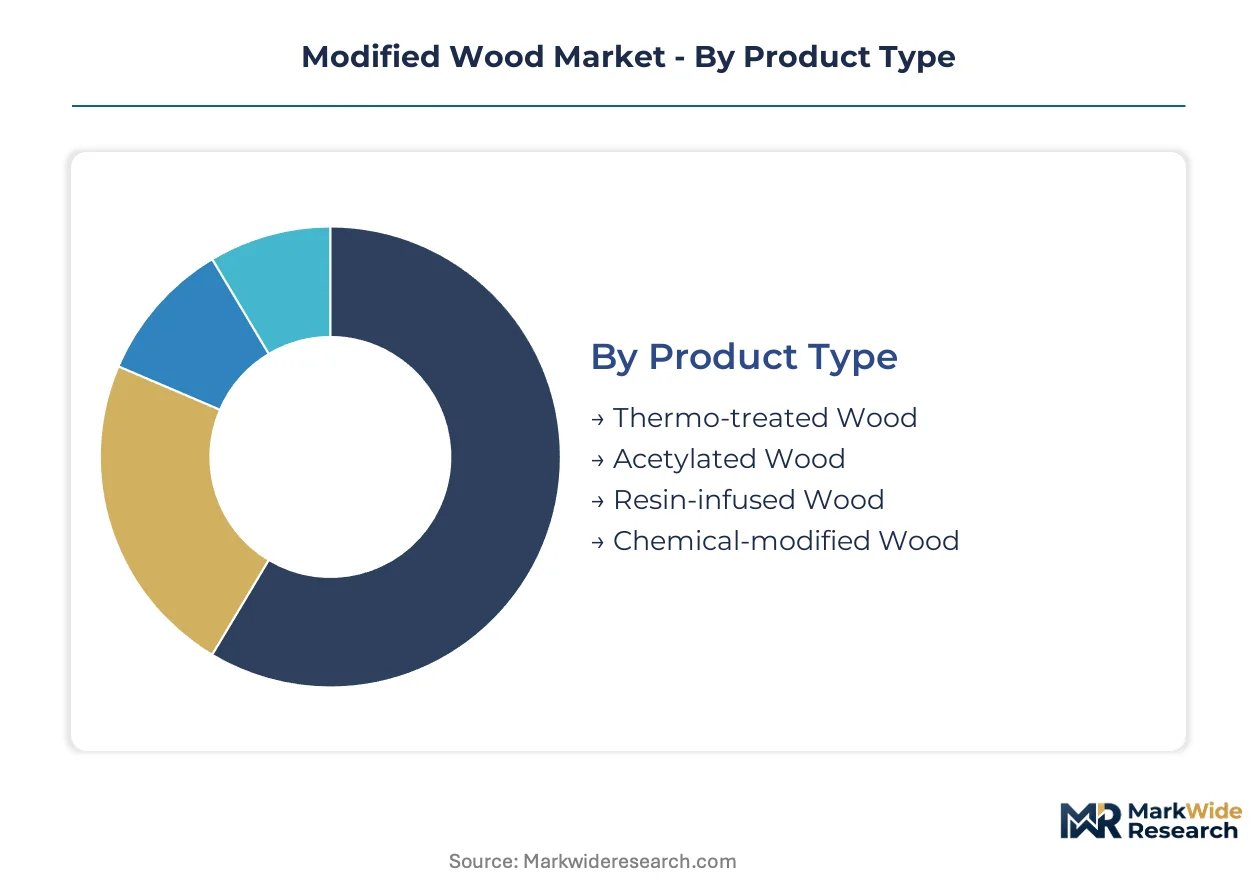
Technology pathways determine performance specifications and regulatory pathways for modified wood. Specification decisions cascade through end-use requirements, distribution economics, and compliance frameworks.
Product Type:
Thermal modification protocols and chemical pathways create distinct performance envelopes and certification obligations.
- Thermo-treated Wood:High-temperature kiln processes alter cell-wall chemistry without chemical additives, achieving enhanced dimensional stability and reduced equilibrium moisture content. German commercial construction and Nordic cladding applications absorb the majority of European output as ECHA substance restrictions tighten.
- Acetylated Wood:Esterification with acetic anhydride creates permanent moisture resistance through cell-wall acetylation, delivering superior performance in window joinery and maritime decking. Dutch and German window manufacturers are pre-qualifying acetylated alternatives ahead of potential biocide restrictions.
- Resin-infused Wood:Polymer impregnation fills cell lumens with thermoset resins, increasing hardness and decay resistance for high-traffic flooring applications.
- Chemical-modified Wood:Traditional preservative treatments using copper compounds or creosote face REACH compliance pressure and residential application limitations.
Thermo-treated wood leads on scale; acetylated wood leads on momentum.
Application:
Exterior exposure severity and aesthetic requirements segment demand across structural and decorative uses.
- Decking:Ground-contact moisture cycling and UV exposure demand enhanced durability specifications. Scandinavian producers are expanding kiln capacity specifically for thermo-treated decking as EU F-Gas Regulation constrains chemical preservative alternatives.
- Siding:Facade systems require dimensional stability across humidity fluctuations and thermal cycling. German large-scale office developments are specifying modified wood cladding systems through centralized procurement channels.
- Flooring:Interior applications prioritize hardness and wear resistance over exterior durability, favoring resin-infused options.
- Furniture:Aesthetic grain preservation and finishing compatibility drive specification toward lighter thermal modification treatments.
Decking commands volume concentration; siding is climbing the fastest on embodied-carbon alignment.
End Use Industry:
Construction sector procurement patterns and performance standards shape volume allocation across industrial buyers.
- Construction:Commercial facade systems, structural decking, and exterior millwork absorb the largest share of modified wood output. German retail and office developments are pulling volume through architect-specified material selections.
- Boat Building:Mid-tier yacht manufacturers are substituting acetylated wood for tropical hardwoods in decking and interior joinery. Maritime certification requirements and teak substitution economics are expanding this niche.
- Landscaping:Public space installations and residential garden structures specify thermo-treated options for ground-contact durability.
- Furniture Manufacturing:Interior-focused producers favor lighter thermal modification for dimensional stability without darkening.
Construction leads on scale; boat building gains share fastest on premium substitution economics.
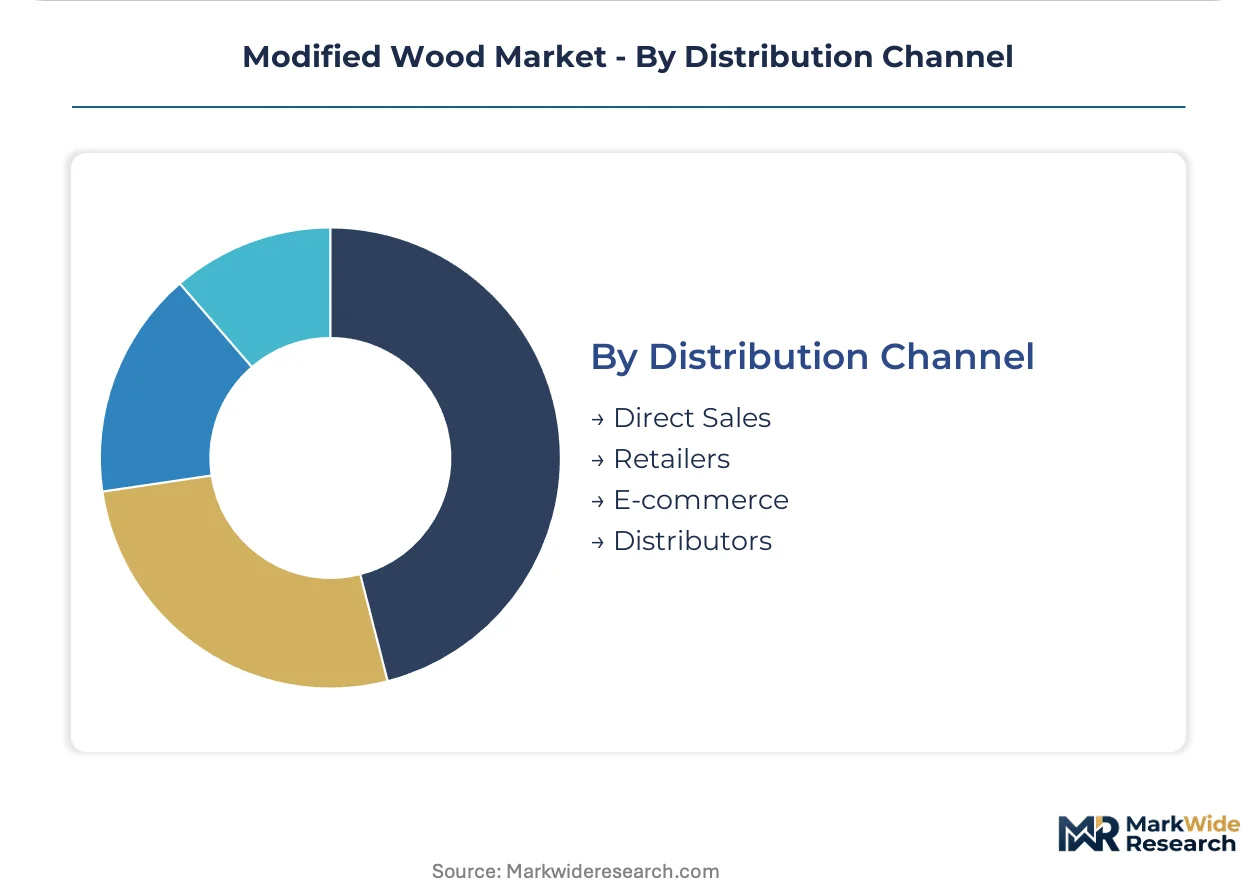
Distribution Channel:
Specification influence is compressing traditional wholesale intermediaries as producers engage directly with design professionals.
- Direct Sales:Large construction projects and architect-specified developments source through producer technical consultation services. Digital specification platforms and BIM integration are shortening procurement paths in Nordic and German markets.
- Distributors:Regional inventory holding and logistics services remain relevant for mid-scale contractors and fragmented project demand.
- Retailers:DIY and residential renovation segments access modified wood through building material merchants with limited technical support.
- E-commerce:Digital channels serve small-scale buyers and specialized product searches with limited project-scale penetration.
Direct sales leads on specification control; e-commerce shows steepest expansion trajectory on digital tool adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs modified wood volumes faster than the United States as EU embodied-carbon regulations tighten procurement standards. Nordic producers export thermo-treated cladding southward while Baltic states expand kiln capacity for German commercial projects.
Germany
Large-scale office and retail developments in Berlin and Munich specify modified wood facade systems through architect-driven procurement. The EU Green Deal's embodied-carbon thresholds redirect specification decisions toward thermally modified options with lower lifecycle emissions. Industrial clusters in North Rhine-Westphalia host window manufacturers pre-qualifying acetylated alternatives ahead of potential ECHA biocide restrictions.
Finland
Scandinavian producers operate thermo-treatment kilns serving decking and cladding demand across Baltic markets. REACH compliance requirements constrain chemical modification pathways and elevate testing burdens for export-bound products. Helsinki-Tampere industrial corridors anchor captive spruce supply chains feeding industrial-scale autoclave networks.
United States
Residential decking specifications in coastal states drive demand for thermo-treated alternatives to traditional pressure-treated lumber. EPA treated-wood standards create compliance frameworks that European producers must navigate for market entry. Pacific Northwest forestry regions supply raw material to modification facilities targeting California and Northeast corridor construction markets.
Netherlands
Window and door joinery manufacturers in Rotterdam-Amsterdam corridors absorb acetylated wood volumes for moisture-resistant applications. ECHA substance evaluations under REACH expand scrutiny of biocide-treated products for residential uses. Dutch specification professionals engage directly with modification specialists through digital channels, compressing traditional distributor influence.
Sweden
Stora Enso anchors national output through vertical integration from forest resources to finished modified wood products. The EU F-Gas Regulation tightens chemical treatment standards, accelerating migration toward thermo-treated alternatives. Gothenburg and Stockholm industrial zones concentrate production capacity serving German and UK export markets.
Modified Wood Market Competitive Landscape
Scandinavian producers anchor one tier; Central European specialists hold differentiated positions in acetylation chemistry. The vendor base organizes around three strategic archetypes: forest-integrated conglomerates with captive raw material supply, standalone modification specialists licensing proprietary thermal protocols, and chemical technology providers scaling acetylation reactors. Capacity expansion and backward integration into timber supply represent dominant competitive moves as energy input costs compress operating margins.
Among Nordic forest-integrated players, Stora Enso exemplifies the conglomerate archetype through in-house production of spruce feedstock and industrial-scale autoclave networks. Lunawood occupies a specialist position within the thermo-treatment tier, while Thermory represents vertically integrated operations spanning forest to finished cladding. These three companies illustrate how geographic proximity to raw material and energy infrastructure shapes competitive positioning across Baltic and German markets.
| Leading Market Players |
|---|
| Arbor Wood |
| Thermawood Tech |
| Thermory |
| Timura Holzmanufaktur |
| Cambia by NFP |
| Stora Enso |
| SWM-Wood |
| Novawood |
| Lunawood |
| Others |
Value Network & Pricing Analysis
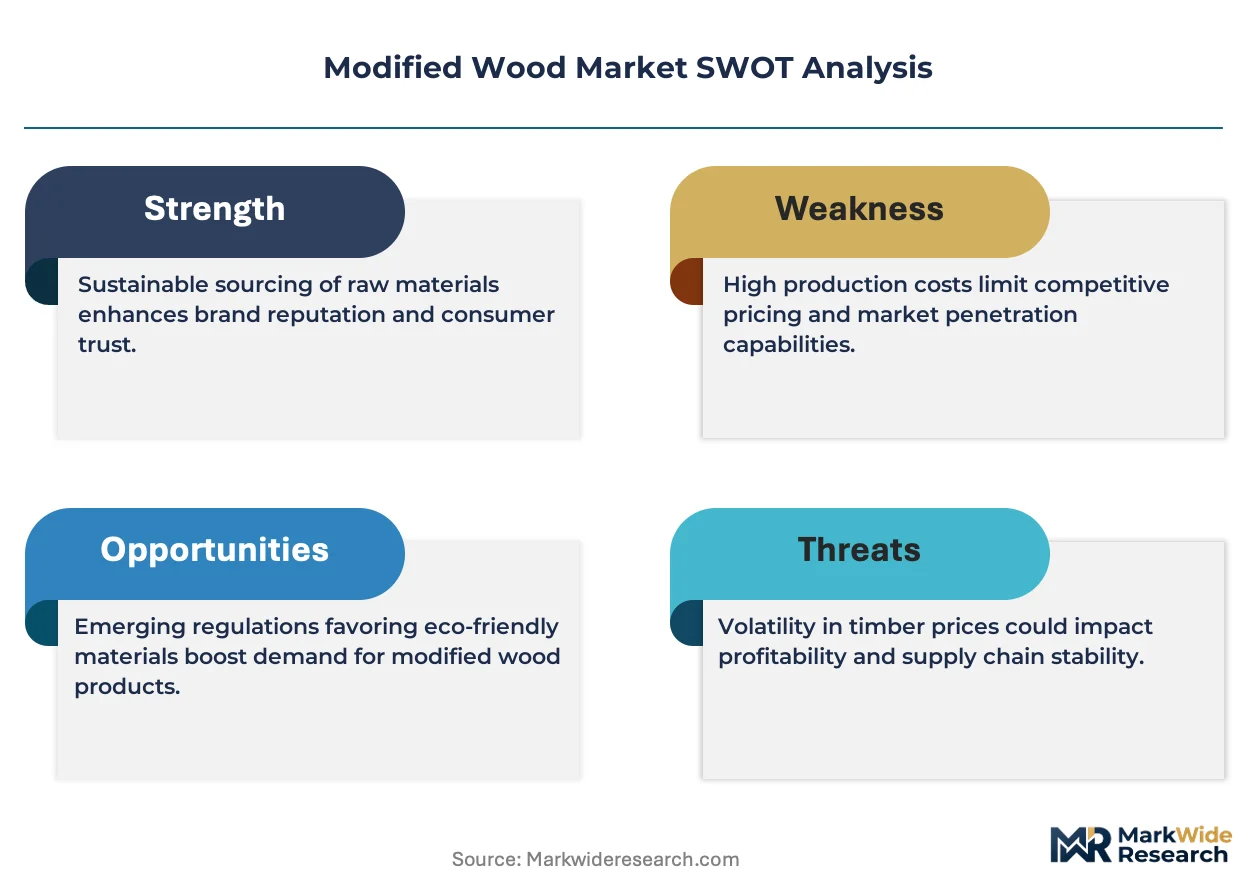
EU Green Deal embodied-carbon thresholds gate qualified supply and premium-tier pricing access, restricting specification eligibility to thermally modified producers with verified lifecycle data while compressing margins for chemical modification pathways facing compliance escalation.
Pricing Analysis
Capacity additions in the Baltic states are reshaping price floors for thermo-treated decking as Nordic energy costs compress operating margins. Pricing stratifies across premium acetylated joinery, standard thermo-treated cladding, and economy-grade chemical-treated alternatives. Cost compression in the standard tier intensifies because biomass and electricity price volatility erode kiln operator returns. Mid-scale German contractors exhibit highest price sensitivity, while Dutch window manufacturers demonstrate lowest sensitivity due to certification-driven specification lock-in.
Supply Chain Analysis
Refurbishment flows for thermo-treated decking are emerging as secondary raw material channels, extending product lifecycle value and creating reverse logistics infrastructure. Feedstock supply concentrates in Finland, Sweden, and Estonia, where captive spruce and pine forests anchor modification capacity. Production draws from acetic anhydride, thermoset resins, and high-grade biomass fuel inputs. Single-source vulnerability sits with Nordic electricity grids powering kiln operations. Distribution runs through direct technical consultation channels for architect-specified projects and regional distributors for fragmented contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Modified Wood Market functions as a stable compounder, with EU regulatory tightening on embodied carbon and chemical treatments driving steady specification migration toward compliant thermal modification pathways.
For Market Incumbents: Anticipate margin compression from Baltic kiln capacity additions by securing long-term biomass supply contracts and embedding carbon accounting into product passports. Prioritize backward integration into forest assets to insulate against raw material cost volatility. Defend specification position by pre-qualifying acetylated alternatives ahead of ECHA biocide restrictions. For New Entrants and Emerging Players: Launch via digital specification platforms targeting mid-tier yacht builders substituting acetylated wood for tropical hardwoods. The US residential decking segment offers lowest entry barriers due to fragmented EPA compliance frameworks and coastal state demand concentration. Prioritize BIM-integrated technical support to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone modification specialists lacking captive timber supply, presenting consolidation targets for forest-integrated conglomerates seeking capacity expansion. Long-term viability hinges on carbon border adjustment alignment and certification infrastructure durability. Monitor ECHA substance restriction enactment timelines as inflection indicators for acetylation pathway acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Baltic kiln additions target German commercial construction absorption through just-in-time delivery commitments. |
| Backward Integration | Captive spruce supply chains in Finland and Sweden insulate Stora Enso and Lunawood from raw material volatility. |
| Green Certification Program | EU Green Deal alignment enables premium positioning for thermally modified products in Dutch and German facade specifications. |
| Long-term Supply Agreement | Biomass fuel contracts with Nordic energy utilities stabilize kiln operating costs against electricity price swings. |
| Joint Venture | Technology partnerships between acetylation specialists and window manufacturers accelerate moisture-resistant product availability. |
Research Methodology
Coverage spans Germany, Finland, the Netherlands, Sweden, and the United States, with primary inputs from each market cluster combining interviews with thermo-treatment plant managers, window manufacturer procurement leads, architect specification consultants, and marine decking contractors. Secondary validation draws from ECHA substance evaluation databases, EU F-Gas Regulation implementation trackers, EPA treated-wood standard filings, and Nordic timber trade statistics. Bottom-up volume estimates triangulate against top-down construction sector absorption models.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, modeling technology pathway splits, application intensity shifts, and end-use industry penetration curves. Segmentation dimensions include thermal versus chemical modification protocols, decking versus siding versus joinery applications, and construction versus boat building demand. CAGRs derive from regression against historic kiln capacity utilization, energy input cost indices, and regulatory compliance timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA restriction enactment or Nordic energy price spikes. Practitioners should monitor ECHA substance evaluation publication schedules and EU carbon border adjustment implementation progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Seals Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Mineral Wool Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Couplings Market