
 Home Control and Security Systems Market | 2026-2036
Home Control and Security Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Home Control and Security Systems Market Analysis
Recurring platform licensing revenue is tilting away from one-time hardware sales as vendors monetize ongoing remote monitoring and cloud-based access management. Honeywell International Inc. leverages its building automation heritage to anchor enterprise-grade security deployments across North American commercial real estate. ADT Inc. competes through professionally monitored service bundles that sustain higher customer lifetime value than standalone device sales. Hangzhou Hikvision Digital Technology dominates video analytics manufacturing scale, extending cost advantages in camera sensor production.
Home control and security systems encompass networked hardware and software platforms that integrate intrusion detection, environmental sensing, access control, and surveillance functions through protocols operating across 2.4 GHz and sub-GHz frequency bands with typical latency thresholds below 250 milliseconds for real-time alert transmission. These systems serve residential and light commercial users by centralizing visibility and automated response to physical threats and operational anomalies. Security cameras command the largest installed base among product types, though smart locks are capturing disproportionate margin expansion as biometric authentication and temporary credentialing replace mechanical key systems. Wi-Fi retains dominant connectivity share for standalone consumer devices, yet Z-Wave and Zigbee are gaining ground in whole-home deployments where mesh reliability and lower power draw reduce infrastructure redundancy.
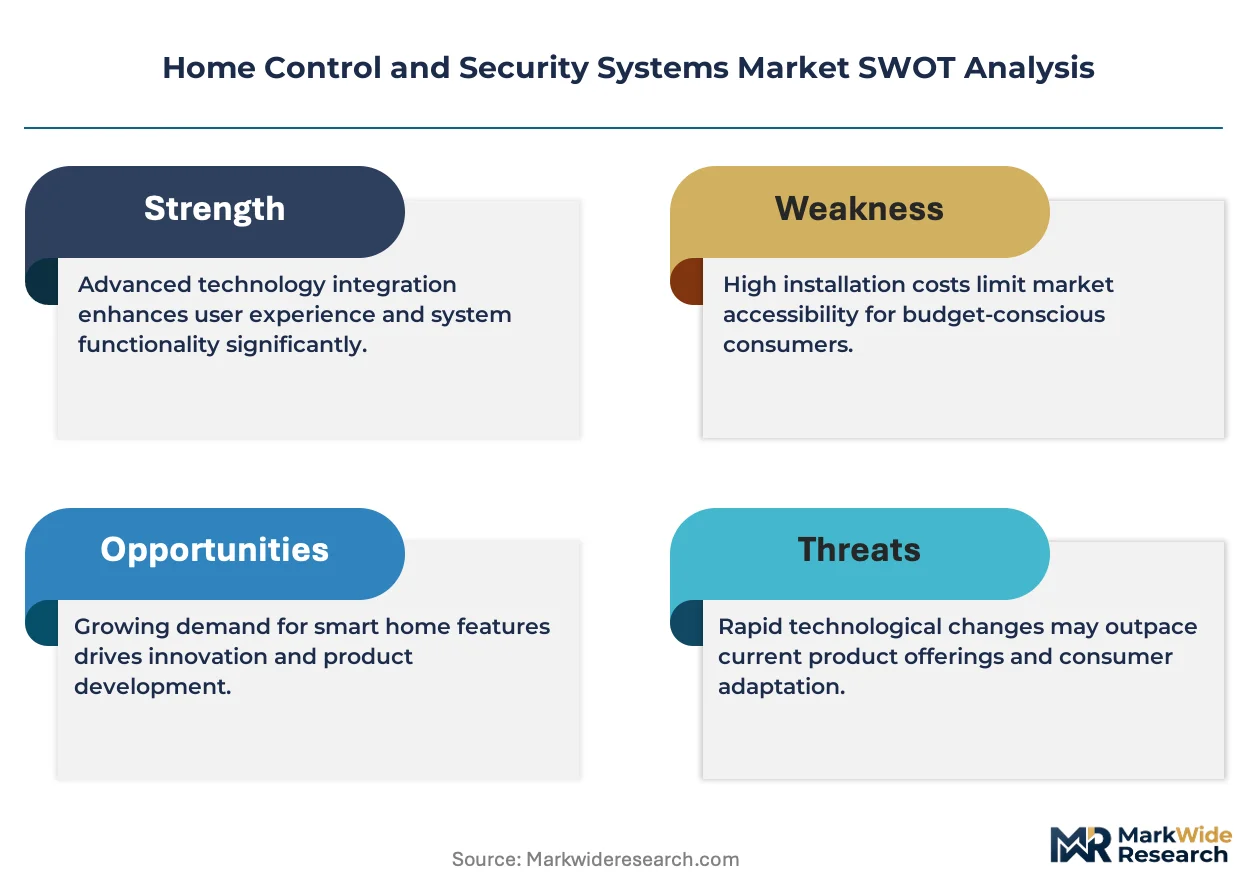
The Federal Communications Commission governs radio frequency allocations for wireless security devices in the United States, while the EU Cybersecurity Act mandates baseline certification for connected home products accessing European markets. The California Consumer Privacy Act and emerging state-level biometric regulations in Illinois and Texas impose data handling constraints on facial recognition-enabled cameras and fingerprint-storing smart locks. Stakeholders must weigh interoperability investments against fragmentation risk as Matter protocol adoption, CSA certification requirements, and divergent regional privacy enforcement create competing compliance pathways.
Market Dynamics
Platform consolidation is compressing vendor margins as multi-dwelling property managers demand unified access, surveillance, and environmental control through single-pane dashboards rather than fragmented point solutions.
Growth Catalysts
- EU AI Act:Mandatory risk classification for biometric-enabled devices is accelerating vendor investment in compliant edge-processing architectures, expanding addressable markets for certified European suppliers.
- Multi-dwelling retrofits:Germany's building energy retrofit mandates are converging with smart infrastructure upgrades, creating bundled procurement opportunities for integrated security and HVAC control systems.
- Sub-GHz mesh protocols:Z-Wave Long Range and Zigbee PRO deployments are penetrating whole-home installations where Wi-Fi reliability degrades across concrete construction, particularly in dense urban housing stock.
Market Restraints
- Semiconductor concentration:Camera image sensors and RF transceivers depend on Taiwan and South Korean foundry capacity, exposing lead times to geopolitical disruption.
- California Consumer Privacy Act:Facial recognition data retention limits impose architectural constraints on cloud-based video analytics, forcing costly on-premise processing retrofits.
- Mechanical lock substitution:Low-cost Bluetooth-enabled retrofit cylinders are capturing price-sensitive residential segments, compressing margins for full-platform smart lock vendors.
Strategic Opportunities
- Insurance channel partnerships:Property and casualty underwriters in Florida and Texas are mandating monitored leak detection and intrusion systems for coastal premium discounts, creating referral-driven customer acquisition.
- Matter protocol convergence:CSA certification is enabling cross-brand interoperability that reduces consumer switching costs and expands ecosystem attach rates for hub-anchored vendors.
- Biometric credentialing:Fingerprint and vein-pattern authentication is displacing keypad entry in assisted living facilities, opening recurring SaaS revenue from temporary access provisioning.
Industry Challenges
- Cybersecurity certification timelines:EU Cybersecurity Act baseline assessments are extending product launch cycles by 8-14 months for connected camera and lock manufacturers.
- Legacy panel integration:Hardwired intrusion systems from the 1990s-2000s installation wave resist seamless cloud migration, forcing expensive rip-and-replace or hybrid gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Control and Security Systems Market |
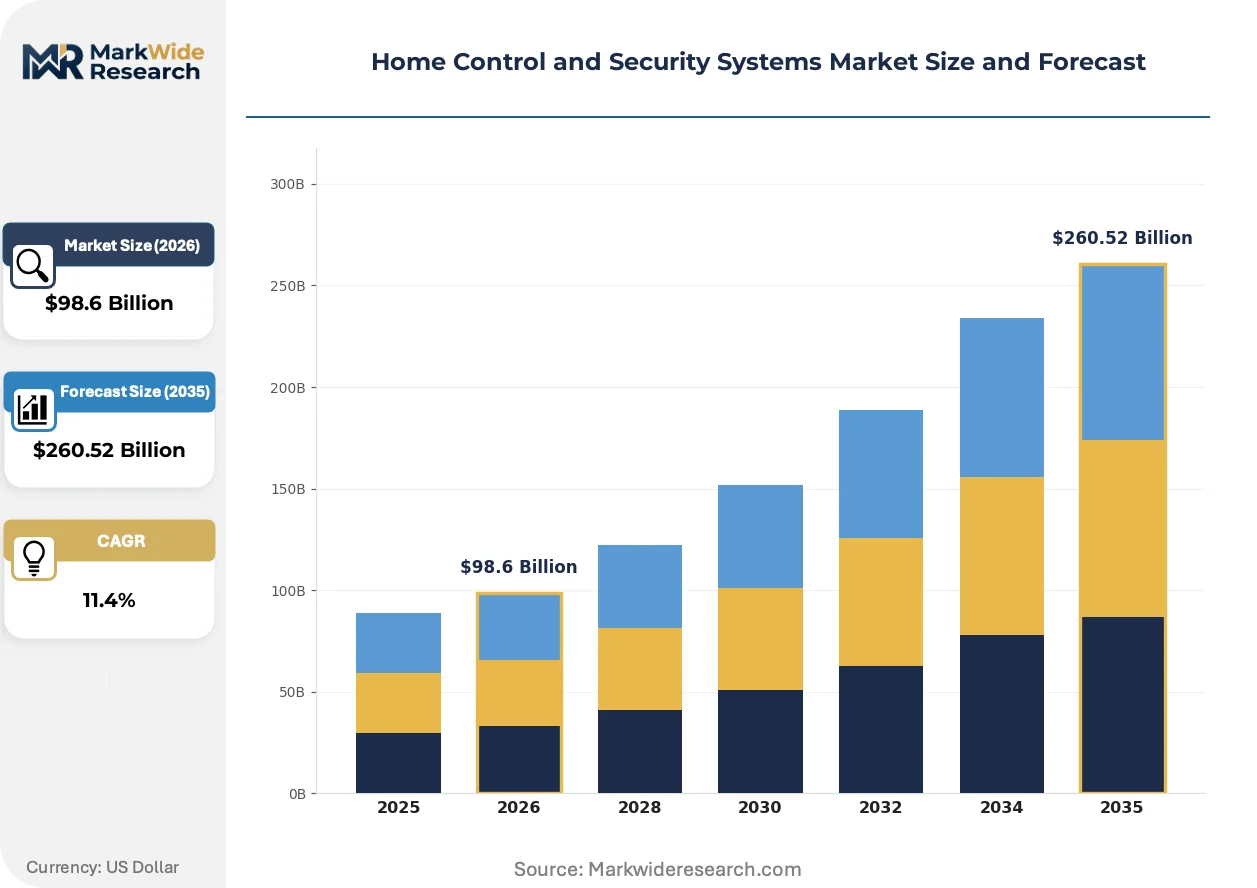
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $260.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Locks, Security Cameras, Alarm Systems, Sensor Systems Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave End User: Homeowners, Renters, Property Managers, Real Estate Developers Application: Home Automation, Surveillance, Remote Monitoring, Intrusion Detection |
| Companies Covered | Honeywell International Inc., ADT Inc., Johnson Controls, Hangzhou Hikvision Digital Technology, ASSA ABLOY, Resideo Technologies Inc., Robert Bosch, Allegion plc, SimpliSafe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Control and Security Systems Market Emerging Trajectories
Edge computing architectures are displacing cloud-dependent processing as latency requirements tighten and privacy regulations harden data localization mandates across major economies.
Video management software is virtualizing physical security operations by enabling remote guard replacement through AI-verified event filtering. Large multi-site retail and logistics operators are deploying these systems at scale across distribution centers and storefront networks. This virtualization is compressing manned guarding expenditure while elevating technical sophistication requirements for integrator partners.
The EU AI Act's prohibited-practices list is forcing redesign of facial recognition deployments in public-facing residential applications. Vendors must now implement explicit consent workflows and on-device template storage to maintain market access. German and French housing associations are responding by piloting palm-vein alternatives that circumvent biometric classification thresholds.
Property management procurement is consolidating vendor relationships as institutional owners seek operational simplicity across dispersed portfolios. Single-platform contracts covering access, video, and environmental monitoring are displacing point-solution aggregation. This concentration is most visible in Sun Belt multifamily markets where REITs operate thousands of units under centralized facilities management.
Home Control and Security Systems Market Segmentation
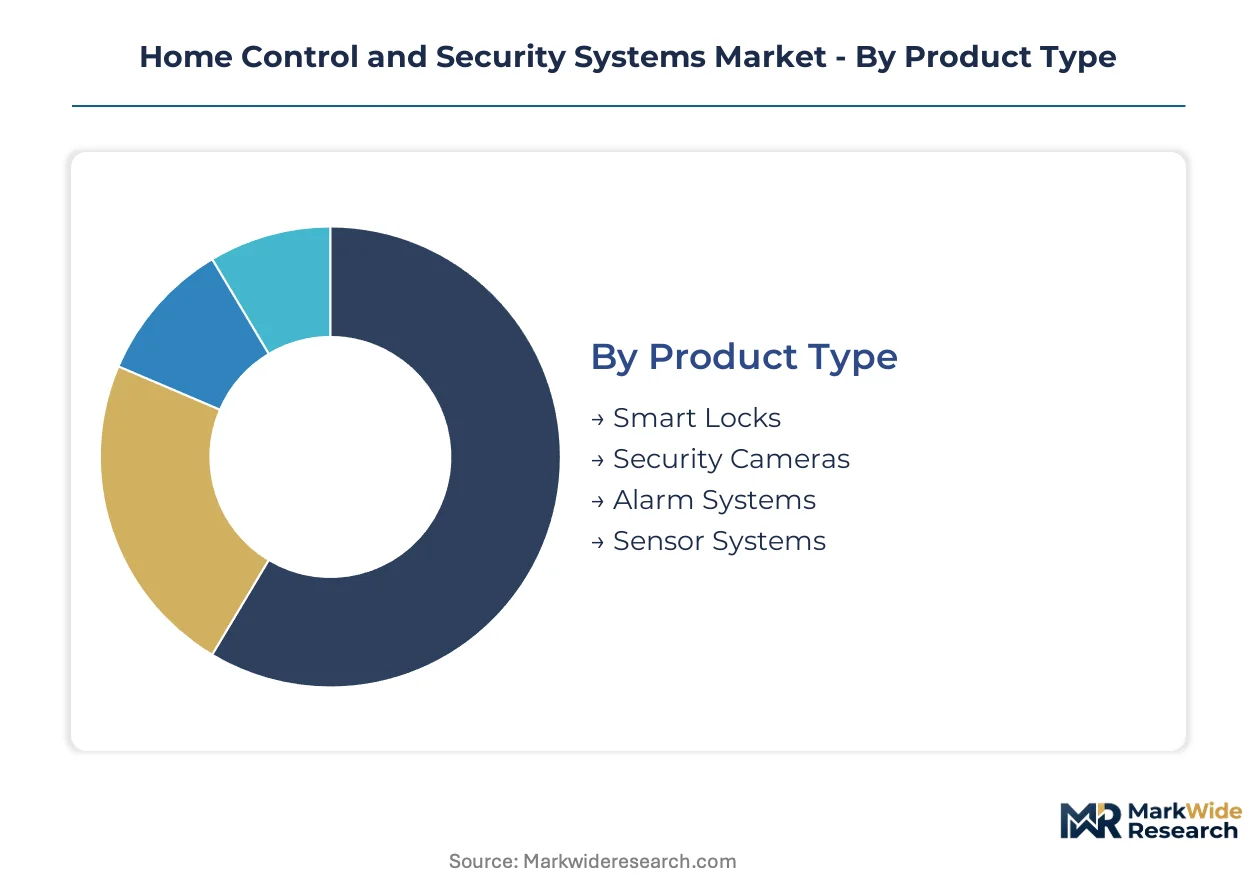
Segmentation in home control and security systems reveals how procurement cycles, technical requirements, and compliance burdens vary dramatically across buyer types and connectivity standards. Understanding these fault lines exposes where vendors can command pricing power versus where commoditization pressures dominate.
Product Type:
Replacement cycles stretch from 3-year camera refresh schedules to 15-year hardwired panel lifespans, creating divergent revenue recognition patterns across hardware categories.
- Security Cameras:CMOS and CCD sensor assemblies with motorized varifocal lenses dominate residential and commercial installations. Property managers in Germany bundle camera upgrades with building energy retrofits to satisfy dual compliance mandates under the EU AI Act and national efficiency regulations.
- Smart Locks:Electromechanical deadbolts with biometric fingerprint modules or Bluetooth credentialing replace mechanical cylinders. Assisted living facilities in France and Texas are accelerating adoption of vein-pattern authentication to circumvent facial recognition prohibitions while maintaining keyless entry workflows.
- Alarm Systems:Centralized intrusion panels with hardwired zone configurations persist in legacy installations. FCC Part 15 compliance requirements govern wireless siren and sensor transmissions in US residential deployments.
- Sensor Systems:PIR motion detectors, glass-break acoustic sensors, and environmental monitors for leak detection. Florida property insurers now mandate monitored water sensors for coastal condominium policies, creating referral channel demand concentration.
Security cameras dominate installed base. Smart locks are where expansion concentrates.
Technology:
Cost tiers separate premium whole-home mesh deployments from standalone consumer devices, with protocol choice determining integration depth and recurring service attach rates.
- Wi-Fi:2.4 GHz and 5 GHz radios enable direct cloud connectivity without hub intermediaries. Standalone camera and doorbell vendors targeting US homeowners prioritize Wi-Fi for frictionless self-installation, though concrete construction in dense urban housing degrades signal reliability.
- Z-Wave:Sub-GHz mesh protocol with 100-meter range and 250-millisecond latency thresholds. Z-Wave Long Range variants penetrate German multi-dwelling retrofits where building materials obstruct higher-frequency signals.
- Zigbee:IEEE 802.15.4-based mesh networking with PRO certification for commercial-grade reliability. Matter protocol convergence is accelerating Zigbee hub adoption as CSA certification enables cross-brand interoperability.
- Bluetooth:Low-energy 2.4 GHz protocol for proximity-based credentialing and device commissioning. Low-cost retrofit cylinders targeting price-sensitive US renters compress margins for full-platform smart lock vendors.
Wi-Fi commands volume leadership in direct-to-consumer channels. Z-Wave and Zigbee are climbing the fastest in professionally installed whole-home systems.
End User:
Customer type dictates procurement complexity, with institutional buyers consolidating vendors while individual consumers prioritize standalone convenience.
- Property Managers:Multi-dwelling operators managing dispersed portfolios across Sun Belt US markets and German urban centers. Single-platform contracts covering access, video, and environmental monitoring displace point-solution aggregation.
- Real Estate Developers:New construction specifiers embedding pre-wired security infrastructure during build phases. Pre-installation of Z-Wave or Zigbee backbone networks enables premium pricing on smart home packages in Texas and Florida master-planned communities.
- Homeowners:Individual purchasers of standalone devices through retail and direct-to-consumer channels. California Consumer Privacy Act constraints on facial recognition data retention force architectural compromises in cloud camera deployments.
- Renters:Temporary residents seeking non-destructive installation options. Bluetooth-enabled retrofit cylinders satisfy this segment without landlord permission requirements.
Property managers dominate enterprise contract value. Real estate developers are where pre-installation platform commitments concentrate.
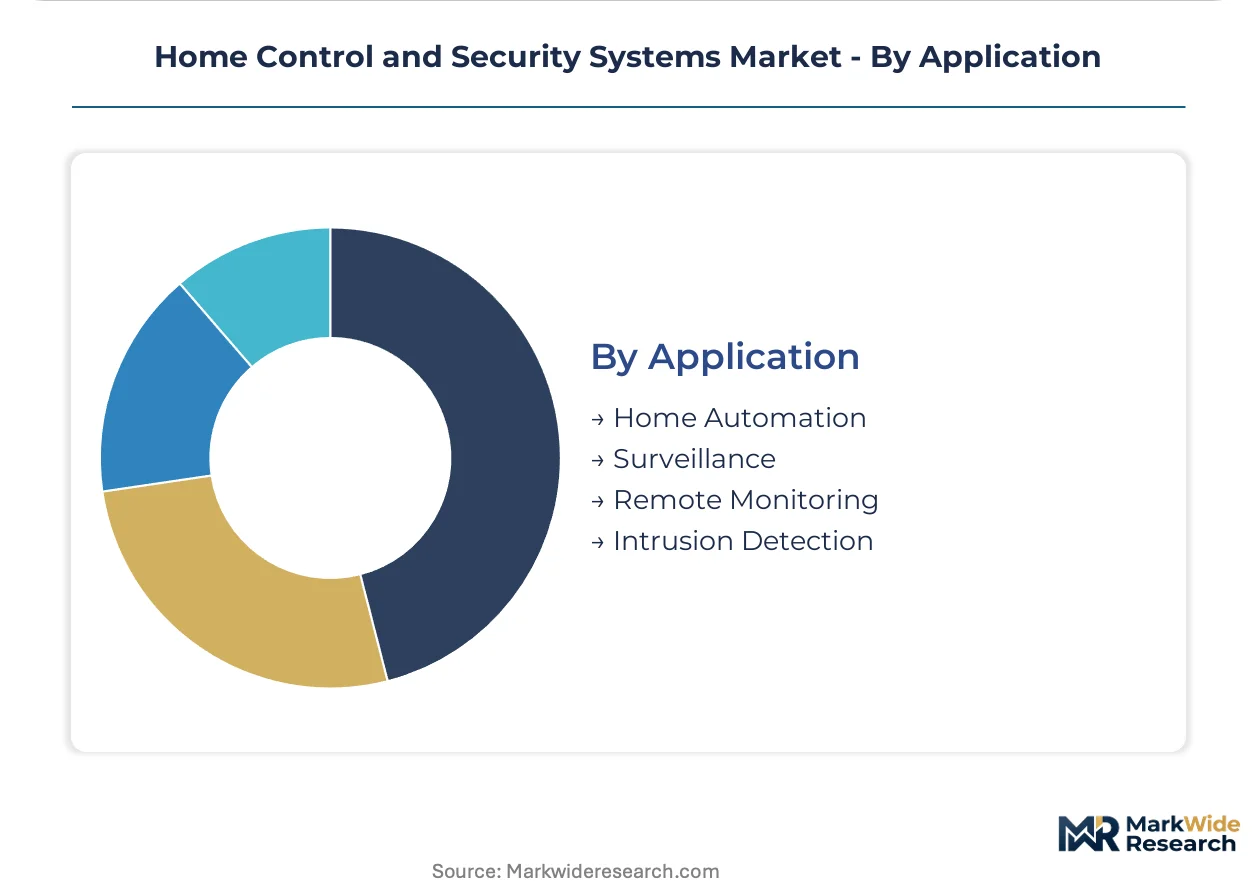
Application:
Functional use case determines sensor fusion requirements and whether edge or cloud processing architectures prevail.
- Surveillance:Continuous video recording with AI-verified event filtering for remote guard replacement. Large US retail and logistics operators deploy virtualized security operations across distribution centers, compressing manned guarding expenditure.
- Intrusion Detection:Perimeter and interior monitoring with real-time alert transmission below 250-millisecond thresholds. EU Cybersecurity Act baseline certification extends product launch cycles for connected sensor manufacturers accessing European markets.
- Home Automation:Integrated control of lighting, climate, and security through unified dashboards. Matter protocol adoption reduces consumer switching costs and expands ecosystem attach rates for hub-anchored vendors.
- Remote Monitoring:Cloud-based visibility and automated response to operational anomalies. On-premise processing retrofits are proliferating as Illinois and Texas biometric regulations harden data localization requirements.
Surveillance commands the largest technology expenditure. Home automation is where cross-category integration revenue concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German property managers bundle security upgrades with building energy retrofits, while US Sun Belt operators prioritize insurance-mandated leak detection. Chinese manufacturing clusters dominate camera sensor supply, though European compliance requirements reshape local procurement patterns.
United States
Florida and Texas property insurers now mandate monitored water sensors for coastal condominium policies, creating referral-driven demand concentration. The FCC governs radio frequency allocations for wireless security devices under Part 15 rules. Dallas-Fort Worth multifamily REITs consolidate vendor relationships across thousands of units under centralized facilities management.
Germany
Building energy retrofit mandates converge with smart infrastructure upgrades, bundling procurement for integrated security and HVAC control systems. The EU AI Act mandates risk classification for biometric-enabled devices, accelerating compliant edge-processing investment. Berlin housing associations pilot palm-vein authentication to circumvent facial recognition prohibitions while maintaining keyless entry.
China
Video analytics manufacturing scale extends cost advantages in camera sensor production for export markets. The country's national cybersecurity regulator imposes data localization requirements on connected home products. Hangzhou-based production clusters supply CMOS assemblies to global integrators facing Taiwan and South Korean foundry concentration risks.
United Kingdom
GDPR constraints on biometric data retention force architectural compromises in cloud camera deployments for residential channels. The Information Commissioner's Office enforces explicit consent workflows for facial recognition systems. London property managers demand single-pane dashboards unifying access, surveillance, and environmental control across dispersed portfolios.
France
Assisted living facilities accelerate adoption of vein-pattern authentication to maintain keyless entry without triggering EU AI Act biometric classification. The CNIL regulates facial recognition deployments in public-facing residential applications. Lyon-based integrators develop on-device template storage solutions for compliant edge architectures.
Home Control and Security Systems Market Vendor Landscape
Capability concentration sits with building automation heritage players; scale advantage sits with video analytics manufacturers. The market structures around three tiers: enterprise-grade platform vendors, professionally monitored service providers, and direct-to-consumer device specialists. Consolidation pressure intensifies as multi-dwelling property managers reject fragmented point solutions. Dominant competitive moves include insurance channel partnerships and Matter protocol certification investments.
Within the building automation tier, Honeywell International Inc. and Johnson Controls occupy positions anchored by enterprise security deployments. ADT Inc. exemplifies the professionally monitored service model. Hangzhou Hikvision Digital Technology represents manufacturing-scale video analytics supply. These three archetypes illustrate how heritage infrastructure, recurring service bundles, and production scale constitute distinct competitive vectors.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ADT Inc. |
| Johnson Controls |
| Hangzhou Hikvision Digital Technology |
| ASSA ABLOY |
| Resideo Technologies Inc. |
| Robert Bosch |
| Allegion plc |
| SimpliSafe Inc. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors connecting Hangzhou manufacturing clusters to German port terminals transmit cost volatility directly into smart lock and camera module pricing, amplifying margin compression for vendors lacking long-term offtake agreements while enabling tiered pricing power for those with captive foundry relationships.
Pricing Analysis
Long-term offtake agreements dominate enterprise procurement for multi-dwelling property managers, while spot-market transactions prevail in direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified whole-home platforms from Bluetooth retrofit cylinders and unbranded white-label imports. Cost compression in the economy tier is intensifying because low-cost Chinese manufacturers are flooding European markets with uncertified alternatives. Renters exhibit highest price sensitivity, seeking sub-fifty-dollar retrofit solutions without subscription obligations.
Supply Chain Analysis
Export-control regimes restricting semiconductor manufacturing equipment to Chinese fabs are constraining CMOS sensor supply expansion despite surging demand. Taiwan and South Korean foundries anchor camera image sensor production, while Chinese assembly plants handle final device integration. Raw material dependencies include rare-earth magnets for lock motors, lithium-ion cells for battery backup, and copper for RF antenna traces. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity for edge-processing chips. Distribution runs through professional integrator networks for commercial deployments and retail big-box channels for consumer self-installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional property managers consolidating vendor relationships across dispersed portfolios, compressing margins for fragmented point-solution providers unable to deliver unified access, video, and environmental dashboards.
For Market Incumbents: Build switching-cost moats through Matter protocol certification investments that lock property managers into hub-anchored ecosystems. Deepen backward integration into sub-GHz radio module production to offset Taiwan foundry concentration risk. Prioritize insurance channel partnerships in Florida and Texas where underwriters mandate monitored leak detection, creating referral-driven customer acquisition barriers against emerging competitors. For New Entrants and Emerging Players: German assisted living facilities represent underpenetrated demand for palm-vein authentication systems circumventing EU AI Act facial recognition prohibitions. Target vein-pattern biometric hardware bundled with temporary credentialing SaaS for French and Texas senior housing operators. Pursue white-label supply agreements with Lyon-based integrators developing on-device template storage for compliant edge architectures. For Investors and Strategic Acquirers: Edge-computing security specialists with EU Cybersecurity Act pre-certification represent the most defensible acquisition targets as compliance timelines extend launch cycles for uncertified competitors. Long-term viability hinges on regulatory moats deepening rather than interoperability standards commoditizing hardware. Watch for German housing association procurement consolidation announcements as inflection indicators for platform vendor concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | CSA certification enables cross-brand interoperability that reduces consumer switching costs for hub-anchored vendors. |
| Insurance Channel Partnership | Florida and Texas underwriters mandate monitored sensors, creating referral-driven customer acquisition concentration. |
| Edge Processing Architecture Investment | On-device template storage satisfies EU AI Act biometric prohibitions while avoiding cloud data retention limits. |
| Sub-GHz Radio Module Integration | Z-Wave Long Range and Zigbee PRO penetration in German concrete construction retrofits demands mesh reliability. |
| Biometric Credentialing SaaS Launch | Vein-pattern authentication displaces facial recognition in assisted living facilities, opening recurring revenue streams. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with smart home platform engineers, multi-dwelling property management technology officers, professional security integrators, and insurance risk assessment specialists; and secondary validation against FCC Part 15 filings, EU Cybersecurity Act certification databases, SEC 10-K disclosures from building automation vendors, and German federal building energy retrofit procurement records. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation against aggregate platform licensing revenue produced convergent market sizing.
Forecast inputs considered product-type replacement cycles stretching from 3-year camera refresh schedules to 15-year hardwired panel lifespans, technology-protocol adoption curves across Wi-Fi and sub-GHz mesh standards, and end-user procurement consolidation patterns among Sun Belt REITs and German housing associations. CAGRs were derived from segment-level growth rate reconciliation across connectivity standards and buyer archetypes. Modeled variables included EU AI Act compliance cost pass-through rates and semiconductor foundry capacity utilization thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese camera sensor manufacturers would shift outcomes beyond modeled ranges. Material shifts in Taiwan Strait logistics reliability or EU Cybersecurity Act certification timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Smart Locks Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Automated Barriers and Bollards Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
India Access Control Hardware Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Europe Airport Passenger Screening Systems Market