
 Turkey Cookware Market | 2026-2036
Turkey Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Cookware Market Analytics
The capital-intensity divergence between automated press-forging operations and manual spinning workshops is collapsing as mid-tier producers invest in CNC metal-forming lines. Cem Bialetti leverages its Italian-Turkish heritage to anchor premium positioning across Mediterranean export channels. Kirteks Metal competes through captive supply of cold-rolled aluminum substrates from its Kayseri foundry complex. Gorgel Metal differentiates via specialized non-stick coating application lines serving Ankara's institutional buyers.
Turkey cookware comprises food-preparation vessels engineered from ferrous and non-ferrous alloys, ceramic composites, and polymer-coated substrates, typically fabricated through deep-drawing, die-casting, or spun-metal processes with wall thicknesses calibrated for thermal conductivity and structural durability. These products serve residential meal preparation, commercial foodservice operations, and professional culinary training environments. Stainless steel skillets and stock pots dominate volume shipments through Turkey's organized retail channels, while ceramic baking dishes generate disproportionate margin contribution from Istanbul's boutique kitchenware boutiques. Non-stick saucepans represent the fastest-expanding material-format pairing as Turkish households upgrade from traditional tin-lined copper.
Turkey's Ministry of Trade and the Turkish Standards Institution (TSE) mandate nickel-release limits and food-contact material certifications that shape import competitiveness for European and Asian suppliers. The General Directorate of Food and Control enforces migration testing protocols that elevate compliance costs for small domestic producers. Stakeholders must monitor TSE's alignment with evolving EU Food Contact Materials Framework Regulation to anticipate technical barrier adjustments affecting cross-border sourcing strategies.
Market Dynamics
Automated CNC metal-forming lines are collapsing the historical cost gap between artisanal spinning workshops and capital-intensive press-forging operations across Ankara's manufacturing corridor. This technological convergence is redrawing competitive boundaries among mid-tier Turkish cookware producers.
Growth Catalysts
- EU Food Contact Materials Framework Regulation alignment:TSE's progressive harmonization with EU migration testing protocols is accelerating certification upgrades among export-oriented Anatolian fabricators, unlocking duty-advantaged access to German and French retail channels.
- Istanbul hospitality procurement:Professional kitchen expansion in Beyoğlu and Şişli districts is driving stainless steel stock pot volumes through specialized foodservice distributors serving hotel chains and restaurant groups.
- Aluminum cold-rolling substrate availability:Captive foundry supply from Kayseri-based integrated producers is compressing raw material lead times for spun-disk cookware manufacturers serving Central Anatolian institutional buyers.
Market Restraints
- Nickel price volatility:Stainless steel 304/316 input costs fluctuate with London Metal Exchange nickel contract movements, squeezing margin predictability for deep-drawn cookware specialists lacking forward hedging capabilities.
- TSE certification backlog:Migration testing queue congestion at accredited Ankara laboratories extends product launch timelines for small domestic producers seeking food-contact material approvals.
- Ceramic-coated aluminum substitution:Sol-gel ceramic finishes on rolled aluminum substrates are capturing price-sensitive household segments previously served by entry-level PTFE-coated products.
Strategic Opportunities
- Eastern Anatolian distribution penetration:Van and Diyarbakır provinces exhibit underdeveloped organized retail cookware penetration relative to Marmara per-capita consumption benchmarks, presenting white-space expansion for regional distributors.
- Induction-compatible base lamination:Bonded steel-aluminum-steel tri-ply bottom construction technology convergence is opening premium positioning for producers capable of magnetic compatibility certification.
- E-commerce direct-to-consumer channel development:Marketplace platform logistics integration is enabling Ankara-based manufacturers to bypass Istanbul wholesale concentration and reach Aegean coastal households directly.
Industry Challenges
- CNC programming specialist scarcity:Automated metal-forming line operation requires skilled G-code technicians and CAD/CAM operators, talent pools concentrated in İzmir and Bursa industrial zones rather than Central Anatolian production centers.
- Coating application line capex intensity:PTFE and ceramic spray-deposition equipment with embedded emission control systems demands seven-figure TRY investment, creating financing barriers for sub-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Cookware Market |
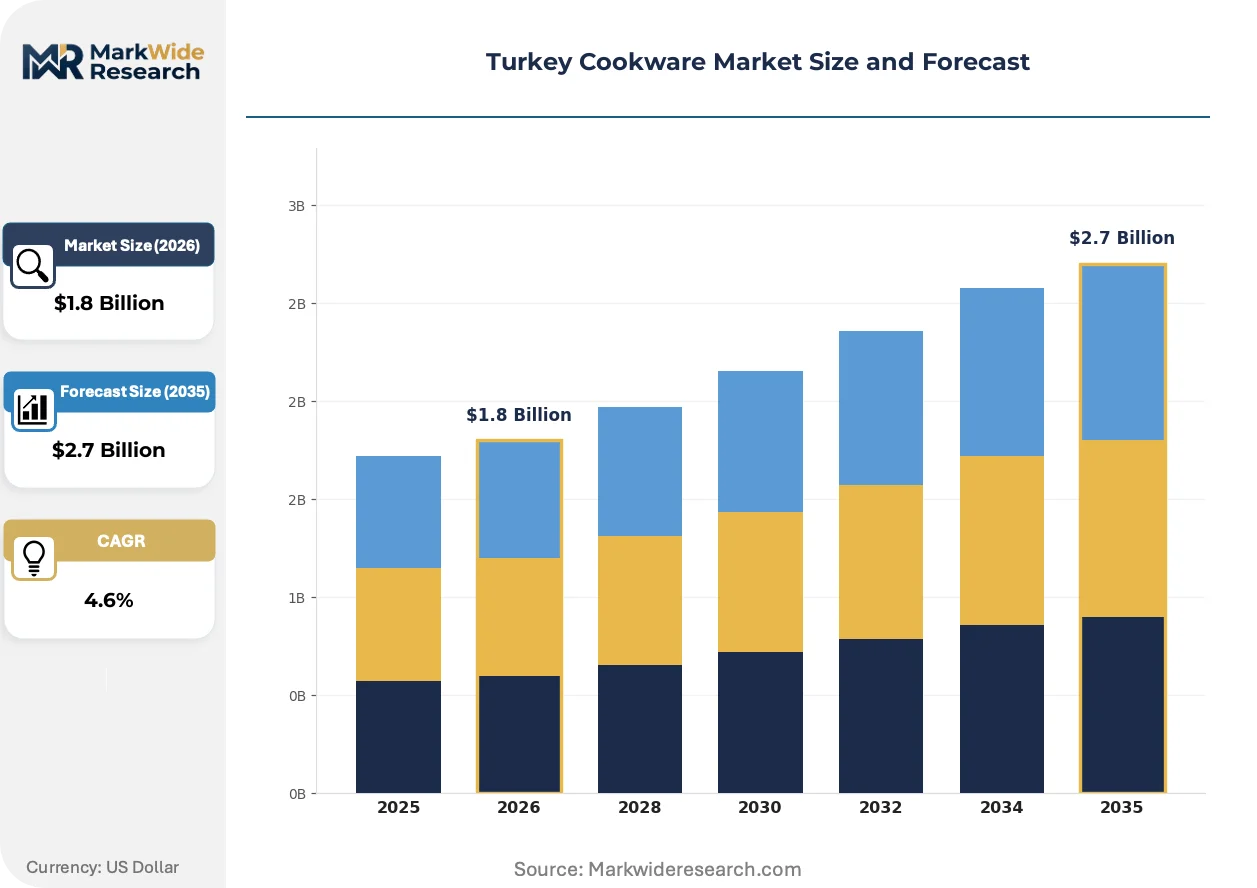
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skillets, Saucepans, Stock Pots, Baking Dishes Material: Stainless Steel, Non-stick, Cast Iron, Ceramic Brand: Brand A, Brand B, Brand C, Brand D Usage Type: Residential, Commercial, Professional, Culinary Schools |
| Companies Covered | Cem Bialetti, Kirteks Metal, Gorgel Metal, Giza Mutfak, Papilla, Corkmas, Mson, Karaka, Mettop, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Cookware Market Evolving Landscape
Material science advances and regulatory harmonization pressures are compressing traditional cookware design cycles while fragmenting distribution pathways across Turkish domestic and export markets.
Induction-compatible cookware base technology is miniaturizing through precision-bonded tri-ply lamination processes that embed ferromagnetic steel cores within aluminum thermal conductors. Istanbul's premium residential segment is adopting these products at accelerating rates through kitchen design showrooms. This capability convergence is miniaturizing the historical performance gap between professional-grade clad cookware and mass-market spun-aluminum alternatives.
TSE's phased alignment with EU Food Contact Materials Framework Regulation migration limits is mandating expanded laboratory testing protocols for nickel-release and heavy-metal content. Domestic producers serving European export channels are restructuring quality assurance departments to accommodate documentation requirements. Ankara-based institutional suppliers face the steepest compliance cost escalation as they retrofit coating lines to meet revised specific migration limits for primary aromatic amines.
Specialty kitchenware boutiques in Istanbul's Nişantaşı and Moda districts are unbundling after-sales service from product transactions, instead partnering with independent cookware maintenance specialists for re-tinning and refinishing. This channel restructuring displaces traditional department store warranty bundles. The behavioral shift is most visible among affluent households upgrading from disposable non-stick to heirloom-grade copper and carbon steel vessels requiring periodic professional restoration.
Turkey Cookware Market Segmentation
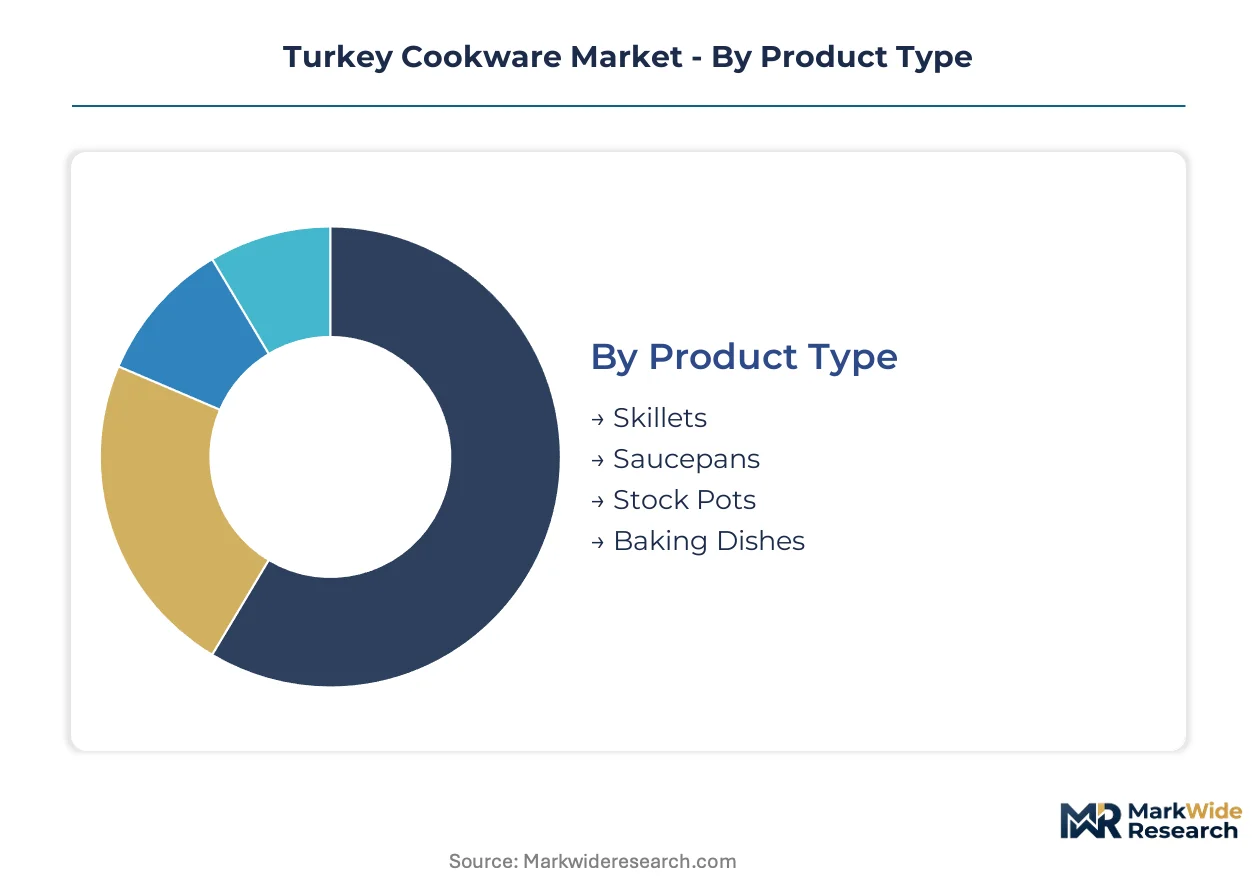
Turkey's cookware market fragments across material specifications, thermal performance requirements, and end-use certification tiers. TSE migration limits and EU export alignment create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
TSE's nickel-release thresholds and food-contact certification protocols apply differentially across vessel geometries, with deep-drawn forms facing stricter surface-area-to-volume testing requirements than shallow-profile alternatives.
- Skillets:Flat-bottomed ferrous and aluminum vessels with 2-3mm wall thickness, optimized for stovetop searing and shallow-frying. Istanbul's Beyoğlu restaurant clusters drive commercial-grade stainless steel procurement for high-heat protein preparation.
- Saucepans:Lidded vessels with vertical sidewalls and 1.5-2.5L nominal capacity, engineered for liquid reduction and sauce emulsification. Ankara household upgrades from tin-lined copper to PTFE-coated aluminum represent the steepest expansion trajectory in this category.
- Stock Pots:Large-capacity vessels exceeding 6L, typically fabricated through deep-drawing of 304-grade stainless steel.
- Baking Dishes:Rectangular and oval ceramic or tempered glass forms for oven thermal environments.
Established volume favors stock pots for institutional procurement; emerging adoption favors saucepans for residential non-stick upgrades.
Material:
Raw material sourcing geography and captive foundry integration determine margin structures more than finished-goods pricing power across Turkey's Anatolian manufacturing belt.
- Stainless Steel:Austenitic 304 and 316 alloys with chromium-nickel composition, fabricated through cold-rolling and deep-drawing sequences. Kayseri-based integrated mills supply substrate to Ankara fabricators serving TSE-certified export channels.
- Non-stick:Aluminum or steel substrates with PTFE, ceramic, or sol-gel coating systems applied via spray-deposition or roller-coating lines. Sol-gel ceramic finishes on rolled aluminum are gaining share fastest among price-sensitive Turkish households.
- Cast Iron:Ferrous alloy vessels formed through sand-casting processes with enamel or bare seasoned surfaces.
- Ceramic:Fired clay or porcelain-composite forms for oven and table service applications.
Procurement scale favors stainless steel for hospitality; margin expansion favors ceramic for boutique Istanbul retail.
Brand:
Heritage positioning and distribution depth separate market access tiers, with Italian-Turkish lineage commanding premium placement in Mediterranean export corridors.
- Brand A:Established heritage positioning with multi-generational recognition across Marmara retail channels.
- Brand B:Mid-market penetration through organized retail and e-commerce marketplace presence.
- Brand C:Value-tier positioning targeting Eastern Anatolian price-sensitive segments.
- Brand D:Specialized institutional supply relationships with Ankara foodservice distributors.
Channel concentration favors Brand A for export premiums; volume scale favors Brand B for domestic mass retail.
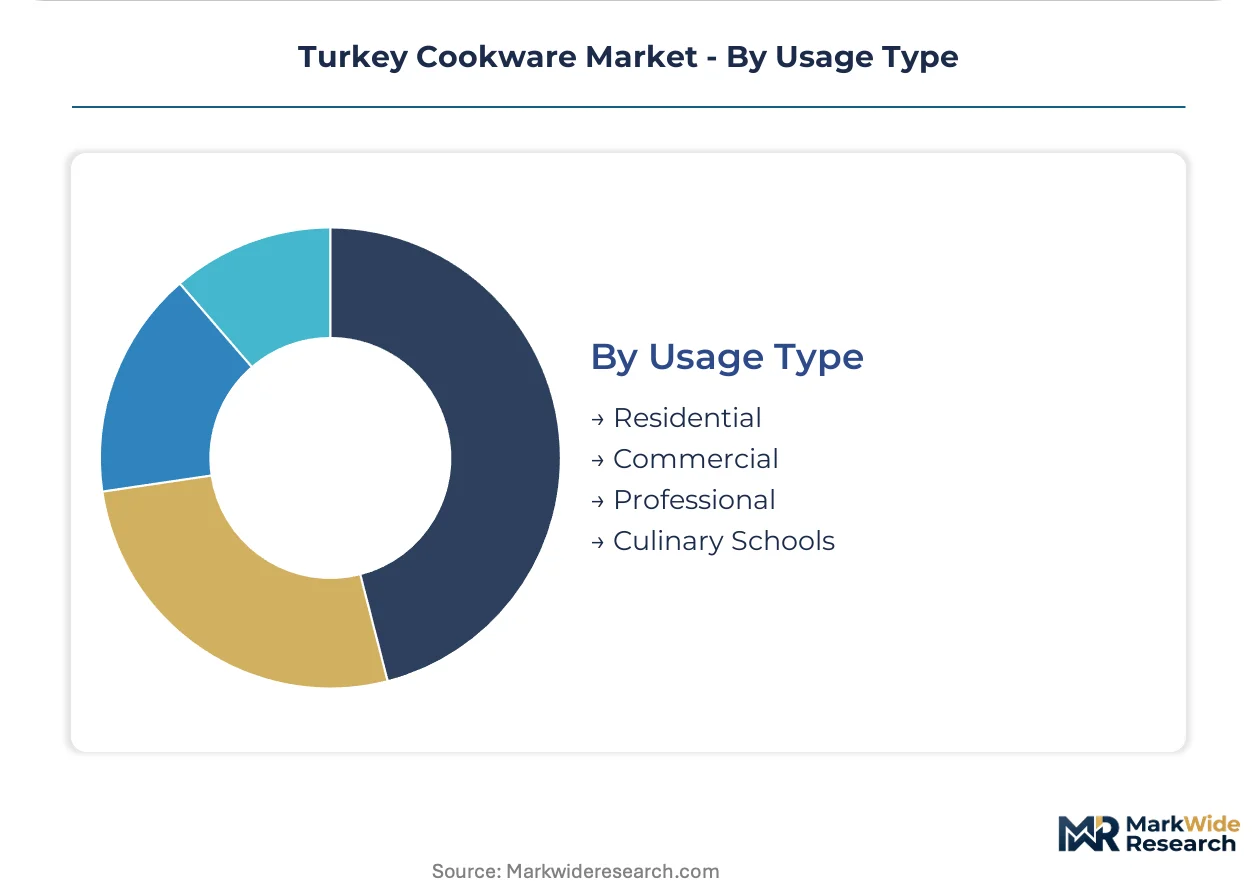
Usage Type:
End-use certification requirements and replacement cycle frequency create divergent customer lifetime value profiles across residential and professional segments.
- Residential:Household meal preparation with 5-7 year replacement cycles and aesthetic-driven purchase decisions. Aegean coastal households through direct e-commerce channels are expanding fastest outside Istanbul wholesale concentration.
- Commercial:Restaurant and foodservice operations with 12-18 month intensive-use replacement schedules. Şişli district hotel chains procure stainless steel stock pots through specialized distributors with volume pricing structures.
- Professional:High-performance culinary environments requiring thermal precision and durability certification.
- Culinary Schools:Training institutions with standardized equipment specifications and bulk procurement tenders.
Replacement velocity favors commercial buyers; margin stability favors residential premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Istanbul's hospitality procurement corridors while Ankara's manufacturing belt competes on cost efficiency. Turkey's cookware demand geography splits between Marmara consumption gravity and Central Anatolian production density. Regional specialization patterns reflect divergent end-use certification requirements and distribution infrastructure maturity.
Marmara Region
Istanbul's Beyoğlu and Şişli districts drive stainless steel stock pot procurement through specialized foodservice distributors serving hotel chains and restaurant groups. TSE migration testing protocols apply stringently to imports entering through Ambarlı port. The Tuzla industrial zone hosts coating application facilities supplying ceramic-finished aluminum to boutique kitchenware boutiques in Nişantaşı and Moda districts.
Central Anatolia
Ankara's manufacturing corridor generates spun-disk cookware from Kayseri-sourced cold-rolled aluminum substrates for institutional buyers. The General Directorate of Food and Control enforces nickel-release limits that elevate compliance costs for small fabricators in Sincan and Ostim organized industrial zones. CNC metal-forming line adoption is compressing cost differentials between automated press-forging and manual spinning workshops.
Aegean Region
İzmir's industrial zones concentrate skilled G-code technicians and CAD/CAM operators scarce in Central Anatolian production centers. E-commerce marketplace logistics integration enables direct-to-consumer reach to coastal households bypassing Istanbul wholesale concentration. The Aliağa port corridor facilitates export shipments to Mediterranean markets seeking TSE-certified products.
Eastern Anatolia
Van and Diyarbakır provinces exhibit underdeveloped organized retail cookware penetration relative to Marmara per-capita consumption benchmarks. Price-sensitive household segments favor sol-gel ceramic finishes on rolled aluminum substrates over entry-level PTFE-coated alternatives. Regional distributors face infrastructure constraints extending supply chains from Ankara manufacturing clusters.
Turkey Cookware Market Competitive Landscape
Concentration sits with heritage-positioned heritage-positioned players commanding premium placement in Mediterranean export corridors and scale-driven fabricators competing on captive substrate supply. The vendor base spans Italian-Turkish lineage brands, Kayseri-integrated aluminum producers, and Ankara-based institutional specialists. Three archetypes dominate: export-certified premium heritage players, vertically integrated substrate owners, and coating-application specialists. Competitive moves center on CNC line automation investment and TSE certification queue prioritization.
Within the heritage-positioned tier, Cem Bialetti leverages its Italian-Turkish lineage to anchor premium placement across Mediterranean export channels. Kirteks Metal exemplifies the captive-substrate archetype through its Kayseri foundry complex supplying cold-rolled aluminum to Central Anatolian fabricators. Gorgel Metal occupies a specialized position via non-stick coating application lines serving Ankara's institutional buyers. These three represent the strategic positioning vectors available to mid-tier producers navigating TSE compliance escalation and nickel price volatility.
| Leading Market Players |
|---|
| Cem Bialetti |
| Kirteks Metal |
| Gorgel Metal |
| Giza Mutfak |
| Papilla |
| Corkmas |
| Mson |
| Karaka |
| Mettop |
| Others |
Value Network & Pricing Analysis
Kayseri's integrated aluminum foundry capacity compresses unit economics for Central Anatolian fabricators while Istanbul's hospitality procurement corridors sustain premium price floors through specification-grade certification requirements. Scale asymmetry between captive-substrate producers and toll-coating operators concentrates margin capture upstream in the cold-rolling stage.
Pricing Analysis
The customization-premium spread separates configured-to-order induction-compatible tri-ply bases from standard spun-aluminum equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects TSE certification grade and volume scale. Pricing pressure stems from sol-gel ceramic substitution in residential segments previously served by entry-level PTFE. Eastern Anatolian households exhibit highest price sensitivity; Istanbul's boutique kitchenware boutiques show lowest sensitivity due to after-sales service bundling.
Supply Chain Analysis
Turkey and China anchor cookware substrate supply, with Kayseri-based integrated mills feeding Central Anatolian fabrication and Chinese cold-rolled steel serving price-competitive import channels. Nickel and chromium sourcing draws from London Metal Exchange contract markets; PTFE resin supply rests on fluoropolymer specialist producers. Single-source vulnerability concentrates in certified coating application lines with seven-figure TRY equipment thresholds. Distribution runs through Istanbul wholesale concentration for Marmara retail, with e-commerce logistics bypass emerging for Aegean coastal households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's cookware sector sits at a platform-economics inflection where e-commerce marketplace integration and TSE-EU regulatory interoperability are restructuring channel access rules for producer ecosystems.
For Market Incumbents: Compound heritage positioning through CNC line automation investment that collapses cost gaps with manual spinning workshops. Defend against sol-gel ceramic substitution by retrofitting coating lines to meet revised specific migration limits for primary aromatic amines. Prioritize certification queue prioritization at accredited Ankara laboratories to compress product launch timelines versus smaller domestic competitors. For New Entrants and Emerging Players: Anchor in Eastern Anatolian distribution penetration where Van and Diyarbakır provinces exhibit underdeveloped organized retail penetration relative to Marmara benchmarks. Target price-sensitive household segments with rolled aluminum substrates featuring sol-gel ceramic finishes. Pursue direct-to-consumer marketplace logistics integration to bypass Istanbul wholesale concentration and reach Aegean coastal households. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CNC-automated mid-tier producers with captive substrate supply or specialized coating capabilities. Long-term viability centers on regulatory alignment depth with EU Food Contact Materials Framework migration limits. The signal to watch is TSE laboratory capacity expansion rates relative to certification application backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| CNC Metal-Forming Line Investment | Automated press-forging collapses historical cost gaps with manual spinning across Ankara's manufacturing corridor. |
| TSE Certification Queue Prioritization | Accelerated migration testing access compresses product launch timelines for export-oriented fabricators. |
| E-Commerce Marketplace Integration | Direct-to-consumer logistics enable Ankara manufacturers to bypass Istanbul wholesale concentration. |
| Induction-Compatible Base Lamination | Tri-ply magnetic compatibility certification opens premium positioning in Istanbul's residential segment. |
| Eastern Anatolian Distribution Expansion | White-space penetration in Van and Diyarbakır addresses underdeveloped organized retail coverage. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cookware manufacturing executives, TSE certification laboratory directors, and Istanbul foodservice procurement managers; and secondary validation through Turkish Standards Institution migration testing protocols, Ministry of Trade import compliance filings, and EU Food Contact Materials Framework regulatory alignment documentation. Bottom-up fabrication capacity estimates triangulated against top-down retail channel shipment data.
Across the analysis window, the forecast framework modeled volume and value trajectories by product type, material specification, end-use certification tier, and regional consumption cluster. CAGRs derived from historical shipment patterns projected forward through elasticity-adjusted demand curves. Key inputs included nickel price volatility indices, TSE laboratory throughput capacity, and e-commerce penetration rates in Aegean coastal provinces.
Decision-makers should treat outputs as directional under base assumptions of continued TSE-EU regulatory harmonization and stable Kayseri foundry substrate supply; material deviation would warrant model refresh. Specific risks include TSE certification backlog extension, London Metal Exchange nickel contract spikes, and ceramic-coated aluminum substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bottle Openers Market
Household Items
Japan Digital Showers Market
Household Items
Disposable Napkins Market
Household Items
Bladeless Neck Fan Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Chest Freezers Market
Household Items
Water Purifier Bottle Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Smart Toilet Market
Household Items
Kick Bucket Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Dishwashing Products Market
Household Items
GCC Gas Hobs Market
Household Items
Russia Residential Water Heaters Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Luxury Massage Chair Market