
 Russia Residential Water Heaters Market | 2026-2036
Russia Residential Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Residential Water Heaters Market Analytics
Multi-story residential construction in Moscow is expanding its share of water heater procurement, shifting volume toward wall-mounted electric and compact gas-fired systems. Thermex dominates the domestic channel through its captive production base in the Leningrad region. Ariston Thermo leverages its European engineering heritage to anchor the premium storage segment. Baltgaz Group specializes in gas-fired equipment and controls distribution across Russia's Far Eastern construction corridors.
Russia residential water heaters are pressurized vessels designed to heat and store potable water for household use, typically operating at pressures between 0.6 and 0.8 MPa with tank capacities ranging from 30 to 200 liters depending on dwelling size. These systems serve the essential function of delivering sanitary hot water to kitchens, bathrooms, and laundry facilities in single-family homes and apartments where centralized district heating is unavailable or unreliable. Storage-type units still occupy the largest installed base across Russian households, though tankless systems are gaining ground in premium urban renovations where space constraints dominate purchase criteria. Heat pump water heaters remain nascent but attract policy-sensitive buyers in regions where electricity tariffs favor renewable-integrated building designs.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST-R certification and energy labeling requirements that determine which products qualify for state-backed housing programs. The Eurasian Economic Commission's technical regulations for low-voltage equipment and gas appliances create a unified compliance barrier across the customs union, filtering out uncertified imports from Central Asian and Chinese suppliers. Russia's Ministry of Construction maintains building codes that mandate minimum efficiency thresholds for new residential developments, directly shaping manufacturer R&D priorities. Stakeholders must monitor how sanctions-driven supply chain restructuring affects component sourcing for electronic control modules and corrosion-resistant tank linings.
Market Dynamics
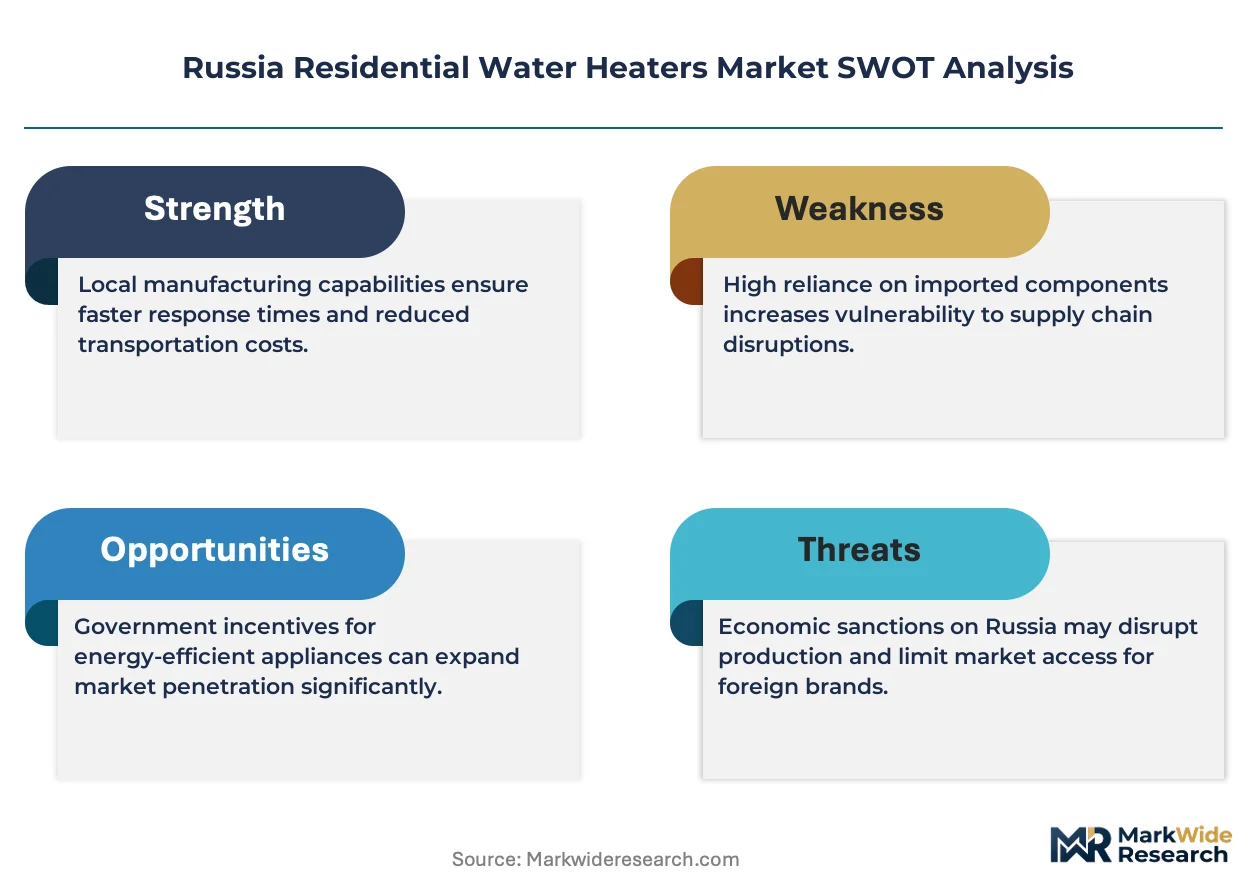
Russia's residential water heater sector operates under intense pressure from energy efficiency mandates and supply chain restructuring. Rosstandart's tightening GOST-R certification requirements are forcing manufacturers to redesign insulation systems and electronic controls while navigating sanctions-affected component sourcing.
Growth Catalysts
- Moscow Urban Renewal:State-funded apartment reconstruction programs in the capital are replacing Soviet-era centralized heating with individual water heating units, creating sustained procurement volume for compact electric and gas-fired systems.
- Eurasian Technical Regulations:The EEC's unified standards for low-voltage equipment and gas appliances are filtering out uncertified Central Asian imports, clearing shelf space for compliant domestic and European suppliers.
- Heat Pump Technology Maturation:Improved cold-climate performance of air-source heat pumps is attracting policy-sensitive buyers in regions with favorable electricity tariffs, particularly in new-build residential developments.
Market Restraints
- Electronic Component Sourcing:Sanctions-driven restrictions on semiconductor and control module imports from Western suppliers are forcing manufacturers toward higher-cost alternative sourcing routes through third-country intermediaries.
- Corrosion-Resistant Tank Linings:Dependence on specialized enamel and stainless steel formulations from European suppliers creates input cost volatility and extended lead times for storage-type unit production.
- District Heating Persistence:Legacy centralized hot water infrastructure in older Russian cities limits addressable market expansion, as many households remain tethered to municipal supply systems despite reliability issues.
Strategic Opportunities
- Far Eastern Construction Corridors:Infrastructure development in Vladivostok and Khabarovsk is outpacing district heating expansion, creating demand for distributed gas-fired water heating in new residential zones.
- Smart Control Convergence:Integration of IoT-enabled diagnostics with traditional tank designs allows manufacturers to command premium positioning through remote monitoring and predictive maintenance features.
- State Housing Subsidies:Russia's Ministry of Construction efficiency mandates for new developments are channeling public procurement toward certified high-insulation units, rewarding compliant suppliers with program eligibility.
Industry Challenges
- GOST-R Certification Timelines:Extended testing protocols for modified product lines delay market entry, compressing revenue recognition windows for seasonal sales cycles.
- Installation Workforce Shortage:Qualified technicians for gas-fired system commissioning are concentrated in legacy industrial centers, creating service bottlenecks in rapidly expanding peripheral regions.
- Legacy Control System Integration:Retrofit installations must accommodate aging Soviet-era plumbing infrastructure with non-standard connection specifications, complicating product standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Residential Water Heaters Market |
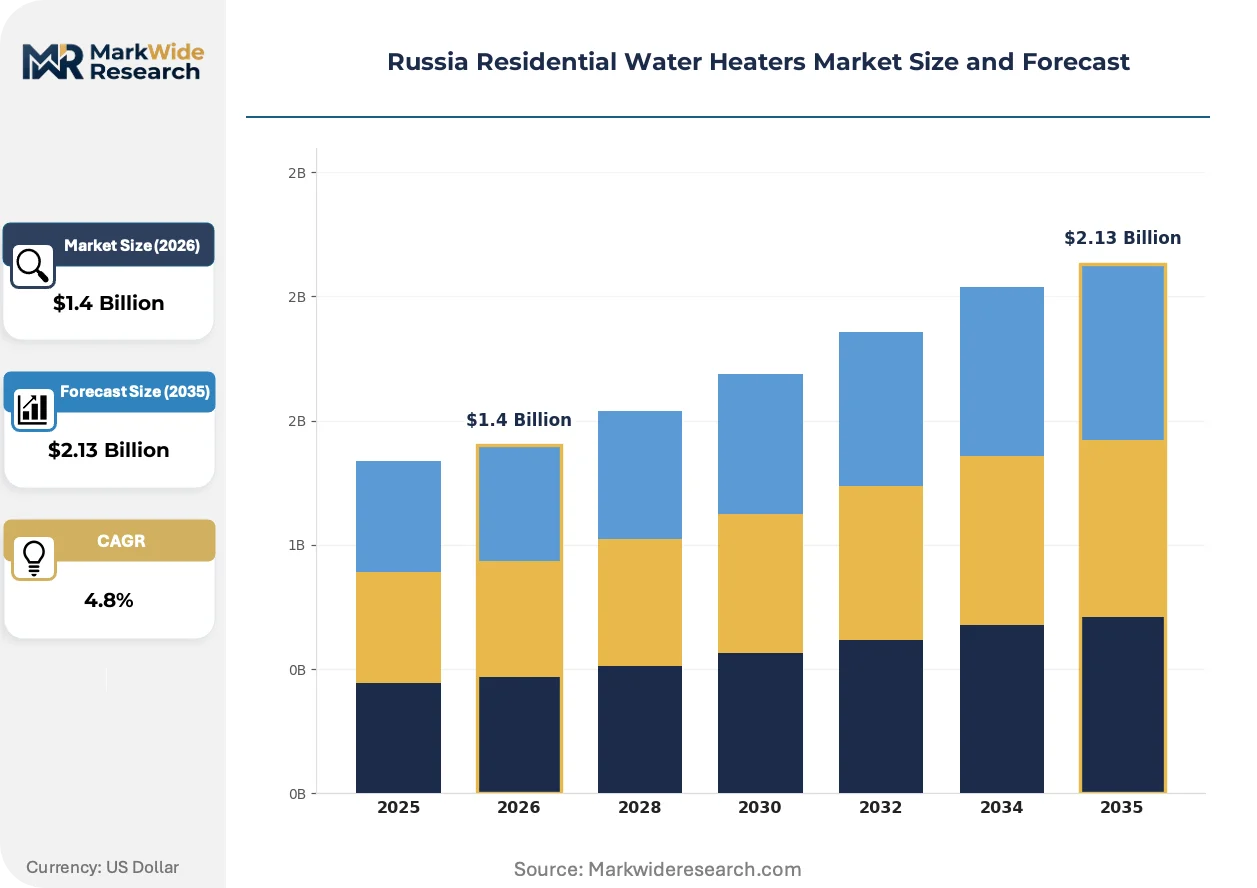
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage, Heat Pump, Solar Energy Source: Electric, Gas, Propane, Biomass Installation Type: Indoor, Outdoor, Under-sink, Wall-mounted Market Segment: Residential, Commercial, Industrial, Others |
| Companies Covered | Lemax, Thermex, Ariston Thermo, Vogel Flug Ltd, Haier, Rheem, Baltgaz Group, Isoterm, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Residential Water Heaters Market Evolving Landscape
Digital control architectures and cold-climate heat pump engineering are redefining product development priorities. Russian manufacturers are racing to embed connectivity features while adapting thermal performance to harsh winter operating conditions.
Heat pump water heaters are integrating variable-speed compressors and enhanced evaporator designs to maintain coefficient-of-performance ratings at ambient temperatures below minus 15 degrees Celsius. Premium developers in Saint Petersburg are specifying these units for eco-certified residential projects. This technology is integrating renewable-energy building mandates with practical cold-climate performance, compressing the historical dominance of pure electric resistance heating in new construction.
Rosstandart's 2024 amendments to energy labeling requirements are mandating digital display of actual consumption data alongside standardized efficiency ratings. Manufacturers must now equip units with embedded metering chips to qualify for state-backed mortgage programs. The storage segment faces the steepest compliance costs, as legacy analog control platforms require complete redesign to meet the new technical regulations.
Builder procurement is consolidating around turnkey mechanical package suppliers who bundle water heating with HVAC and ventilation systems. Large Moscow developers are negotiating multi-year framework agreements with single-source providers, displacing traditional distributor-mediated spot purchasing. This concentration is most visible in the Central Federal District, where integrated design-build firms dominate new apartment construction and specify equipment at the schematic design phase.
Russia Residential Water Heaters Market Segmentation
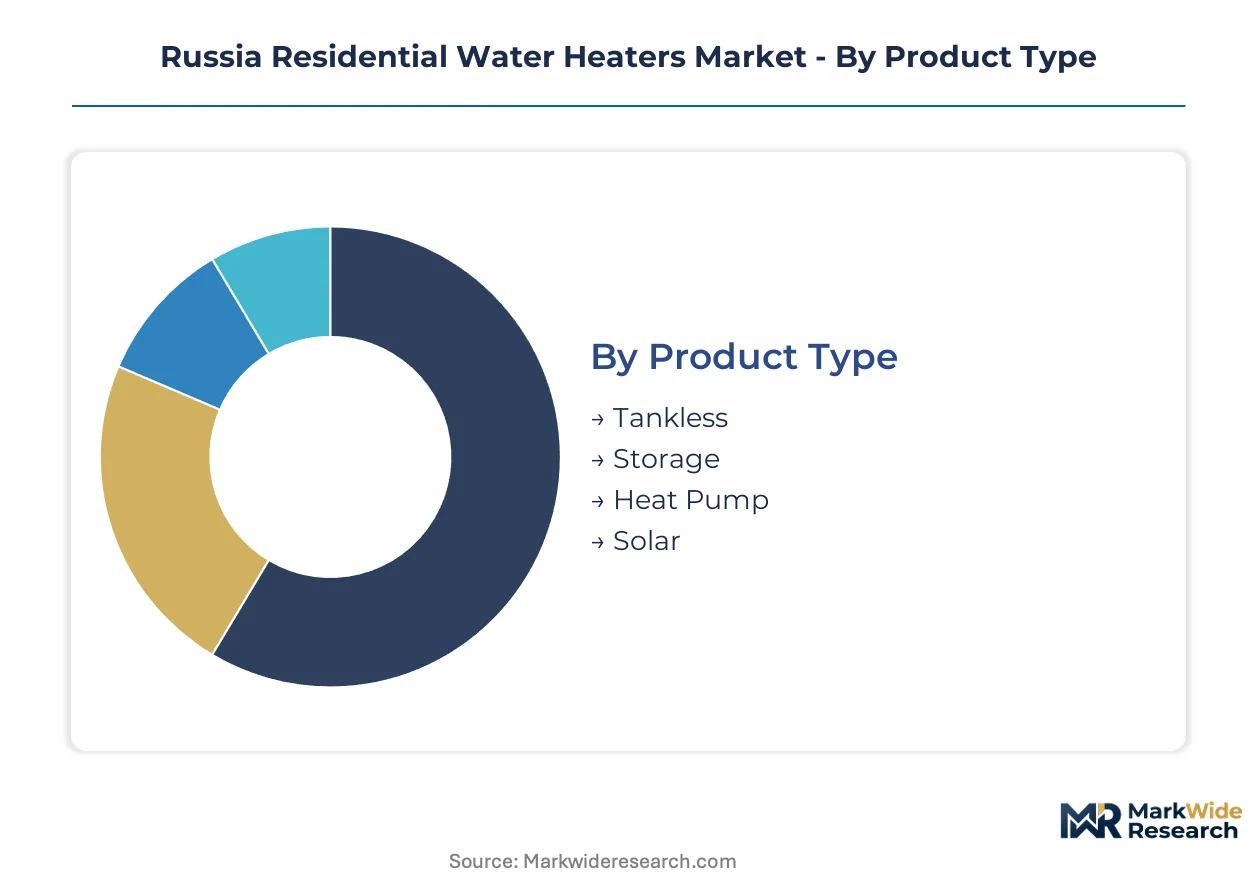
Russia's residential water heater market fragments across four distinct category axes. Each dimension carries specific regulatory and infrastructure implications that shape procurement patterns and manufacturer positioning strategies.
Product Type:
Thermal storage architecture and heat transfer mechanisms define the technical hierarchy across Russian households.
- Storage:Pressurized tank systems with 30-200 liter capacities dominate installed base across Soviet-era apartment stock. Moscow urban renewal programs sustain replacement demand as district heating infrastructure ages out.
- Tankless:On-demand gas and electric units eliminate standby thermal losses. Saint Petersburg premium renovations favor these for space-constrained bathrooms where footprint reduction overrides first-cost sensitivity.
- Heat Pump:Air-source systems with cold-climate compressors are gaining policy-sensitive buyers in regions with favorable electricity tariffs.
- Solar:Vacuum tube collectors serve dacha and rural applications where grid connectivity is intermittent and seasonal usage patterns align with solar availability.
Storage leads on scale; heat pump leads on momentum.
Energy Source:
Fuel availability and tariff structures create sharp geographic segmentation across Russia's federal districts.
- Electric:Resistance and heat pump systems leverage grid infrastructure in Central Federal District cities. Rosstandart energy labeling mandates are pushing manufacturers toward higher-efficiency heating elements.
- Gas:Natural gas-fired units anchor demand in pipeline-connected urban corridors. Baltgaz Group distribution networks concentrate supply across Far Eastern construction zones where district heating lags development.
- Propane:Bottled gas systems serve exurban and rural settlements beyond pipeline reach. Installation workforce shortages in peripheral regions constrain service quality.
- Biomass:Pellet and wood-fired boilers occupy niche positions in forested regions with established fuel supply chains.
Gas commands volume concentration; electric captures regulatory tailwinds.
Installation Type:
Spatial constraints and building codes determine mounting configurations across Russian residential stock.
- Indoor:Closet and utility room placement dominates legacy apartment layouts. GOST-R ventilation requirements mandate specific clearances that limit retrofit flexibility.
- Outdoor:Weatherized enclosures serve standalone homes and dacha communities. Cold-climate insulation ratings determine equipment survival through Siberian winter extremes.
- Under-sink:Point-of-use electric units address kitchen hot water demand in studio apartments. Compact dimensions trade capacity for spatial economy.
- Wall-mounted:Vertical orientation maximizes floor area in premium Moscow new-builds. Developer procurement is consolidating around these for multi-story residential towers.
Indoor retains installed base dominance; wall-mounted climbs fastest on new construction specifications.
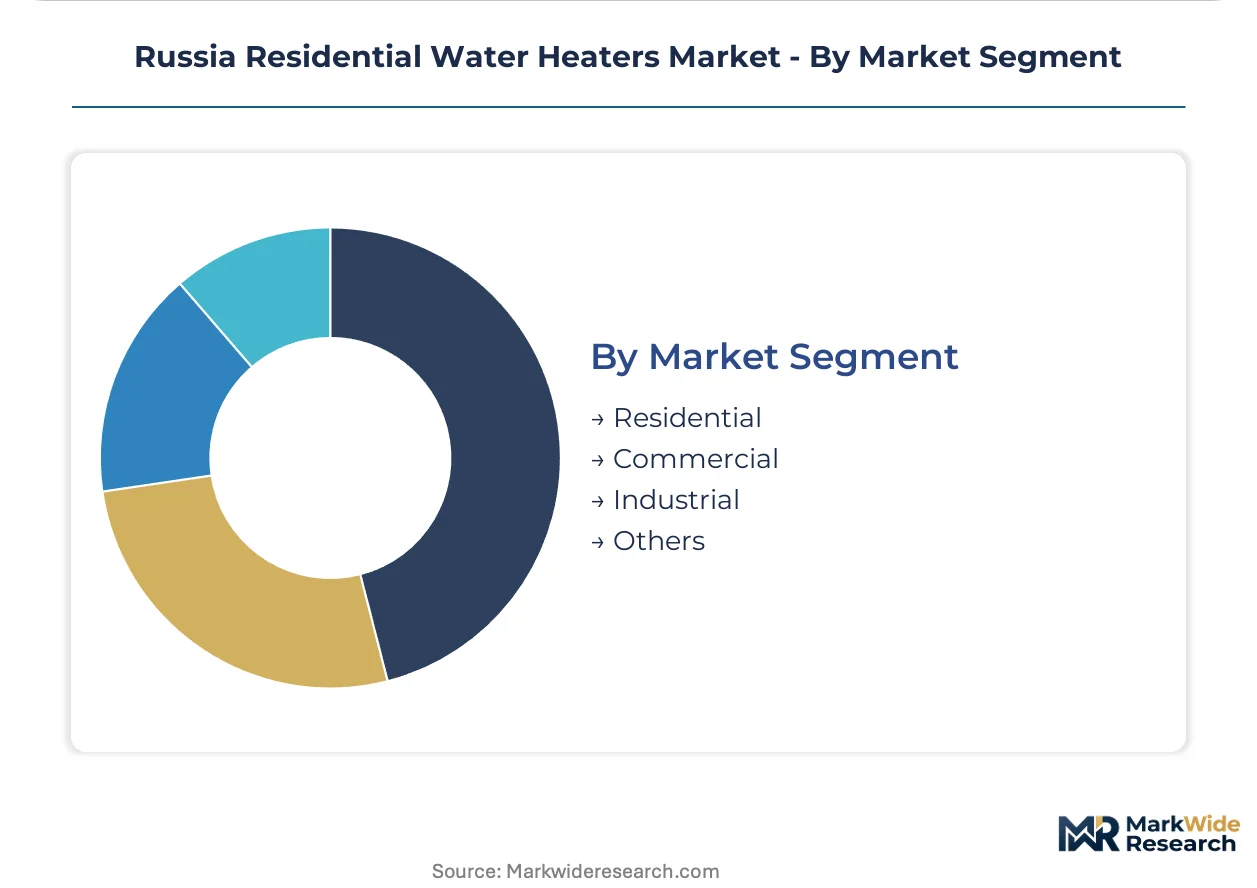
Market Segment:
End-use application scope defines regulatory exposure and procurement channel structure.
- Residential:Single-family homes and apartments constitute the core addressable market. State housing subsidies channel public procurement toward certified high-efficiency units.
- Commercial:Small hotels and retail spaces drive demand for higher-capacity multi-point systems. EEC technical regulations for low-voltage equipment filter supplier eligibility.
- Industrial:Worker housing and camp facilities in extractive industries create batch procurement opportunities. Remote location logistics favor robust simple designs over sophisticated controls.
- Others:Institutional and agricultural applications occupy peripheral market positions with specialized compliance requirements.
Residential anchors revenue concentration; commercial offers margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions where GOST-R compliance costs less than Eurasian Economic Commission alternatives, creating regulatory arbitrage across Russia's federal districts.
Central Federal District
Moscow's urban renewal programs and Saint Petersburg's premium renovation pipeline drive concentrated demand for wall-mounted electric and compact gas-fired systems. Rosstandart enforces GOST-R certification timelines that delay modified product launches. The Leningrad region hosts captive production bases serving domestic distribution channels.
Volga Federal District
Nizhny Novgorod and Kazan anchor procurement for mid-range storage units replacing Soviet-era district heating infrastructure. The Ministry of Construction channels state housing subsidies toward certified high-efficiency equipment. Samara's industrial corridor supports component fabrication for electronic control modules.
Siberian Federal District
Novosibirsk and Krasnoyarsk generate demand for cold-climate heat pump configurations with enhanced evaporator designs. Electricity tariff structures in these regions favor renewable-integrated building mandates. Omsk maintains legacy manufacturing capacity for conventional resistance heating elements.
Far Eastern Federal District
Vladivostok and Khabarovsk construction corridors outpace district heating expansion, creating distributed gas-fired water heating demand. Baltgaz Group controls distribution networks across this zone. The Eurasian Economic Commission's unified standards filter uncertified Central Asian imports from shelf space.
Southern Federal District
Rostov-on-Don and Krasnodar serve dacha communities and seasonal residences with solar vacuum tube collectors and propane systems. Grid intermittency in rural settlements favors off-grid thermal solutions. Stavropol's agricultural processing clusters create peripheral demand for worker housing installations.
Russia Residential Water Heaters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with domestic producers leveraging captive fabrication while European heritage brands anchor premium positioning. The vendor base clusters around three strategic archetypes: vertically integrated domestic champions with regional distribution control, European engineering-led premium specialists, and Asian-scale producers competing on cost. M&A activity concentrates on distribution network consolidation, while capacity expansion targets Far Eastern logistics corridors.
Within the domestic champion tier, Thermex exemplifies captive production strategy through its Leningrad region manufacturing base, while Baltgaz Group occupies the gas-fired specialization vector with Far Eastern distribution dominance. Ariston Thermo represents the European heritage archetype, anchoring premium storage segment positioning through engineering credibility. These three players illustrate how compliance with Rosstandart's GOST-R certification requirements and Eurasian Economic Commission technical regulations creates divergent competitive moats across price-performance tiers.
| Leading Market Players |
|---|
| Lemax |
| Thermex |
| Ariston Thermo |
| Vogel Flug Ltd |
| Haier |
| Rheem |
| Baltgaz Group |
| Isoterm |
| Bosch |
| Others |
Value Network & Pricing Analysis
Rosstandart's GOST-R energy labeling mandates gate qualified supply and premium-tier pricing access, as only certified manufacturers can participate in state-backed housing programs. Sanctions-driven component sourcing disruptions have compressed margins for storage-type units while rewarding compliant domestic producers with program eligibility.
Pricing Analysis
Distributor markups of 15-25% separate factory gate from retail shelf across the Central Federal District. Three-tier pricing structure across premium, standard, and economy levels reflects GOST-R certification grade and insulation performance ratings. Cost compression in the economy tier is intensifying because Asian-scale producers are routing through third-country intermediaries to bypass EEC technical regulation barriers. Developer procurement teams exhibit lowest price sensitivity, while individual replacement buyers in peripheral regions drive hard bargaining on installed cost.
Supply Chain Analysis
Electronic control module supply rests on Chinese and South Korean semiconductor fabricators after Western sourcing routes closed. Stainless steel tank formulations draw from European and Turkish specialty metal suppliers, while copper heating elements source from Kazakh and Uzbek mining operations. Single-source vulnerability concentrates in cold-climate compressor technology for heat pump variants. Distribution runs through Baltgaz Group's Far Eastern networks and Thermex's Leningrad-region captive channels, with builder-direct procurement bypassing traditional wholesale layers in Moscow new-build segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's residential water heater market functions as a stable compounder, with state-mandated urban renewal programs generating predictable replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Lock in GOST-R certification timelines by pre-positioning modified product lines ahead of Rosstandart amendment windows. Secure captive supply of corrosion-resistant tank linings through backward integration or long-term offtake agreements with Turkish metal suppliers, insulating against European input volatility. Deepen channel control in Far Eastern construction corridors before infrastructure investment peaks. For New Entrants and Emerging Players: Capture white-space in smart-enabled diagnostics convergence, where IoT integration commands premium positioning with minimal incumbent lock-in. Target under-sink point-of-use segments in Moscow studio apartment conversions, where space constraints override brand loyalty. Enter through turnkey mechanical package bundling with HVAC contractors, bypassing established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional distribution networks because builder procurement consolidation favors single-source providers with geographic density. Mid-cap specialists with GOST-R compliance infrastructure and Far Eastern logistics access represent optimal acquisition targets. Watch heat pump cold-climate performance breakthroughs as the inflection signal for technology substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GOST-R Certification Pre-Positioning | Rosstandart amendment windows compress revenue recognition for unprepared manufacturers. |
| Backward Integration into Tank Lining Supply | Turkish and domestic metal sourcing insulates against European supply volatility. |
| Smart Control Platform Development | IoT-enabled diagnostics allow premium positioning through predictive maintenance features. |
| Far Eastern Distribution Network Expansion | Vladivostok and Khabarovsk construction corridors outpace district heating infrastructure. |
| Turnkey Mechanical Package Bundling | Moscow developers consolidate procurement around single-source HVAC-water heating providers. |
Research Methodology
Coverage spans Russia's Central, Volga, Siberian, Far Eastern and Southern Federal Districts, with primary inputs from each. The research combines interviews with water heater manufacturer product managers, Rosstandart certification specialists, Moscow developer procurement directors, and Far Eastern HVAC contractor networks with secondary validation through EEC technical regulation filings, Rosstandart energy labeling databases, and Russian Ministry of Construction housing program disclosures. Bottom-up unit shipment estimates triangulate against top-down addressable housing stock calculations.
Rate-of-change decomposition separates replacement demand from new construction absorption across the projection horizon. The analytical framework models product type, energy source, installation configuration, and market segment dimensions alongside regional electricity tariff structures and gas pipeline connectivity. CAGRs derive from housing completion forecasts, urban renewal program budgets, and technology substitution elasticity estimates. Cold-climate heat pump performance maturation and smart control adoption curves inform segment-specific growth differentials.
Sanctions regime evolution, Rosstandart regulatory amendment timing, and district heating infrastructure reliability are the dominant revision risks. Forecasts reflect assumptions about component sourcing route stability and state housing subsidy continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Handheld Fans Market
Household Items
Mosquito Trap Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Innerspring Mattresses Market
Household Items
Insulated Drinkware Market
Household Items
Shoe Shine Machine Market
Household Items
Barbeque Grill Market
Household Items
Microwave Safe Utensils Market
Household Items
Gas Hobs Market
Household Items
Electric Tealight Candles Market
Household Items
Pocket Tissues Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Global Nap Pod Market
Household Items
Sanitary Metal Ware Market
Household Items
Dishwashing Products Market
Household Items
Thermos Bottle Market