
 Middle East Handheld Vacuum Cleaner Market | 2026-2036
Middle East Handheld Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Handheld Vacuum Cleaner Market Insights
SASO energy-efficiency certification is redrawing competitive boundaries for appliance suppliers entering the Middle East. Dyson leverages its cyclone technology leadership to command premium positioning across UAE electronics retailers. Philips anchors its regional presence through established service networks and localized warranty infrastructure. Xiaomi competes aggressively on lithium-ion battery economics, undercutting legacy brands in Saudi Arabian e-commerce channels.
A handheld vacuum cleaner is a portable suction device powered by electric motors, typically operating at 12-22 volts in cordless configurations with lithium-ion cells, designed for localized debris removal in constrained spaces. Cordless variants now dominate Middle East retail shelves as lithium-ion energy density improvements extend runtime beyond twenty minutes per charge. The residential end-user segment captures the deepest margin pools due to replacement-cycle frequency and brand loyalty, while wet-and-dry product types gain traction among commercial cleaning contractors serving Dubai's hospitality sector. HEPA filtration features increasingly segment premium from standard tiers as Gulf consumers prioritize indoor air quality amid regional dust conditions.
SASO mandates govern energy consumption labeling and electrical safety compliance for all vacuum cleaners sold in Saudi Arabia, while the UAE's Emirates Authority for Standardization and Metrology enforces parallel efficiency benchmarks that shape import eligibility. The Gulf Standardization Organization coordinates cross-border technical harmonization, reducing manufacturer adaptation costs across Bahrain, Kuwait, Oman, Qatar, and the UAE. Stakeholders must monitor evolving battery disposal regulations as Gulf states advance extended producer responsibility frameworks for lithium-ion waste streams.
Market Dynamics
SASO energy-efficiency labeling mandates are compressing product lifecycles and forcing rapid redesign cycles across Saudi Arabian supply chains, while lithium-ion battery density improvements extend cordless runtime thresholds beyond legacy corded performance benchmarks.
Growth Catalysts
- Cordless lithium-ion platforms:Saudi residential buyers prioritize 20-plus minute runtime units for multi-room cleaning without outlet dependency. Retail shelf space in Riyadh electronics corridors tilts toward battery-powered configurations.
- SASO energy-efficiency mandates:The Saudi regulator's tightening consumption thresholds accelerate replacement demand for obsolete high-wattage models. Compliance certification becomes a gating factor for import eligibility.
- Dubai hospitality sector expansion:Commercial cleaning contractors serving hotels and serviced apartments specify wet-and-dry handheld units for rapid turnaround protocols. Procurement volumes concentrate in the emirate's facility management clusters.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs fluctuate with cobalt and nickel spot markets, compressing assembler margins on economy-tier products. Gulf-based distributors absorb currency translation effects on imported cells.
- Extended producer responsibility frameworks:Emerging Gulf state mandates for lithium-ion waste stream collection impose reverse-logistics infrastructure investments. Compliance timelines remain undefined across Bahrain, Kuwait, and Oman.
- HEPA filtration technical limitations:Fine particulate capture efficiency degrades rapidly in high-dust Gulf environments, accelerating filter replacement frequency and total cost of ownership.
Strategic Opportunities
- Qatar and Kuwait underpenetration:Per-household handheld vacuum ownership trails Saudi and UAE benchmarks by significant margins. Localized distribution partnerships unlock first-mover positioning in Doha and Kuwait City retail channels.
- Smart home ecosystem convergence:Integration of battery management systems with IoT-enabled charging docks enables predictive maintenance alerts. Early adopters in UAE smart residential towers demonstrate willingness to pay connectivity premiums.
- Emirates Authority for Standardization and Metrology efficiency benchmarks:UAE parallel certification requirements create dual-compliance efficiencies for manufacturers already adapting to SASO thresholds. Harmonized testing protocols reduce adaptation costs.
Industry Challenges
- Certification timeline compression:SASO's evolving technical specifications require repeated third-party testing cycles. Product launch windows slip as documentation requirements expand.
- After-sales service network density:Sparse authorized repair infrastructure across Oman and Bahrain extends warranty fulfillment timelines. Brand equity erodes when battery replacement requires cross-border shipping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Handheld Vacuum Cleaner Market |
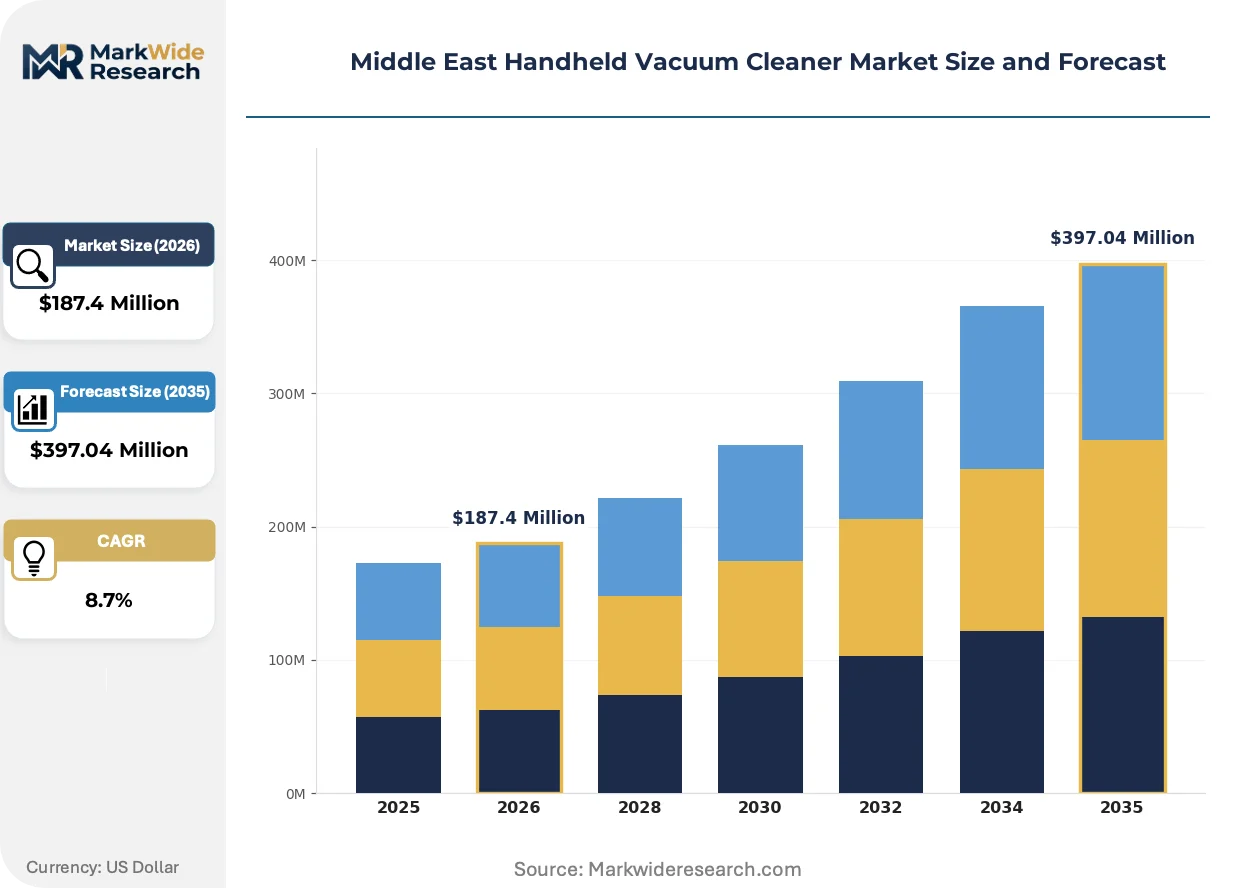
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Wet & Dry, Multi-surface Battery Type: Lithium-ion, Nickel-cadmium, NiMH, Lead-acid End User: Residential, Commercial, Automotive, Industrial Feature: HEPA Filter, Bagless, Lightweight, Ergonomic Design |
| Companies Covered | Dyson, Philips, Black & Decker, Xiaomi, Deerma, Karcher, LG, Panasonic, Geepas, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Handheld Vacuum Cleaner Market Trends and Innovations
Cyclone separation architectures and solid-state battery prototypes are fragmenting established performance hierarchies, while regulatory pressure on energy consumption and indoor air quality rewrites product positioning rules across Gulf retail channels.
Cyclone multi-stage dust separation is fragmenting traditional bagged and bagless suction architectures in premium Saudi Arabian retail. Dyson's dual-cyclone patents expire through 2027, enabling local assemblers to replicate core airflow geometries at reduced royalty burdens. Residential buyers in Jeddah and Riyadh now expect visible dustbin transparency and tool-free emptying as baseline features.
SASO's 2024-2025 energy-efficiency labeling revisions mandate standby power consumption below one watt and active-mode thresholds tied to suction-wattage ratios. The Saudi regulator's testing protocols now incorporate simulated carpet and hard-floor duty cycles. Importers holding legacy certifications face forced model refreshes or market withdrawal.
Direct-to-consumer e-commerce channels are displacing traditional electronics retailer intermediaries for replacement-unit purchases. Saudi Arabian consumers research HEPA filtration specifications and battery cycle ratings through platform reviews before checkout. Amazon.sa and Noon.com capture disproportionate volume in cordless category searches, compressing brick-and-mortar foot traffic in Riyadh's Olaya district.
Middle East Handheld Vacuum Cleaner Market Segmentation
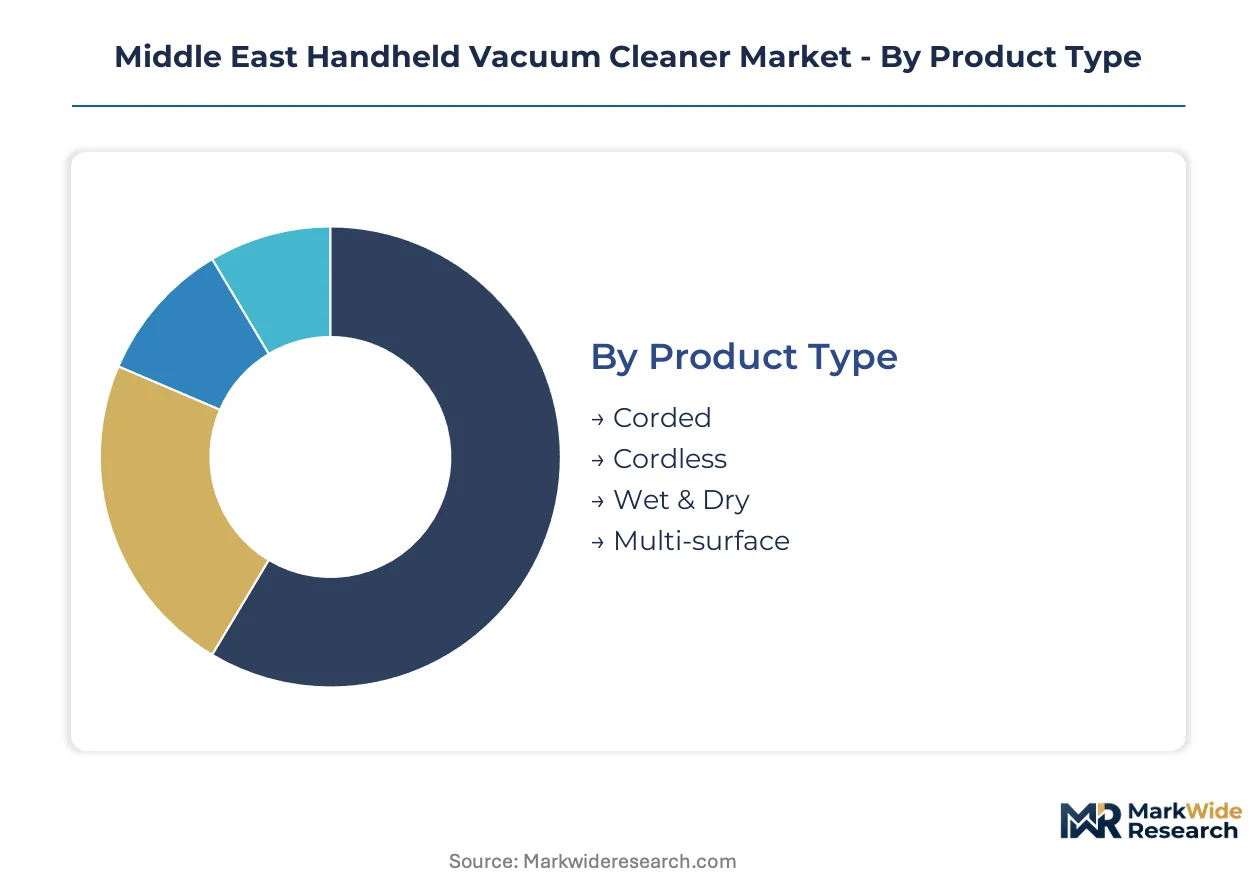
Handheld vacuum cleaner purchasing decisions across Saudi Arabia and the UAE fragment across power source preferences, battery chemistry trade-offs, and filtration requirements. SASO energy-efficiency mandates and lithium-ion cost curves reshape which segments capture margin versus volume.
Product Type:
SASO certification thresholds differentiate compliant from non-compliant configurations, with cordless units facing stricter active-mode efficiency ratios than corded alternatives.
- Cordless:Lithium-ion platforms operating at 18-22 volts now exceed twenty-minute runtime thresholds. Residential buyers in Riyadh and Jeddah prioritize outlet-independent operation for multi-room cleaning routines.
- Wet & Dry:Dual-chamber suction architectures handle liquid spills and solid debris without filter saturation. Dubai hospitality contractors specify these units for rapid hotel room turnaround protocols.
- Corded:Continuous power delivery suits fixed-location cleaning stations in Saudi commercial facilities. Tethered operation avoids battery replacement cost concerns among price-sensitive institutional buyers.
- Multi-surface:Adjustable suction heads transition between carpet pile and hard flooring. UAE electronics retailers merchandise these as versatile middle-tier options.
Established volume favors corded units in commercial installations; emerging adoption favors cordless configurations in Saudi residential channels.
Battery Type:
Cell chemistry determines weight, cycle life, and import cost structure for Gulf distributors managing currency exposure on East Asian battery pack sourcing.
- Lithium-ion:Energy density above 250 watt-hours per kilogram enables compact handheld form factors. Nickel and cobalt spot price volatility compress assembler margins on economy-tier cordless models.
- Nickel-cadmium:Legacy chemistry persists in price-sensitive commercial fleet replacements across Oman and Bahrain. Memory effect degradation accelerates replacement frequency versus lithium alternatives.
- NiMH:Intermediate energy density suits mid-range cordless units targeting budget-conscious Saudi households. Cell suppliers face declining economies of scale as lithium-ion costs descend.
- Lead-acid:Heavy, low-cycle chemistry retains niche presence in industrial wet-and-dry units. Gulf-based assemblers source these domestically to avoid import documentation complexity.
Procurement concentrates on lithium-ion for new cordless designs; lead-acid and nickel-cadmium capture replacement demand in legacy installed bases.
End User:
Application context dictates performance specifications, warranty expectations, and service network requirements across the Gulf Cooperation Council corridor.
- Residential:Replacement-cycle frequency and brand loyalty generate the deepest margin pools. Saudi consumers research HEPA specifications and battery cycle ratings through Amazon.sa and Noon.com before purchase.
- Commercial:Facility management contractors in Dubai's hospitality sector procure wet-and-dry handhelds under annual maintenance agreements. Procurement volumes cluster in emirate-level facility management clusters.
- Automotive:Compact form factors access vehicle interiors and trunk compartments. Detailing shops in Abu Dhabi and Riyadh specify crevice tools and brush attachments for upholstery cleaning.
- Industrial:Dust extraction requirements in manufacturing environments drive sealed-motor specifications. Sparse authorized repair infrastructure across Oman extends warranty fulfillment timelines for these heavy-duty units.
Margin accretion concentrates in residential replacement cycles; volume expansion favors commercial procurement tied to Dubai hospitality construction pipelines.
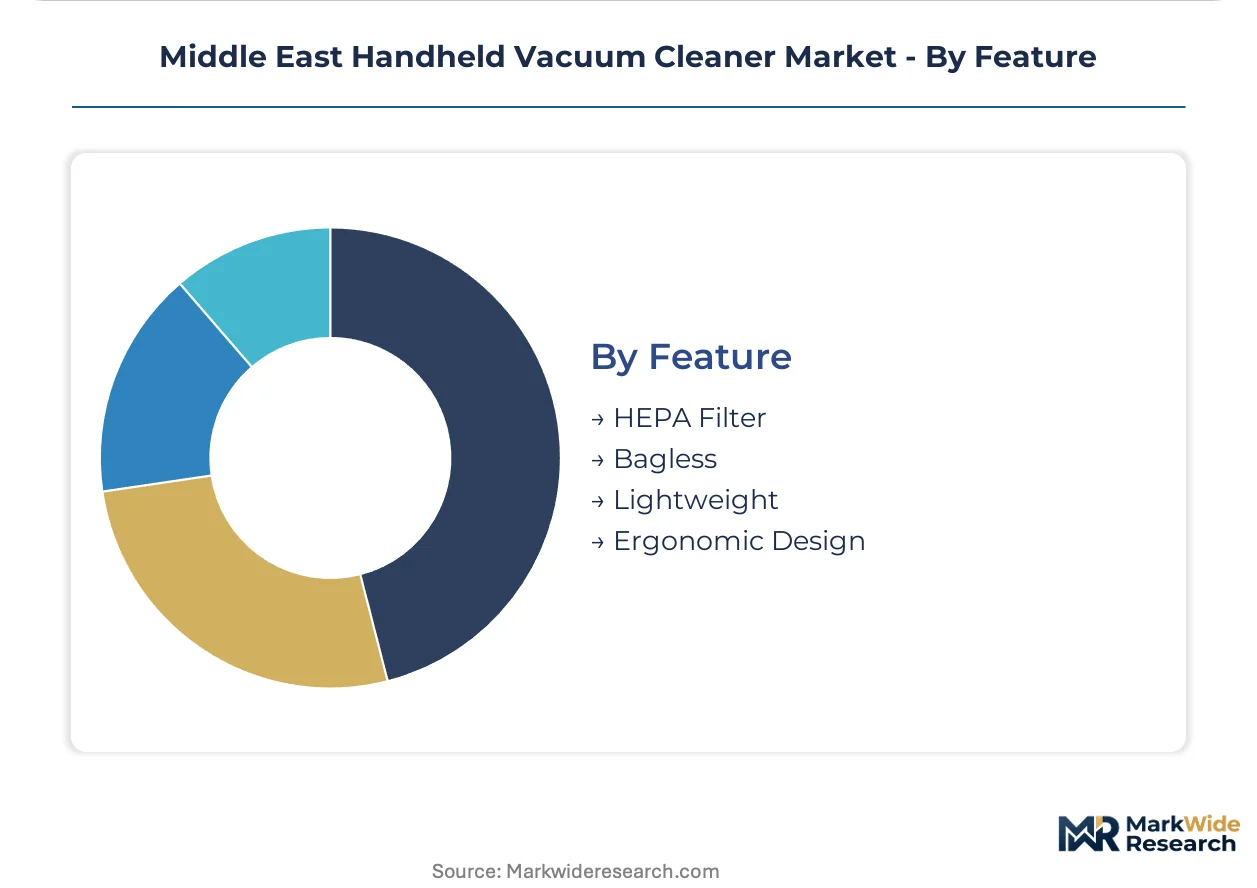
Feature:
Filtration and ergonomics segment premium from standard tiers as Gulf consumers prioritize indoor air quality amid regional dust conditions.
- HEPA Filter:Fine particulate capture efficiency degrades rapidly in high-dust Saudi and UAE environments. Filter replacement frequency elevates total cost of ownership for residential buyers.
- Bagless:Cyclone separation architectures with visible dustbin transparency satisfy Riyadh consumer preferences for tool-free emptying. Dustbin hygiene concerns persist among allergy-sensitive households.
- Lightweight:Sub-1.5 kilogram configurations reduce wrist fatigue during extended cleaning sessions. Elderly buyers and multi-story villa residents in Jeddah prioritize maneuverability.
- Ergonomic Design:Rotating wrist joints and trigger placement accommodate varied grip anthropometrics. UAE retailers report reduced return rates for units with adjustable handle angles.
HEPA and bagless features command pricing premiums; lightweight and ergonomic specifications expand addressable market among demographic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO energy-efficiency labeling mandates and Emirates Authority for Standardization and Metrology benchmarks are redrawing import eligibility across Gulf Cooperation Council corridors, concentrating procurement volume in Riyadh and Dubai retail channels while accelerating compliance-driven replacement cycles.
Saudi Arabia
Residential buyers in Jeddah and Riyadh prioritize cordless lithium-ion units with twenty-plus minute runtime for multi-room villa cleaning. SASO's 2024-2025 standby power consumption thresholds below one watt force model refreshes for legacy importers. Electronics corridors in Riyadh's Olaya district tilt retail shelf space toward battery-powered configurations.
United Arab Emirates
Dubai hospitality contractors procure wet-and-dry handhelds under annual facility management agreements for rapid hotel room turnaround. The Emirates Authority for Standardization and Metrology enforces parallel efficiency benchmarks that shape dual-compliance efficiencies for SASO-adapted manufacturers. Procurement volumes cluster in Dubai's emirate-level facility management clusters.
Qatar
Per-household handheld vacuum ownership trails Saudi benchmarks significantly, creating first-mover positioning opportunities in Doha retail channels. The Qatar General Organization for Standardization coordinates technical harmonization with Gulf Standardization Organization protocols. Localized distribution partnerships unlock penetration in emerging residential developments around Lusail.
Kuwait
Budget-conscious households in Kuwait City respond to mid-range NiMH cordless configurations as lithium-ion costs descend. The Public Authority for Industry administers import compliance testing that mirrors SASO technical specifications. Electronics retailers in Salmiya district report rising cordless category searches through direct-to-consumer platforms.
Oman
Sparse authorized repair infrastructure extends warranty fulfillment timelines for commercial fleet replacements in Muscat. The Ministry of Commerce, Industry and Investment Promotion advances extended producer responsibility frameworks for lithium-ion waste streams. Industrial buyers in Sohar port zone specify sealed-motor configurations for manufacturing dust extraction.
Middle East Handheld Vacuum Cleaner Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and battery technology dimensions, producing a tiered structure where cyclone patent holders, established service network operators, and lithium-ion cost optimizers occupy distinct positioning bands. Strategic archetypes include premium technology licensors, warranty infrastructure anchors, and e-commerce volume attackers. Competitive moves concentrate on geographic licensing arrangements and backward integration into battery pack assembly.
Within the premium technology tier, Dyson and Philips exemplify divergent approaches to regional positioning. Dyson occupies a cyclone-separation archetype that commands retail shelf premiums across UAE electronics channels. Philips anchors warranty infrastructure density through localized service networks. Xiaomi sits within the e-commerce volume tier, representing lithium-ion battery economics that undercut legacy brand positioning in Saudi Arabian online channels.
| Leading Market Players |
|---|
| Dyson |
| Philips |
| Black & Decker |
| Xiaomi |
| Deerma |
| Karcher |
| LG |
| Panasonic |
| Geepas |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lithium-ion battery pack lead times from East Asian cell suppliers compress Gulf distributors' pricing flexibility and force inventory positioning ahead of SASO certification windows. This lead-time band concentrates procurement power with established importers holding bonded warehouse capacity in Jebel Ali and Dammam, while smaller distributors absorb currency translation effects on spot cell purchases.
Pricing Analysis
Certification level creates the primary spread between import-eligible and gray-market handheld vacuum cleaners across Saudi Arabia and the UAE. Three-tier pricing structure across premium cyclone-technology, standard HEPA-compliant, and economy-tier nickel-cadmium configurations reflects SASO energy-efficiency grade differentiation. Pricing pressure stems from Xiaomi's lithium-ion battery economics undercutting legacy brand positioning in Saudi e-commerce channels. Commercial facility management contractors in Dubai exhibit lowest price sensitivity due to annual maintenance agreement structures, while budget-conscious Kuwaiti households drive volume in mid-range NiMH configurations.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Dubai-based distributors serving hospitality sector procurement clusters, while Saudi importers maintain strategic stockpiles ahead of SASO specification revision deadlines. Manufacturing concentration in China, South Korea, and Vietnam feeds Gulf import channels through Jebel Ali transhipment hubs. Raw material dependencies on cobalt, nickel, and rare-earth magnet assemblies expose assemblers to commodity price volatility. Single-source vulnerability concentrates in lithium-ion cell supply from tier-one East Asian producers. Distribution runs through electronics retailer networks in Riyadh's Olaya district and direct-to-consumer platforms including Amazon.sa and Noon.com.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Saudi and UAE e-commerce platforms consolidating cordless category search traffic, fragmenting traditional electronics retailer intermediaries. This platform consolidation compresses distributor margins while elevating brand marketing spend efficiency for direct-to-consumer entrants.
For Market Incumbents: Fortify warranty infrastructure density across Oman and Bahrain to close service network gaps that erode brand equity when battery replacement requires cross-border shipping. Deepen backward integration into lithium-ion pack assembly to offset cell cost volatility and secure SASO certification timeline adherence. The priority lever rests on captive supply of battery management systems. For New Entrants and Emerging Players: Lead with Qatar and Kuwait underpenetration gaps where per-household handheld vacuum ownership trails Saudi benchmarks significantly. Target Doha retail channels in emerging Lusail residential developments through localized distribution partnerships. Deploy direct-to-consumer platform optimization as the primary go-to-market angle, capturing cordless category search volume before brick-and-mortar shelf space allocation solidifies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance parent companies with neglected handheld vacuum product lines lacking SASO certification infrastructure. Long-term viability across the five-to-ten-year window hinges on lithium-ion battery chemistry transition and Gulf state extended producer responsibility compliance capability. The acquisition archetype centers on mid-tier assemblers with established UAE electronics retailer relationships. Watch for lithium-ion waste stream regulation finalization across Bahrain, Kuwait, and Oman as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Pre-Positioning | Early compliance investment secures import eligibility ahead of 2024-2025 standby power threshold enforcement. |
| Lithium-Ion Battery Backward Integration | In-house pack assembly reduces cobalt spot price exposure and compresses procurement lead times. |
| Direct-to-Consumer Platform Optimization | Amazon.sa and Noon.com search dominance displaces traditional retailer intermediaries for replacement purchases. |
| Warranty Infrastructure Expansion | Authorized service density in Oman and Bahrain closes competitive gaps against Philips' established network. |
| Wet-and-Dry Product Line Extension | Dubai hospitality contractor procurement clusters specify dual-chamber architectures for rapid room turnaround. |
Research Methodology
Cross-validation between primary interviews with appliance category managers, SASO compliance officers, lithium-ion cell procurement leads, and electronics retailer buyers anchors the qualitative findings against secondary validation. Secondary sources include customs import records, SASO technical specification filings, Gulf Standardization Organization harmonization protocols, and bonded warehouse throughput disclosures from Jebel Ali and Dammam free zones. Bottom-up unit shipment estimates from distributor channel checks triangulate against top-down market size calculations derived from retail shelf space allocation and e-commerce platform search volume indices.
Sensitivity analysis around lithium-ion cell cost curves, SASO certification timeline slippage, and extended producer responsibility implementation schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include power source configuration, battery chemistry tier, end-user application, and filtration specification grade. CAGRs derive from replacement cycle frequency analysis, per-household penetration trajectory modeling, and commercial procurement elasticity to Dubai hospitality construction pipelines. Industry-specific forecast inputs incorporate HEPA filter replacement frequency in high-dust Gulf environments and smart home ecosystem integration willingness-to-pay premiums in UAE residential towers.
The analysis sits within stated boundaries; outcomes outside SASO enforcement consistency, lithium-ion energy density improvement continuity, or Gulf state regulatory harmonization would require recalibration. Forecasts reflect documented assumptions regarding certification timeline adherence and cell chemistry cost descent. Revision becomes warranted when extended producer responsibility mandates cross implementation thresholds or when solid-state battery prototypes achieve commercial viability ahead of projected adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Thermos Bottle Market
Household Items
Cat Hair Remover Market
Household Items
Remote Control Holder Market
Household Items
Washing Machine Cleaner Market
Household Items
Consumerware Market
Household Items
Cups and Pots Market
Household Items
Ceramic Travel Mug Market
Household Items
Air Purifier Market
Household Items
Electric Air Freshener Market
Household Items
Global Rimless Toilets Market
Household Items
Ironing Boards Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Global Buddhist Supplies Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Neck Pillows Market
Household Items
Basin, Bowl, and Cup Market