
 Dishwashing Products Market | 2026-2036
Dishwashing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dishwashing Products Market Analysis
Premium concentrated formulations is unwinding legacy low-dose habits across developed and emerging markets alike. Henkel AG and Co. KGaA leverages its European manufacturing base to sustain supply continuity for enzymatic tablet lines. The Procter and Gamble Company anchors North American shelf presence through club-channel exclusives and refill innovations. Kao Corporation dominates Asia-Pacific markets with phosphate-free chemistry tailored to regional water hardness profiles.
Dishwashing products encompass surfactant-based cleaning agents formulated with alkalinity builders, enzymes, and rinse aids to remove food soils from cookware and tableware, typically operating effectively at temperatures between 45°C and 65°C in both manual and machine-wash applications. Their primary commercial purpose spans sanitation compliance in foodservice operations and labor reduction in residential settings. Liquid detergents occupy the largest volume share due to versatility across hand-wash and pre-soak routines, while dishwasher tablets capture expanding machine-penetration demand in middle-income households. Eco-friendly formulations represent the fastest-growing margin pool as certification requirements from Ecolabel and EPA Safer Choice reshape procurement criteria across European and North American retail channels.
The EPA Safer Choice program and EU Ecolabel framework restrict alkylphenol ethoxylates and phosphates in surfactant blends, compelling reformulation investments that raise barrier costs for regional challengers. India's BIS standards for household detergents are tightening heavy-metal limits, accelerating compliance-driven consolidation among unorganized manufacturers. Stakeholders must monitor how divergent biodegradability timelines between jurisdictions reshape export eligibility and localized production economics.
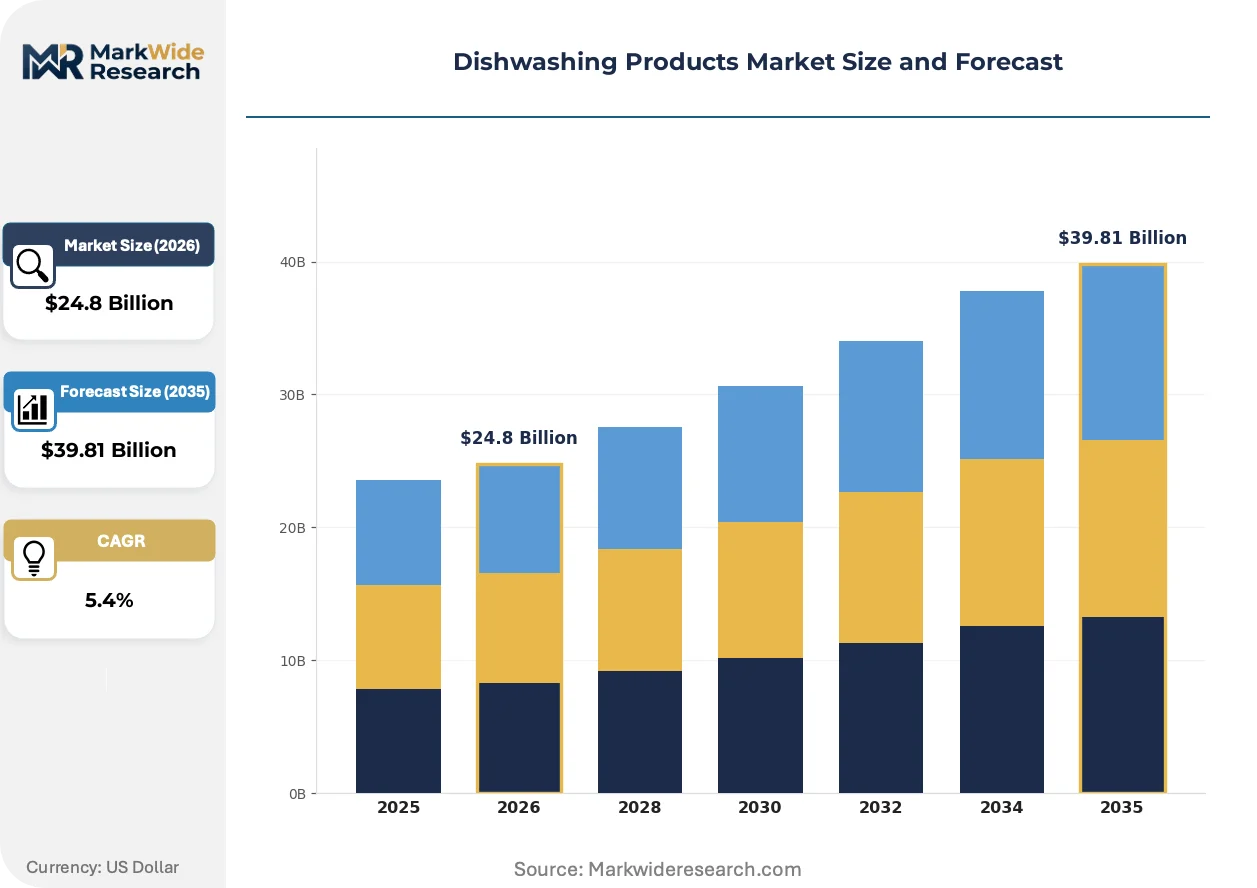
Market Dynamics
Concentrated enzymatic formulations are compressing legacy powder volumes while forcing capital retooling across contract manufacturing networks serving retail and foodservice channels.
Growth Catalysts
- EU Ecolabel certification thresholds:Tightening surfactant biodegradability standards in Europe are disqualifying legacy alkylphenol ethoxylates and redirecting procurement toward enzymatic tablet suppliers with compliant chemistry pipelines.
- Quick-service restaurant chain expansion:Commercial kitchen procurement teams across franchised networks are standardizing on concentrated formulations to reduce storage footprint and simplify inventory management at high-turnover locations.
- India urban household format migration:Metropolitan consumers are abandoning bar soaps for liquid and tablet formats, creating volume pull for packaging lines optimized for unit-dose delivery systems.
Market Restraints
- Palm kernel oil and lauric acid feedstock volatility:Surfactant input costs fluctuate with Malaysian and Indonesian plantation output cycles, compressing margin predictability for mid-tier private-label manufacturers.
- Specialty enzyme supplier concentration:Novozymes and DuPont Nutrition & Biosciences control critical protease and amylase strains for low-temperature dishwashing, creating single-source vulnerability for reformulating brands.
- Phosphate ban grandfathering timelines:Divergent phase-out schedules between US states and EU member countries fragment production batch economics for multinational suppliers.
Strategic Opportunities
- India tier-2 and tier-3 city penetration:Dishwasher machine ownership remains below 5% in secondary urban centers, positioning concentrated liquid formats for hand-wash pre-soak routines ahead of appliance adoption curves.
- EPA Safer Choice direct-to-institutional procurement:Federal and state agency cleaning contracts now mandate certification, opening bypass channels around retail slotting fee structures for qualified suppliers.
- Refill station network integration:Bulk dispensing systems in European retail cooperatives and US club channels are collapsing packaging cost ratios for household penetration of premium concentrated chemistry.
Industry Challenges
- Enzyme stability in alkaline builder matrices:Maintaining protease activity above pH 10 across 18-month shelf life requires encapsulation IP that remains concentrated among specialized chemical houses.
- Legacy powder production asset stranding:Spray-drying towers configured for phosphate-built formulations face utilization collapse as tablet and liquid formats capture volume share, forcing write-down decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dishwashing Products Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Detergents, Powder Detergents, Dishwasher Tablets, Rinse Aids Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Restaurants, Cafeterias, Hotels Formulation: Eco-friendly, Heavy-duty, Concentrated, Antibacterial |
| Companies Covered | Henkel AG and Co. KGaA, Colgate-Palmolive Company, The Procter and Gamble Company, Kao Corporation, The Clorox Company, Unilever Plc, Church and Dwight Co. Inc., Godrej Consumer Products Limited, Reckitt Benckiser Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dishwashing Products Market Emerging Trajectories
Formulation chemistry, regulatory certification frameworks, and procurement channel structures are simultaneously restructuring competitive position in dishwashing products.
Enzymatic cold-water tablets are bifurcating performance expectations between energy-conscious European households and high-temperature commercial operations. German and Dutch retail buyers are prioritizing 45°C effective formulations for residential machines, while US foodservice distributors maintain 65°C specifications for sanitation compliance. This temperature-performance split is forcing parallel SKU architectures that strain manufacturing flexibility.
REACH Annex XVII restrictions on microplastic-containing glitter and abrasive additives are eliminating visual differentiation tactics in European manual dish liquids. Formulators are pivoting to plant-derived viscosity modifiers and natural fragrance encapsulation to maintain shelf appeal without non-biodegradable particulates. The reformulation burden falls heaviest on value-tier brands dependent on cost-engineered sensory cues.
Direct institutional contracting is collapsing traditional distributor markups in North American healthcare and education sectors. Hospital procurement consortiums and university purchasing cooperatives are negotiating multi-year supply agreements with EPA Safer Choice-certified manufacturers, bypassing JanSan wholesalers. This channel compression concentrates volume with formulation specialists capable of documentation compliance rather than broadline distributors.
Dishwashing Products Market Segmentation
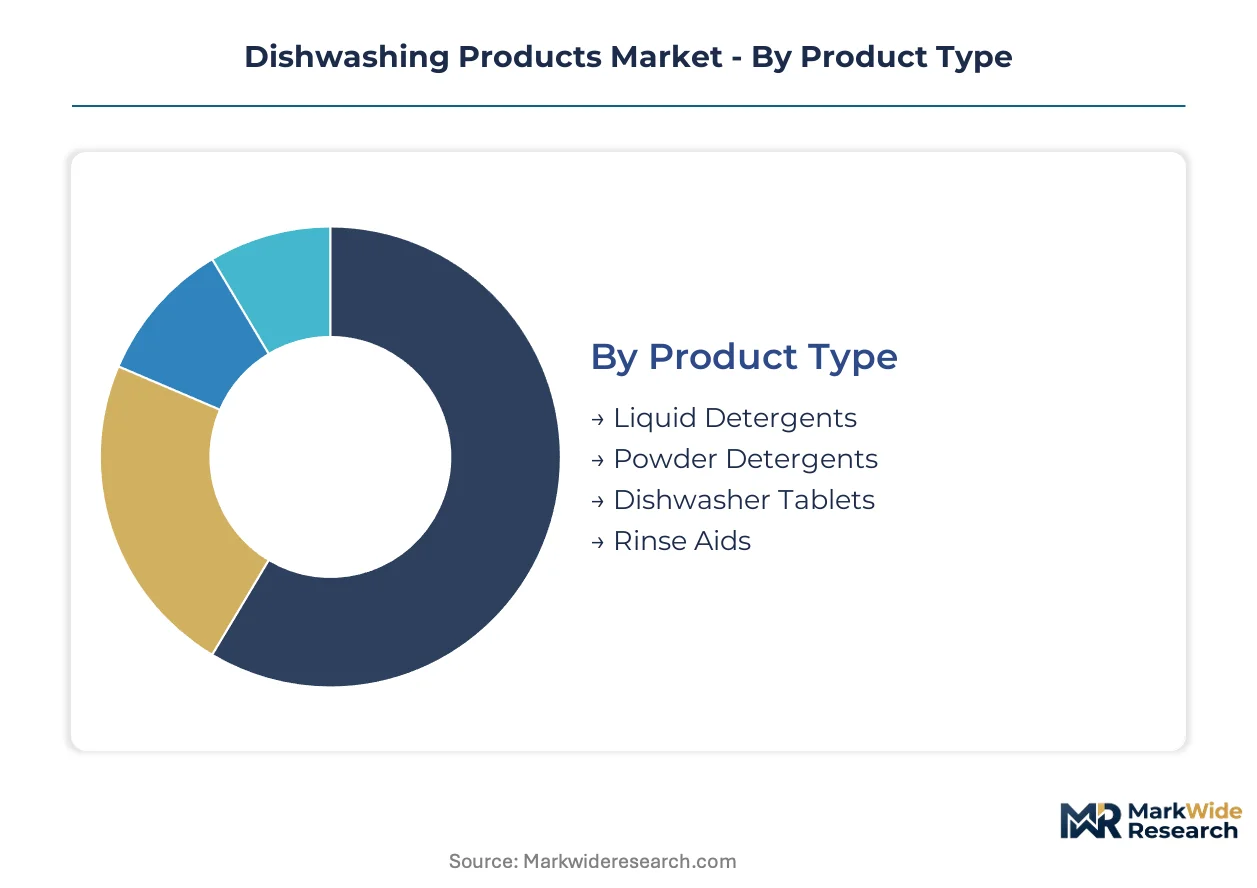
Dishwashing product margins concentrate in concentrated enzymatic formulations and certified eco-friendly chemistry, while legacy powders face utilization collapse. Segmentation strategy must track where procurement standards tighten and where appliance penetration reshapes format preferences.
Product Type:
Liquid detergents and dishwasher tablets command the steepest margin premiums, while powder volumes compress under format migration pressure.
- Liquid Detergents:Surfactant-based formulations with alkalinity builders enable hand-wash versatility and pre-soak routines across residential and light commercial settings. Demand concentrates in India as urban households abandon bar soaps for pump-dispensed formats in metropolitan kitchens.
- Dishwasher Tablets:Unit-dose enzymatic tablets with encapsulated protease and amylase strains deliver low-temperature performance in residential machines. European retail buyers prioritize 45°C effective formulations, creating SKU bifurcation against commercial 65°C specifications.
- Powder Detergents:Spray-dried phosphate-built formulations face asset stranding as tablet and liquid formats capture volume share.
- Rinse Aids:Surfactant blends reduce water surface tension for spot-free drying in machine-wash applications.
Liquid detergents hold installed capacity. Dishwasher tablets are rotating up the share rankings.
Distribution Channel:
Channel economics split between retail slotting fee structures and bypass opportunities through direct institutional contracting.
- Supermarkets:Brick-and-mortar retail chains dominate household penetration with shelf-space negotiations favoring club-channel exclusives and refill innovations. North American procurement teams leverage these outlets for premium concentrated chemistry access.
- Online Retail:E-commerce platforms enable subscription-based replenishment and bulk purchasing for concentrated formulations. Indian metropolitan consumers drive platform growth for liquid and tablet format discovery.
- Convenience Stores:Small-format retail captures emergency replenishment and travel-size demand.
- Wholesale:Foodservice distributors maintain 65°C sanitation specifications for quick-service restaurant chain procurement.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
End User:
Procurement sophistication diverges sharply between residential price sensitivity and institutional compliance documentation requirements.
- Households:Residential consumers prioritize unit-dose convenience and cold-water energy savings. German and Dutch buyers specifically demand 45°C effective enzymatic tablets for residential machine efficiency.
- Restaurants:Quick-service franchise networks standardize on concentrated formulations to reduce storage footprint at high-turnover locations. Commercial procurement teams negotiate multi-year supply agreements with EPA Safer Choice-certified suppliers.
- Cafeterias:Institutional foodservice operations in education and healthcare sectors mandate certification compliance for federal and state agency cleaning contracts.
- Hotels:Hospitality procurement prioritizes bulk dispensing systems and sanitation compliance for guest-facing tableware presentation.
Households hold installed capacity. Restaurants are rotating up the share rankings.
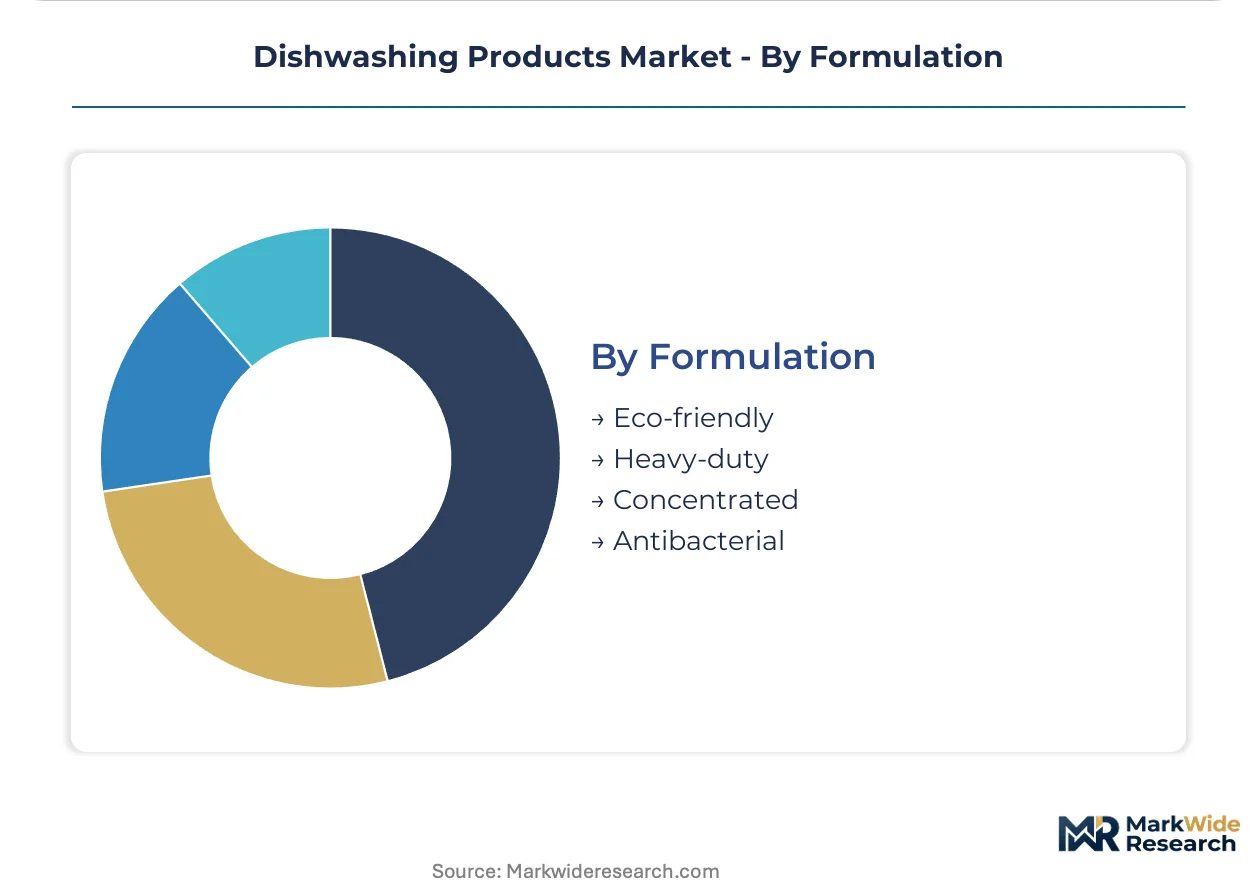
Formulation:
Certification requirements from EPA Safer Choice and EU Ecolabel are restructuring competitive position across chemistry tiers.
- Eco-friendly:Plant-derived surfactants and biodegradable builders meet REACH Annex XVII restrictions and EU Ecolabel biodegradability thresholds. Formulators pivot to natural fragrance encapsulation as microplastic-containing glitter additives face elimination.
- Concentrated:Reduced water content formulations collapse packaging cost ratios through refill station networks in European retail cooperatives and US club channels. Bulk dispensing systems enable household penetration of premium chemistry at lower per-use cost.
- Heavy-duty:High-alkalinity formulations target commercial grease-cutting requirements in foodservice operations.
- Antibacterial:Sanitizing agents address healthcare and institutional procurement specifications for pathogen control.
Heavy-duty holds installed capacity. Eco-friendly formulations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in surfactant chemistry and finished formulations vary sharply across major economies. The United States and Germany maintain formulation leadership while importing lauric acid feedstocks from Southeast Asia. India and China represent the fastest-growing consumption bases with divergent regulatory trajectories.
United States
Quick-service restaurant chain procurement drives concentrated formulation demand across franchised networks. EPA Safer Choice certification now mandates federal and state agency cleaning contracts, bypassing traditional JanSan distribution channels. Chicago and Dallas metropolitan clusters host institutional procurement consortiums negotiating multi-year supply agreements directly with certified manufacturers.
Germany
Retail buyers prioritize 45°C effective enzymatic tablets for residential machine efficiency and energy conservation. EU Ecolabel biodegradability thresholds disqualify legacy alkylphenol ethoxylates, redirecting procurement toward compliant chemistry pipelines. The Rhine-Ruhr industrial corridor concentrates spray-drying tower assets now facing utilization pressure from tablet format migration.
India
Metropolitan consumers abandon bar soaps for pump-dispensed liquid formats and unit-dose tablets in Delhi-Mumbai-Bangalore corridors. BIS standards tighten heavy-metal limits in household detergents, accelerating compliance-driven consolidation among unorganized manufacturers. Gujarat and Maharashtra host packaging lines optimized for liquid and tablet delivery systems serving tier-2 and tier-3 city expansion.
China
Phosphate-free chemistry development accelerates for both domestic consumption and export qualification to EU markets. Dual carbon goals reshape manufacturing energy profiles for spray-drying and tablet compression operations. The Yangtze River Delta cluster concentrates surfactant production capacity with backward integration into fatty alcohol supply chains.
Japan
Compact dishwasher penetration in Tokyo-Osaka metropolitan areas sustains premium tablet demand with low-temperature performance specifications. METI efficiency standards drive cold-water enzymatic formulation adoption ahead of European regulatory timelines. Kansai region chemical houses specialize in encapsulated protease stability for alkaline builder matrices.
Dishwashing Products Market Vendor Landscape
Listed leaders compete with private specialists across certification compliance and channel access dimensions. The vendor base stratifies between multinational consumer goods conglomerates with enzymatic IP portfolios and regional private-label manufacturers serving price-sensitive institutional accounts. Three archetypes dominate: European heritage formulators with Ecolabel pipelines, Asia-Pacific phosphate-free specialists, and North American club-channel exclusivity players. Competitive moves concentrate on direct institutional contracting bypass and refill station network integration.
Within the heritage formulator tier, Henkel AG and Co. KGaA and The Procter and Gamble Company exemplify divergent geographic anchoring strategies. Kao Corporation occupies a position as the Asia-Pacific phosphate-free chemistry representative. Among these, Henkel AG and Co. KGaA represents European manufacturing base continuity for enzymatic tablet lines, while The Procter and Gamble Company anchors North American shelf presence through club-channel structures. Kao Corporation exemplifies regional water hardness tailoring for country-specific formulation requirements.
| Leading Market Players |
|---|
| Henkel AG and Co. KGaA |
| Colgate-Palmolive Company |
| The Procter and Gamble Company |
| Kao Corporation |
| The Clorox Company |
| Unilever Plc |
| Church and Dwight Co. Inc. |
| Godrej Consumer Products Limited |
| Reckitt Benckiser Group Plc |
| Others |
Supply Flow & Price Mechanics
EPA Safer Choice and EU Ecolabel certification regimes gate supplier qualification while simultaneously enabling price premiums for compliant chemistry pipelines, compressing margin ladders for non-certified manufacturers and concentrating purchasing power with documented formulators.
Pricing Analysis
Quick-service restaurant procurement teams anchor contract-based long-term offtake pricing for concentrated formulations, with price differentiation driven by EPA Safer Choice certification tier and volume scale commitments. Pricing pressure intensifies in legacy powder segments as tablet and liquid formats capture share, forcing write-down decisions on spray-drying assets. Private-label manufacturers exhibit highest price sensitivity due to feedstock volatility exposure, while certified enzymatic tablet suppliers command lowest sensitivity through compliance documentation.
Supply Chain Analysis
Malaysia and Indonesia anchor lauric acid and palm kernel oil feedstock production for surfactant manufacturing, while Germany and the United States concentrate enzymatic tablet formulation and packaging line optimization. Supply chains draw from Southeast Asian plantation output cycles, Novozymes and DuPont protease strains, and regional water-hardness-tailored builder chemistry. Single-source vulnerability in specialty enzyme supply creates structural risk for reformulating brands. Distribution runs through foodservice distributors for commercial specifications and retail cooperatives for refill station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across EPA Safer Choice, EU Ecolabel, and India's BIS standards fragments competitive position and creates white-space niches for certification-specialist formulators and regional compliance advisors.
For Market Incumbents: Shield enzymatic tablet margins through backward integration into encapsulation IP for protease stability in alkaline matrices. Consolidate position in direct institutional contracting channels before JanSan distributors restructure, leveraging EPA Safer Choice documentation as a barrier against private-label encroachment in healthcare and education sectors. For New Entrants and Emerging Players: Differentiate on phosphate-free chemistry tailored to regional water hardness profiles in Asia-Pacific markets. Target tier-2 and tier-3 Indian cities with concentrated liquid formats for hand-wash pre-soak routines ahead of dishwasher appliance adoption curves, deploying e-commerce platform discovery as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic tablet production as encapsulation technology and certification compliance documentation requirements reshape facility economics. Long-term viability favors acquisition targets with captive enzyme supply relationships and multi-regulatory approval pipelines. Watch for divergence in phosphate ban grandfathering timelines between US states and EU member countries as the inflection signal for production batch economics stress.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Cold-Water Formulation Development | 45°C effective chemistry captures German and Dutch residential efficiency priorities ahead of commercial specifications. |
| Direct Institutional Contracting Expansion | Bypassing JanSan distributors concentrates volume with EPA Safer Choice-certified manufacturers in healthcare procurement. |
| Refill Station Network Integration | Bulk dispensing systems in European retail cooperatives collapse packaging cost ratios for household penetration. |
| Phosphate-Free Chemistry Pipeline Investment | REACH Annex XVII and divergent state-level bans disqualify legacy formulations from export eligibility. |
| Tier-2 and Tier-3 India Distribution Buildout | Packaging lines optimized for liquid and tablet delivery systems capture format migration ahead of appliance adoption. |
Methodological Framework
A standing panel of brand managers at multinational consumer goods conglomerates, category buyers at European retail cooperatives, procurement leads at quick-service restaurant chains, and technical R&D directors at enzymatic specialty houses provided ongoing calibration. Primary interview findings were validated against secondary sources including customs and trade data for lauric acid feedstock flows, SEC 10-K filings for disclosed segment performance, EPA Safer Choice certified product listings, and EU Ecolabel registry databases. Bottom-up volume modeling across product type, distribution channel, end user, and formulation segments was triangulated against top-down macroeconomic anchors.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled segmentation dimensions including format type, certification tier, regional regulatory cluster, and water hardness profile. CAGRs were derived from fitted growth curves incorporating appliance penetration rates, urbanization trajectories, and compliance-driven consolidation timelines. Forecast inputs included dishwasher machine ownership projections and enzymatic tablet substitution elasticities.
The analysis sits within stated boundaries; outcomes outside sustained EPA Safer Choice program continuity, EU Ecolabel threshold stability, or plantation output cycle normalization would require recalibration. Forecasts reflect documented assumptions regarding feedstock price trajectories and regulatory phase-out schedules. Recalibration cycles align with material shifts in certification requirement amendments and enzyme supplier concentration events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Fork Market
Household Items
Infuser Water Bottles Market
Household Items
Portable Steamers Market
Household Items
US Air Purifier Market
Household Items
Brazil Cookware Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Bottle Openers Market
Household Items
Canada Digital Showers Market
Household Items
Tablet Tissue Paper Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Sorting Hampers Market
Household Items
Japan Faucets Market
Household Items
Robot Vacuum Cleaners Market
Household Items
North America B2B Air Care Market
Household Items
Toilet Cistern Blocks Market