
 Kick Bucket Market | 2026-2036
Kick Bucket Market Size, Share, and Industry Trends Forecast 2026-2036
Kick Bucket Market Analytics
REACH compliance is restructuring the cost-of-entry calculus for European-sourced polymer components in kick bucket manufacturing. Stryker Corporation leverages its orthopedic supply chain scale to anchor distribution across North American hospital networks. Cardinal Health competes through direct sales contracts with integrated delivery networks, while Medline Industries sustains private-label manufacturing flexibility across multiple material grades.
A kick bucket is a mobile, lidded receptacle—typically constructed from stainless steel, high-density polyethylene, or fiberglass-reinforced polymer—designed to collect and transport surgical waste, soiled linens, or irrigation fluids within sterile environments. Wall thickness ranges from 1.2 mm to 2.5 mm depending on load rating, with caster-mounted bases rated for 150–300 lb capacity to ensure maneuverability under operating tables. Metal variants dominate hospital procurement due to autoclave compatibility and extended service life, though plastic segments are gaining share in outpatient surgical centers where capital budgets constrain upfront investment. Construction end users represent a mature channel with price-sensitive bulk purchasing, while agriculture and landscaping applications show faster growth through wholesale distribution to regional equipment cooperatives.
The FDA enforces 21 CFR Part 820 quality system regulations for medical device accessories, while OSHA's bloodborne pathogen standard shapes lid-sealing and splash-containment specifications; the EPA's medical waste tracking requirements further dictate disposal-container interoperability. ISO 13485 certification has become a de facto gate for supplier qualification at tier-one distributors. Stakeholders must monitor evolving state-level surgical waste regulations and assess whether material substitution strategies preserve sterility assurance while reducing compliance burden.
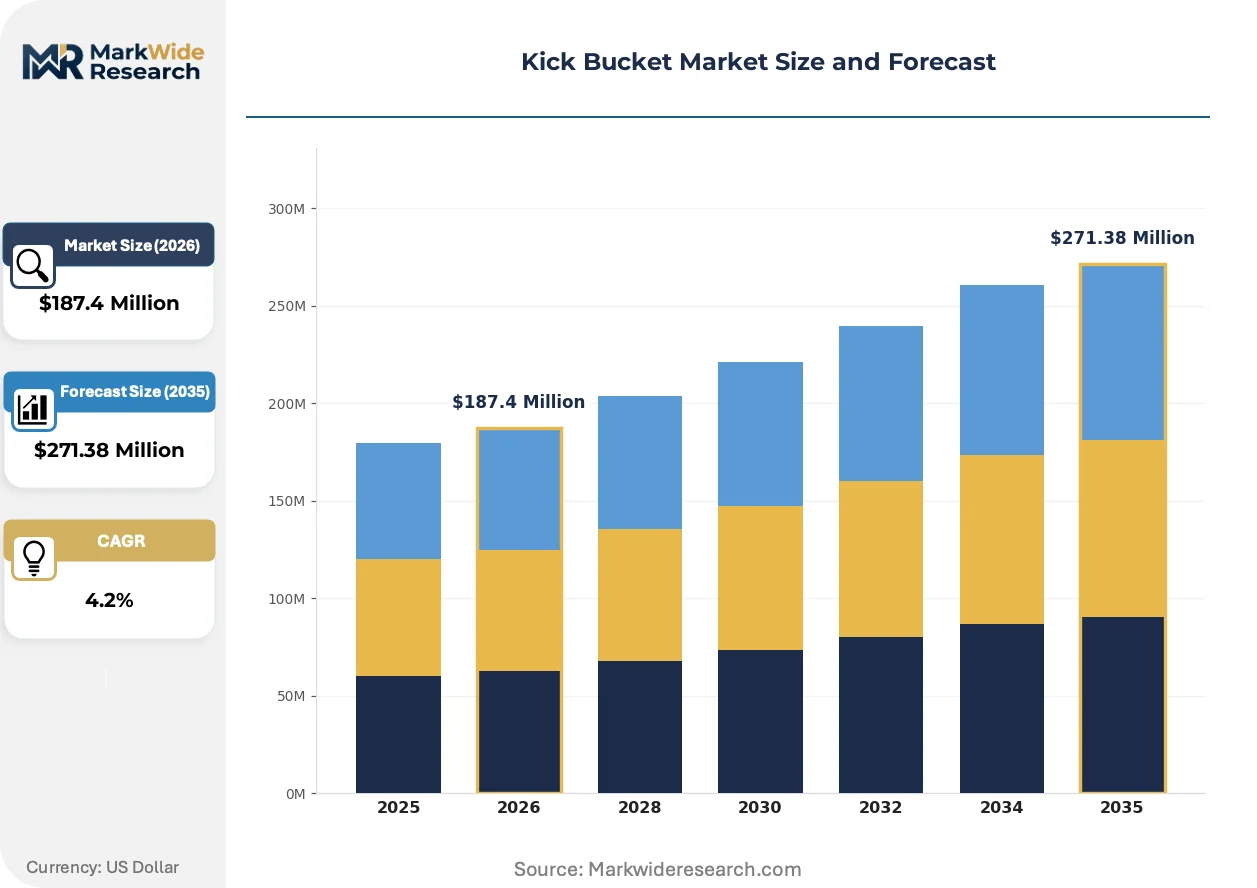
Market Dynamics
Hospital procurement consolidation is concentrating purchasing power among integrated delivery networks, forcing kick bucket manufacturers to restructure pricing and service models around multi-year enterprise contracts rather than transactional sales.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Stricter splash-containment mandates in US surgical environments are accelerating replacement cycles for legacy open-top receptacles with sealed-lid designs.
- Outpatient surgical centers:Ambulatory facility expansion across suburban markets is generating demand for lightweight polymer variants that reduce capital expenditure burdens.
- Autoclave compatibility:Stainless steel construction with 1.5 mm wall thickness is displacing plastic alternatives in tertiary hospitals prioritizing instrument reprocessing efficiency.
Market Restraints
- REACH polymer compliance:European chemical registration requirements are inflating raw material costs for fiberglass-reinforced components by 12–18 percent.
- Stainless steel supply concentration:Mill capacity constraints in East Asian metallurgical clusters are extending lead times for surgical-grade 304 sheet.
- Manual handling limitations:Caster-rated load thresholds cap waste volume per transport cycle, limiting throughput in high-volume orthopedic suites.
Strategic Opportunities
- Indian hospital infrastructure:Greenfield medical cities under the Ayushman Bharat scheme require turnkey surgical waste systems including mobile receptacles.
- Smart hospital integration:RFID-enabled kick buckets are converging with real-time location systems to track waste chain-of-custody.
- Direct-to-facility distribution:Bypassing distributor markups through manufacturer-owned logistics networks captures margin in price-sensitive construction channels.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management audits require 14–18 months, delaying supplier qualification for tier-one distributors.
- Weld seam integrity:Stainless steel fabrication demands specialized orbital welding expertise that contract manufacturers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kick Bucket Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Fiberglass, Wood End User: Construction, Agriculture, Landscaping, Mining Size: Small, Medium, Large, Extra Large Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Boston Scientific, Smith & Nephew, B. Braun Melsungen, Becton Dickinson, Stryker Corporation, Medline Industries, Cardinal Health, McKesson Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kick Bucket Market Evolving Landscape
Material science advances and digital traceability requirements are redefining kick bucket specifications, with manufacturers racing to balance sterility assurance against total cost-of-ownership pressures.
Antimicrobial copper-alloy surface coatings are integrating into premium stainless steel variants to reduce bioburden in extended-use scenarios. Tertiary care centers in Germany and Japan are piloting these formulations for 72-hour continuous deployment. The technology is integrating pathogen-resistance metrics into standard procurement scorecards, compressing competitive differentiation around clinical outcomes rather than price alone.
EPA's medical waste tracking regulations are mandating serialized container identification for interstate transport documentation. Manufacturers must now embed permanent marking systems capable of withstanding autoclave cycling and chemical disinfection. Outpatient surgery chains in California and Texas are retrofitting existing fleets to maintain compliance, creating aftermarket revenue streams for labeling system suppliers.
Health system buyers are consolidating vendor rosters from 12–15 suppliers to 3–4 strategic partners covering full surgical waste workflows. Integrated delivery networks now demand kick buckets as components of comprehensive fluid management programs rather than standalone capital purchases. This concentration is most visible in the southeastern United States, where hospital mergers have compressed purchasing cycles and elevated service-level agreements above unit pricing in selection criteria.
Kick Bucket Market Segmentation
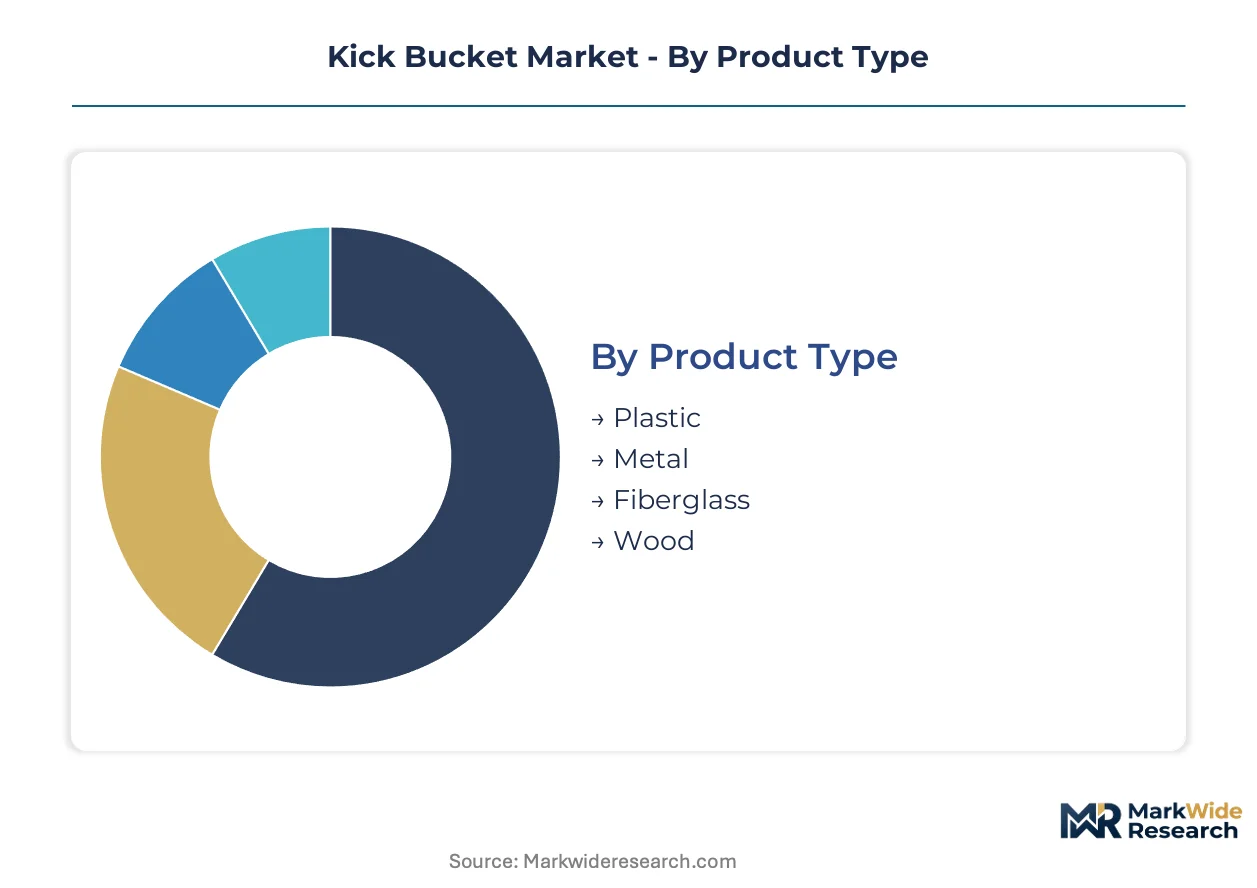
Kick bucket procurement patterns diverge sharply across material grades, end-use environments, and channel structures. Understanding these fault lines exposes where margin pools concentrate and which specifications command pricing power.
Product Type:
Supply concentration in East Asian metallurgical clusters and European polymer feedstock networks shapes competitive dynamics across material categories.
- Plastic:High-density polyethylene and fiberglass-reinforced polymer formulations dominate outpatient surgical centers and construction sites where capital constraints limit upfront investment. REACH compliance costs are inflating European-sourced polymer components, compressing margins for manufacturers dependent on EU feedstock supply chains.
- Metal:Surgical-grade 304 stainless steel with 1.5 mm wall thickness anchors hospital procurement due to autoclave compatibility and extended service life. Mill capacity constraints in East Asian clusters are extending lead times, forcing tertiary hospitals to pre-position inventory.
- Fiberglass:Reinforced polymer variants balance chemical resistance with moderate weight reduction for agricultural cooperatives and landscaping fleets.
- Wood:Legacy material persists in price-sensitive construction bulk purchasing where disposable deployment outweighs durability requirements.
Today's leader: Metal. Tomorrow's challenger: Plastic.
End User:
Application-specific durability requirements and regulatory exposure create tiered demand profiles with divergent service expectations.
- Construction:Bulk purchasing patterns prioritize unit economics over feature sophistication, with wholesale distribution capturing volume through regional equipment cooperatives.
- Agriculture:Regional equipment cooperatives drive faster growth through wholesale channels, with fiberglass variants gaining traction for chemical resistance in livestock and crop operations.
- Landscaping:Wholesale distribution to municipal and commercial maintenance fleets favors medium-capacity polymer models for maneuverability across uneven terrain.
- Mining:Heavy-duty metal construction with reinforced caster mounts addresses load-rated requirements in mineral extraction environments where equipment failure carries operational downtime costs.
Construction commands current volume. Agriculture climbs the fastest.
Size:
Load-rated capacity thresholds and maneuverability constraints segment the market across facility types and waste throughput requirements.
- Small:Compact footprints suit outpatient surgical suites and confined construction zones where space optimization overrides volume efficiency.
- Medium:Balanced capacity-to-maneuverability ratio dominates hospital operating rooms and landscaping maintenance fleets as the default specification.
- Large:Extended capacity serves high-volume orthopedic suites and agricultural operations where transport cycle frequency directly impacts labor productivity.
- Extra Large:Specialized deployment in mining and tertiary hospital central sterile processing addresses bulk waste aggregation with reinforced caster ratings for 300 lb capacity.
Medium holds installed base dominance. Large gains share fastest.
Distribution Channel:
Procurement consolidation among integrated delivery networks and price-sensitive construction buyers is restructuring channel economics and margin capture.
- Retail:Limited penetration outside small-scale landscaping and residential construction where immediate availability outweighs unit pricing.
- Wholesale:Regional equipment cooperatives and distributor networks anchor volume in construction, agriculture, and landscaping through price-sensitive bulk purchasing.
- Online:Digital procurement platforms gain traction among outpatient surgical centers and independent construction contractors seeking specification transparency.
- Direct Sales:Multi-year enterprise contracts with integrated delivery networks capture margin in hospital systems, bypassing distributor markups while embedding service-level agreements.
Wholesale owns current volume. Direct Sales captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled surgical equipment technicians cluster in the United States, Germany, Japan, India, and China, anchoring regional manufacturing capabilities and procurement patterns for mobile waste receptacles.
United States
Integrated delivery networks in Texas and Florida are consolidating vendor rosters for surgical waste systems. OSHA bloodborne pathogen standards mandate sealed-lid designs in California and New York operating rooms. The Cleveland Clinic and Mayo Clinic procurement coalitions in Ohio and Minnesota are pre-positioning stainless steel inventory amid mill lead time extensions.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia are piloting antimicrobial copper-alloy coated receptacles for extended deployment cycles. REACH compliance is restructuring polymer component sourcing from BASF and Covestro feedstock networks. The Stuttgart industrial cluster is developing specialized orbital welding capacity for surgical-grade 304 fabrication.
Japan
Metropolitan Tokyo and Osaka hospital systems prioritize autoclave-compatible metal construction for instrument reprocessing efficiency. METI guidelines on medical device quality management shape supplier qualification timelines. The Nagoya manufacturing corridor is concentrating precision fabrication expertise for thin-wall stainless steel components.
India
Greenfield medical cities under Ayushman Bharat in Maharashtra and Gujarat require turnkey surgical waste infrastructure. CDSCO medical device rules are tightening material traceability for imported polymer components. The Chennai and Hyderabad device manufacturing zones are scaling contract fabrication capacity for regional hospital procurement.
China
Provincial hospital consolidation in Jiangsu and Guangdong is standardizing mobile receptacle specifications across facility networks. NMPA quality system regulations align with ISO 13485 for domestic and export qualification. The Yangtze River Delta metallurgical cluster is expanding surgical-grade stainless sheet capacity for domestic and Asia-Pacific supply.
Kick Bucket Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Hospital systems and construction buyers face distinct vendor mixes. Three archetypes dominate: diversified medical supply conglomerates with orthopedic and surgical portfolios; pure-play hospital equipment specialists with ISO-certified fabrication; and regional contract manufacturers serving price-sensitive bulk channels. Capacity pre-positioning and distributor relationship consolidation represent the dominant competitive moves as lead times extend and procurement concentrates.
Among diversified medical supply conglomerates, Stryker Corporation and Cardinal Health exemplify scale-driven positioning across North American hospital networks. Medline Industries occupies a specialist tier with private-label manufacturing flexibility. These three anchors represent contrasting strategic postures: Stryker leverages orthopedic supply chain integration, Cardinal Health competes through direct integrated delivery network contracts, and Medline sustains multi-material production adaptability across stainless steel and polymer grades.
| Leading Market Players |
|---|
| Boston Scientific |
| Smith & Nephew |
| B. Braun Melsungen |
| Becton Dickinson |
| Stryker Corporation |
| Medline Industries |
| Cardinal Health |
| McKesson Corporation |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Backward integration into surgical-grade stainless steel sheet production anchors both supply security and pricing power for tier-one manufacturers serving integrated delivery networks. This captive sourcing strategy insulates procurement costs from mill capacity volatility in East Asian metallurgical clusters while enabling multi-year enterprise contract pricing that undercuts distributor-dependent competitors.
Pricing Analysis
Service bundling separates hospital procurement from construction channel economics. Three-tier pricing structure across premium antimicrobial-coated, standard autoclave-compatible, and economy polymer grades reflects ISO 13485 certification investment and wall thickness specifications. Cost compression in the plastic segment intensifies as REACH compliance inflates European-sourced polymer feedstock expenses. Construction buyers exhibit highest price sensitivity, while tertiary hospitals prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Orbital welding technician scarcity in Germany and Japan constrains stainless steel fabrication capacity for thin-wall surgical-grade components. Supply concentrates in China's Yangtze River Delta metallurgical cluster, India's Chennai device manufacturing zone, and the Stuttgart industrial corridor for specialized fabrication. Raw material flows draw from East Asian 304 stainless sheet mills, European BASF and Covestro polymer feedstock networks, and regional fiberglass reinforcement suppliers. Single-source vulnerability runs through concentrated East Asian mill capacity for surgical-grade sheet. Distribution runs through direct sales contracts with integrated delivery networks for hospital systems, wholesale regional cooperatives for construction and agriculture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kick bucket market functions as a stable compounder anchored by perpetual replacement demand from OSHA-mandated sealed-lid upgrades and hospital infrastructure expansion.
For Market Incumbents: Cement multi-year enterprise service agreements with integrated delivery networks to lock out distributor-dependent challengers. Deepen backward integration into surgical-grade stainless steel sheet sourcing to insulate margins from East Asian mill lead time volatility. Prioritize ISO 13485 certification maintenance as a qualification gate against emerging regional contract manufacturers. For New Entrants and Emerging Players: Launch via direct-to-facility distribution bypassing wholesale markups in price-sensitive construction and agriculture channels. Target outpatient surgical centers in suburban US markets and greenfield medical cities under India's Ayushman Bharat scheme where capital constraints favor lightweight polymer variants. Emphasize RFID-enabled traceability features for smart hospital integration as a differentiation wedge. For Investors and Strategic Acquirers: Roll-up economics work for regional contract manufacturers with ISO-certified fabrication capacity because hospital procurement consolidation is compressing vendor rosters from fragmented supplier bases to strategic partnerships. The 5-10 year viability window favors targets with established integrated delivery network relationships and multi-material production flexibility. Watch for NMPA alignment with ISO 13485 accelerating China domestic qualification timelines as an inflection signal for regional manufacturing footprint expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Qualification gate for tier-one distributor access and integrated delivery network contracts. |
| Antimicrobial Surface Coating Development | Copper-alloy integration shifts procurement scorecards toward clinical outcome metrics. |
| RFID Traceability System Integration | EPA medical waste tracking compliance creates aftermarket retrofit revenue streams. |
| Direct Sales Channel Establishment | Bypasses distributor markups while embedding service-level agreements in hospital procurement. |
| Regional Manufacturing Footprint Expansion | Proximity to India's Chennai and Hyderabad device zones reduces import logistics exposure. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and surgical equipment distributors grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, hospital procurement databases, OSHA regulatory dockets, and customs trade records for surgical-grade stainless steel and polymer component flows. Bottom-up facility installation estimates and top-down surgical procedure volume projections were triangulated to anchor market sizing.
Segment-level outputs across material grade, end-use environment, load capacity tier, and distribution channel structure were generated across the projection horizon. CAGRs were derived from procedure volume growth trajectories, replacement cycle compression from regulatory mandate timing, and capital expenditure patterns in outpatient facility expansion. Forecast inputs incorporated REACH compliance cost pass-through rates, mill capacity utilization in East Asian metallurgical clusters, and integrated delivery network vendor consolidation timelines.
Several conditions sit outside the modeled scope, including abrupt tariff reclassification for surgical device accessories, breakthrough material substitution displacing stainless steel in autoclave environments, and pandemic-scale disruption to hospital capital expenditure planning. Forecasts reflect assumptions about regulatory enforcement continuity and supply chain corridor stability. Material deviation in OSHA mandate expansion timing, REACH polymer registration cost trajectories, or integrated delivery network merger velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
India POU Water Purifiers Market
Household Items
Hydration Containers Market
Household Items
Brazil Cookware Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Gas Hobs Market
Household Items
Candle Air Fresheners Market
Household Items
Insulated Lunch Box Market
Household Items
Acrylic Aquarium Market
Household Items
Electric Hedge Trimmer Market
Household Items
Nebulizing Diffuser Market
Household Items
Asean Cookware Market
Household Items
Household Sewing Machines Market
Household Items
Smart Shower Market
Household Items
Toilet Paper Market
Household Items
Scouring Pads Market
Household Items
LAMEA Robotic Pool Cleaner Market