
 Water Purifier Bottle Market | 2026-2036
Water Purifier Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Water Purifier Bottle Market Analytics
Direct-to-consumer channels is rewriting how water purifier bottles reach end users, with subscription models and brand-owned storefronts displacing traditional wholesale arrangements. GRAYL leverages its premium positioning to capture high-margin adventure travel segments through controlled digital distribution. LifeStraw anchors humanitarian and outdoor retail presence with institutional procurement contracts that sustain volume. CamelBak competes across hydration system integration, extending its brand from reservoirs into filtration bottles with shared component ecosystems.
A water purifier bottle integrates physical filtration media, chemical treatment, or ultraviolet sterilization into a portable vessel designed to reduce pathogens, particulates, and chemical contaminants from untreated water sources. Most units employ hollow-fiber membranes rated to 0.1 micron absolute or activated carbon blocks to address protozoa, bacteria, and chlorine taste simultaneously. Gravity filter configurations lead in basecamp and group scenarios where volume throughput outweighs portability constraints. UV filter variants occupy the fastest-expanding niche among ultralight travelers prioritizing weight reduction over mechanical redundancy. Activated carbon segments retain margin concentration in developed markets where aesthetic improvement commands premium positioning.
EPA guidelines for microbiological purifiers and NSF/ANSI 42, 53, and P231 standards in the United States establish performance baselines that shape product development budgets and import eligibility. The EU Drinking Water Directive and REACH chemical compliance in Europe add material disclosure and migration testing requirements that filter out low-cost competitors. Stakeholders must monitor evolving state-level PFAS notification thresholds and emerging microplastic filtration claims that will redefine certification scope and consumer expectation.
Market Dynamics
Certification requirements are fragmenting competitive access across the Water Purifier Bottle Market, with NSF/ANSI 42 and 53 standards in the United States and EU Drinking Water Directive compliance in Europe creating divergent qualification costs that favor established players with dedicated regulatory affairs capacity.
Growth Catalysts
- Hiking participation in Germany and the United Kingdom:Municipal water quality concerns overlap with outdoor recreation demand, creating dual-use purchase motivation among consumers seeking portable filtration for both trail and tap scenarios.
- NSF/ANSI P231 microbiological purifier standards:The EPA-aligned testing protocol for virus removal is elevating performance baselines and opening institutional procurement channels for emergency responders and humanitarian agencies.
- UV-C LED miniaturization:Solid-state ultraviolet sources are reducing power requirements and bulb fragility, enabling battery-integrated designs that appeal to ultralight backpackers prioritizing weight reduction.
Market Restraints
- Hollow-fiber membrane supply concentration:Asian contract manufacturers dominate microporous polyethersulfone production, creating single-source vulnerability for brands without backward integration into membrane casting.
- REACH chemical compliance costs:European material disclosure and migration testing requirements add fixed overhead that filters out low-volume competitors from EU market entry.
- Gravity filter portability limits:The volume-throughput advantage of pump-free configurations sacrifices packability, restricting adoption to basecamp scenarios and excluding day-hiker segments.
Strategic Opportunities
- Emerging PFAS notification thresholds:State-level per- and polyfluoroalkyl substance regulations in the United States are creating demand for activated carbon formulations with expanded adsorption capacity beyond chlorine taste improvement.
- Subscription filter replacement models:Direct-to-consumer channels are enabling recurring revenue streams through automated cartridge replenishment, displacing traditional retail replenishment cycles.
- Microplastic filtration claims:Emerging certification scope for synthetic particle removal offers positioning differentiation in developed markets where aesthetic improvement commands premium tier placement.
Industry Challenges
- NSF/ANSI certification timeline compression:Multi-month laboratory validation processes delay product launches and tie up working capital in inventory awaiting approval.
- Activated carbon sourcing complexity:Coconut shell supply volatility and virgin versus reactivated grade differentiation require specialized procurement expertise to maintain margin concentration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Purifier Bottle Market |
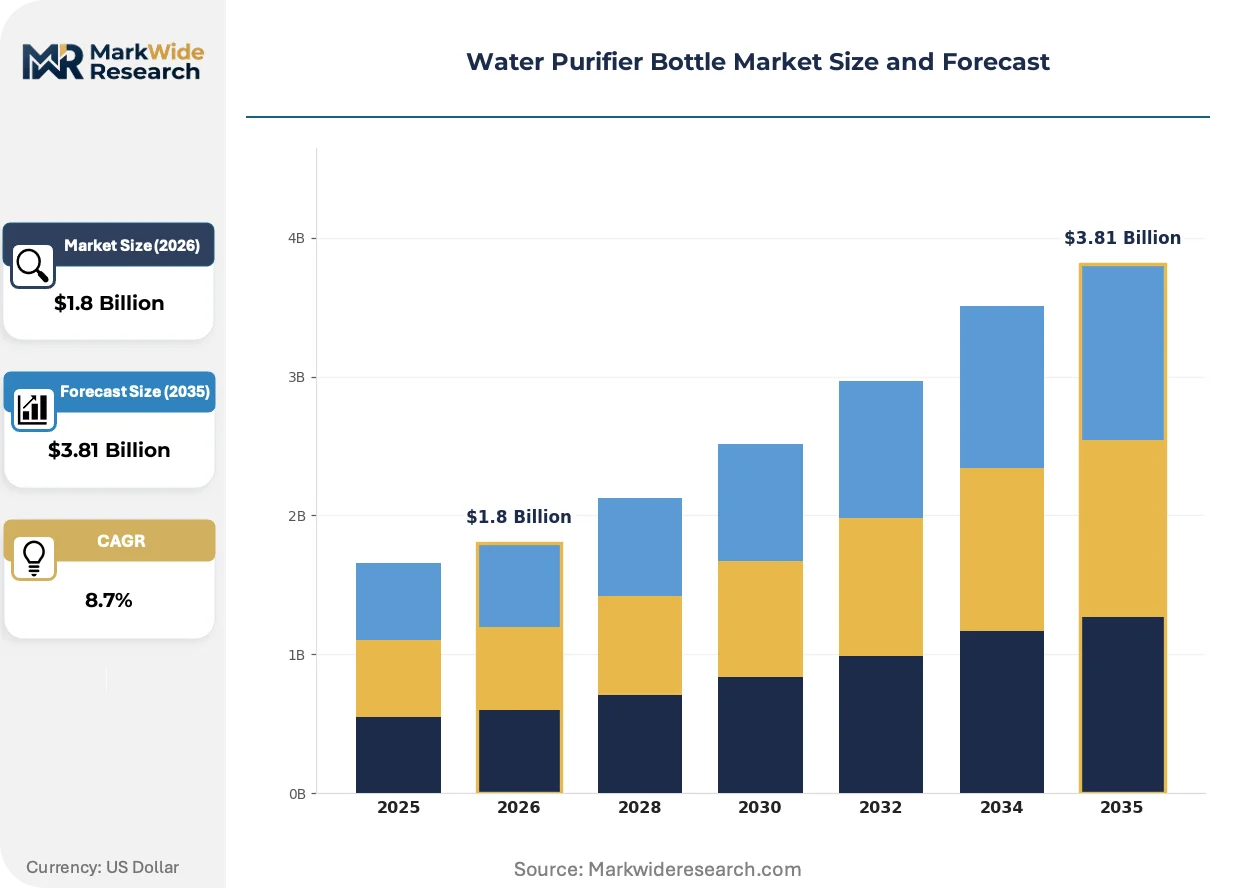
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Filter, UV Filter, Activated Carbon, Reverse Osmosis Application: Camping, Traveling, Emergency Preparedness, Everyday Use Distribution Channel: E-commerce, Retail Stores, Outdoor Shops, Health & Wellness Stores End User: Outdoor Enthusiasts, Travelers, Emergency Responders, Households |
| Companies Covered | GRAYL, LifeStraw, CamelBak, Brita, Sawyer, Aquasana, LifeSaver, KOR Water, Nalgene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Purifier Bottle Market Evolving Landscape
Filtration technology convergence with connected hardware and shifting procurement channels are compressing traditional product lifecycles while expanding addressable use cases beyond recreational outdoor activity.
Electrochemical advanced oxidation processes integrated into portable vessels are rendering obsolete chemical tablet dependence among military and expedition users who previously accepted taste degradation for pathogen inactivation. Defense procurement programs in NATO member states are piloting these systems for forward deployment scenarios where resupply logistics constrain iodine or chlorine dioxide stockpiles. The structural consequence is a compression of the chemical treatment segment to price-sensitive consumer tiers while electrochemical platforms capture institutional volume.
REACH chemical compliance in Europe is mandating material disclosure thresholds for bisphenol and phthalate content that reshape polymer selection across housing and seal components. Manufacturers are accelerating migration from polycarbonate to Tritan copolyester and stainless steel to preempt regulatory friction. The premium segment is responding fastest, using compliance as a positioning wedge against uncertified imports in German and United Kingdom retail channels.
Brand-owned digital storefronts are displacing traditional outdoor retail distribution for replacement cartridge sales and accessory attach. Subscription mechanics tied to usage-based algorithms rather than calendar intervals are capturing customer lifetime value previously lost to third-party replenishment. This channel rotation is most visible in North American direct-to-consumer operations where data ownership enables predictive inventory positioning ahead of seasonal demand spikes.
Water Purifier Bottle Market Segmentation
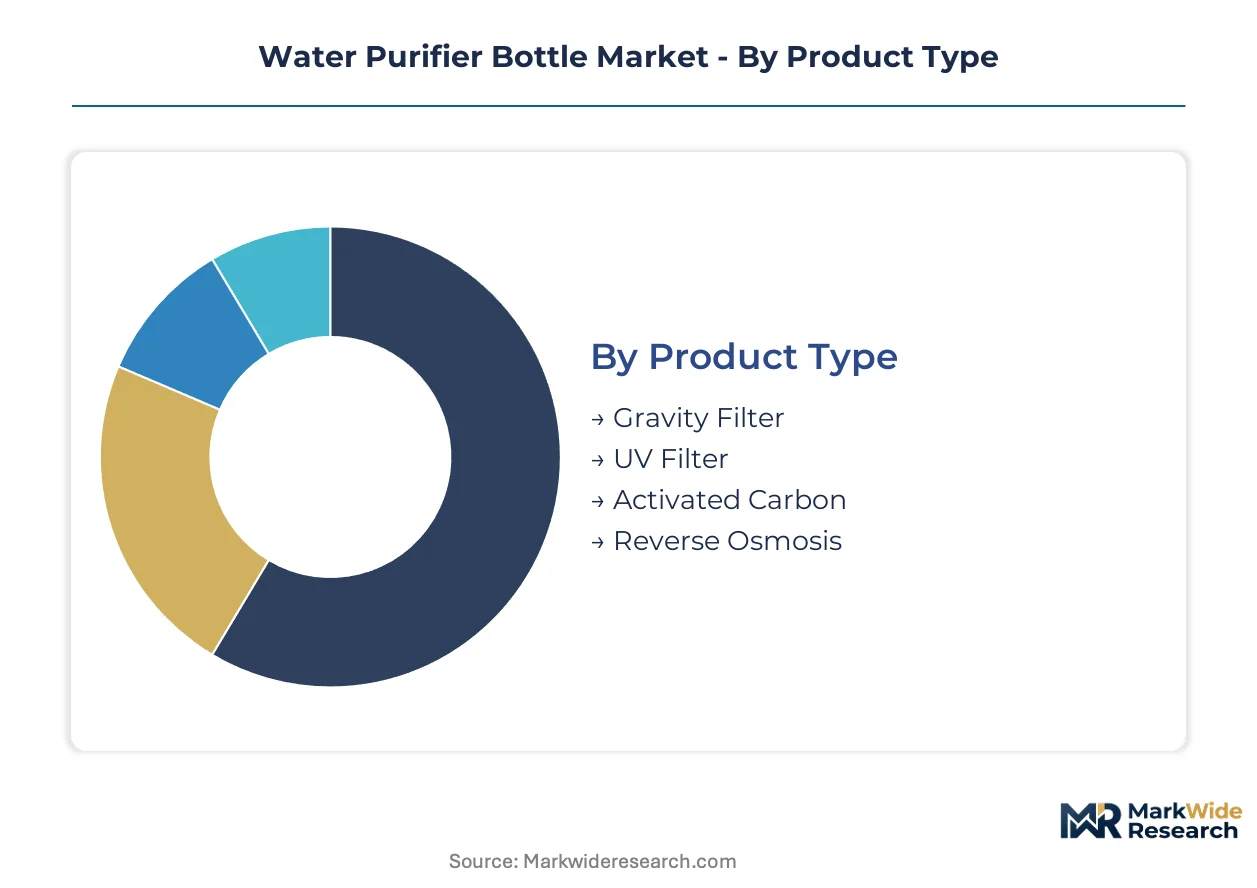
Water purifier bottle segmentation reflects divergent performance requirements across recreational, professional, and domestic contexts. Technical specifications, certification tiers, and channel economics create distinct addressable markets within each dimension.
Product Type:
Mature mechanical filtration platforms coexist with emerging electrochemical and solid-state sterilization technologies, creating a bifurcated innovation landscape.
- Gravity Filter:Pump-free configurations employ hollow-fiber membranes in vertical flow geometries optimized for group basecamp scenarios. Demand concentrates in Germany and the United Kingdom where multi-day hiking participation drives volume procurement for alpine and trailhead use; throughput advantages sacrifice packability and exclude ultralight segments.
- UV Filter:Solid-state ultraviolet LED miniaturization enables battery-integrated designs below 150 grams total system weight. Ultralight backpackers in North American national parks and Pacific Crest Trail corridors prioritize this segment for weight reduction over mechanical redundancy; EPA microbiological purifier standards elevate performance baselines and open institutional channels.
- Activated Carbon:Coconut shell and reactivated carbon blocks address chlorine taste, odor, and emerging PFAS adsorption requirements in developed markets.
- Reverse Osmosis:Integrated pump systems achieve dissolved solids rejection for brackish source compatibility in expedition and maritime applications.
Gravity Filter retains volume leadership; UV Filter holds the steepest expansion curve.
Application:
Cost tier stratification separates premium expedition-grade systems from mass-market everyday solutions.
- Camping:Multi-day backcountry use demands NSF/ANSI 42 and 53 certified pathogen reduction combined with field-maintainable cartridge replacement. Demand clusters around REI Co-op and specialty outdoor retailers in Colorado, Oregon, and Washington state where wilderness permit issuance correlates with equipment procurement cycles.
- Traveling:International destination use prioritizes compact form factors and broad-spectrum pathogen coverage for municipal source uncertainty. Business travelers and adventure tourists in the United Kingdom and Germany drive replacement cycles through airport retail and direct-to-consumer channels; subscription filter models capture recurring revenue.
- Emergency Preparedness:Institutional procurement by FEMA, state emergency management agencies, and humanitarian organizations sustains volume for virus-rated systems.
- Everyday Use:Municipal tap improvement applications emphasize aesthetic filtration and microplastic reduction claims in premium positioning.
Everyday Use commands margin concentration; Emergency Preparedness generates the most predictable procurement volumes.
Distribution Channel:
Channel rotation toward direct-to-consumer ownership is compressing wholesale margin structures and enabling usage-based subscription mechanics.
- E-commerce:Brand-owned digital storefronts and Amazon marketplace presence enable data capture for predictive inventory positioning. GRAYL and LifeStraw direct channels displace traditional outdoor retail for replacement cartridge replenishment; subscription algorithms tied to filter lifespan rather than calendar intervals capture customer lifetime value.
- Retail Stores:Mass-market big-box placement depends on NSF/ANSI certification eligibility that filters uncertified imports from Walmart and Target shelves.
- Outdoor Shops:REI Co-op, Bass Pro Shops, and regional specialty retailers maintain experiential merchandising for high-consideration purchases.
- Health & Wellness Stores:Whole Foods Market and independent natural products retailers emphasize BPA-free and REACH-compliant material positioning.
E-commerce is gaining share fastest; Outdoor Shops retain the highest average transaction values.
End User:
Customer type segmentation aligns procurement authority with use case specificity and certification requirements.
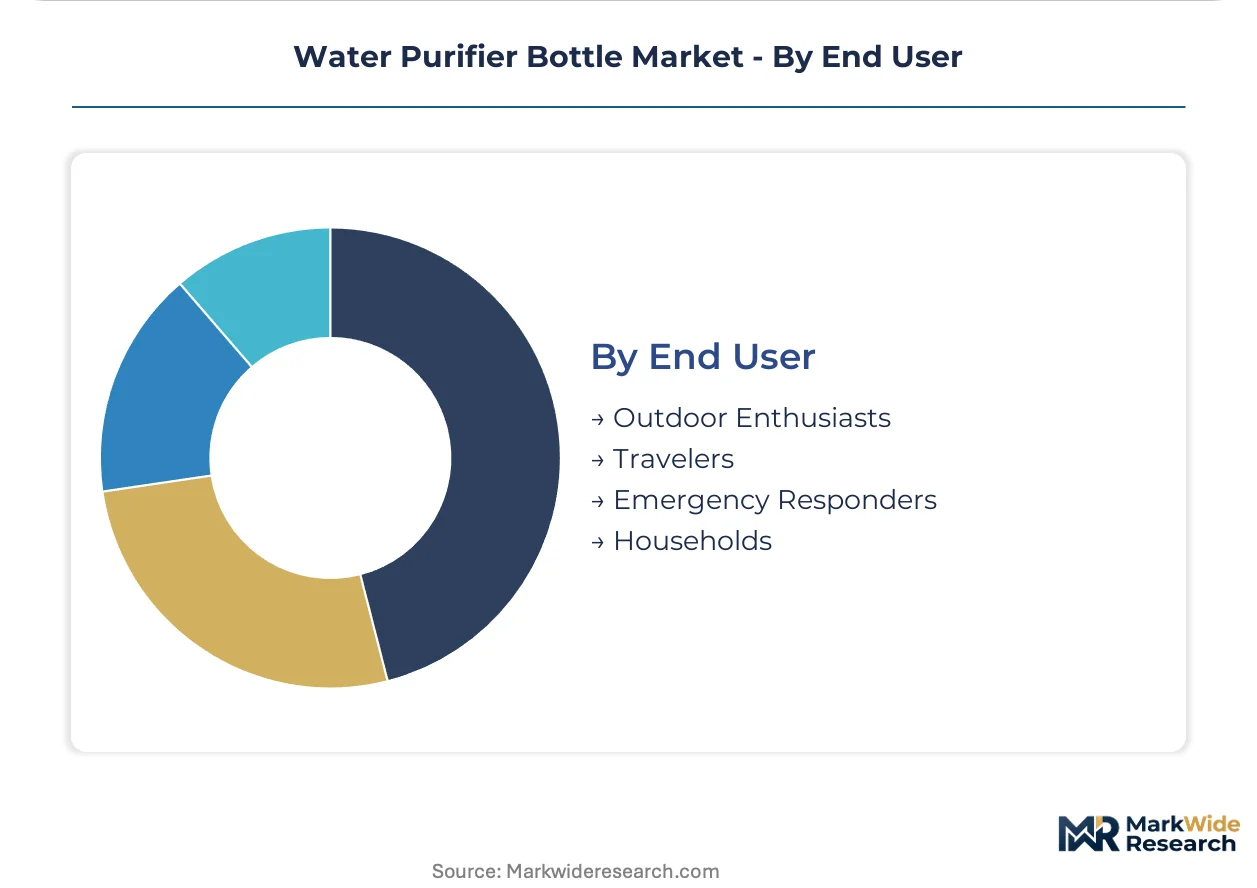
- Outdoor Enthusiasts:Backpackers, climbers, and paddlers prioritize weight-to-performance ratios and field serviceability. Appalachian Trail and Pacific Crest Trail thru-hiker communities in the United States drive seasonal demand spikes; ultralight UV and hollow-fiber configurations dominate this segment.
- Travelers:International destination users seek compact all-in-one solutions for airline carry-on compliance and broad-spectrum protection.
- Emergency Responders:Fire departments, search-and-rescue teams, and military units require NSF/ANSI P231 virus-rated systems for institutional procurement.
- Households:Municipal tap improvement applications concentrate in German and United Kingdom urban centers where consumer confidence in water quality varies by postcode.
Outdoor Enthusiasts drive replacement frequency; Emergency Responders provide the most stable contract revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA microbiological purifier guidelines and NSF/ANSI certification requirements in the United States filter uncertified imports and elevate performance baselines. The EU Drinking Water Directive and REACH chemical compliance add material disclosure costs that reshape competitive access across developed markets.
United States
Outdoor enthusiasts and emergency responders drive replacement cycles across Colorado, Oregon, and Washington state where wilderness permit issuance correlates with equipment procurement. NSF/ANSI 42, 53, and P231 standards establish EPA-aligned testing protocols for virus removal that open institutional procurement channels. Appalachian Trail and Pacific Crest Trail thru-hiker communities in the eastern and western mountain corridors sustain seasonal demand for ultralight configurations.
Germany
Hiking participation overlaps with municipal water quality concerns, creating dual-use purchase motivation for portable filtration serving both trail and tap scenarios. REACH chemical compliance mandates material disclosure thresholds for bisphenol and phthalate content that accelerate polymer migration from polycarbonate to Tritan copolyester. Bavaria and Baden-Württemberg host alpine equipment clusters where specialty outdoor retailers maintain experiential merchandising for high-consideration purchases.
United Kingdom
Adventure tourists and business travelers drive replacement cycles through airport retail and direct-to-consumer channels, with subscription filter models capturing recurring revenue. The Drinking Water Inspectorate enforces quality standards that shape consumer confidence in municipal supply and boost portable filtration adoption. London and Southeast England concentrate urban demand where postcode-level water quality variation sustains everyday use applications.
Canada
Backcountry canoe tripping and northern expedition use sustains demand for gravity filter configurations optimized for group basecamp scenarios. Health Canada and PMRA establish microbiological and chemical contaminant guidelines that align with NSF/ANSI performance baselines for cross-border product eligibility. Ontario and British Columbia host wilderness recreation clusters where multi-day hiking participation drives volume procurement for trailhead filtration.
Australia
Remote area travel and bushwalking sustain demand for broad-spectrum pathogen coverage in municipal source uncertainty scenarios. The Therapeutic Goods Administration and state-level health departments regulate water treatment device claims that shape import eligibility and certification requirements. New South Wales and Victoria concentrate urban outdoor retail channels where premium positioning around microplastic reduction claims commands margin concentration.
Water Purifier Bottle Market Competitive Landscape
On the supply side, the industry is consolidating around established players with dedicated regulatory affairs capacity and backward integration into membrane casting or activated carbon sourcing. Three strategic archetypes dominate: premium adventure-travel specialists leveraging controlled digital distribution, institutional procurement anchors sustaining volume through humanitarian and emergency responder contracts, and hydration system integrators extending component ecosystems from reservoirs into filtration. Competitive moves concentrate on direct-to-consumer channel rotation and subscription-based filter replacement models that displace traditional retail replenishment cycles.
Within the premium-tier vector, GRAYL occupies a position exemplifying high-margin adventure travel segmentation through brand-owned storefronts. LifeStraw anchors the institutional procurement archetype with sustained volume through humanitarian agency and outdoor retail presence. CamelBak sits within the hydration system integration tier, extending shared component ecosystems from reservoirs into filtration bottles. These three represent divergent strategic postures rather than direct substitution, with each archetype capturing distinct customer lifetime value mechanics across recreational, professional, and emergency preparedness contexts.
| Leading Market Players |
|---|
| GRAYL |
| LifeStraw |
| CamelBak |
| Brita |
| Sawyer |
| Aquasana |
| LifeSaver |
| KOR Water |
| Nalgene |
| Others |
Value Network & Pricing Analysis
The Shanghai-to-Rotterdam maritime corridor feeds hollow-fiber membrane and activated carbon feedstock flows that concentrate procurement leverage among Asian contract manufacturers, compressing margins for brands lacking backward integration while enabling certification-based price premiums in German and United Kingdom retail channels.
Pricing Analysis
Certification level creates the primary spread between premium and mass-market tiers, with NSF/ANSI P231 virus-rated systems commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EPA-aligned testing protocols and REACH material compliance rather than raw performance metrics. Pricing pressure stems from subscription filter replacement models that displace traditional retail replenishment cycles and compress per-unit margins. Emergency responder procurement contracts exhibit lowest price sensitivity due to institutional budget security, while everyday household segments in German urban centers drive cost compression through price-comparison platforms.
Supply Chain Analysis
Polyethersulfone membrane casting and coconut shell activated carbon sourcing concentrate in China, South Korea, and Indonesia, with German and Japanese specialty chemical producers retaining niche positions in high-purity grades. Raw material dependencies include microporous hollow-fiber membranes, UV-C LED semiconductor chips, and Tritan copolyester polymer resins. Single-source vulnerability in Asian membrane production creates exposure to logistics chokepoints at the Port of Shanghai and regional regulatory restrictions on chemical exports. Distribution runs through brand-owned digital storefronts and Amazon marketplace presence that displaces traditional outdoor retail wholesale arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are concentrating value capture around subscription-enabled filter replacement ecosystems and shared-component hydration systems that lock in recurring revenue through interoperability rather than discrete product sales.
For Market Incumbents: Build regulatory certification moats through dedicated NSF/ANSI and REACH compliance infrastructure that filters out low-volume competitors. Deepen backward integration into membrane casting or activated carbon sourcing to preempt supply concentration risks from Asian contract manufacturers. Expand direct-to-consumer channel control to capture customer lifetime value previously lost to third-party retail replenishment cycles.
For New Entrants and Emerging Players: Mid-market everyday use applications in United Kingdom urban centers with postcode-level water quality variation represent the most penetrable entry point for uncertified challengers seeking margin before compliance investment. Ultralight UV filter configurations for Pacific Crest Trail and Appalachian Trail thru-hiker communities offer niche volume without institutional procurement barriers. Pursue go-to-market partnerships with specialty outdoor retailers in Colorado and Washington state for experiential merchandising validation.
For Investors and Strategic Acquirers: Specialist membrane technology developers with captive polyethersulfone casting capabilities and established EPA testing relationships present the most defensible acquisition targets in a five-to-ten year consolidation window. Brands with proven subscription mechanics and usage-based filter replacement algorithms signal durable customer lifetime value capture. Watch for state-level PFAS notification threshold expansions as the inflection indicator that will reshape activated carbon formulation demand and certification scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Filter Replacement Model | Recurring revenue capture through automated cartridge replenishment displaces retail-dependent competitors. |
| NSF/ANSI P231 Certification Investment | EPA-aligned virus removal standards open institutional procurement channels for emergency responders. |
| Backward Integration into Membrane Casting | Captive polyethersulfone production mitigates single-source vulnerability from Asian contract manufacturers. |
| Direct-to-Consumer Channel Expansion | Brand-owned storefronts enable data-driven predictive inventory positioning ahead of seasonal demand spikes. |
| PFAS-Expanded Activated Carbon Formulation | State-level per- and polyfluoroalkyl substance regulations drive premium positioning in developed markets. |
Research Methodology
Operator-level perspectives from product development executives at filtration technology developers, regulatory affairs leads managing NSF/ANSI certification timelines, category buyers at REI Co-op and Bass Pro Shops, and supply chain directors overseeing hollow-fiber membrane procurement anchored the qualitative base. Secondary validation drew from EPA microbiological purifier guidelines, EU REACH chemical compliance filings, customs records tracking activated carbon imports, and SEC 10-K disclosures from publicly traded hydration equipment manufacturers. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade association publications and outdoor industry participation surveys.
Scenario-bracketing around regulatory timeline compression and supply chain disruption probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include filtration technology type, application context, distribution channel, and end-user procurement authority. CAGRs were derived from weighted average growth assumptions across these segments, with cross-border certification eligibility and replacement cycle frequency serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in freight rates along the Shanghai-to-Rotterdam corridor or sudden tightening of EPA testing protocols would shift the trajectory. Forecasts reflect documented assumptions about certification timeline stability and membrane supply continuity. Cross-checking against wilderness permit issuance data from Colorado and Oregon state parks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Fan Market
Household Items
Cookware Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Dishwasher Detergent Market
Household Items
United States Barbeque Grill Market
Household Items
Smart Bathroom Market
Household Items
Umbrella Market
Household Items
UK Digital Showers Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Washing Capsules Market
Household Items
India Air Purifier Market
Household Items
Toilet Care Wipes Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
North America Liquid Hand Soap Market
Household Items
China Digital Showers Market