
 Europe & UK Nonstick Cookware Market | 2026-2036
Europe & UK Nonstick Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Europe & UK Nonstick Cookware Market Insights
European nonstick cookware production capacity is rebalancing toward southern Spain and Portugal as energy costs reshape manufacturing economics. Groupe SEB leverages its multi-brand architecture to control shelf space across hypermarket and specialty channels. ZWILLING J.A. Henckels anchors its position through forged-aluminum expertise and chef-endorsed product lines. SCANPAN differentiates via its Danish-made, PFOA-free ceramic-titanium coating systems that command price premiums in Nordic markets.
Europe & UK nonstick cookware comprises kitchen vessels engineered with low-friction surface treatments—typically polytetrafluoroethylene (PTFE), sol-gel ceramic, or anodized aluminum oxide layers applied through spray-coating or roll-bonding processes—to enable fat-reduced cooking and rapid food release in residential and foodservice environments. PTFE frying pans still occupy the largest volume share across mass-market channels, though ceramic-coated saucepans are recording the fastest growth trajectory as health-conscious households reject legacy fluoropolymer chemistries. Cookware sets concentrate margin pools at the premium tier, while grill pans remain a specialized, slower-rotation category dependent on seasonal promotional cycles.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) and the EU F-Gas Regulation are forcing reformulation of conventional nonstick coatings and reshaping import compliance requirements for Asian-origin suppliers. ECHA's ongoing substance evaluations and national regulators in France and Germany are tightening testing protocols for coating durability and thermal degradation. Stakeholders must monitor the regulatory trajectory on PFAS phase-outs and calibrate their material sourcing strategies accordingly.
Market Dynamics
REACH restrictions on PFAS and the EU F-Gas Regulation are forcing coating reformulations across European manufacturing, compressing legacy PTFE supply chains while accelerating ceramic and sol-gel alternatives into commercial kitchens and retail channels.
Growth Catalysts
- Professional kitchen adoption:Commercial chefs in Germany and France are expanding ceramic-coated collections for high-heat performance, validating premium pricing for PFOA-free alternatives in foodservice procurement.
- REACH compliance mandates:ECHA substance evaluations are tightening testing protocols for coating durability, creating certified-supplier advantages for manufacturers with in-house analytical capabilities.
- Energy cost rebalancing:Manufacturing gravity is shifting toward southern Spain and Portugal as electricity differentials reshape foundry and coating facility economics across the continent.
Market Restraints
- Aluminum price volatility:Forged-aluminum substrate costs fluctuate with LME pricing, squeezing margin pools for mid-tier producers without long-term smelter contracts.
- Asian import dependency:Roll-bonding equipment and ceramic precursor chemicals concentrate in Chinese supply bases, exposing European coaters to shipping cost spikes and customs clearance friction.
- Thermal degradation limits:Ceramic coatings crack above 450°C, restricting their deployment in professional searing applications where PTFE still dominates.
Strategic Opportunities
- Portuguese manufacturing expansion:Unused industrial capacity in the Porto corridor offers low-cost coating facility establishment with EU regulatory alignment already built in.
- Induction-compatible base innovation:Magnetic stainless steel bonding to aluminum cores opens replacement cycles in UK households upgrading from gas cooktops.
- F-Gas Regulation tailwind:The EU's phasedown of hydrofluorocarbon propellants in coating application equipment creates first-mover advantage for water-based sol-gel adopters.
Industry Challenges
- Coating chemist scarcity:Formulation expertise in PFAS-free ceramic-titanium systems concentrates in Danish and German R&D clusters, creating recruitment bottlenecks for southern European producers.
- REACH registration timelines:New substance notifications for modified sol-gel precursors require 18-24 month ECHA review cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe & UK Nonstick Cookware Market |
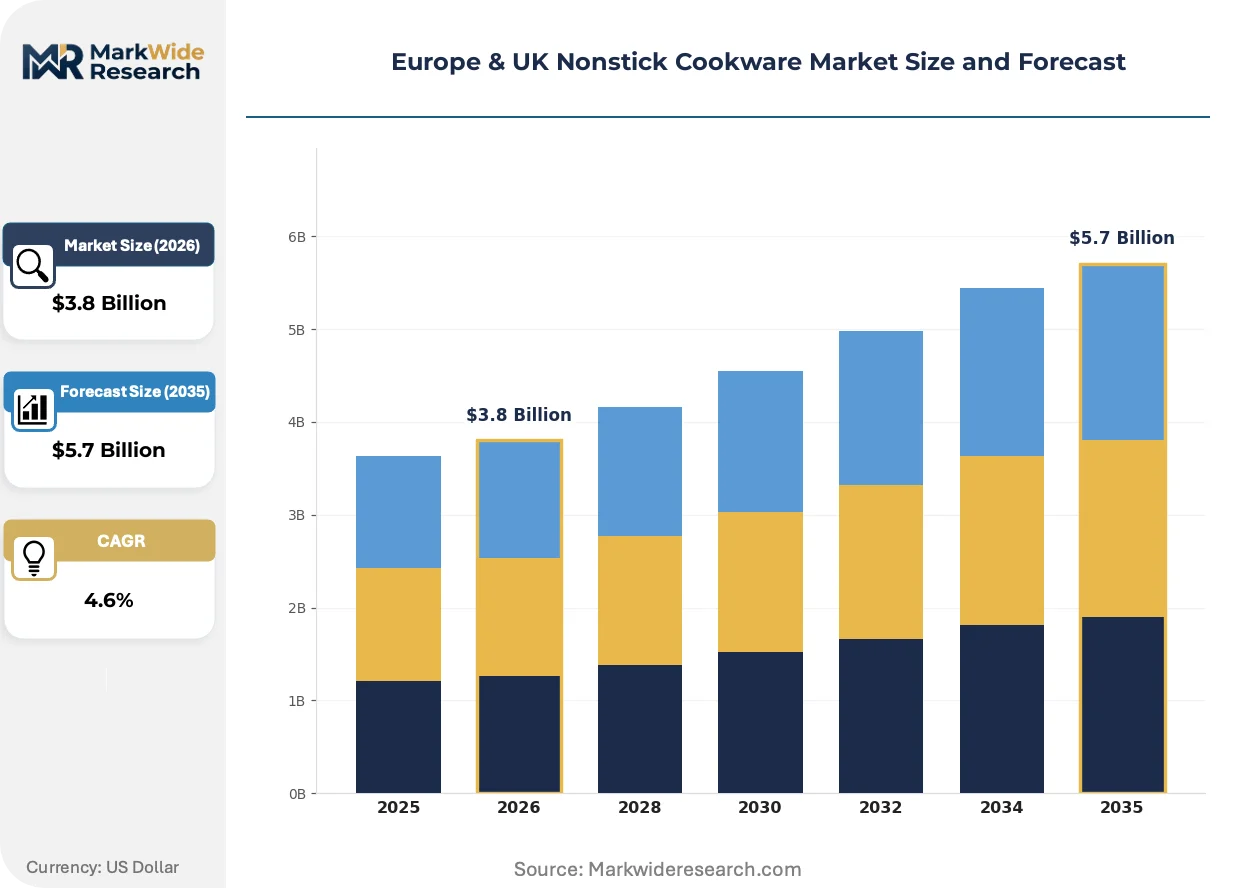
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frying Pans, Cookware Sets, Grill Pans, Saucepans Material: PTFE, Ceramic, Anodized Aluminum, Cast Iron End User: Households, Restaurants, Catering Services, Professional Chefs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Groupe SEB, ZWILLING J.A. Henckels, Meyer Corporation, Fissler GmbH, Newell Brands, SCANPAN, WMF Group, Tramontina, Horwood Homewares, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe & UK Nonstick Cookware Market Trends and Innovations
Coating technology convergence with induction cooktop proliferation and circular economy mandates is reshaping material specifications and end-of-life obligations across European supply chains.
Ceramic-titanium hybrid coatings are absorbing market share in Nordic premium segments as SCANPAN's Danish-made systems demonstrate 50,000-cycle durability. Professional kitchens in Stockholm and Copenhagen specify these collections for health-conscious clientele. The technology is absorbing price premiums that legacy PTFE cannot command, compressing fluoropolymer margins in adjacent tiers.
ECHA's ongoing PFAS restriction proposals under REACH are forcing coating reformulations and raw material substitutions across the continent. Manufacturers face substance evaluation deadlines that invalidate existing supply contracts. France's ANSM and Germany's BfR are accelerating national testing protocols, pushing importers toward certified European coaters.
UK household buyers are shortening replacement cycles for nonstick frying pans as induction cooktop penetration exceeds 60% in new kitchen installations. Retailers are unbundling cookware sets into single-SKU purchases, disrupting traditional margin structures. This pattern concentrates in London and southeast England housing stock renovations.
Europe & UK Nonstick Cookware Market Segmentation
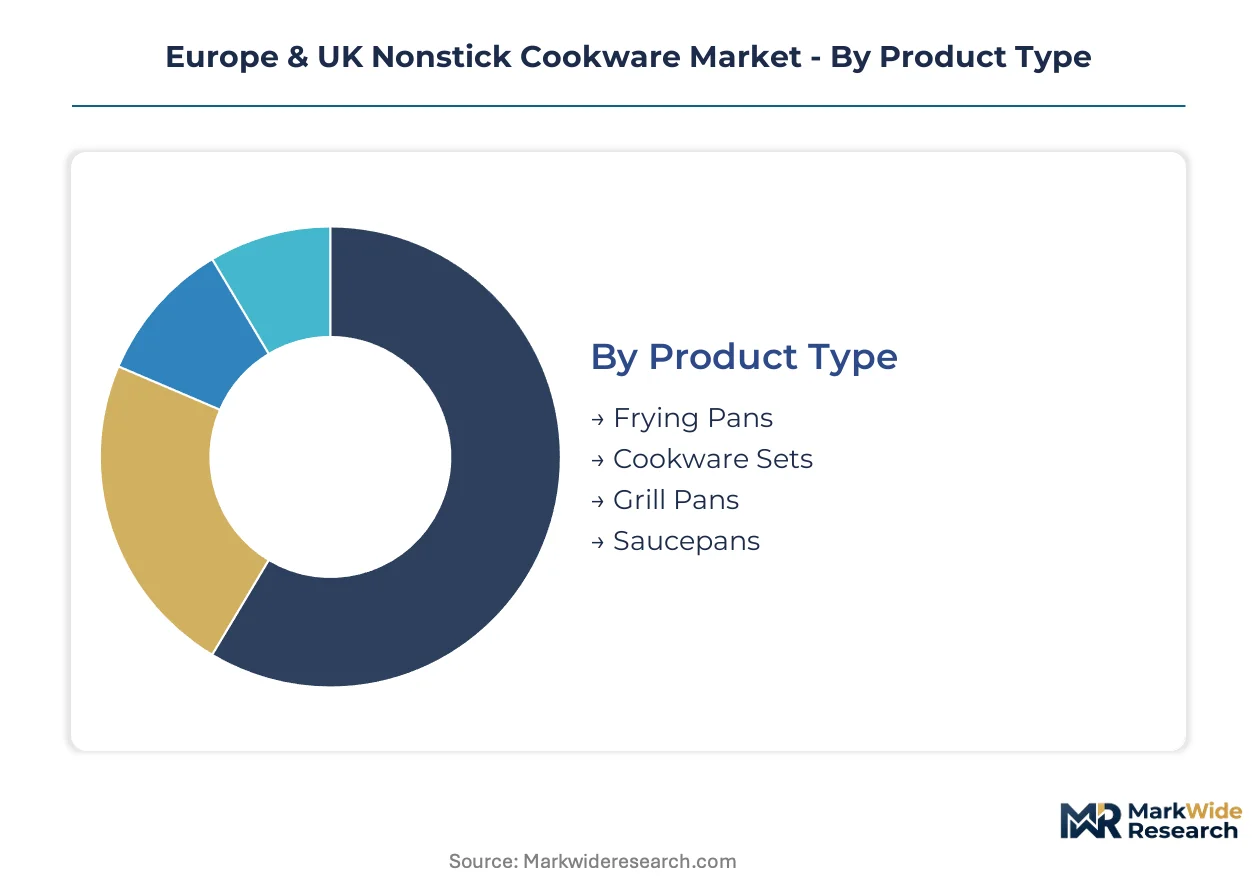
Nonstick cookware segmentation in Europe and the UK reveals divergent purchasing logics across residential and commercial environments. Material chemistry and distribution channel selection determine margin capture and regulatory compliance pathways for manufacturers.
Product Type:
Frying pans function as standalone replacement purchases, while cookware sets embed multiple vessel types into coordinated kitchen systems.
- Frying Pans:PTFE-coated skillets dominate mass-market volume through hypermarket channels in France and Germany. ECHA's PFAS evaluation timelines are accelerating ceramic substitution in UK household replacement cycles.
- Cookware Sets:Premium tier concentration occurs in Lyon's kitchenware cluster, where forged-aluminum construction with ceramic-titanium coatings commands price premiums. Professional procurement in Parisian foodservice validates multi-piece configurations.
- Grill Pans:Seasonal promotional dependency in Iberian retail channels.
- Saucepans:Sol-gel ceramic variants recording steepest expansion trajectory in Nordic health-conscious segments.
Frying pans lead volumes today; saucepans are climbing the fastest.
Material:
Coating chemistry separates embedded supply chains from reformulation-flexible sourcing strategies.
- PTFE:Legacy fluoropolymer coatings face REACH substance evaluation deadlines. German and French regulators are tightening thermal degradation testing protocols, invalidating existing Asian import contracts.
- Ceramic:Sol-gel and ceramic-titanium systems absorb share in commercial kitchens across Stockholm and Copenhagen. SCANPAN's Danish manufacturing demonstrates 50,000-cycle durability that PTFE cannot match.
- Anodized Aluminum:Hard-anodized oxide layers serve induction-compatible base requirements in UK housing renovations.
- Cast Iron:Enamel-coated variants occupy niche premium positioning in specialty retail.
PTFE retains volume leadership; ceramic coatings are gaining share fastest.
End User:
Procurement authority separates household discretionary purchasing from institutional specification requirements.
- Households:Induction cooktop penetration exceeding 60% in southeast England is shortening replacement cycles. London retailers are unbundling cookware sets into single-SKU purchases.
- Restaurants:High-heat searing applications in Berlin and Munich commercial kitchens still specify PTFE where ceramic thermal limits restrict deployment.
- Catering Services:Volume procurement concentrates through Portuguese manufacturing corridors with EU regulatory alignment.
- Professional Chefs:Chef-endorsed product lines from German R&D clusters validate premium pricing for PFOA-free alternatives in foodservice procurement.
Households drive absolute volume; professional chefs are expanding ceramic adoption most rapidly.
Distribution Channel:
Channel selection determines margin capture and certification visibility for coating compliance.
- Online Retail:UK e-commerce penetration concentrates replacement purchases in unbundled single-SKU patterns. Amazon and Ocado logistics favor lightweight ceramic-coated shipments.
- Supermarkets:Hypermarket shelf space in France remains controlled by multi-brand architectures. Carrefour and Auchan channels favor established PTFE volumes.
- Specialty Stores:Lyon's premium kitchenware cluster and Copenhagen design retailers showcase ceramic-titanium systems with durability certifications.
- Direct Sales:Restaurant supply contracts in Germany bypass retail markup through manufacturer-direct procurement.
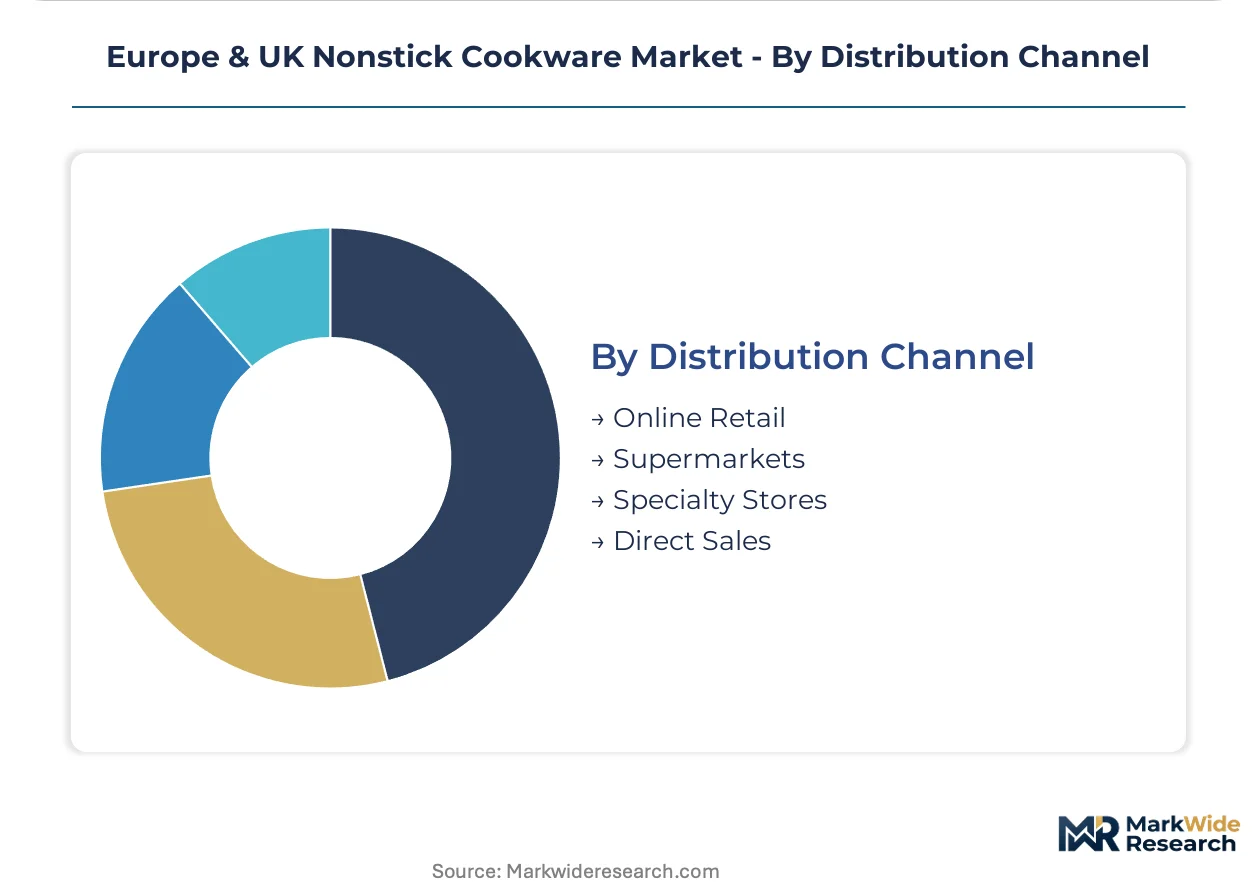
Supermarkets maintain volume dominance; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity is migrating toward southern Europe as energy cost differentials widen the regulatory-arbitrage gap between legacy northern foundries and Iberian coating facilities.
Germany
Commercial kitchens in Berlin and Munich drive specification-grade ceramic adoption for health-conscious foodservice procurement. The BfR tightens thermal degradation testing protocols for PTFE alternatives, invalidating uncertified Asian import contracts. Bavaria's industrial corridor hosts R&D clusters where coating chemists concentrate formulation expertise.
France
Premium kitchenware demand concentrates in Paris and Lyon's design-conscious household segments. ANSM accelerates national testing protocols for PFAS-free coating durability beyond baseline REACH requirements. The Auvergne-Rhône-Alpes cluster anchors forged-aluminum production for chef-endorsed product lines.
United Kingdom
Southeast England housing renovations shorten replacement cycles as induction cooktop penetration exceeds sixty percent. London retailers unbundle cookware sets into single-SKU purchases, disrupting traditional margin structures. Midlands distribution hubs channel lightweight ceramic-coated shipments through Amazon and Ocado logistics networks.
Spain
Unused industrial capacity in the Porto corridor attracts coating facility establishment with EU regulatory alignment already embedded. Spanish electricity differentials reshape foundry economics versus northern European competitors. Andalusian assembly plants serve Iberian retail channels with seasonal promotional dependency.
Denmark
SCANPAN's domestic manufacturing demonstrates fifty-thousand-cycle ceramic-titanium durability that commands Nordic price premiums. Copenhagen design retailers showcase certified systems to health-conscious professional kitchens. Danish R&D clusters concentrate scarce formulation expertise in PFAS-free coating systems.
Europe & UK Nonstick Cookware Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic-specialist positioning and regional manufacturing arbitrage. The vendor base stratifies across multi-brand conglomerates, forged-aluminum specialists, and coating-technology innovators. Three archetypes dominate: integrated manufacturers with captive foundry capacity, brand licensors leveraging third-party production, and R&D-intensive coating formulators. Competitive moves concentrate on Portuguese manufacturing expansion and induction-compatible base innovation.
Among French-based conglomerates, Groupe SEB exemplifies multi-brand architecture control across hypermarket and specialty channels. German fabricators ZWILLING J.A. Henckels and Fissler GmbH occupy positions within the forged-aluminum expertise tier, anchoring chef-endorsed validation for premium pricing. SCANPAN represents the coating-technology archetype through Danish-made ceramic-titanium systems that absorb price premiums in Nordic markets.
| Leading Market Players |
|---|
| Groupe SEB |
| ZWILLING J.A. Henckels |
| Meyer Corporation |
| Fissler GmbH |
| Newell Brands |
| SCANPAN |
| WMF Group |
| Tramontina |
| Horwood Homewares |
| Others |
Pricing and Supply Chain Analysis
Coating chemist scarcity in Danish and German R&D clusters widens the labor-cost differential between northern European formulation centers and Iberian assembly plants, compressing margin spreads between premium ceramic-titanium systems and mid-tier sol-gel alternatives.
Pricing Analysis
Distributor margin layers in French hypermarket channels absorb the widest spreads between factory gate and shelf price, while direct-to-foodservice contracts in Berlin and Munich bypass retail markup entirely. Three-tier pricing structure across premium, standard, and economy levels separates SCANPAN's certified ceramic-titanium collections from Portuguese-assembled sol-gel lines and mass-market PTFE imports. Price differentiation rests on REACH certification tier and chef endorsement validation. Cost compression in the mid-tier is intensifying because aluminum substrate volatility squeezes producers without long-term smelter contracts. Household buyers in UK online channels demonstrate highest price sensitivity; professional chefs in Nordic markets show lowest sensitivity due to durability requirements.
Supply Chain Analysis
Regional distribution centers in the Midlands and Lyon corridor operate hub-and-spoke patterns that channel lightweight ceramic-coated shipments through Amazon and Ocado logistics networks. Manufacturing concentrates in Denmark, Germany, and Portugal, with assembly drawing from Chinese roll-bonding equipment and ceramic precursor chemical sources. Raw material dependencies include LME-traded aluminum, sol-gel silica precursors, and titanium dioxide nanoparticles. Single-source vulnerability concentrates in Asian ceramic chemical supply bases. Distribution runs through supermarket shelf-space allocation in France, specialty design retailers in Copenhagen, and unbundled single-SKU online purchases in southeast England.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portuguese electricity differentials against German industrial rates create a geographic-arbitrage foundation for coating facility relocation, with EU regulatory alignment already embedded in Iberian industrial zones.
For Market Incumbents: Anticipate REACH substance evaluation deadlines invalidating existing Asian import contracts by accelerating in-house analytical capability investments. Defend market position through backward integration into Porto corridor coating capacity and exclusive chef endorsement contracts that validate premium pricing for PFOA-free alternatives. For New Entrants and Emerging Players: The price-point gap between SCANPAN's Nordic premium collections and mass-market PTFE imports offers white-space entry through mid-tier ceramic-titanium positioning. Target Portuguese manufacturing establishment with EU regulatory alignment already built in. Penetrate UK online retail channels through lightweight ceramic-coated SKUs optimized for Amazon and Ocado logistics. For Investors and Strategic Acquirers: Private equity firms with consumer goods portfolios are the most active acquirer in this space, consolidating fragmented mid-tier producers. Long-term viability over a five-to-ten year horizon favors coating-technology innovators with captive formulation expertise. Target acquisition archetype: Portuguese-based assemblers with unused industrial capacity and REACH-compliant supply chains. Watch ECHA's PFAS restriction timeline as the signal for ceramic substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Portuguese Manufacturing Expansion | Unused Porto corridor capacity offers low-cost EU-aligned coating facility establishment. |
| Backward Integration into Sol-Gel Precursors | In-house precursor formulation bypasses Asian chemical dependency and REACH registration delays. |
| Induction-Compatible Base Innovation | Magnetic stainless steel bonding captures UK household upgrade cycles from gas cooktops. |
| Chef Endorsement Contracting | Professional kitchen validation in Berlin and Munich sustains premium pricing for PFOA-free lines. |
| Water-Based Sol-Gel Transition | F-Gas Regulation phasedown creates first-mover advantage over hydrofluorocarbon-dependent competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating chemists, hypermarket category buyers, restaurant procurement managers, and Portuguese plant managers with secondary validation against ECHA substance evaluation databases, EU customs trade records, and SEC filings from listed cookware conglomerates. Bottom-up demand modeling and top-down supply capacity estimates were triangulated.
Segment-weighting approaches distributed value and volume across product type, material chemistry, end-user category, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis against induction cooktop penetration rates, REACH compliance cost trajectories, and aluminum price volatility indices.
Caveats apply where ECHA PFAS restriction timelines, energy cost differentials, or ceramic coating thermal degradation limits could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Residential Air Purifiers Market
Household Items
Portable Steamers Market
Household Items
Bristle Brush Market
Household Items
Smart Drying Racks Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Europe Hand Dryers Market
Household Items
Candle Air Fresheners Market
Household Items
China Digital Showers Market
Household Items
Copper Water Bottle Market
Household Items
Permanent Marker Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Water Purifier Market
Household Items
India Non-Stick Cookware Market
Household Items
Smart Spin Mop Market
Household Items
Portable Humidifiers Market
Household Items
Portable Vacuum Cleaner Market