
 Japan Digital Showers Market | 2026-2036
Japan Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital Showers Market Insights
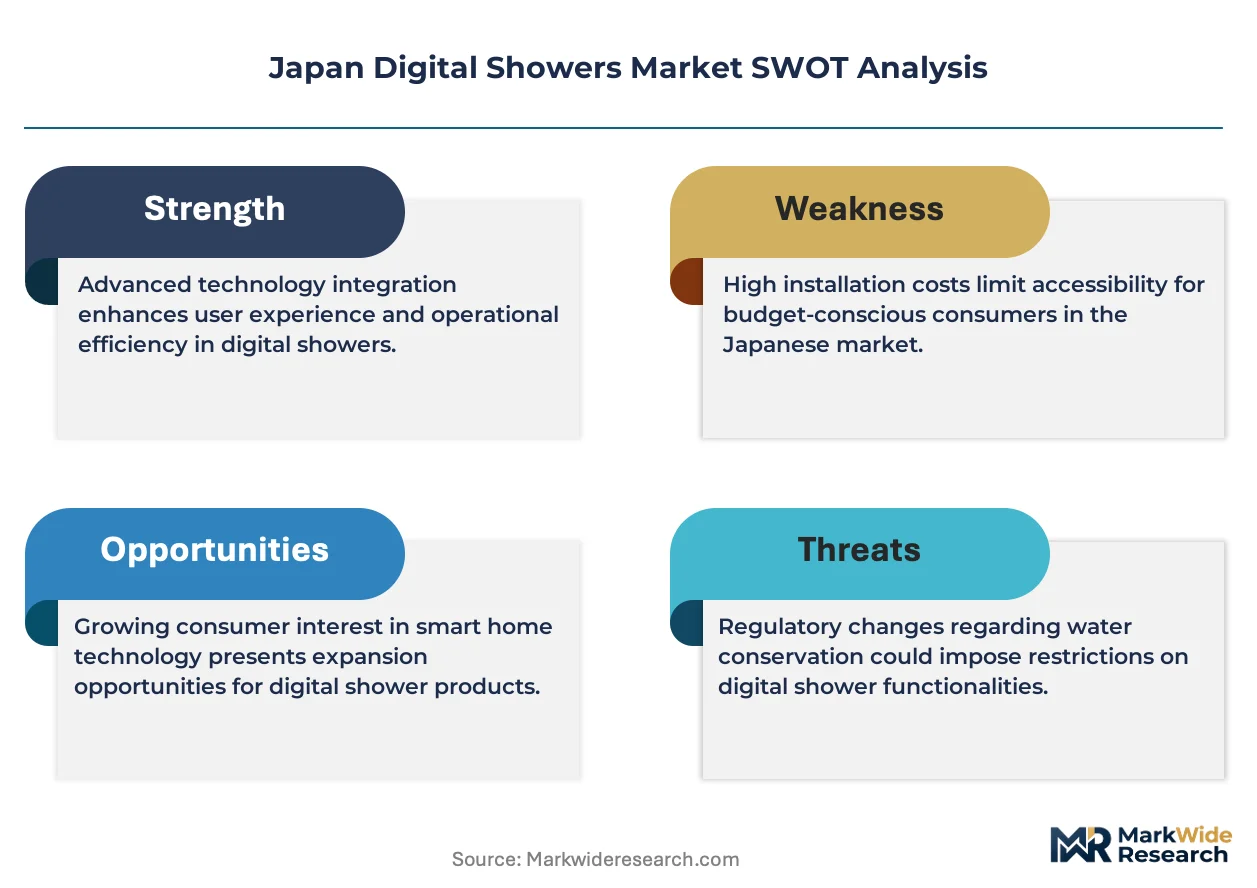
Premium-grade thermostatic precision is rotating the Japan digital showers market toward specification-intensive contracts. TOTO Ltd leverages its captive ceramics and electronics supply chain to dominate integrated system development. LIXIL Corporation sustains channel control through exclusive partnerships with Japan's largest homebuilder networks. Panasonic Corporation anchors its position via R&D intensity in wireless connectivity modules for bathroom environments.
Japan digital showers comprise electronically controlled water delivery systems that regulate temperature within 0.5 degrees Celsius, manage flow rates through solenoid valves, and enable remote operation via Bluetooth or home automation protocols. These systems serve both water conservation mandates and user experience customization in residential and commercial wet spaces. Smart showers command the dominant revenue position due to their embedded sensor arrays and app compatibility, while retrofit showers represent the fastest expansion vector as aging housing stock undergoes bathroom modernization. Digital controls concentrate margin pools because proprietary interface software creates switching costs for both installers and end users.
METI energy-efficiency guidelines, JIS standards for plumbing fixtures, and the Ministry of Health, Labour and Welfare's sanitation codes collectively shape product certification requirements and installation protocols across Japan. Compliance with these frameworks determines market access for both domestic manufacturers and imported systems. Stakeholders must monitor evolving interoperability standards between digital shower controllers and broader home energy management platforms.
Market Dynamics
Water efficiency mandates from METI are compressing installation timelines and forcing manufacturers to redesign valve architectures for sub-6-liter-per-minute flow compliance. This regulatory pressure cascades through specification chains, privileging suppliers with captive ceramics and electronics integration capabilities.
Growth Catalysts
- Hotel refurbishment cycles:Luxury properties in Tokyo and Osaka are specifying voice-activated shower systems as standard amenities, creating specification pull-through into adjacent residential segments.
- METI efficiency standards:Mandatory household water efficiency benchmarks are disqualifying mechanical mixer valves from new construction tenders, accelerating digital adoption curves.
- Greater Tokyo high-rise density:Kanto region residential developments concentrate demand for space-optimized, app-controlled bathroom systems with centralized building management integration.
Market Restraints
- Copper and rare-earth input volatility:Solenoid valve production depends on concentrated Chilean copper supply and Chinese rare-earth processing, exposing margin structures to commodity shocks.
- Retrofit installation complexity:Aging Japanese housing stock requires extensive plumbing reconfiguration to accommodate digital shower electronics, extending sales cycles and contractor training burdens.
- Mechanical valve residual preference:Traditional thermostatic mixers retain installer familiarity and lower upfront cost positioning in rural prefectures outside major metropolitan corridors.
Strategic Opportunities
- Kansai secondary city expansion:Osaka, Kyoto, and Kobe municipal housing renewal programs present underpenetrated demand for mid-tier digital shower retrofits with simplified installation protocols.
- Home energy management convergence:Integration between shower controllers and residential solar-battery systems creates cross-selling opportunities through electrical contractor channels.
- Ministry of Health, Labour and Welfare sanitation code updates:Anticipated revisions to hygiene standards for multi-unit dwellings will mandate antimicrobial surface specifications, favoring suppliers with integrated ceramics capabilities.
Industry Challenges
- Certified plumber scarcity:JIS-compliant digital shower installation requires licensed technicians with electrical and plumbing dual competencies, creating bottleneck conditions in rural prefectures.
- Legacy building management protocol fragmentation:Proprietary communication standards across Japanese condominium automation systems force manufacturers to maintain multiple controller firmware variants, elevating support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital Showers Market |
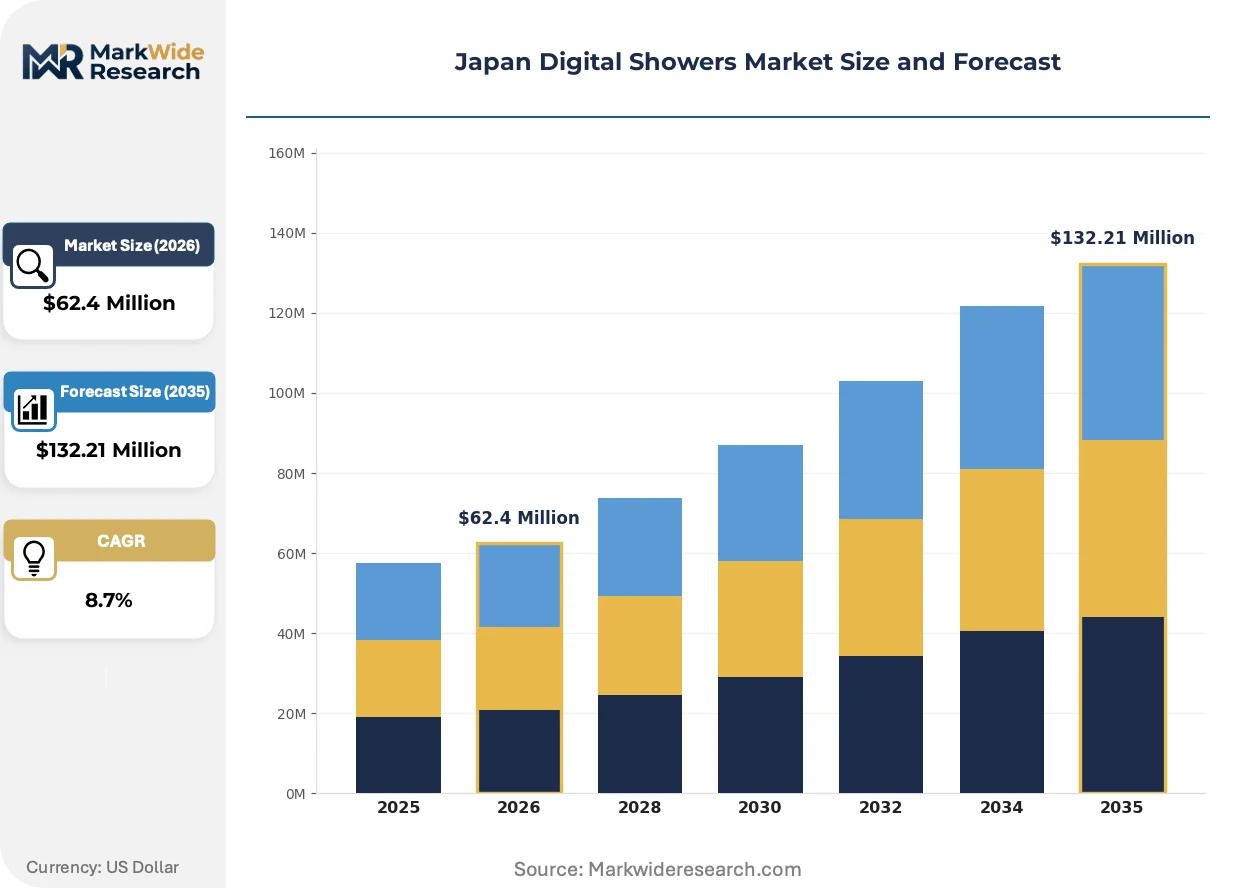
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $132.21 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showers, Retrofit Showers, Shower Panels, Digital Controls Technology: Temperature Control, Water Flow Management, Wireless Connectivity, Voice Activation End User: Residential, Commercial, Hospitality, Spa Facilities Installation Type: Wall-Mounted, Ceiling-Mounted, Free-Standing, Integrated Systems |
| Companies Covered | TOTO Ltd, LIXIL Corporation, Panasonic Corporation, Hitachi Global Life Solutions, Mitsubishi Electric Corporation, Toshiba Corporation, Sharp Corporation, Grohe AG, Kohler Co, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital Showers Market Trends and Innovations
Wireless connectivity architectures are fragmenting competitive positioning across the Japan digital showers market. Three distinct trajectories are compressing traditional hardware margins while opening service-layer revenue pools.
Sensor-array technology is fragmenting product differentiation strategies. Multi-point temperature and flow sensors enable real-time consumption analytics and leak detection. High-rise developers in Yokohama and Chiba are specifying these systems for building-level water monitoring. The technology is fragmenting vendor competitive sets into hardware specialists versus platform-integrated providers.
METI's 2024 revision to household appliance efficiency labeling requirements is tightening test protocols for digital shower controllers. Manufacturers must now submit third-verified flow-rate accuracy data across variable inlet pressure conditions. Premium system developers with captive calibration facilities are absorbing compliance costs more efficiently than import-dependent competitors.
Direct-to-developer specification contracting is displacing traditional wholesale distribution for new construction volumes. Major homebuilders in Saitama and Kanagawa prefectures are consolidating procurement through exclusive supply agreements with integrated bathroom system vendors. This channel compression is most visible in tower condominium projects exceeding 200 units, where standardized controller specifications reduce on-site commissioning complexity.
Japan Digital Showers Market Segmentation
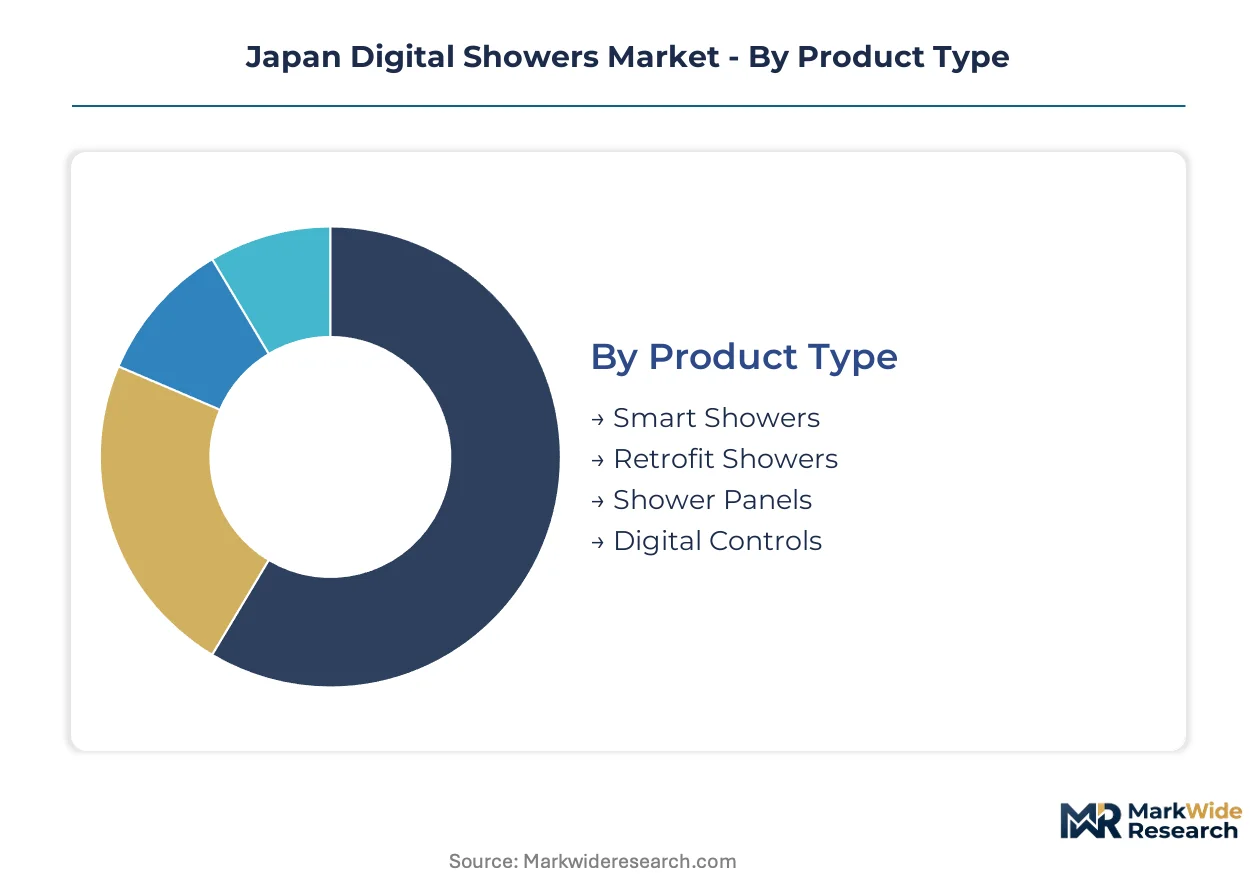
Segmentation in the Japan digital showers market tracks how regulatory pressure from METI and JIS standards fragments product development priorities. Each dimension reveals distinct compliance burdens and specification pathways that determine competitive viability across Tokyo's high-rise corridor and regional retrofit markets.
Product Type:
METI water-efficiency labeling requirements create divergent certification costs across product architectures, privileging systems with integrated sensor arrays over modular add-ons.
- Smart Showers:Embedded temperature sensors, solenoid valve arrays, and Bluetooth-enabled controllers regulate flow within 0.5-degree precision. Luxury hotel chains in Tokyo and Osaka specify these as standard amenities, pulling demand through adjacent residential segments. Smart showers handle the majority of throughput; retrofit showers are the fastest mover on share.
- Retrofit Showers:Modular controller units designed for existing plumbing infrastructure with minimal wall-opening requirements. Aging housing stock in Greater Tokyo's suburban prefectures drives concentrated demand as bathroom modernization accelerates.
- Shower Panels:Integrated wall-mounted units combining multiple spray heads with centralized digital interfaces. Simplified installation protocols appeal to Kansai municipal housing renewal programs.
- Digital Controls:Standalone controller modules enabling remote operation via home automation protocols. Proprietary interface software creates switching costs that concentrate margin pools for established suppliers.
Smart showers absorb the bulk of R&D investment; retrofit configurations expand most quickly as contractor training programs mature.
Technology:
Cost tier differentiation separates premium sensor-integrated systems from basic electromechanical alternatives, with wireless modules commanding substantial price premiums.
- Temperature Control:Thermostatic mixing valves with real-time feedback loops maintain set points across variable inlet pressure. High-rise developers in Yokohama and Chiba specify multi-point sensor arrays for building-level water monitoring.
- Water Flow Management:Solenoid-actuated flow restrictors achieving sub-6-liter-per-minute compliance with METI mandates. These systems dominate new construction tenders where mechanical mixers face disqualification.
- Wireless Connectivity:Bluetooth and Wi-Fi modules enabling app-based scheduling and consumption analytics. Integration with residential solar-battery systems creates cross-selling opportunities through electrical contractor channels.
- Voice Activation:Natural language processing controllers compatible with major home automation ecosystems. Luxury properties deploy these for guest experience differentiation, though rural prefectures show limited installer familiarity.
Temperature control anchors baseline compliance; voice activation is climbing the fastest as hospitality specification cycles accelerate.
End User:
Application-specific durability and sanitation requirements fragment product specifications across installation environments.
- Residential:Single-family and multi-unit dwellings prioritizing water conservation and user customization. Kanto region high-rise density concentrates demand for space-optimized, app-controlled systems.
- Commercial:Office buildings and mixed-use developments requiring centralized building management integration. Standardized controller specifications reduce on-site commissioning complexity in tower projects.
- Hospitality:Hotels and ryokan properties demanding antimicrobial surface specifications and guest-facing interface simplicity. Anticipated Ministry of Health, Labour and Welfare code revisions will tighten hygiene mandates for multi-unit dwellings.
- Spa Facilities:Wellness centers and onsen-adjacent properties requiring specialized hydrotherapy configurations. Premium pricing tolerance supports advanced sensor-array deployments.
Residential installations generate the highest volume; hospitality represents the steepest expansion trajectory as refurbishment cycles intensify.
Installation Type:
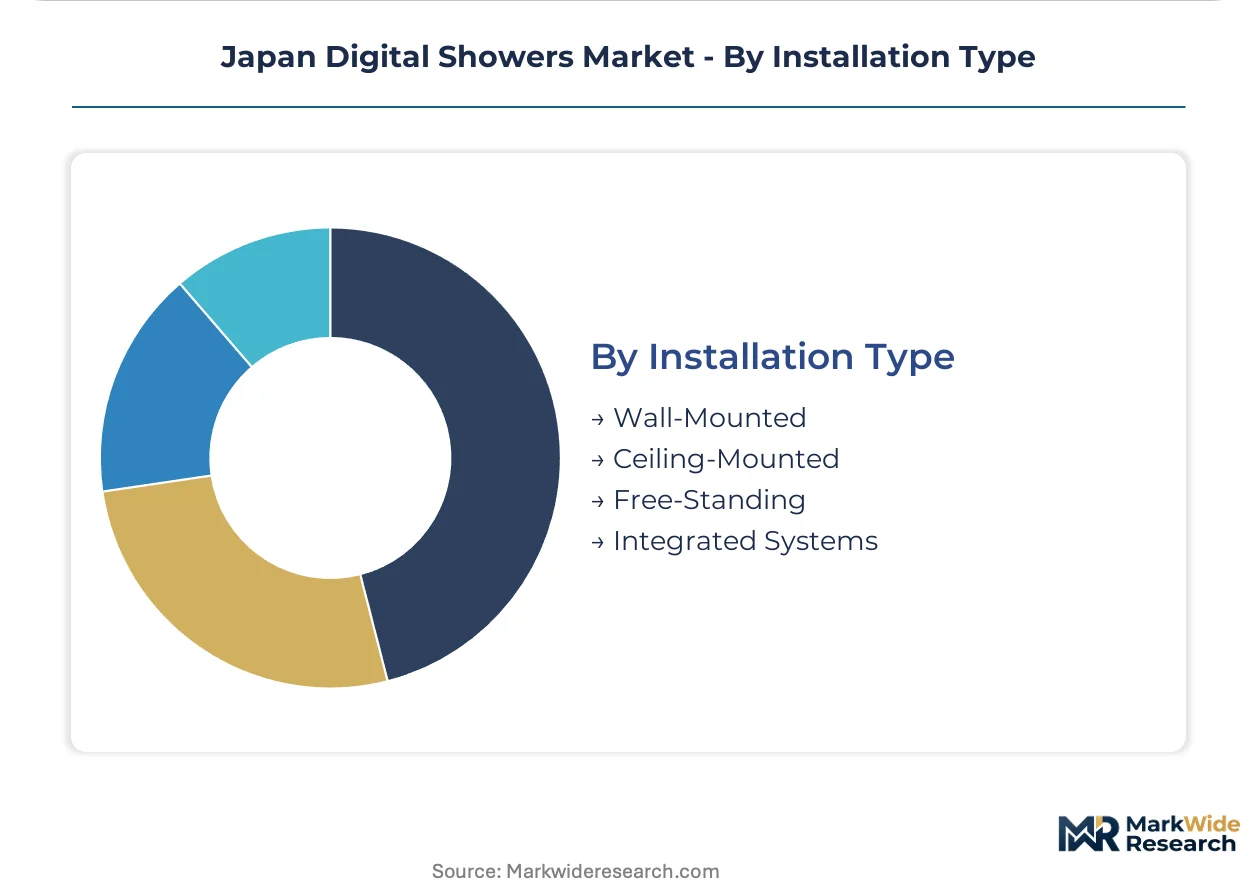
Volume concentration in new construction favors integrated systems, while retrofit activity sustains demand for adaptable mounting configurations.
- Wall-Mounted:Standard recessed or surface-mounted controllers compatible with conventional bathroom layouts. Dominates replacement demand in aging housing stock across Osaka, Kyoto, and Kobe.
- Ceiling-Mounted:Overhead rain shower configurations with hidden plumbing infrastructure. Tower condominium projects exceeding 200 units favor these for aesthetic minimalism and reduced fixture visibility.
- Free-Standing:Portable or semi-permanent units for temporary installations and renovation staging. Limited penetration outside commercial staging applications.
- Integrated Systems:Complete wet-room solutions combining digital controls with captive ceramics and enclosure systems. Direct-to-developer contracting in Saitama and Kanagawa prefectures consolidates procurement through exclusive supply agreements.
Wall-mounted configurations retain the largest installed base; integrated systems are gaining share fastest as homebuilder consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's digital showers market operates as a net importer of copper and rare-earth components while exporting finished integrated bathroom systems to Southeast Asian markets. Trade flows concentrate through Yokohama and Osaka ports, with domestic value addition rising as METI efficiency mandates deepen local manufacturing requirements.
Kanto/Tokyo
Greater Tokyo's high-rise residential pipeline drives concentrated demand for ceiling-mounted integrated systems with building management integration. METI household water efficiency standards disqualify mechanical mixers from new construction tenders in Saitama and Kanagawa prefectures. Tower condominium projects exceeding 200 units in Yokohama consolidate procurement through exclusive supply agreements with integrated system vendors.
Kansai/Osaka
Luxury hotel refurbishment cycles in Osaka, Kyoto, and Kobe create specification pull-through for voice-activated shower systems. Municipal housing renewal programs in these secondary cities present underpenetrated demand for mid-tier retrofit configurations. Osaka-based homebuilder networks sustain channel control through exclusive partnerships with captive ceramics suppliers.
Chubu/Nagoya
Industrial automation heritage in Aichi and Gifu prefectures supports precision valve manufacturing for digital shower controllers. JIS standards for plumbing fixtures shape local certification requirements and installation protocols. Nagoya's automotive supply chain expertise transfers into solenoid valve production for sub-6-liter-per-minute flow compliance systems.
Kyushu
Fukuoka's growing tech sector generates residential demand for app-controlled bathroom systems with solar-battery integration. Certified plumber scarcity creates bottleneck conditions for digital shower installation across rural prefectures. Local electrical contractor channels expand through cross-selling opportunities with residential energy management platforms.
Hokkaido
Tourism infrastructure investment in Sapporo and Niseko drives hospitality specification for antimicrobial surface systems. Anticipated Ministry of Health, Labour and Welfare sanitation code revisions will tighten hygiene mandates for multi-unit dwellings. Cold climate adaptations in thermostatic precision systems differentiate regional product requirements from southern markets.
Japan Digital Showers Market Competitive Landscape
Concentration sits with integrated bathroom system developers possessing captive ceramics and electronics capabilities. Three domestic conglomerates anchor market structure through backward integration into valve manufacturing and wireless connectivity modules. Strategic moves center on exclusive homebuilder supply agreements and direct-to-developer specification contracting for tower condominium volumes.
Within the integrated system tier, TOTO Ltd, LIXIL Corporation, and Panasonic Corporation exemplify divergent competitive positioning. TOTO Ltd leverages its captive ceramics supply chain to dominate specification-intensive contracts. LIXIL Corporation sustains channel control through exclusive partnerships with Japan's largest homebuilder networks. Panasonic Corporation anchors its position via R&D intensity in wireless connectivity modules for bathroom environments.
| Leading Market Players |
|---|
| TOTO Ltd |
| LIXIL Corporation |
| Panasonic Corporation |
| Hitachi Global Life Solutions |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Sharp Corporation |
| Grohe AG |
| Kohler Co |
| Others |
Pricing and Supply Chain Analysis
METI water-efficiency labeling requirements gate both supply qualification and price differentiation simultaneously, privileging manufacturers with captive calibration facilities while compressing margins for import-dependent competitors. JIS-compliant certification tiers stratify the market into specification-intensive contracts for integrated system vendors and commodity-positioned modular controllers.
Pricing Analysis
Luxury hotel chains anchor premium pricing for voice-activated shower systems with embedded sensor arrays and app compatibility. Price differentiation separates systems with third-verified flow-rate accuracy data from basic electromechanical alternatives. Cost compression in mid-tier retrofit configurations is intensifying because certified plumber scarcity extends installation timelines and contractor training burdens. Municipal housing renewal programs in secondary cities exhibit highest price sensitivity; hospitality specification cycles show lowest.
Supply Chain Analysis
Chile and China anchor copper concentrate and rare-earth processing for solenoid valve production. Component sourcing draws from Taiwanese semiconductor foundries for wireless connectivity modules and Aichi prefecture precision manufacturers for thermostatic mixing assemblies. Single-source vulnerability concentrates in Chinese rare-earth processing for neodymium-based actuator magnets. Distribution runs through exclusive supply agreements with Japan's largest homebuilder networks and direct-to-developer specification contracting for tower condominium volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with service-layer specialization as hospitality refurbishment cycles and municipal housing renewal programs create divergent specification niches. Demand-side shift toward building management integration in high-rise developments fragments competitive sets between hardware specialists and platform-integrated providers.
For Market Incumbents: Fortify backward integration into ceramics and electronics to absorb METI compliance costs more efficiently than import-dependent competitors. Deepen exclusive partnerships with Saitama and Kanagawa homebuilder networks to lock in tower condominium procurement. Counter threat from electrical contractor channel expansion by accelerating R&D intensity in wireless connectivity modules for solar-battery integration. For New Entrants and Emerging Players: Post-installation analytics and predictive maintenance services represent under-served white space where incumbents focus on hardware margins. Target Kansai secondary city municipal housing renewal programs for mid-tier retrofit configurations with simplified installation protocols. Pursue go-to-market angle through cross-selling with residential energy management platforms in Fukuoka's growing tech sector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated system development as METI efficiency mandates deepen local manufacturing requirements. Long-term viability favors acquisition targets with captive ceramics capabilities and exclusive homebuilder network access. Watch signal of Ministry of Health, Labour and Welfare sanitation code revisions tightening antimicrobial surface specifications as inflection indicator for integrated bathroom system consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramics | METI compliance cost absorption privileges manufacturers with captive supply chains over import-dependent competitors. |
| Exclusive Homebuilder Partnership | Direct-to-developer contracting in Saitama and Kanagawa prefectures locks in tower condominium volume procurement. |
| Wireless Module R&D Expansion | Integration with residential solar-battery systems opens cross-selling through electrical contractor channels in Kyushu. |
| Retrofit Installation Simplification | Modular controller protocols address certified plumber scarcity bottleneck conditions across rural prefectures. |
| Antimicrobial Surface Certification | Anticipated Ministry of Health, Labour and Welfare code revisions favor suppliers with integrated ceramics capabilities. |
Research Methodology
A spread of perspectives from product development executives at integrated bathroom system manufacturers, regulatory affairs specialists at METI and JIS standards bodies, procurement managers at luxury hotel chains, licensed plumbing contractors in Greater Tokyo, and building management system engineers converged on the working assumptions. Secondary validation drew from METI appliance efficiency labeling disclosures, JIS plumbing fixture certification databases, homebuilder capex announcements, and customs records for copper and rare-earth import flows. Bottom-up unit economics triangulated against top-down construction permit data across the analysis window.
Segmentation dimensions modeled include product type architecture, technology integration level, end-user application environment, and installation configuration complexity. CAGRs derived from installed base evolution, replacement cycle compression, and new construction specification penetration across the projection horizon. Forecast inputs incorporated METI regulatory revision timelines, high-rise development pipeline data from Saitama and Kanagawa prefectures, and hospitality refurbishment cycle intensity in Osaka and Kyoto.
Underlying assumptions cover regulatory compliance trajectory, copper and rare-earth price stability, and certified technician training program expansion, with deviation risk concentrated in commodity input volatility and legacy building management protocol fragmentation. Recalibration cycles align with material shifts in METI efficiency standards and Ministry of Health, Labour and Welfare sanitation code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Pocket Tissues Market
Household Items
Brush Cover Market
Household Items
US Flashlights Market
Household Items
Paper Towel Dispenser Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Cutlery Steel Market
Household Items
Home Use Air Purifiers Market
Household Items
Dishwasher Tablets Market
Household Items
Toilet Hygiene Products Market
Household Items
Nebulizing Diffuser Market
Household Items
Facial Tissue Paper Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Hands-Free Faucet Market
Household Items
Sleeping Pillow Market
Household Items
US Air Purifier Market