
 Smart Toilet Market | 2026-2036
Smart Toilet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Toilet Market Intelligence
The expansion into the commercial and hospitality sectors is recalibrating the smart toilet market's traditional focus on residential applications. Japanese manufacturer TOTO dominates the high-end segment with its deep brand equity and technological innovation. In contrast, Kohler leverages its extensive global distribution network to reach both residential and commercial projects. Geberit specializes in concealed systems and wall-hung solutions, differentiating its offerings in the European market.
A smart toilet is an advanced plumbing fixture that integrates electronic bidet functions with automated features like heated seats, air dryers, and self-cleaning mechanisms. These units often incorporate sensor technology for hands-free operation, utilizing proximity sensors to control the lid and flushing functions. Integrated bidet toilets command the premium price points, while washlet-style add-on seats offer a lower-cost entry point. The residential end-user segment remains the largest by volume, but the hospitality sector represents the fastest-growing application due to its focus on luxury amenities.
Product compliance is governed by a matrix of regional standards, including FCC regulations in the United States for electronic emissions and CE marking in Europe for safety and health requirements. Water efficiency mandates, such as the EPA's WaterSense program, also influence product design and market access in North America. Navigating the patchwork of electrical safety, water conservation, and data privacy rules is a critical challenge for manufacturers seeking to expand their geographic footprint.
Market Dynamics
The convergence of IoT-based health monitoring with advanced plumbing fixtures is the central force shaping the smart toilet market. This evolution transforms the product from a luxury convenience item into a proactive wellness tool, attracting investment from both the high-end hospitality and health-conscious residential sectors globally.
Growth Catalysts
- IoT Connectivity:Integration with home automation platforms and mobile health applications expands functionality beyond basic hygiene, creating new value propositions for tech-savvy consumers and enabling personalized user experiences.
- Hospitality Sector Investment:Luxury hotels in North America and Europe are adopting smart toilets as a key amenity to differentiate guest experiences, driving demand for premium, feature-rich models in commercial projects.
- Water Conservation Mandates:Regulations like the EPA's WaterSense program in the United States and similar initiatives in Australia incentivize the adoption of efficient dual-flush systems often integrated into smart toilet designs.
Market Restraints
- High Initial Cost:The premium price point for fully integrated smart toilet units remains a primary barrier to mass-market adoption, confining sales largely to the luxury residential and commercial construction segments.
- Installation Complexity:Retrofitting existing bathrooms often requires specialized electrical and plumbing modifications, increasing the total cost of ownership and deterring many potential residential buyers without major renovation plans.
- Data Privacy Concerns:The collection of sensitive user data by health monitoring features creates consumer hesitancy and poses compliance challenges with stringent regulations like GDPR in Europe.
Strategic Opportunities
- Aged Care and Assisted Living:Automated functions and health tracking capabilities present a significant opportunity in the senior care sector, where such features can enhance safety, independence, and non-invasive monitoring for elderly residents.
- Emerging Markets in the Middle East:Rapid growth in luxury residential and hospitality construction in cities like Dubai and Riyadh offers an underpenetrated market for high-end smart bathroom fixtures.
- AI-Powered Health Analytics:Integrating artificial intelligence for real-time analysis of biometric data can position the smart toilet as a preventative health device, opening pathways for new service-based revenue models.
Industry Challenges
- Navigating Regional Certifications:Manufacturers face significant operational hurdles in securing simultaneous compliance with disparate electronic emissions (FCC), safety (CE marking), and water efficiency standards across global markets.
- Interoperability with Smart Home Ecosystems:Ensuring seamless software integration and compatibility with a fragmented landscape of smart home platforms from major technology companies remains a persistent and resource-intensive development challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Toilet Market |
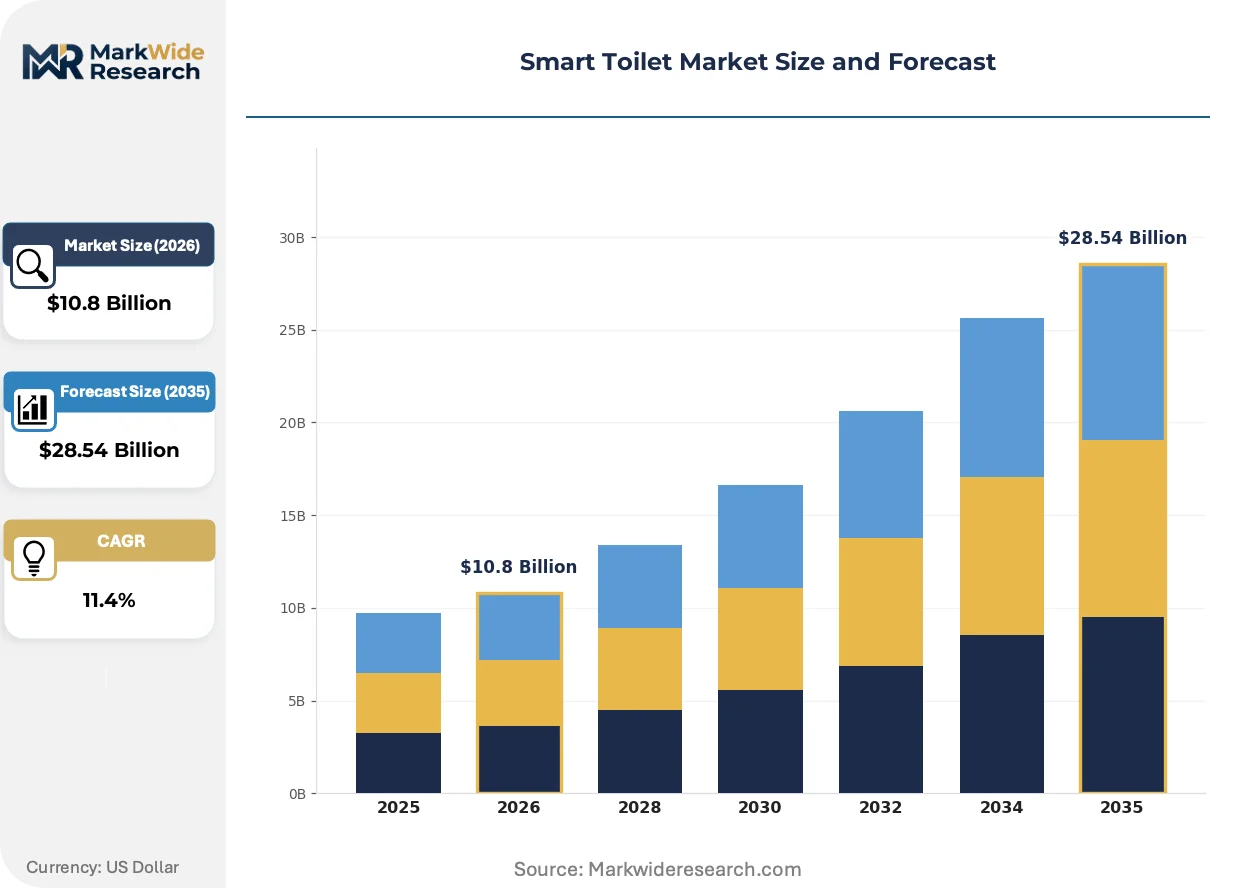
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $28.54 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bidet Toilets, Washlet Toilets, Smart Rimless Toilets, Self-Cleaning Toilets Technology: Touchless Control, Remote Control, IoT Connectivity, Sensor Technology End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Home Improvement Stores |
| Companies Covered | Jomoo Group, Roca Sanitario, TOTO, Panasonic, Geberit, Kohler, Villeroy & Boch, Woodbridge, LIXIL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Toilet Market Strategic Shifts & Innovations
The market's evolution is defined by the product's transition from a hygiene-focused appliance to a connected wellness hub. This shift is driven by advancements in sensor technology, data processing, and a growing consumer focus on proactive health management within the home environment.
Edge computing integrated into the toilet's processor enables on-device analysis of health data without constant reliance on the cloud. The senior care and wellness-oriented residential segments are key adopters, valuing the enhanced privacy and immediate feedback of local processing. This technology is decentralizing health data management, shifting analytical power from remote servers to the point of collection.
European Union regulations, particularly the Medical Device Regulation (MDR), are influencing the design of products with health monitoring capabilities. The MDR mandates stricter evidence and risk management for any device making a health claim, impacting product development cycles. Consequently, manufacturers targeting the wellness segment in Europe must now invest in more rigorous clinical validation processes.
A strong preference for touchless interfaces is accelerating, moving beyond automated lids and flushing to comprehensive voice control. This behavioral shift reduces the reliance on physical remote controls and wall panels, favoring integration with established smart home voice assistants. This trend is most visible in the North American luxury residential market, where seamless ecosystem integration is a primary purchasing factor.
Smart Toilet Market Segmentation
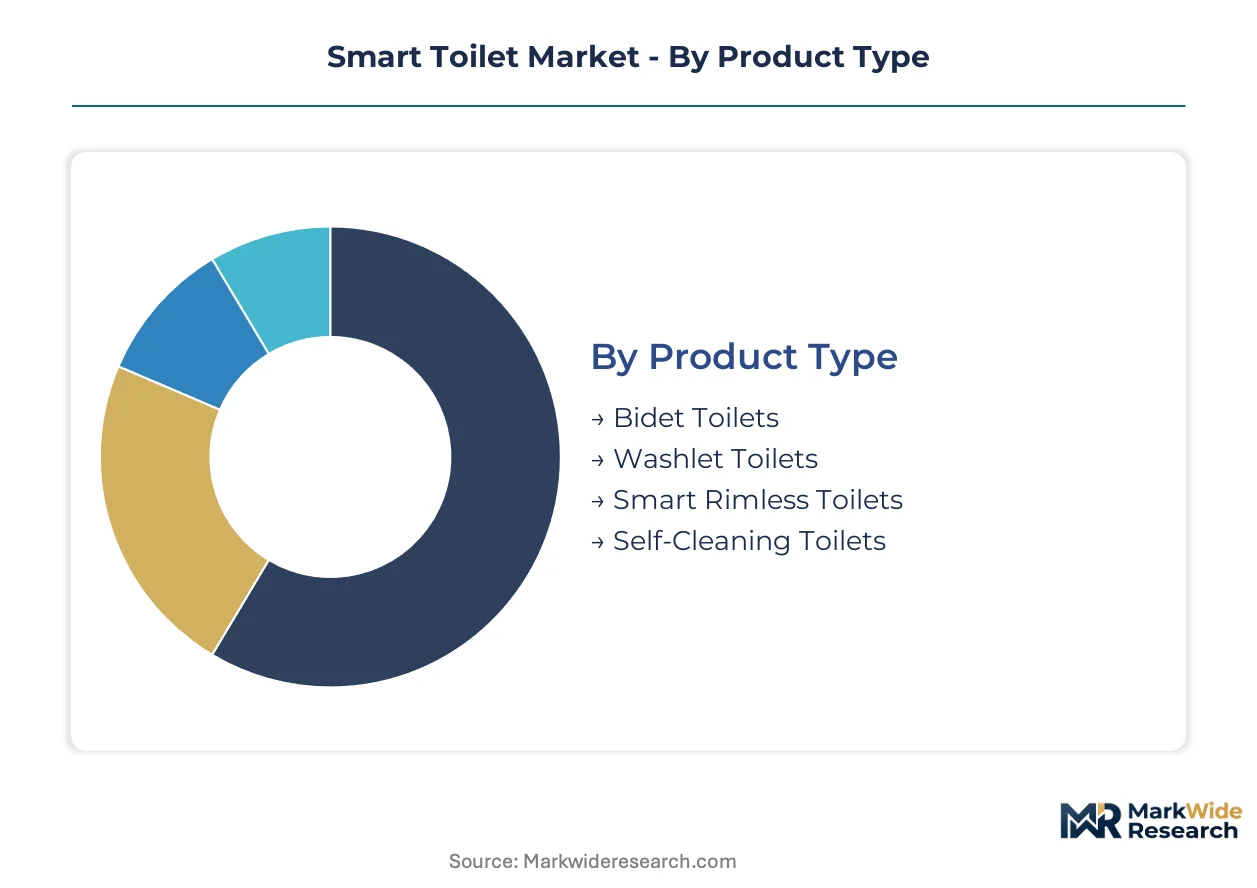
Understanding the smart toilet market through segmentation reveals critical insights into demand patterns and technological adoption. This analysis dissects how product variations, underlying technologies, diverse end-user applications, and distinct distribution channels shape the competitive landscape. Each segment represents a unique opportunity or challenge for manufacturers and retailers.
Product Type:
Product type segmentation highlights the customization-versus-standardization spectrum influencing consumer choice and market penetration. Integrated units offer comprehensive features, while add-on solutions provide accessible entry. Manufacturers balance feature sets with installation complexity across these diverse offerings.
- Bidet Toilets:These integrated fixtures combine a toilet bowl with advanced bidet functions, including heated seats and warm water washing. Demand is strong in luxury residential markets like Japan and South Korea.
- Washlet Toilets:Add-on seats provide bidet functionality, heated seats, and air drying at a lower price point. This offers a cost-effective entry for residential consumers in North America.
- Smart Rimless Toilets:These designs eliminate the traditional rim, promoting easier cleaning and improved hygiene. European markets prioritize these hygienic and aesthetically minimalist designs.
- Self-Cleaning Toilets:Units featuring automated cleaning cycles for the bowl and nozzle reduce maintenance requirements. This appeals to residential users and commercial operators focused on efficiency.
Most installed capacity flows through Washlet Toilets. Expansion is steepest in Bidet Toilets.
Technology:
Technology differentiation shapes functional sophistication and user interaction within the smart toilet market. Innovations range from basic operational convenience to advanced data collection, influencing product appeal. This array defines the intelligence embedded in each unit.
- IoT Connectivity:This technology integrates smart toilets with home automation platforms and mobile applications, enabling personalized settings and health monitoring. High-end residential consumers and luxury hospitality venues prioritize seamless integration.
- Sensor Technology:Utilizing proximity, occupancy, and water flow sensors, this core technology enables hands-free operation for lid opening and flushing. These features enhance hygiene and convenience in public restrooms and healthcare facilities.
- Touchless Control:This feature includes gesture recognition and motion detection for various functions, minimizing physical contact. Demand accelerates in commercial and hospitality settings due to hygiene concerns.
- Remote Control:Handheld or wall-mounted remote controls offer users precise command over temperature, pressure, and spray patterns. These controls provide accessibility for a broad residential demographic.
The market's technological core is Sensor Technology. IoT Connectivity is rapidly gaining functional breadth.
End User:
End-user segmentation illustrates varying demand drivers, from individual comfort to institutional efficiency. This breakdown highlights volume versus value dynamics, with residential users dominating volume and commercial sectors driving premium adoption. Each segment has distinct purchasing criteria.
- Residential:Homeowners and multi-family residences represent the largest volume demand for smart toilets, driven by personal hygiene, comfort, and luxury. High-income households in North America and Europe are key purchasers.
- Hospitality:Luxury hotels, resorts, and guesthouses constitute this segment, where smart toilets serve as a premium amenity to enhance guest experience. Investment from hotel chains in Dubai and London drives demand.
- Commercial:Office buildings, retail spaces, and public facilities focus on hygiene, durability, and low maintenance. Efficiency is critical for high-traffic environments.
- Healthcare:Hospitals, clinics, and assisted living facilities utilize smart toilets for enhanced patient hygiene, infection control, and health monitoring. Aged care facilities in Germany and Australia explore these systems.
Residential users currently account for the largest volume uptake. The Hospitality segment is expanding most quickly.
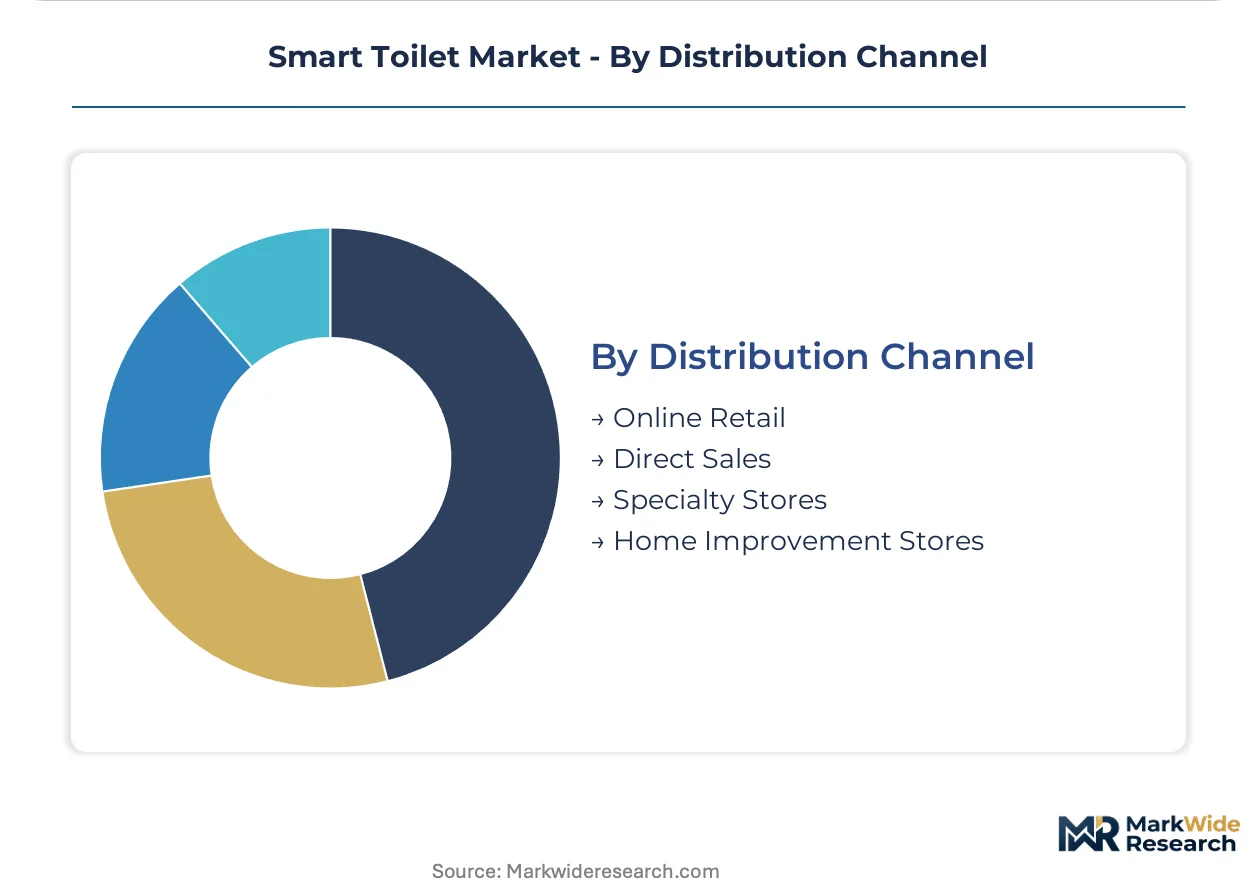
Distribution Channel:
Distribution channels define how smart toilets reach their diverse customer base, reflecting varying procurement patterns and customer access points. This spectrum ranges from direct manufacturer-to-project sales to broad consumer retail, influencing pricing and market reach.
- Direct Sales:Manufacturers engage directly with commercial developers, luxury hotel groups, and large-scale project contractors for bulk orders. This channel is crucial for securing high-value contracts in new construction across the Middle East.
- Online Retail:E-commerce platforms and brand websites provide consumers with convenience, extensive product information, and competitive pricing. This channel gains traction among tech-savvy residential buyers in the United States and Canada.
- Specialty Stores:Dedicated bathroom showrooms and high-end appliance stores offer personalized consultations and product demonstrations. These stores cater to residential customers seeking expert advice.
- Home Improvement Stores:Large retail chains provide accessible options for a broader consumer base, offering integrated units and washlet-style add-ons. This channel serves budget-conscious residential buyers.
Direct Sales facilitates large-scale project installations. Online Retail offers growing convenience for individual consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturing clusters drive significant innovation in the smart toilet market. Demand for advanced hygiene and luxury amenities is particularly strong in high-income regions. Global product compliance standards significantly influence design and market access for manufacturers.
Japan
Demand for integrated bidet toilets in Japan is fueled by a cultural preference for advanced hygiene and technological sophistication. JIS standards ensure product quality and safety for consumers. Tokyo and Osaka serve as major hubs for smart toilet R&D and high-end residential installations.
South Korea
South Korea exhibits high adoption rates for smart toilets, driven by a strong focus on wellness and home automation integration. The country's national product safety regulations influence design choices. Seoul's affluent residential districts demonstrate robust demand for premium, feature-rich units.
United States
Luxury residential and hospitality sectors in the United States prioritize smart toilet installations for enhanced comfort and guest experience. EPA's WaterSense program promotes water-efficient designs. New York City and Los Angeles drive significant commercial and high-end residential project demand.
Germany
Germany's market for smart toilets is influenced by a strong emphasis on product quality, durability, and integration into modern bathroom aesthetics. CE marking ensures compliance with European safety and health requirements. Munich and Berlin's healthcare facilities and luxury homes increasingly adopt these systems.
United Arab Emirates
The United Arab Emirates presents a significant growth opportunity due to rapid expansion in luxury residential and hospitality construction. MOHAP regulations may influence health monitoring features in future designs. Dubai and Riyadh are central to large-scale project procurements for high-end smart bathroom fixtures.
Smart Toilet Market Key Industry Players
Market expansion dominates the current landscape as manufacturers target diverse end-user segments. The smart toilet market exhibits a tiered structure, with established players focusing on distinct strategic archetypes. High-end innovators drive technological advancements, while broad-market distributors leverage extensive networks. Niche specialists differentiate through specific product features or regional focus. Geographic expansion and continuous technology innovation are primary competitive moves.
On the premium-tier vector, TOTO, a Japanese corporation, exemplifies leadership through deep brand equity and technological innovation in high-end integrated units. This company consistently pushes the boundaries of design and functionality, attracting luxury residential and hospitality clients globally. Kohler, an American company, anchors the broader market through its extensive global distribution network, effectively reaching both residential consumers and large-scale commercial projects across various regions. Geberit, a Swiss group, sits within the specialist archetype, differentiating its offerings in the European market with sophisticated concealed systems and aesthetically minimalist wall-hung solutions, catering to specific architectural and design preferences.
| Leading Market Players |
|---|
| Jomoo Group |
| Roca Sanitario |
| TOTO |
| Panasonic |
| Geberit |
| Kohler |
| Villeroy & Boch |
| Woodbridge |
| LIXIL Corporation |
| Others |
Cost & Logistics Intelligence
Semiconductor chip pricing, a critical input for smart toilet electronics, cascades through the supply chain, influencing the final pricing tiers for integrated units and add-on washlets. This dynamic interplay between component costs and finished product value shapes market accessibility and manufacturer profitability.
Pricing Analysis
Input cost pass-through from electronic components and specialized ceramic materials directly impacts smart toilet pricing. The market primarily operates on a tiered premium-mid-economy pricing differentiation. Price differentiation stems from brand premium and technological sophistication, including IoT integration and advanced health monitoring features. Pricing pressure intensifies for entry-level washlet units due to increased competition. Luxury residential buyers and hospitality developers demonstrate the least price sensitivity, valuing feature sets and brand reputation.
Supply Chain Analysis
Reverse logistics for smart toilets, encompassing returns and potential refurbishment of electronic components, is an emerging consideration for manufacturers. Geographic supply concentration centers in Japan for premium ceramic and electronic sub-assemblies, with South Korea and China contributing significantly to general electronic components and plastics. The supply chain relies on specialized sensor technology and microcontrollers. Geopolitical risks affecting electronic component availability present a structural risk. Distribution runs through direct sales channels for commercial projects and online retail for residential consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
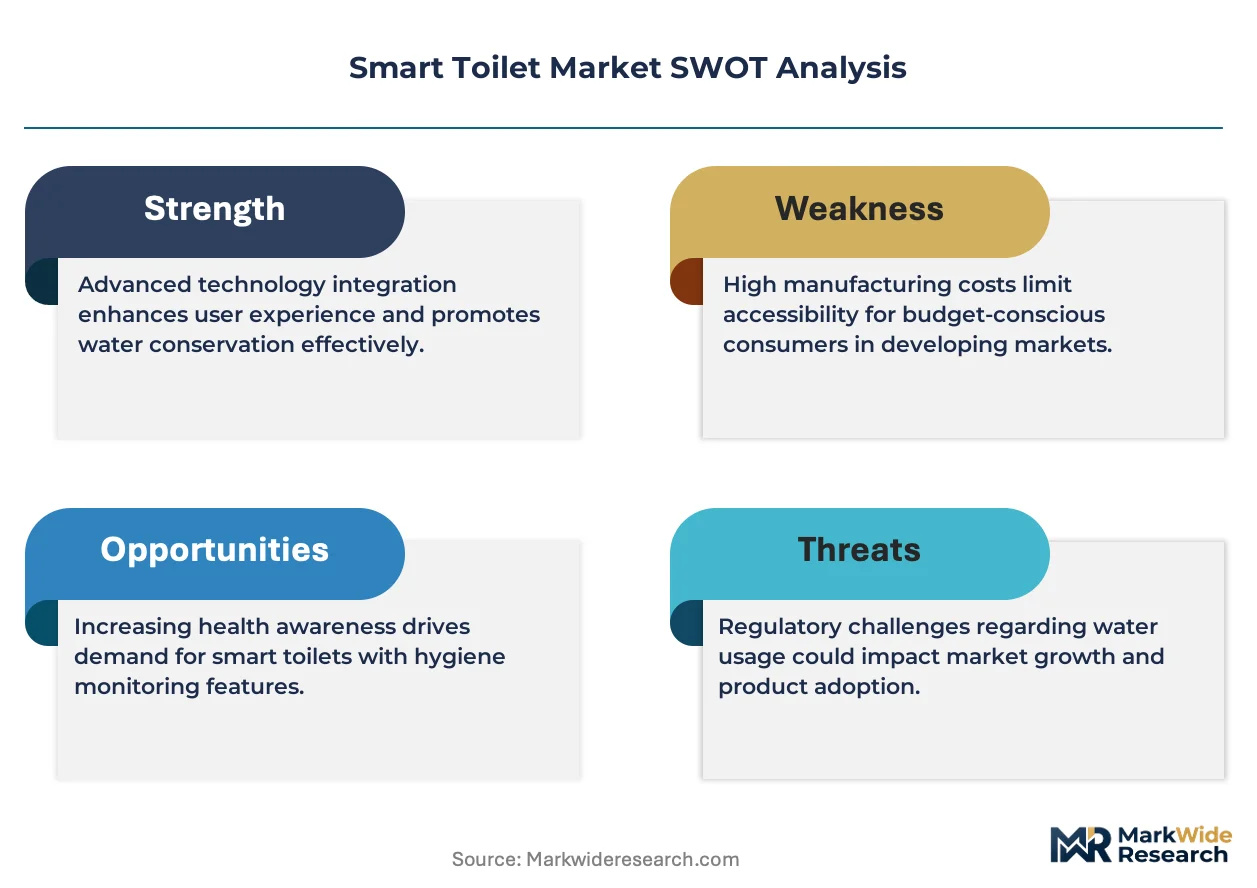
The smart toilet market presents a clear margin-expansion story, driven by the shift towards advanced health monitoring and personalized wellness features.
For Market Incumbents:
Cement leadership by deepening R&D investment in AI-powered health analytics and securing intellectual property for novel biometric sensors. Expand manufacturing capacity for high-end integrated units in regions like the Middle East to capture luxury construction projects. This mitigates the threat of commoditization in basic bidet functions. Investment in Medical Device Regulation (MDR) compliance for health-focused products represents a critical lever for European market access.
For New Entrants and Emerging Players:
Enter via strategic partnerships with assisted living facilities, focusing on automated functions and non-invasive health tracking for seniors. Target the aged care segment in Germany and Australia, which shows early adoption for these specialized features. Develop modular, upgradeable software platforms for health data analytics as a service. This go-to-market angle leverages the growing demand for proactive wellness management in residential settings.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized technology firms developing advanced sensor arrays and AI algorithms for biometric analysis. The market's long-term viability hinges on its evolution into a preventative health device, extending beyond hygiene. Acquisition targets should include software companies with expertise in data privacy compliance and seamless smart home integration. Practitioners should monitor regulatory approvals for health claims, such as those under the EU's MDR, for early signals of market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Biometric Analysis | Positions smart toilets as preventative health devices, opening new revenue streams in wellness. |
| Expand into Aged Care Facilities | Addresses a high-growth end-user segment with specific needs for safety and monitoring. |
| Secure Medical Device Certifications | Enables market entry and credibility for health-monitoring features in regulated regions like Europe. |
| Develop Modular Software Platforms | Ensures interoperability with diverse smart home ecosystems and future-proofs product functionality. |
| Strengthen Direct Sales in Middle East | Captures high-value luxury residential and hospitality construction projects in emerging markets. |
Research Approach
Direct dialogue with product development engineers, hospitality procurement managers, residential contractors, and healthcare facility administrators provided qualitative insights into market dynamics. This primary research was triangulated with secondary validation from company annual reports, government trade statistics, industry association publications, and academic research on health technology. A combination of bottom-up and top-down approaches ensured comprehensive data coverage.
The analytical framework utilized a bottom-up estimation of unit sales across various product types, technologies, end users, and distribution channels, validated against top-down market size figures. Segmentation dimensions included bidet toilets, washlet add-ons, IoT connectivity, sensor technology, residential, hospitality, and healthcare applications, and direct sales or online retail. Compound annual growth rates were derived through regression analysis of historical adoption data and projected feature penetration rates over the projection horizon. Smart home device penetration and luxury construction project pipelines served as key industry-specific forecast inputs.
The model holds under current regulatory frameworks and consistent consumer technology adoption trends; deviation in data privacy laws or major electronic component supply chain disruptions would shift projections. Forecasts reflect assumptions documented through extensive industry engagement. Practitioners should monitor regulatory changes impacting health claims and global trade policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Humidifiers Market
Household Items
Drain Cleaners Market
Household Items
Netherlands Cookware Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Bristle Brush Market
Household Items
Japan Digital Showers Market
Household Items
Hydralight Lanterns Market
Household Items
Asean Cookware Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Portable Showers Market
Household Items
Remote Control Holder Market
Household Items
Global Tableware Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Steam Cleaners Market
Household Items
Shoe Shine Machine Market
Household Items
Electric Brooms Market