
 Asia-Pacific Air Purifier Market | 2026-2036
Asia-Pacific Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air Purifier Market Outlook
Filter replacement subscription programs is restructuring how manufacturers capture lifetime value from installed bases. Daikin Industries Ltd leverages its HVAC service infrastructure to bundle air purifier maintenance contracts with climate system packages. Panasonic Corporation anchors its position through proprietary nanoe technology integration across residential and commercial lines. Xiaomi Corporation competes aggressively on smart connectivity, embedding air purifiers within its IoT ecosystem to drive recurring software engagement.
Asia-Pacific air purifiers are electromechanical filtration systems designed to remove particulate matter, volatile organic compounds, and biological contaminants from indoor air, typically achieving CADR ratings between 200-400 cubic meters per hour for residential units. HEPA filtration occupies the dominant product category due to proven efficacy against PM2.5, the primary pollutant concern across East Asian metropolitan areas. Smart technology integration represents the fastest-expanding segment as manufacturers embed particulate sensors and app-based automation to differentiate hardware commoditization. The medical application category commands premium positioning, with hospitals and clinics demanding ISO-certified units for infection control environments.
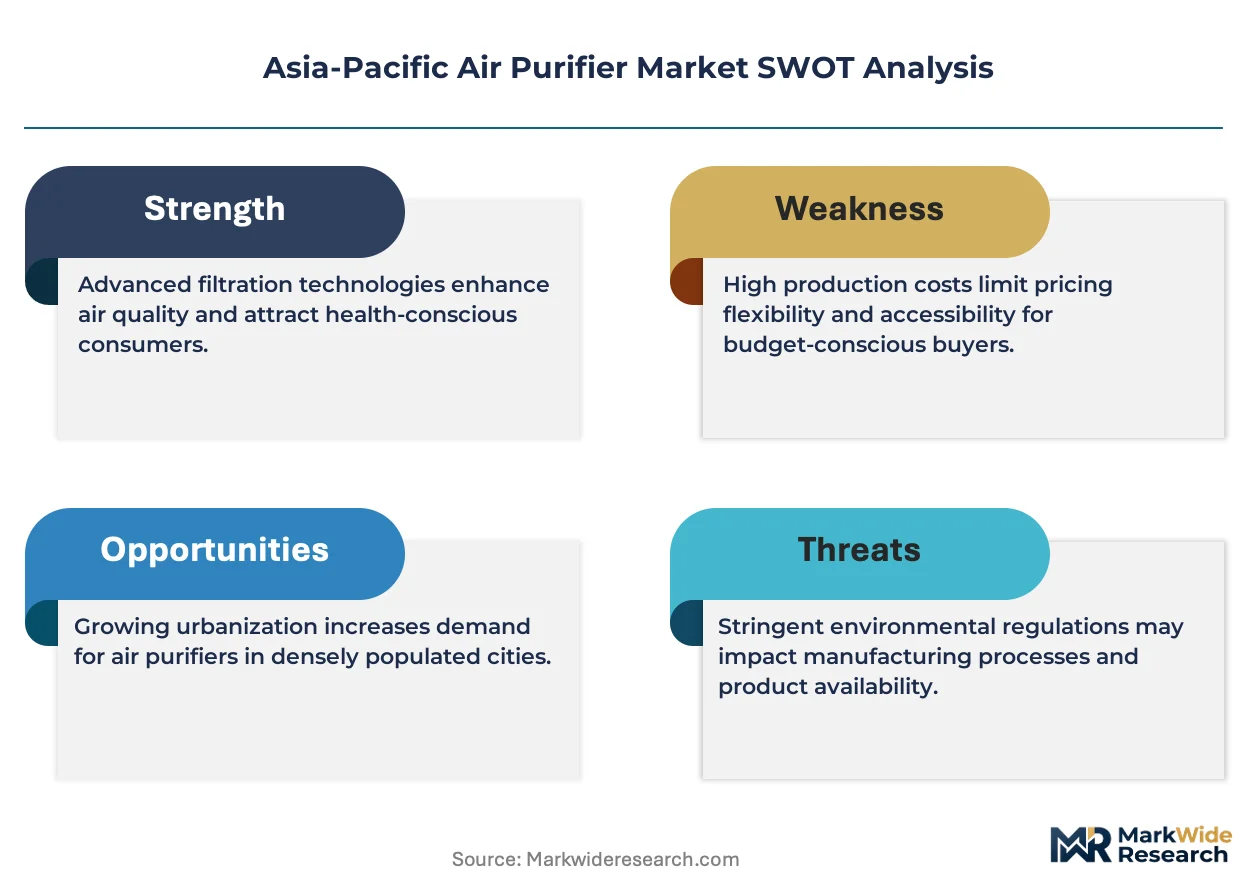
China's MEE enforces ambient air quality standards that indirectly mandate indoor mitigation in public buildings, while India's BIS certification requirements for clean air delivery rates are elevating minimum performance thresholds for market entry. Japan's METI energy efficiency labeling program shapes consumer purchasing decisions by disclosing power consumption per unit of filtered air volume. Stakeholders must monitor how fragmented national certification regimes evolve toward mutual recognition or continued divergence, as this will determine whether regional product platforms or country-specific SKUs prove more cost-efficient.
Market Dynamics
Filter subscription programs are restructuring manufacturer revenue models across Asia-Pacific, converting one-time hardware sales into recurring service relationships. India's BIS certification tightening and China's MEE indoor air mandates are accelerating product refresh cycles while compressing margins for uncertified entrants.
Growth Catalysts
- HEPA-CADR standardization:India's BIS mandates for clean air delivery rates are eliminating substandard products from retail channels. Tier-one Chinese cities now require public buildings to maintain indoor PM2.5 thresholds below 35 μg/m³.
- Urban apartment densification:Residential units in Shanghai, Beijing, and Delhi face acute outdoor air infiltration. Sealed-window designs in new high-rise construction amplify demand for mechanical filtration.
- Nanoe and plasma cluster integration:Japanese manufacturers embed charged particle technology across HVAC-purifier bundles. METI energy efficiency labeling drives consumer preference toward low-wattage high-CADR units.
Market Restraints
- Filter media supply concentration:Glass microfiber HEPA substrate production clusters in Germany and Japan. Freight costs and currency volatility transmit directly to landed costs for Korean and Southeast Asian assemblers.
- Activated carbon price volatility:Coconut shell charcoal sourcing from Sri Lanka and Indonesia faces agricultural yield fluctuations. Petrochemical-based alternatives carry inferior VOC adsorption capacity.
- Fragmented certification regimes:China's GB standards, India's BIS requirements, and Japan's JIS specifications lack mutual recognition. Manufacturers must maintain three distinct SKU portfolios for regional compliance.
Strategic Opportunities
- Vietnam and Indonesia penetration:Urban middle-class expansion in Ho Chi Minh City and Jakarta precedes regulatory mandates. Early entrants can establish brand preference before BIS-equivalent standards emerge.
- Medical-grade ISO certification:Hospital HVAC retrofits in India and Thailand demand H14 HEPA with antimicrobial coatings. This segment commands three-to-four times residential unit pricing.
- IoT ecosystem convergence:Smart home platforms in China integrate particulate sensors with climate control. Data monetization and predictive filter replacement apps create recurring revenue streams.
Industry Challenges
- Electronics-embedded filtration engineering:Sensor calibration and firmware integration require skills scarce among traditional appliance manufacturers. Recruitment competition with automotive and smartphone sectors intensifies.
- Dual certification timelines:Simultaneous BIS and GB testing extends product launch windows by eight to fourteen months. Working capital ties up in inventory awaiting multiple approval stamps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air Purifier Market |
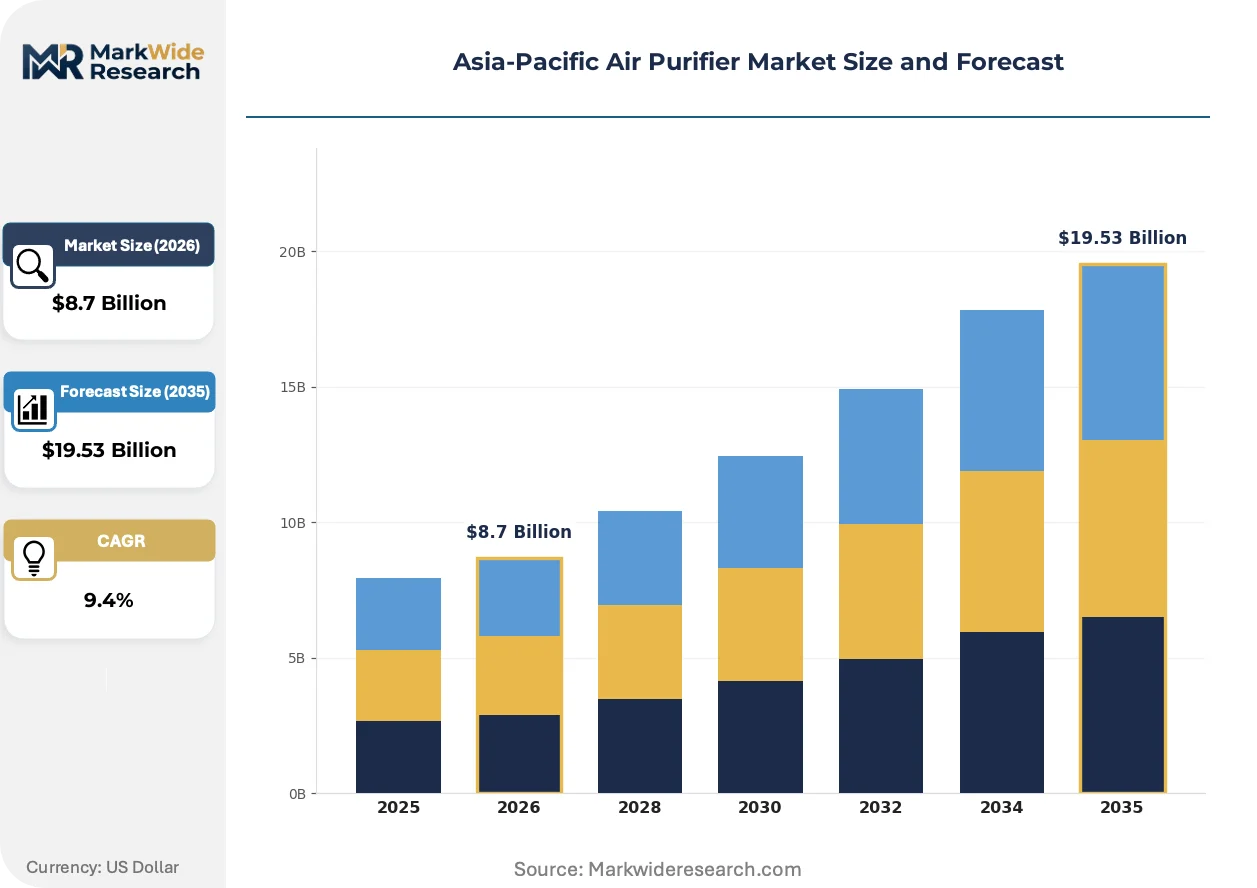
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Ionizers, UV-C Light Application: Residential, Commercial, Industrial, Medical Technology: Passive, Active, Hybrid, Smart End User: Households, Offices, Hospitals, Schools |
| Companies Covered | Daikin Industries Ltd, Panasonic Corporation, Dyson Ltd, Koninklijke Philips NV, Xiaomi Corporation, Sharp Corporation, LG Electronics Inc., Honeywell International Inc., Coway Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air Purifier Market Strategic Shifts
Sensor-embedded automation and filter-as-a-service business models are compressing replacement cycles while shifting competitive advantage from hardware specifications to data-driven air quality management platforms.
Electrostatic precipitator modules with washable collection plates are modularizing maintenance economics for commercial building operators. Facility managers in Singapore and Sydney commercial towers adopt these units to eliminate quarterly filter procurement. The technology is modularizing capital expenditure into operational leases, reducing upfront HVAC retrofit commitments by sixty percent.
China's MEE enforcement of GB/T 18801-2022 performance testing protocols is disqualifying imported units lacking domestic laboratory certification. Korean and Japanese manufacturers must rebuild test data packages for mainland market access. The policy compresses effective product lifecycles as older certified models face delisting.
Appliance retailers in Seoul and Tokyo are unbundling installation and filter subscription services from hardware transactions. Consumers purchase purifiers through e-commerce platforms while manufacturer service networks handle deployment and consumables. This channel bifurcation is most pronounced in Japan, where METI labeling requirements already drive online specification comparison before physical inspection.
Asia-Pacific Air Purifier Market Segmentation
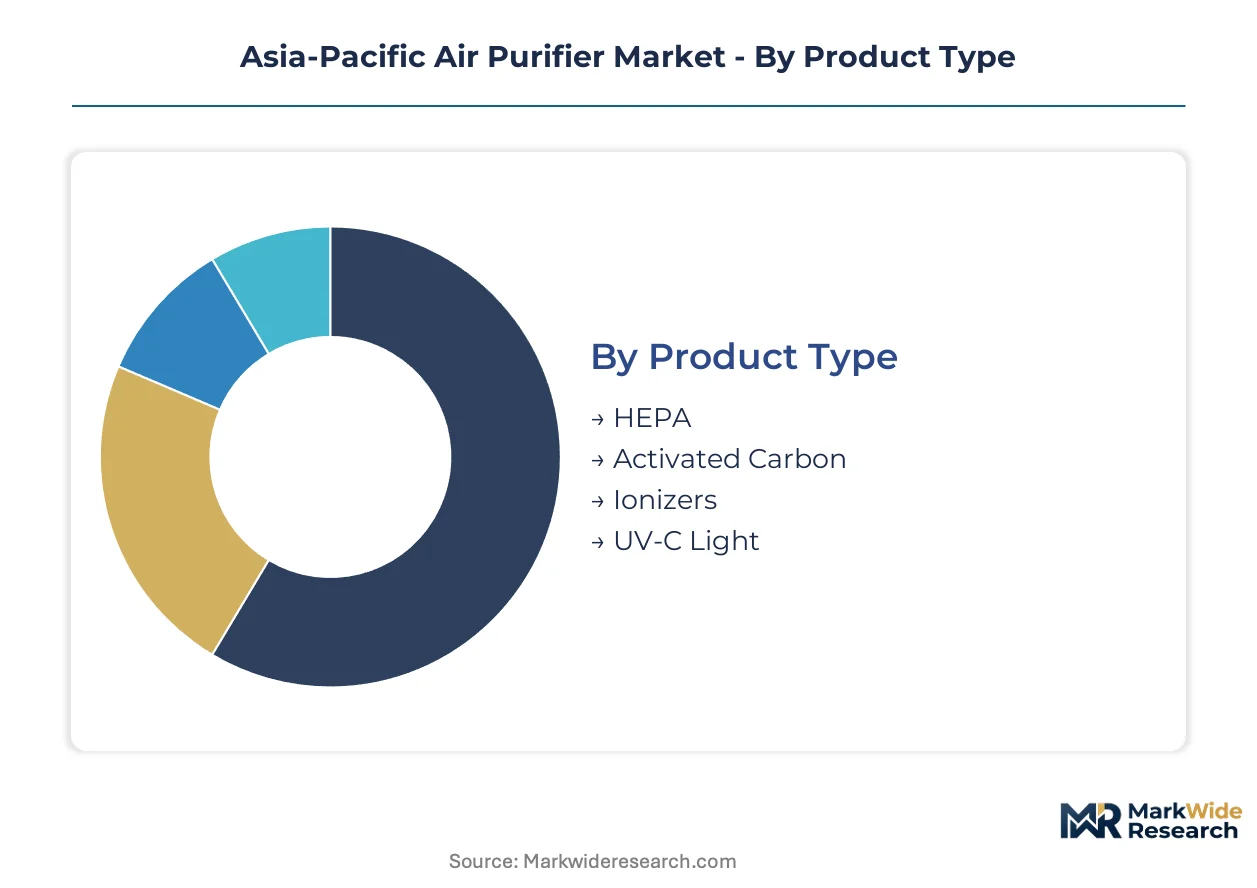
Segmentation in the Asia-Pacific air purifier market reveals how technology choices, application environments, and end-user requirements fragment purchasing decisions. Manufacturers must align product architectures with distinct performance thresholds, regulatory compliance levels, and service intensity demands across each category.
Product Type:
Volume concentration clusters around proven filtration media, while premium positioning attaches to technologies with demonstrable efficacy against specific pollutant classes.
- HEPA:High-efficiency particulate air filters utilize glass microfiber mats rated H13-H14 to capture 99.97% of particles 0.3 microns and above. Shanghai and Beijing residential towers specify HEPA as baseline equipment, with India's BIS certification mandating minimum CADR thresholds that only HEPA systems reliably achieve.
- Activated Carbon:Porous carbon substrates adsorb volatile organic compounds and gaseous pollutants through physisorption. Demand concentrates in Jakarta and Ho Chi Minh City commercial buildings, where formaldehyde off-gassing from new construction materials drives specification requirements.
- Ionizers:Electrostatic discharge systems precipitate particles onto charged collection surfaces. Japanese manufacturers integrate these into compact desktop units for Tokyo office cubicles.
- UV-C Light:Germicidal ultraviolet irradiation at 253.7 nanometers neutralizes biological contaminants. Hospital procurement in Bangkok and Manila specifies UV-C modules for infection control zones.
Today's leader: HEPA. Tomorrow's challenger: UV-C Light.
Application:
Application segmentation maps directly to air exchange requirements, duty cycle intensity, and regulatory oversight stringency.
- Residential:Compact units designed for 20-50 square meter coverage with noise thresholds below 35 decibels. Delhi and Mumbai apartment complexes drive volume, with sealed-window high-rises amplifying mechanical filtration dependency.
- Commercial:Centralized or distributed systems serving 200-2,000 square meter footprints. Singapore and Sydney facility managers prioritize electrostatic precipitator variants to eliminate recurring filter procurement.
- Industrial:Heavy-duty configurations handling process emissions and occupational exposure limits. Manufacturing clusters in Guangdong and Karnataka deploy these for worker protection compliance.
- Medical:ISO-certified units with H14 HEPA and antimicrobial coatings achieving 400+ CADR. Indian and Thai hospital HVAC retrofits command premium positioning at three-to-four times residential unit pricing.
Medical applications claim the steepest expansion trajectory as healthcare infrastructure investment accelerates.
Technology:
Technology architecture determines capital intensity, operating cost structure, and integration potential with building management systems.
- Passive:Fan-driven mechanical filtration without electronic augmentation. Dominates entry-level pricing tiers across Southeast Asian mass retail channels.
- Active:Electrostatic or ionization-based particle precipitation without filter media replacement. Korean manufacturers emphasize these for cost-conscious commercial buyers.
- Hybrid:Combined mechanical and electronic stages optimizing capture efficiency across particle sizes. Tier-one Chinese cities specify these for public building compliance with MEE indoor air mandates.
- Smart:Sensor-embedded automation with app-based control and predictive maintenance algorithms. Xiaomi and Huawei ecosystem integration drives fastest adoption in Shenzhen and Hangzhou connected homes.
Smart systems are gaining share fastest as IoT platform penetration deepens.
End User:
End user segmentation reflects divergent procurement authority, technical specification literacy, and total cost of ownership horizons.
- Households:Individual consumers purchasing through e-commerce or appliance retail. METI energy efficiency labeling shapes Japanese household decisions before physical inspection.
- Offices:Corporate facility managers negotiating service bundles with HVAC contractors. Daikin leverages its climate infrastructure to attach purifier maintenance contracts in Osaka and Nagoya.
- Hospitals:Infection control committees specifying ISO-certified equipment with documented test data. CDSCO-equivalent state regulators in India audit procurement compliance.
- Schools:Government education departments deploying standardized units across classroom portfolios. China's MEE enforcement of GB/T 18801-2022 protocols disqualifies non-certified products from tender participation.
School procurement represents the most price-elastic segment, with bulk tenders compressing unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces India in absolute installation volumes, though India's regulatory tightening is compressing market entry timelines more aggressively than Beijing's MEE enforcement.
China
Shanghai and Beijing residential towers specify HEPA as baseline equipment for PM2.5 mitigation. MEE enforces GB/T 18801-2022 performance testing protocols that disqualify imported units lacking domestic laboratory certification. The Yangtze River Delta manufacturing corridor supplies filter media to Korean and Southeast Asian assemblers facing freight cost volatility.
India
Delhi and Mumbai apartment complexes drive residential volume as sealed-window high-rises amplify mechanical filtration dependency. BIS certification mandates for clean air delivery rates are eliminating substandard products from retail channels. The National Capital Region hosts HVAC retrofit demand from hospital infection control committees specifying ISO-certified equipment.
Japan
Tokyo office cubicles absorb compact desktop units with noise thresholds below 35 decibels. METI energy efficiency labeling shapes consumer purchasing decisions by disclosing power consumption per unit of filtered air volume. Osaka and Nagoya facility managers negotiate service bundles with climate contractors attaching purifier maintenance contracts.
South Korea
Seoul appliance retailers unbundle installation and filter subscription services from hardware transactions. MFDS-equivalent national standards shape procurement for medical-grade installations in hospital HVAC retrofits. The Seoul Capital Area concentrates smart home platform integration driving sensor-embedded automation adoption.
Vietnam
Ho Chi Minh City urban middle-class expansion precedes regulatory mandates for BIS-equivalent standards. Commercial buildings specify activated carbon substrates for formaldehyde off-gassing from new construction materials. Early entrants establish brand preference before certification requirements emerge.
Asia-Pacific Air Purifier Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with HVAC-integrated players capturing service-contract value while consumer electronics firms drive smart connectivity penetration. The market structure tiers into three clusters: climate-system incumbents leveraging installed service infrastructure, consumer technology platforms embedding devices within IoT ecosystems, and dedicated appliance manufacturers competing on filtration specifications. Consolidation pressure concentrates among mid-scale players lacking either HVAC integration depth or software platform scale. Dominant competitive moves include bundling maintenance contracts with climate system packages and embedding particulate sensors within building management system architectures.
Within the climate-system incumbent tier, Daikin Industries Ltd and Panasonic Corporation occupy positions shaped by HVAC service infrastructure depth. Daikin leverages its climate contractor relationships to attach purifier maintenance contracts, while Panasonic anchors positioning through charged particle technology integration. Xiaomi Corporation sits within the consumer technology platform archetype, competing through smart connectivity and IoT ecosystem embedding rather than hardware specification differentiation. These three exemplify how competitive advantage migrates from filtration performance metrics toward data-driven air quality management and recurring service relationships.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Panasonic Corporation |
| Dyson Ltd |
| Koninklijke Philips NV |
| Xiaomi Corporation |
| Sharp Corporation |
| LG Electronics Inc. |
| Honeywell International Inc. |
| Coway Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sensor calibration engineers concentrated in Shenzhen and Seoul command wage premiums that compress margins for smart-system tiers while widening spreads against passive filtration units. Labor-cost differentials between Chinese firmware developers and Vietnamese assembly technicians translate directly into three-tier pricing stratification across certification grades.
Pricing Analysis
Capacity additions in Vietnam are reshaping price floors for entry-level passive units as domestic mold-injection capabilities expand. Pricing stratifies across medical-grade ISO-certified systems, BIS-mandated residential tiers, and uncertified economy channels. Cost compression in the economy tier intensifies because coconut shell charcoal volatility transmits to activated carbon module costs. Hospital procurement committees show least price sensitivity while government school tenders exhibit maximum elasticity.
Supply Chain Analysis
Freight cost volatility on Shanghai-Hamburg routes directly inflates landed costs for German glass microfiber HEPA substrates. Glass microfiber production clusters in Germany and Japan while activated carbon sourcing draws from Sri Lankan and Indonesian agricultural processors. Single-source vulnerability concentrates in Japanese nanoe generator component supply. Distribution runs through Daikin's climate contractor networks and Xiaomi's direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's tightening BIS certification timelines and Vietnam's pre-regulatory brand-building window. The cost differential stems from India's eight-to-fourteen-month dual approval delays versus Vietnam's absence of equivalent mandates.
For Market Incumbents: To counter Xiaomi's IoT ecosystem lock-in, Daikin and Panasonic must deepen HVAC-purifier bundling with predictive maintenance algorithms. Backward integration into filter media production reduces exposure to German substrate freight volatility. Certification investment in India's BIS and China's GB/T 18801-2022 protocols preserves retail channel access. For New Entrants and Emerging Players: Tier-two Vietnamese hospitals present the most penetrable white-space target for ISO-certified equipment before domestic standards emerge. Jakarta commercial buildings with formaldehyde mitigation needs offer secondary entry points. A go-to-market angle anchored in electrostatic precipitator leasing models sidesteps upfront capital barriers for facility managers. For Investors and Strategic Acquirers: HVAC-integrated climate specialists are the most active acquirer in this space as they seek purifier attach rates to service contracts. Long-term viability centers on recurring filter subscription economics rather than hardware shipment volumes. The signal to monitor is BIS-equivalent standard emergence in Indonesia and Vietnam as inflection points for competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Filter-as-a-Service Subscription Launch | Converts one-time hardware sales into recurring revenue streams with Daikin-style maintenance bundling. |
| Dual Certification Fast-Track Investment | Compresses India's BIS and China's GB/T 18801-2022 approval timelines for accelerated market entry. |
| Smart Home Platform Integration | Embeds particulate sensors within Xiaomi and Huawei IoT ecosystems for data monetization opportunities. |
| Medical-Grade ISO Certification Pathway | Captures three-to-four times residential pricing in Thai and Indian hospital HVAC retrofit demand. |
| Activated Carbon Supply Diversification | Reduces Sri Lankan and Indonesian agricultural yield volatility exposure for VOC adsorption modules. |
Study Parameters
Multiple input streams — primary interviews with HVAC contractors and hospital infection control committees, secondary validation through BIS certification databases and METI energy efficiency registries, customs records on filter media trade flows — were reconciled through bottom-up installation tracking and top-down market sizing. Conversations with facility managers in Singapore commercial towers and procurement leads at Indian GPOs informed service-contract pricing assumptions. SEC filings from listed appliance manufacturers and CDSCO medical device registrations provided secondary anchor points.
Data-stream reconciliation across product type, application environment, technology architecture, and end-user procurement authority generated volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth trajectory modeling against regulatory enforcement timelines. Modeled inputs included India's BIS certification penetration curves, China's MEE indoor air mandate compliance rates, and smart home platform adoption patterns across Seoul and Shenzhen.
Underlying measurement precision varies by segment; medical-grade ISO-certified installations carry tighter precision than economy-tier residential channels due to documented procurement records. Forecasts reflect assumptions on regulatory harmonization timelines and filter media supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Silicone Soap Mold Market
Household Items
China Cookware Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Flatware Market
Household Items
Air Purifier Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
Umbrella Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
US Air Fresheners Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Collapsible Water Bottle Market
Household Items
Hydralight Lanterns Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Cutlery Steel Market
Household Items
Sleeping Pods Market
Household Items
Toilet Care Wipes Market