
 Bottle Openers Market | 2026-2036
Bottle Openers Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Openers Market Analysis
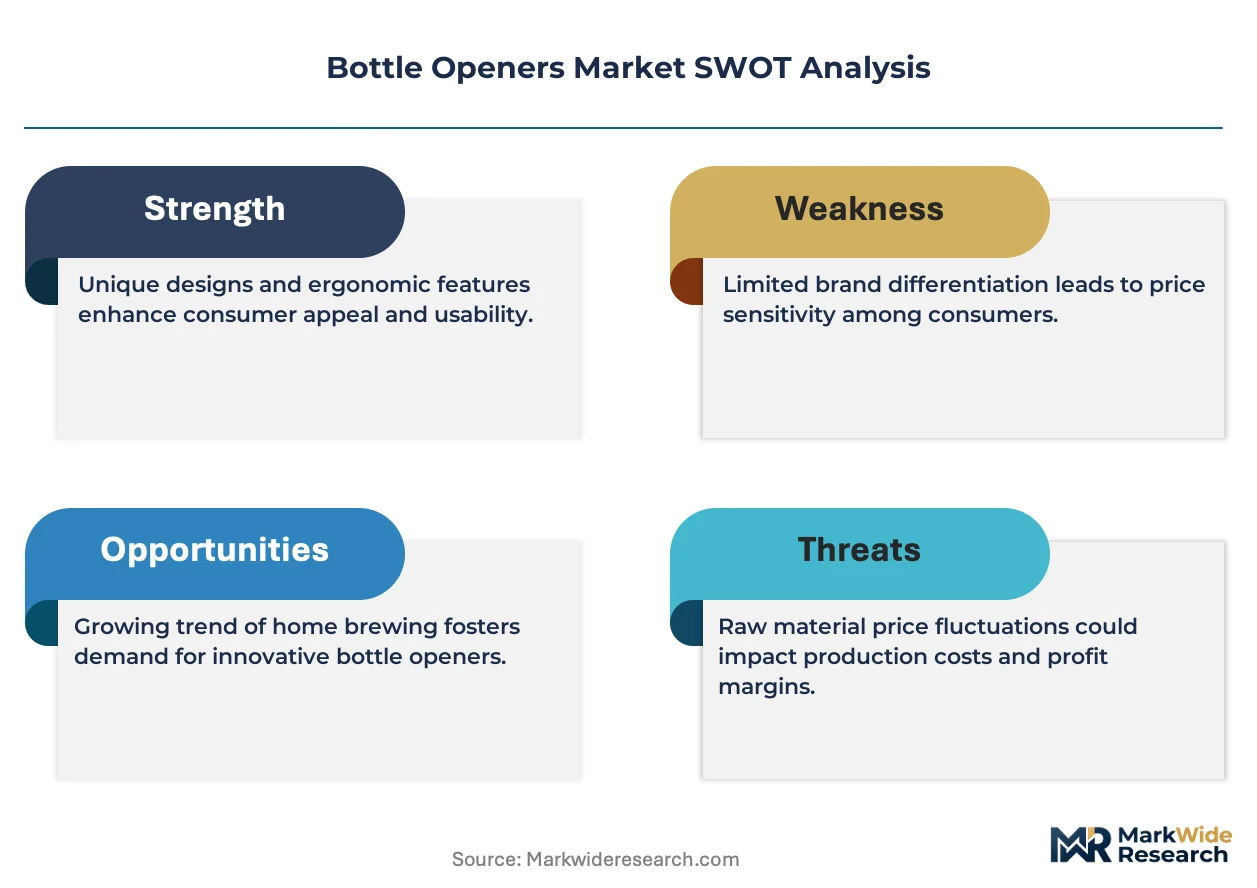
The EU Green Deal is repositioning material sourcing across the European bottle opener supply chain, pushing manufacturers away from virgin plastics toward recycled stainless steel and certified wood. Joseph Joseph leverages its design-led portfolio to sustain premium positioning in modern kitchen environments. OXO International anchors its market presence through ergonomic patent families and broad retail distribution. Le Creuset competes on heritage brand equity and enameled metal craftsmanship.
A bottle opener is a handheld mechanical device, typically fabricated from stainless steel, aluminum, or reinforced thermoplastic, designed to puncture or pry crown caps and extract corks with lever-based force multiplication. Wall-mounted variants dominate commercial installations in bars and restaurants where throughput speed matters, while corkscrew formats command higher unit margins due to precision engineering requirements. Manual openers retain volume leadership in home usage segments, though keychain formats show structural growth through promotional and gift-channel penetration.
REACH and RoHS frameworks govern chemical composition and restricted substance thresholds for metallic and coated components sold within the European Union. CE marking requirements under the General Product Safety Directive shape market access protocols for electric and battery-assisted variants. The country's national consumer protection regulator in France enforces additional labeling standards for food-contact materials. Stakeholders must monitor evolving extended producer responsibility schemes and material traceability mandates that will reshape supplier qualification criteria.
Market Dynamics
REACH compliance and the EU Green Deal are forcing material substitutions across European bottle opener supply chains, displacing virgin plastics with recycled stainless steel and certified wood as manufacturers retool for chemical safety and carbon accountability.
Growth Catalysts
- Craft beverage proliferation:Germany's independent brewery sector drives premium tool adoption in urban hospitality clusters. Specialized corkscrew and lever designs command higher attachment rates in tasting rooms and craft bars.
- REACH substance restrictions:ECHA mandates on nickel release and heavy metal content push manufacturers toward food-grade aluminum and surgical-grade stainless steel. Compliance investments filter out low-grade competitors.
- Extended producer responsibility schemes:France and Italy implement material traceability mandates for food-contact metal goods. Qualified suppliers gain preferential placement in retail and foodservice procurement.
Market Restraints
- Aluminum price volatility:Input cost swings for food-grade 6061 aluminum compress margin buffers for mid-tier manufacturers. Hedging instruments remain underutilized among small-scale producers.
- Asian supply concentration:Forging and finishing capacity clusters in Zhejiang and Guangdong provinces. Geopolitical friction or shipping disruptions propagate through European inventory cycles.
- Electric opener substitution ceiling:Battery-assisted variants face technical limitations in torque precision for aged cork extraction. Manual tools retain irreplaceable function in wine service contexts.
Strategic Opportunities
- Spanish hospitality modernization:Barcelona and Madrid bar renovations create specification windows for wall-mounted commercial systems. Speed-focused designs align with high-volume tapas service models.
- CSRD-aligned carbon accounting:Scope 3 disclosure requirements favor suppliers with certified recycled content and regional sourcing. Early certifiers capture ESG-mandated procurement from hotel chains.
- Direct-to-consumer channel expansion:Subscription wine clubs and curated gift platforms bypass traditional retail markups. Personalized engraving and limited editions penetrate anniversary and corporate gifting segments.
Industry Challenges
- Surface finishing expertise gap:PVD coating and electropolishing specialists are scarce in European manufacturing bases. Quality drift in corrosion resistance undermines brand positioning.
- CE marking timeline compression:Battery-assisted opener variants face extended conformity assessment under the General Product Safety Directive. Documentation bottlenecks delay seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Openers Market |
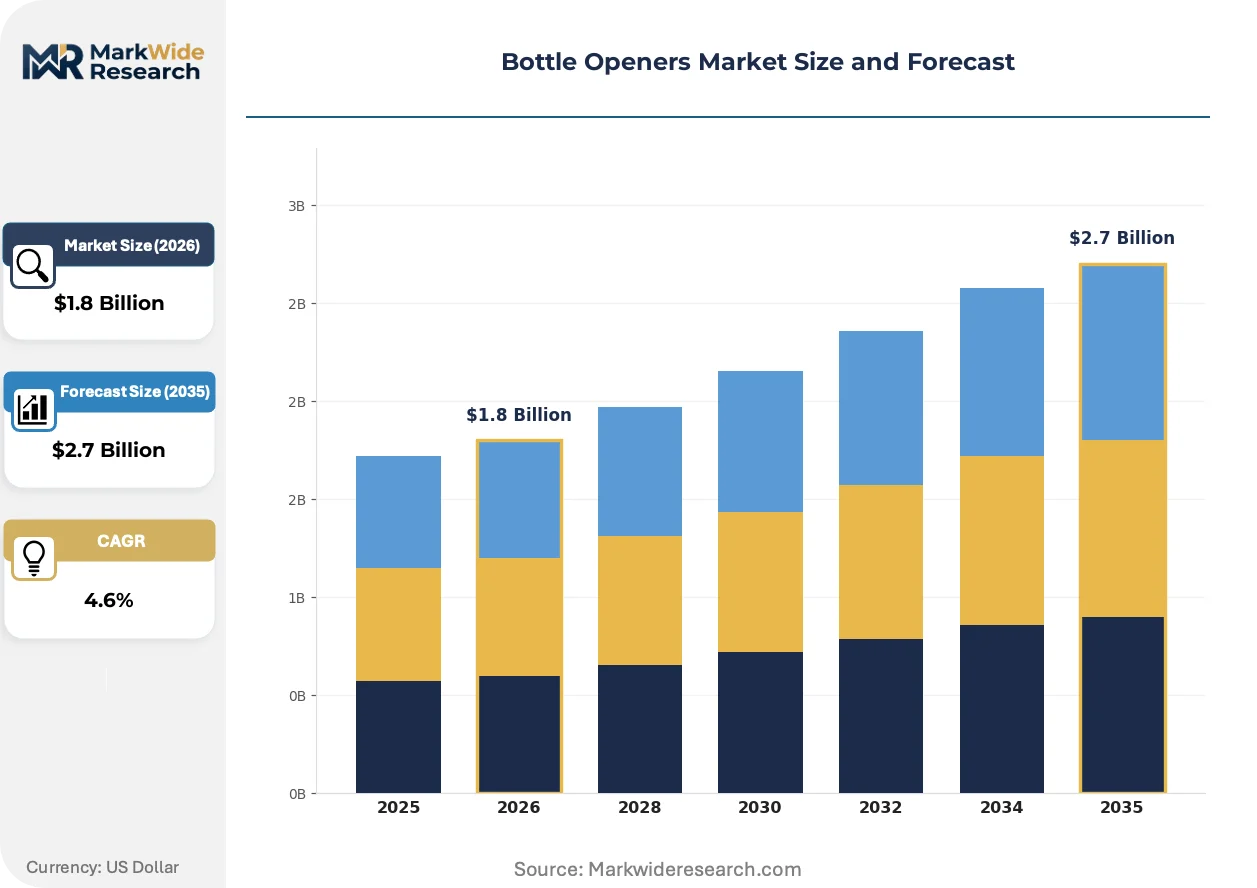
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted, Corkscrew, Keychain, Manual Material: Stainless Steel, Plastic, Wood, Aluminum Usage: Home, Bars, Restaurants, Events Design: Classic, Modern, Vintage, Customized |
| Companies Covered | Joseph Joseph, Le Creuset, OXO International, Chefman, Victorinox, Coravin, Vinocave, BarCraft, Oster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Openers Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are reconfiguring how bottle openers are specified, sourced, and differentiated across European foodservice and retail channels.
Multi-tool integration is modularizing the traditional bottle opener form factor. Swiss-designed implements now combine crown cap levers, corkscrew worms, and foil cutters in interchangeable cartridge systems. Boutique outdoor retailers and alpine hospitality suppliers in Switzerland and Austria are specifying these systems for space-constrained service environments. The approach is compressing standalone SKU counts while elevating average unit values through component upgrade paths.
The EU Green Deal's embodied carbon reporting requirements are reshaping supplier qualification protocols. ECHA's SCIP database mandates disclosure of SVHC content in articles placed on the EU market. German kitchenware distributors are demanding third-party verified recycled content certificates for stainless steel stock. Italian enameled metal specialists face pressure to document smelter electricity sources or risk exclusion from contract foodservice tenders.
Wine club subscription models are fragmenting traditional retail purchasing patterns. Curated monthly deliveries bundle opener accessories as enrollment incentives rather than standalone purchases. California-based wine merchants and Bordeaux négociant direct-ship programs are displacing brick-and-tool accessory sales. The shift is most pronounced in urban millennial demographics where cabinet space constraints favor minimalist, multi-functional designs over single-purpose tools.
Bottle Openers Market Segmentation
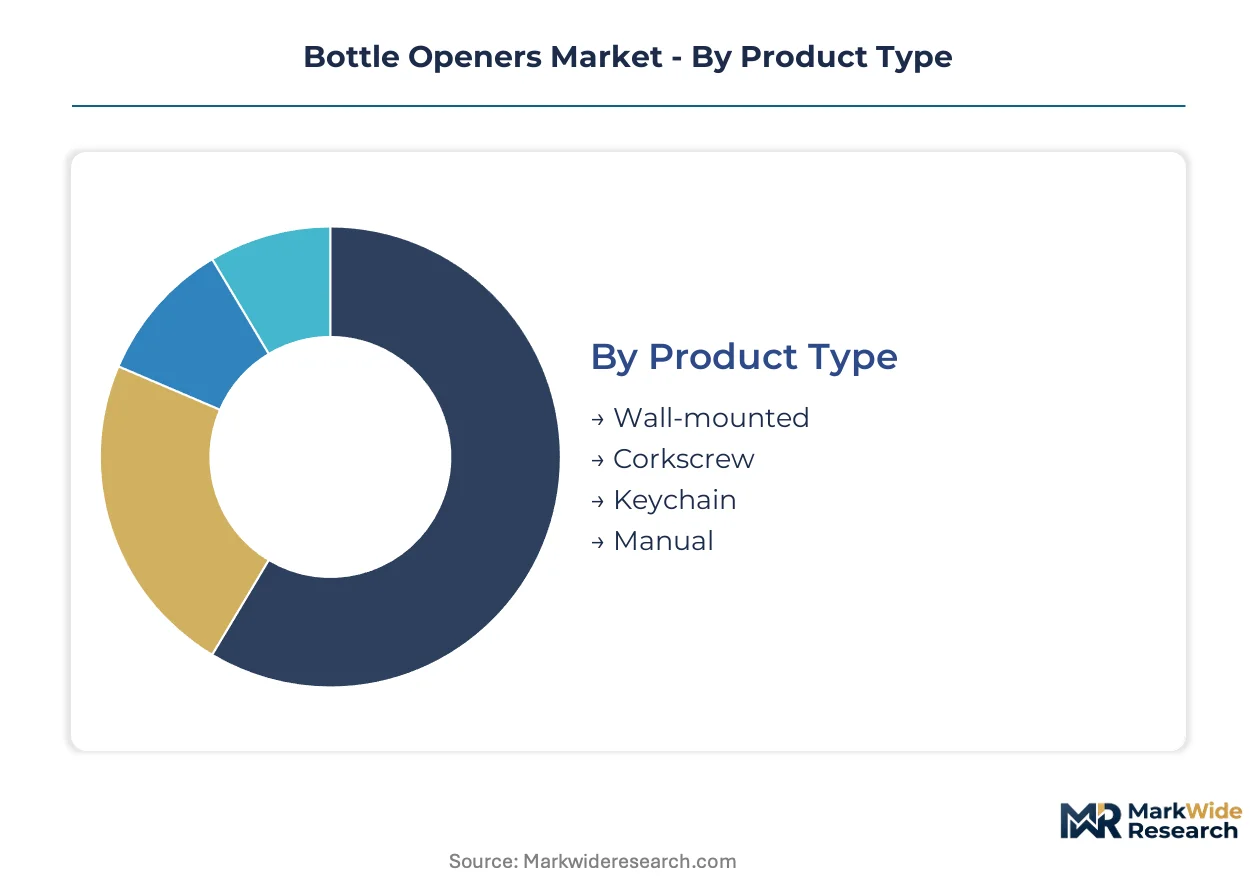
Segmentation in the bottle opener market reveals how procurement patterns bifurcate between speed-optimized commercial installations and aesthetics-driven residential purchases. Material and design specifications diverge sharply across these contexts, with regulatory compliance acting as a gatekeeper for foodservice channel access.
Product Type:
Supply concentration in forging and finishing capacity clusters favors manufacturers with dedicated tooling for high-throughput commercial formats.
- Wall-mounted:Permanently fixed lever systems with hardened steel pivots and magnetic cap catchers. Demand clusters in Barcelona and Madrid tapas bars where speed-focused designs align with high-volume service models.
- Manual:Handheld crown cap levers and waiter's friends with ergonomic grips. German craft brewery tasting rooms drive premium attachment rates for specialized lever designs.
- Corkscrew:Worm-and-lever mechanisms for wine service. Precision engineering requirements elevate unit margins in French and Italian hospitality procurement.
- Keychain:Miniaturized folding levers for portability. Promotional and gift-channel penetration expands through corporate branding and subscription wine club incentives.
Wall-mounted systems absorb the bulk of installed capacity in foodservice; keychain formats are expanding most quickly through promotional channels.
Material:
REACH substance restrictions and ECHA nickel release mandates are eliminating low-grade competitors from European supply chains.
- Stainless Steel:Surgical-grade 304 and 316 alloys with electropolished surfaces. Food-grade certification requirements under France's national consumer protection regulator filter out non-compliant suppliers from retail and foodservice tenders.
- Aluminum:Food-grade 6061 alloy with anodized or PVD coatings. Input cost volatility compresses margin buffers for mid-tier manufacturers unable to hedge commodity exposure.
- Wood:Certified sustainable hardwoods with food-safe oil finishes. CSRD-aligned carbon accounting favors suppliers with documented smelter electricity sources and regional sourcing.
- Plastic:Reinforced thermoplastics and recycled polymers. Virgin plastic displacement accelerates under EU Green Deal embodied carbon reporting requirements.
Stainless steel dominates food-contact applications; aluminum faces pressure from price volatility and regulatory scrutiny.
Usage:
Procurement authority separates high-volume specification from individual purchasing decisions.
- Bars:Speed-optimized wall-mounted systems and durable handheld tools. Urban hospitality clusters across France, Italy, and Spain concentrate replacement demand.
- Restaurants:Wine service precision tools and branded accessories. Extended producer responsibility schemes in France and Italy mandate material traceability for contract foodservice placement.
- Home:Aesthetics-driven purchases for kitchen drawer storage. Minimalist, multi-functional designs displace single-purpose tools in urban millennial demographics.
- Events:Disposable and promotional formats for temporary service. Bulk procurement bypasses traditional retail markups through direct sourcing.
Bars and restaurants absorb the bulk of commercial volume; home usage is climbing fastest through direct-to-consumer channel expansion.
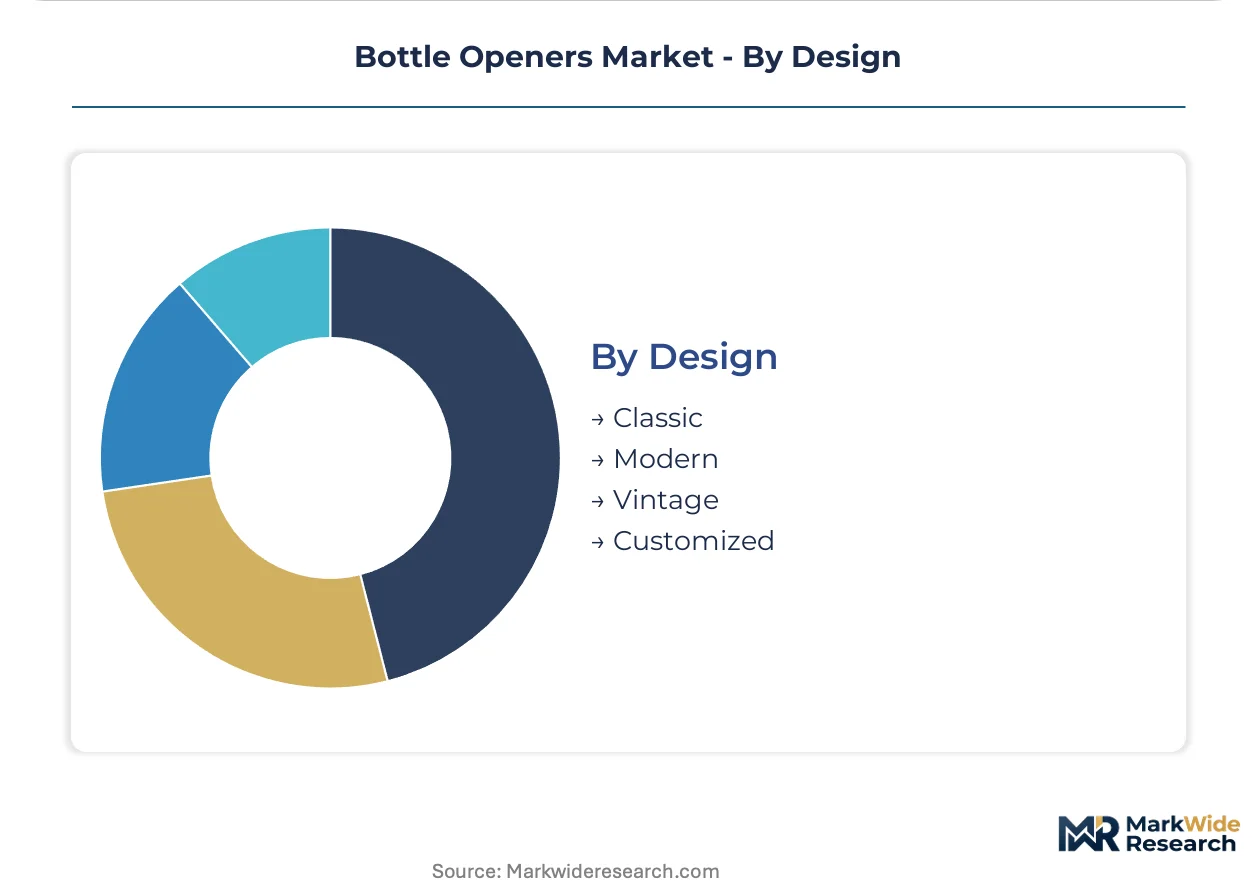
Design:
Heritage positioning versus modern minimalism creates pricing stratification across retail and hospitality channels.
- Classic:Traditional lever forms with utilitarian finishes. Established bar equipment suppliers maintain specification control through distributor relationships.
- Modern:Clean-lined geometries and integrated multi-tool functions. Joseph Joseph and design-led competitors capture premium positioning in contemporary kitchen environments.
- Vintage:Reproduction antique styling with patina finishes. Niche collectors and specialty retailers sustain limited production runs.
- Customized:Personalized engraving and limited edition releases. Anniversary and corporate gifting segments penetrate through subscription wine clubs and curated gift platforms.
Classic designs retain the largest installed base; customized formats are gaining share fastest through personalization services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian forging clusters supply European and North American distributors, while consumption concentrates in urban hospitality corridors and premium kitchenware retail. Regulatory divergence between REACH-governed markets and FDA-administered territories shapes material qualification protocols.
Germany
Craft brewery proliferation in Berlin and Munich drives specialized lever design demand for tasting room service. ECHA nickel release mandates filter non-compliant suppliers from food-contact procurement. Bavarian metalworking districts around Nuremberg maintain precision forging capacity for surgical-grade stainless components.
France
Wine service precision tools command premium placement in Paris and Lyon restaurant supply chains. ANSM enforces supplemental labeling standards for food-contact metal goods beyond baseline EU requirements. Auvergne-Rhône-Alpes enameled metal specialists face pressure to document smelter electricity sources under CSRD disclosure timelines.
United States
Subscription wine club bundling displaces standalone accessory purchases in coastal metropolitan markets. FDA food-contact substance regulations govern stainless steel composition for imported goods. California-based direct-to-consumer merchants anchor personalized engraving and limited edition release programs.
China
Zhejiang and Guangdong provinces concentrate forging and finishing capacity for export-oriented production. GB standards and SAMR market surveillance shape domestic product safety frameworks. Yangtze River Delta manufacturers are retooling for REACH-compliant material traceability to maintain European market access.
Italy
Bar and restaurant renovation cycles in Milan and Rome create specification windows for wall-mounted commercial systems. Extended producer responsibility schemes mandate material traceability for contract foodservice placement. Emilia-Romagna metalworking clusters supply precision-machined corkscrew mechanisms to French and German distributors.
Bottle Openers Market Vendor Landscape
The competitive structure tilts toward design-led premium specialists and scale-driven kitchenware conglomerates. Tiered positioning separates heritage enameled metal craftsmen from ergonomic patent holders and multi-tool integration specialists. Strategic moves concentrate on portfolio diversification into adjacent barware categories and direct-to-consumer channel bypass of traditional retail markups.
Among design-led kitchenware specialists, Joseph Joseph and OXO International exemplify divergent premium positioning strategies. Le Creuset occupies a heritage-tier position anchored in enameled metal craftsmanship. These three companies represent the primary competitive archetypes: modular design innovation, ergonomic patent families, and legacy brand equity respectively.
| Leading Market Players |
|---|
| Joseph Joseph |
| Le Creuset |
| OXO International |
| Chefman |
| Victorinox |
| Coravin |
| Vinocave |
| BarCraft |
| Oster |
| Others |
Supply Flow & Price Mechanics
Captive forging capacity in Nuremberg and Guangdong anchors both supply security and pricing power for precision metal components. European distributors with in-house finishing capabilities command premium placement against commodity importers facing REACH compliance penalties.
Pricing Analysis
Margin tightening in mid-tier aluminum formats reflects 6061 alloy price volatility and underutilized hedging instruments among small-scale producers. Three-tier pricing structure across premium, standard, and economy levels separates surgical-grade stainless certification from anodized aluminum and reinforced thermoplastic alternatives. Cost-down pressure on economy tiers accelerates because virgin plastic displacement under EU Green Deal carbon reporting erodes margin buffers. Foodservice procurement teams show lowest price sensitivity due to extended producer responsibility compliance requirements, while promotional keychain buyers exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Guangdong forging clusters that feed European finishing operations. Raw material flows draw from Indonesian nickel smelters, Australian bauxite refineries, and Swedish recycled steel processors. Regulatory restriction risk intensifies as ECHA SCIP database mandates propagate through supplier qualification protocols. Distribution runs through specialized kitchenware distributors in Germany and France, bypassing generalist retail for commercial hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface finishing expertise scarcity in European manufacturing bases props pricing for PVD coating and electropolishing specialists. Qualified suppliers capture premium placement as corrosion resistance quality drift eliminates low-grade competitors.
For Market Incumbents: Extend certification investments into CSRD-aligned carbon accounting to defend against emerging Asian entrants retooling for REACH compliance. Capture ESG-mandated procurement from hotel chains through third-party verified recycled content documentation. Deepen backward integration into surgical-grade stainless forging capacity around Nuremberg to reduce exposure to Guangdong supply disruption. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling offers the most penetrable route past established distributor relationships controlling retail shelf space. Target anniversary and corporate gifting segments through personalized engraving services bypassing traditional retail markups. Wine club incentive partnerships provide immediate volume traction without brick-and-tool storefront investment. For Investors and Strategic Acquirers: Exit pathways concentrate in design-led kitchenware conglomerates seeking modular multi-tool integration capabilities. Long-term viability favors targets with documented smelter electricity sources and regional European sourcing footprints. Watch ECHA nickel release mandate enforcement timelines as inflection indicators for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | ECHA nickel release mandates filter non-compliant competitors from food-contact procurement tenders. |
| CSRD Carbon Accounting Alignment | Scope 3 disclosure requirements favor early certifiers capturing ESG-mandated hotel chain contracts. |
| Direct-to-Consumer Channel Expansion | Subscription wine club bundling displaces traditional retail markups in urban millennial demographics. |
| Multi-Tool Integration Development | Swiss-designed cartridge systems compress SKU counts while elevating average unit values. |
| Regional Sourcing Documentation | Italian enameled metal specialists document smelter electricity sources to retain foodservice placement. |
Methodological Framework
Multi-period observation of REACH enforcement patterns and craft brewery expansion metrics anchored the trend analysis, supplemented by interviews with kitchenware brand managers, category buyers at German and French retail chains, hospitality procurement directors in Barcelona and Madrid, and precision forging plant managers in Bavaria. Secondary validation drew from ECHA substance restriction updates, EU Green Deal implementation timelines, customs trade data for aluminum and stainless steel imports, and SEC filings from listed kitchenware conglomerates. Bottom-up volume estimates triangulated against top-down market sizing.
Segment-weighting across product type, material composition, usage context, and design archetype shaped the analytical framework. CAGRs derived from regression analysis of historical volume patterns and elasticity-adjusted demand projections. Industry-specific forecast inputs included ECHA nickel release mandate compliance timelines and CSRD disclosure phase-in schedules.
Inputs from ECHA regulatory filings and European customs databases were available through the study window; gaps in real-time smelter electricity sourcing documentation introduce uncertainty bands around carbon intensity assumptions. Forecasts reflect documented assumptions regarding REACH enforcement consistency and aluminum price volatility persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Laptop Tables Market
Household Items
Sorting Hampers Market
Household Items
Massage Pillow Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Air Care Market
Household Items
Shower Heads and Systems Market
Household Items
United Kingdom Air Purifier Market
Household Items
China Cookware Market
Household Items
Smart Faucets Market
Household Items
Dishwashing Products Market
Household Items
Kitchen Towel Market
Household Items
Mosquito Trap Market
Household Items
Washing Machine Cleaner Market
Household Items
United States Barbeque Grill Market
Household Items
Hand Dryer Market
Household Items
Hands-Free Faucet Market