
 HEPA Vacuum Cleaners Market | 2026-2036
HEPA Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
HEPA Vacuum Cleaners Market Foresight
The HEPA vacuum cleaners market is recalibrating around a widening split between certified medical-grade systems and unverified consumer-grade alternatives that trade on loose marketing terminology. Dyson leverages cyclonic separation patents to justify premium positioning across cordless stick formats. Miele sustains its reputation through sealed-body engineering and intensive TÜV certification protocols that anchor its canister dominance in European healthcare procurement.
A HEPA vacuum cleaner employs a pleated mechanical filter capturing 99.97% of particles at 0.3 microns, with sealed airflow pathways preventing re-emission of trapped contaminants into occupied spaces. Robotic units are gaining fastest in residential settings where autonomous scheduling offsets higher upfront costs, while canister formats retain margin concentration in commercial and industrial end-use due to durability requirements and replaceable-component service models. Cordless technology is displacing corded designs in residential channels, though runtime limitations preserve corded dominance in industrial applications requiring continuous suction over extended duty cycles.
The EPA enforces emissions claims under FIFRA and FTC advertising standards, while the EU Ecodesign Directive and REACH framework constrain material choices and energy consumption thresholds for units sold in Europe. Stakeholders must monitor divergence between voluntary certification programs and mandatory regulatory thresholds, as jurisdictions tighten enforcement against HEPA-washing claims that misrepresent actual filtration performance.
Market Dynamics
The HEPA vacuum cleaners market is bifurcating around certification credibility, with sealed-system engineering separating medical-grade procurement from consumer-grade alternatives that rely on unverified marketing claims.
Growth Catalysts
- EPA emissions enforcement:The EPA's tightened particulate standards under FIFRA and FTC advertising rules compel manufacturers to certify true HEPA performance rather than rely on loose terminology.
- Healthcare facility expansion:Hospitals and clinics are expanding sealed-system procurement to contain airborne pathogens, prioritizing TÜV-certified filtration over cost-driven alternatives.
- Cordless lithium-ion advancement:Battery chemistry improvements are extending runtime in residential stick formats, enabling corded-level suction without tethering constraints.
Market Restraints
- Sealed-system cost premium:Medical-grade sealed-body engineering requires precision manufacturing and gasket materials that inflate unit economics beyond mass-market price tolerance.
- Filter replacement dependency:Genuine HEPA filter supply concentrates with certified manufacturers, creating aftermarket lock-in that raises total cost of ownership.
- Runtime limitations in cordless formats:Battery capacity constraints prevent continuous-duty operation in industrial settings requiring sustained suction over multi-hour cycles.
Strategic Opportunities
- Robotic autonomous penetration:Scheduling-enabled robotic units are gaining traction in residential settings where convenience offsets higher upfront capital requirements.
- EU Ecodesign Directive alignment:Energy consumption thresholds and material constraints under REACH are creating competitive advantage for manufacturers with compliant supply chains.
- Service-unbundling in commercial segments:Replaceable-component service models in canister formats enable recurring revenue streams through healthcare and industrial maintenance contracts.
Industry Challenges
- TÜV certification timeline compression:Third-party validation protocols for sealed-system performance extend product development cycles and delay market entry.
- HEPA-washing enforcement variance:Jurisdictional inconsistency in policing misrepresented filtration claims creates uneven competitive terrain between compliant and non-compliant suppliers.
- Legacy corded inventory rationalization:Industrial channel distributors face working capital strain from format transition as cordless gains erode corded demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HEPA Vacuum Cleaners Market |
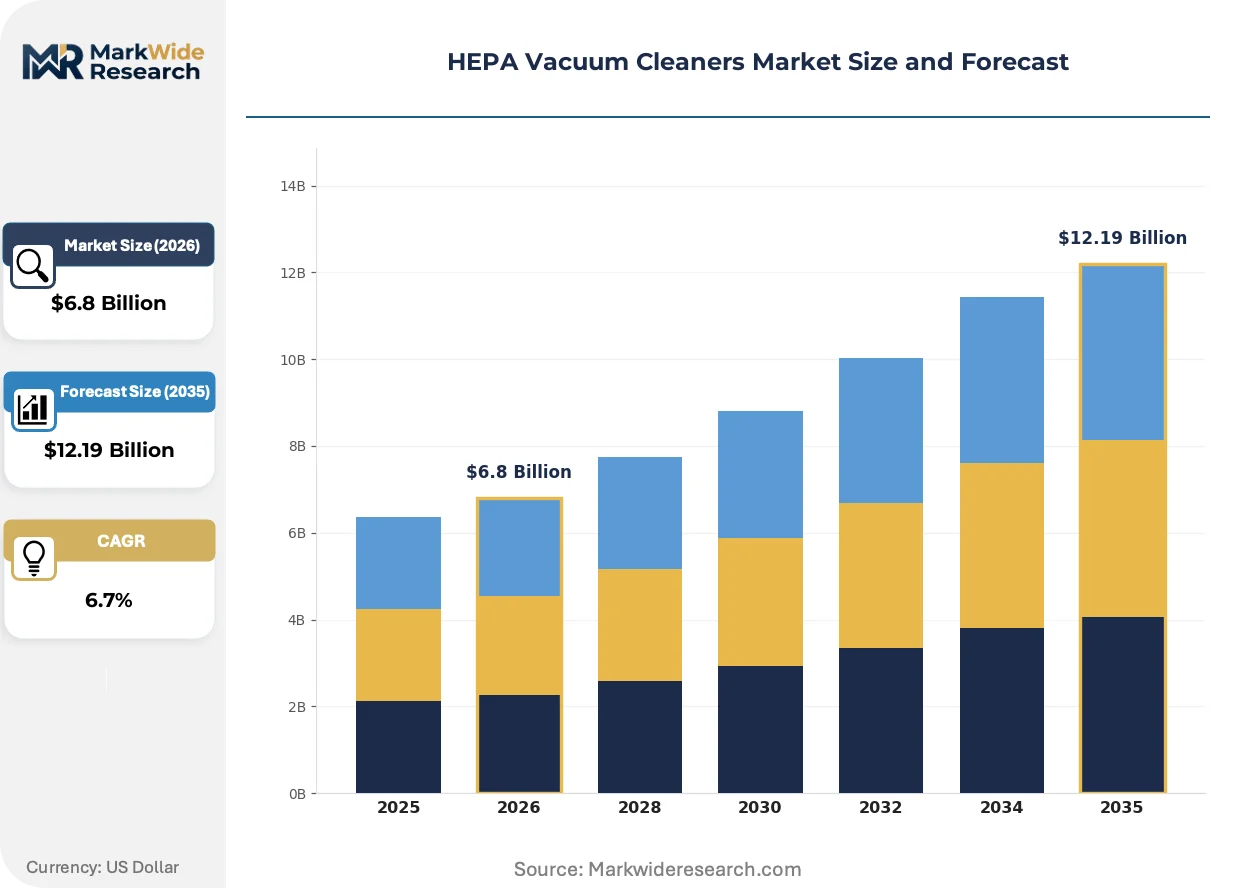
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Stick End User: Residential, Commercial, Industrial, Automotive Technology: Bagless, Corded, Cordless, Smart Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Dyson, Miele, SharkNinja, iRobot, Electrolux, Philips, Hoover, Bissell, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HEPA Vacuum Cleaners Market Shifts & Advancements
Cyclonic separation architectures are redefining suction mechanics, while regulatory pressure on emissions claims and autonomous scheduling capabilities are reshaping competitive positioning across residential and commercial channels.
Multi-stage cyclonic separation is consolidating around Dyson's patent-protected architectures that reduce filter loading and sustain airflow velocity. Residential buyers are adopting these systems at accelerating rates as cordless stick formats displace traditional upright designs. The technology is consolidating premium positioning by enabling bagless operation with maintained HEPA-grade exhaust quality.
REACH framework constraints on material choices and energy consumption thresholds are compelling European manufacturers to redesign motor housings and filtration media. The EU Ecodesign Directive's tightened standby power requirements are forcing component suppliers to requalify electrical subsystems. Canister formats sold in Germany face the strictest compliance burden, with TÜV certification now table stakes for healthcare procurement.
Facility managers are unbundling equipment purchase from maintenance service, favoring operational expenditure models that shift filter replacement and performance verification to OEM service networks. Industrial end-users in manufacturing and pharmaceutical cleanrooms are driving this transition, replacing capital-acquisition cycles with multi-year service agreements. Germany's healthcare procurement channels exhibit the most advanced service-contract penetration.
HEPA Vacuum Cleaners Market Segmentation
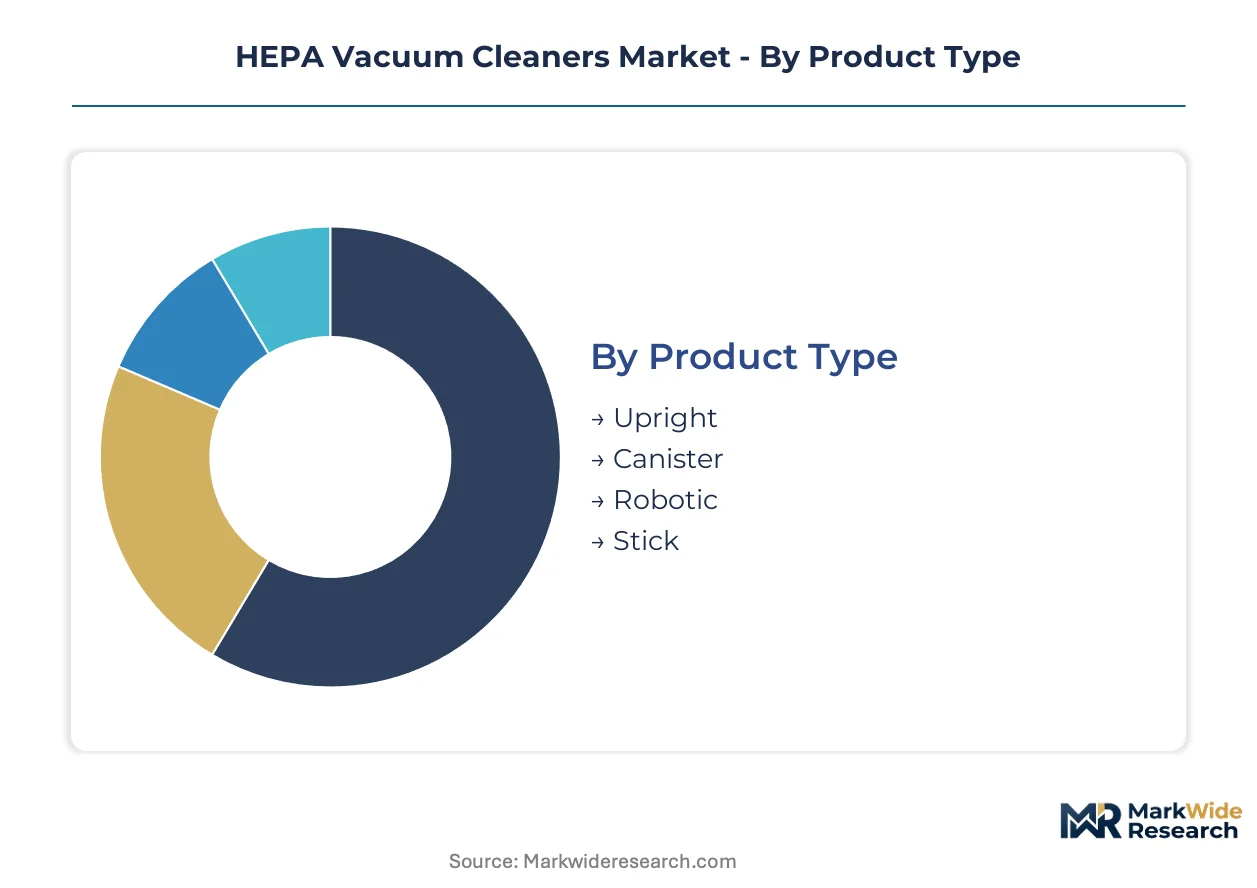
Segmentation in the HEPA vacuum cleaners market reveals how upgrade cycles and replacement timelines diverge sharply between residential convenience-seekers and institutional buyers prioritizing certified performance over unit cost. Procurement patterns across product formats, end-use environments, and distribution channels expose where margin concentrates versus where volume scales.
Product Type:
Replacement-cycle timing separates residential stick and robotic formats with 3-5 year refresh rates from institutional canister units engineered for decade-long service intervals.
- Canister:Sealed-body engineering with TÜV-certified filtration dominates European healthcare procurement. German hospitals specify these units for airborne pathogen containment, accepting premium pricing for validated performance documentation and service-contract availability.
- Stick:Cordless lithium-ion variants are displacing corded uprights in residential channels. Dyson's cyclonic separation patents anchor premium positioning here, though runtime limitations prevent industrial adoption.
- Upright:Traditional corded designs retain footholds in North American retail where consumer familiarity sustains volume despite format decline.
- Robotic:Autonomous scheduling capabilities attract residential buyers seeking convenience offset against higher upfront capital requirements.
Volume placements concentrate in Stick; the faster expansion belongs to Robotic.
End User:
Application severity dictates filtration certification requirements, with medical-grade sealed systems commanding structural margin premiums over consumer-grade alternatives.
- Healthcare:Sealed-system procurement concentrates in German clinics and hospitals where TÜV certification is mandatory for airborne pathogen containment. EPA emissions enforcement under FIFRA drives similar specification tightening in US facilities.
- Residential:Convenience-oriented buyers prioritize cordless stick formats and robotic scheduling over certified filtration performance, creating price-driven commoditization pressure.
- Industrial:Continuous-duty suction requirements preserve corded canister dominance in pharmaceutical cleanrooms and manufacturing environments.
- Automotive:Compact form factors and 12V power compatibility define this niche, with demand tied to professional detailing services rather than consumer replacement cycles.
Revenue concentration sits with Healthcare; Residential delivers the steepest volume scaling.
Technology:
Power delivery architecture and debris containment methods determine where bagless cyclonic separation gains traction against traditional bagged systems with certified sealed pathways.
- Cordless:Lithium-ion chemistry advances are extending runtime toward corded-equivalent suction in residential stick formats, though battery replacement costs inflate total ownership economics.
- Bagless:Cyclonic separation reduces filter loading and sustains airflow velocity, consolidating around patent-protected architectures that enable premium positioning without recurring bag purchases.
- Corded:Continuous power delivery preserves dominance in industrial settings requiring multi-hour suction cycles without interruption.
- Smart:Connectivity features and autonomous scheduling are gaining traction in robotic formats, though filtration certification lags behind mechanical system maturity.
Installed base remains Corded; Cordless climbs the fastest among replacement purchases.
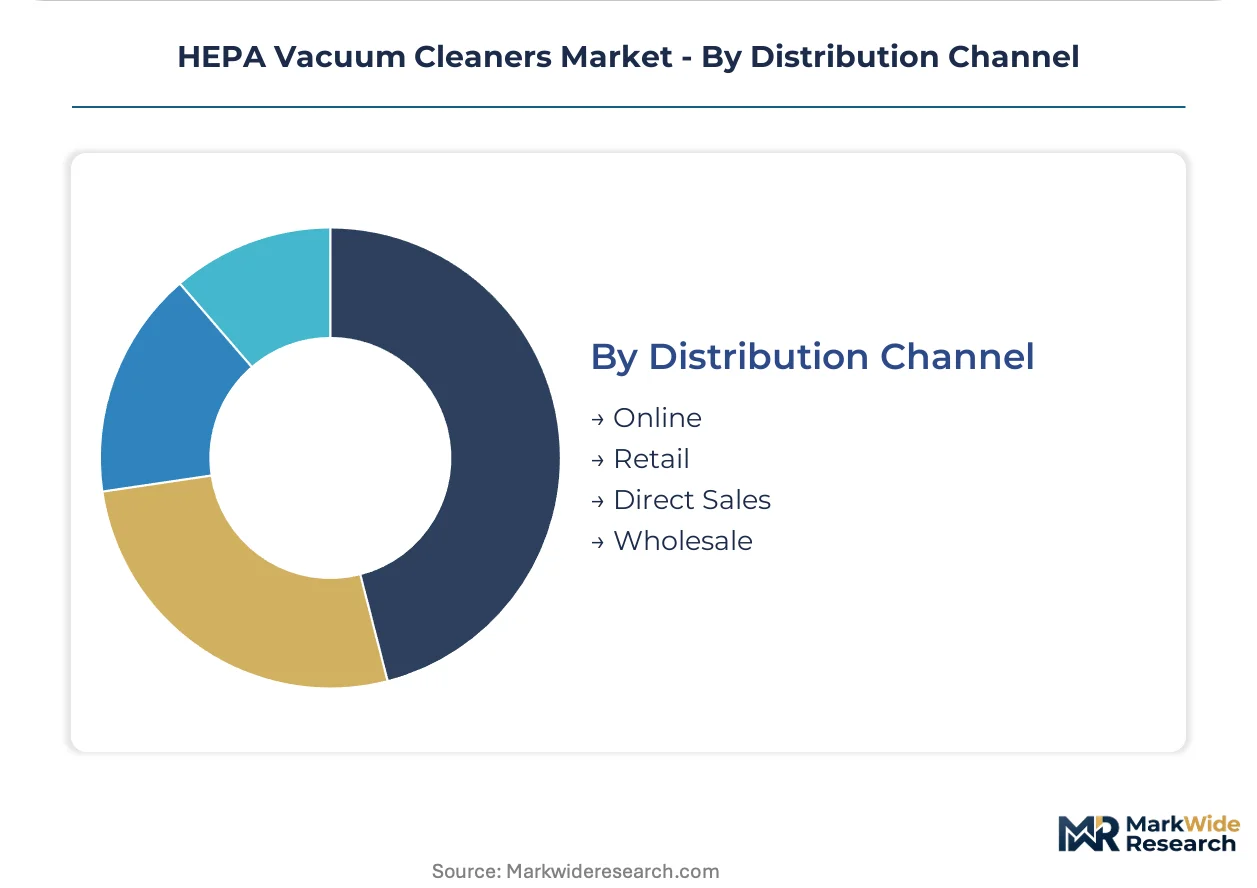
Distribution Channel:
Channel selection reflects buyer sophistication, with certified institutional procurement bypassing retail entirely while residential convenience drives online migration.
- Direct Sales:OEM service networks capture healthcare and industrial accounts through multi-year maintenance contracts bundling equipment, filter replacement, and performance verification.
- Online:E-commerce platforms concentrate residential stick and robotic volume, with review-driven discovery displacing in-store demonstration for tech-forward formats.
- Retail:Big-box and specialty stores retain upright and canister volume among buyers prioritizing physical inspection before purchase.
- Wholesale:Industrial distributors face working capital strain from format transition as cordless gains erode legacy corded inventory turns.
Transaction volume flows through Online; Direct Sales captures the structural margin premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European HEPA vacuum engineering through Miele's headquarters and the surrounding precision manufacturing corridor. This concentration shapes certification standards that propagate across procurement networks worldwide.
United States
Healthcare systems in Boston and Houston drive sealed-system procurement for airborne pathogen containment. EPA enforcement under FIFRA and FTC advertising standards compels manufacturers to verify HEPA performance claims rather than rely on marketing terminology. California's cleanroom manufacturing clusters around San Jose prioritize TÜV-certified filtration for semiconductor fabrication environments.
Germany
Hospital networks in Munich and Berlin mandate TÜV-certified canister systems for infection control protocols. The EU Ecodesign Directive and REACH framework constrain material selections and energy consumption thresholds for domestic manufacturers. Baden-Württemberg's industrial belt concentrates sealed-body engineering expertise that supplies healthcare procurement across continental Europe.
China
Shanghai's pharmaceutical manufacturing districts generate demand for medical-grade filtration in cleanroom environments. SAMR enforcement of GB standards and dual carbon goals pressure domestic producers to upgrade emissions performance documentation. Shenzhen's electronics assembly corridors adopt cordless stick formats for facility maintenance at scale.
Japan
Tokyo's dense residential market favors compact robotic units with autonomous scheduling capabilities. METI efficiency standards and JIS certification requirements filter non-compliant imports from mass-market distribution. Osaka's industrial machinery sector maintains corded canister dominance for continuous-duty manufacturing applications.
India
Delhi-NCR's hospital expansion drives initial sealed-system adoption despite price sensitivity in broader consumer channels. BIS quality standards and PLI scheme incentives encourage domestic assembly of certified filtration components. Maharashtra's pharmaceutical manufacturing clusters in Mumbai-Pune corridor specify imported canister systems for regulatory compliance.
HEPA Vacuum Cleaners Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure separating medical-grade sealed systems from consumer convenience formats. The market consolidates around three strategic archetypes: European precision engineers with certification heritage, Asian scale manufacturers driving cordless cost curves, and robotics specialists automating residential maintenance workflows. Competitive moves concentrate on M&A for filtration technology access and geographic expansion through regional certification partnerships.
Within the precision engineering tier, Miele GmbH and Dyson anchor premium positioning through divergent technical philosophies. Miele exemplifies sealed-body canister dominance validated by intensive third-party protocols, while Dyson occupies a position defined by cyclonic separation patents and cordless stick format leadership. LG Electronics represents the scale-driven archetype, leveraging electronics manufacturing integration to compress lithium-ion power system economics across mass-market distribution channels.
| Leading Market Players |
|---|
| Dyson |
| Miele |
| SharkNinja |
| iRobot |
| Electrolux |
| Philips |
| Hoover |
| Bissell |
| LG Electronics |
| Others |
Supply & Pricing Matrix
REACH compliance and the EU Ecodesign Directive gate qualified supply access and premium-tier pricing power in HEPA vacuum manufacturing. German and Dutch component suppliers command structural premiums for TÜV-certified filtration media and sealed-system gasket materials that mass-market assemblers cannot substitute without forfeiting healthcare procurement eligibility.
Pricing Analysis
Outcome-based pricing anchors medical-grade sealed systems where hospitals pay for validated pathogen containment performance rather than unit hardware. Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified canister systems from cordless stick convenience formats and unverified consumer alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with EPA emissions enforcement under FIFRA intensifying cost compression in non-compliant tiers. Residential buyers exhibit highest price sensitivity, while German healthcare procurement committees accept 40-60% premiums for documented filtration performance.
Supply Chain Analysis
Single-source vulnerability sits with precision-motor suppliers concentrated in Germany and Japan, where permanent-magnet motor engineering for sealed-system canisters remains captive to regional specialists. HEPA filtration media draws from glass microfiber producers in Germany and Switzerland, while lithium-ion battery cells feed from South Korean and Chinese chemistry specialists. Tariff exposure on Chinese-sourced electronics assemblies threatens cordless stick cost curves. Distribution runs through OEM service networks for institutional accounts and e-commerce platforms for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EPA and EU enforcement against HEPA-washing claims forces non-compliant assemblers from healthcare procurement channels. Manufacturers lacking TÜV or equivalent third-party validation face structural margin compression and volume exile.
For Market Incumbents: Anticipate regulatory divergence between jurisdictions by maintaining dual certification portfolios for EPA FIFRA compliance and EU REACH alignment. Prioritize backward integration into sealed-body gasket manufacturing to defend margin position against precision-component suppliers. Lock healthcare accounts through multi-year service contracts bundling filter replacement and performance verification before emerging robotics specialists automate maintenance workflows. For New Entrants and Emerging Players: Launch via direct-to-institutional sales targeting price-sensitive healthcare systems in India and Southeast Asia where TÜV certification is aspirational rather than mandatory. Exploit white space in robotic formats with HEPA-grade filtration for residential markets, where autonomous scheduling capabilities offset premium positioning against Dyson's cyclonic stick dominance. Target pharmaceutical cleanroom maintenance contracts in China as SAMR enforcement of GB standards creates compliance-driven replacement cycles. For Investors and Strategic Acquirers: EPA enforcement actions against HEPA-washing claims are the leading indicator that certification credibility is becoming the primary value driver across both institutional and residential channels. Position for 5-10 year viability by acquiring mid-scale European manufacturers with existing TÜV relationships and sealed-system engineering heritage. Monitor SAMR publication of revised GB filtration standards as the signal for Chinese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| TÜV Certification Investment | EPA FIFRA enforcement and EU procurement rules make third-party validation mandatory for healthcare access. |
| Sealed-System Manufacturing Scale-Up | Precision gasket and body engineering capacity concentrates margin capture in German industrial clusters. |
| Robotic Format Development | Autonomous scheduling capabilities unlock residential premium positioning against cyclonic stick alternatives. |
| Service Contract Unbundling | OEM maintenance networks transform capital equipment sales into recurring revenue streams with healthcare accounts. |
| REACH Compliance Program | ECHA material constraints and standby power thresholds filter non-compliant competitors from European distribution. |
Research Methodology
Document review covered EPA FIFRA enforcement records, ECHA REACH substance restrictions, TÜV certification protocols, and hospital procurement databases, complemented by interviews with biomedical engineering directors, healthcare GPO contracts managers, industrial maintenance heads, and aftermarket service network operators. Secondary validation drew from customs trade data for filtration media and motor components, SEC filings of listed appliance manufacturers, and EU Ecodesign Directive implementation reports. Bottom-up unit economics modeling triangulated against top-down market sizing across product format, end-use, and regional regulatory clusters.
Cross-referencing historical replacement cycle patterns with panel input from procurement committees and distribution channel heads anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format (canister, stick, upright, robotic), end-use severity (healthcare, residential, industrial, automotive), power delivery architecture (corded, cordless), and certification tier (TÜV-validated, EPA-verified, unverified). CAGRs were derived from installed base turnover rates and upgrade cycle compression in cordless formats, with specific inputs from lithium-ion battery cost curves and healthcare facility expansion pipelines.
Regulatory enforcement variance, battery chemistry substitution timelines, and jurisdictional divergence in HEPA-washing prosecution are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about certification timeline compression and cordless runtime improvement trajectories that may accelerate or stall based on R&D outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Robotic Vacuum Cleaner Market
Household Items
Air Mattress Market
Household Items
Smart Air Purifier Market
Household Items
Window Rain Guards Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Integrated Smart Toilet Market
Household Items
Residential Air Purifiers Market
Household Items
Canada Digital Showers Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
China Cookware Market
Household Items
Plastic Bathtub Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Bladeless Neck Fan Market
Household Items
Mosquito Trap Market
Household Items
Car Air Freshener Market