
 Chest Freezers Market | 2026-2036
Chest Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Chest Freezers Market Analytics
Energy Star 5.0 certification is reorganizing competitive priorities among chest freezer manufacturers. Whirlpool Corp. leverages its North American manufacturing footprint to sustain cost-competitive certified production. Midea America Corp. anchors its position through vertical integration into compressor and insulation supply. Haier differentiates via connected-temperature monitoring systems for commercial deployments.
Chest freezers are insulated, top-opening refrigeration appliances utilizing polyurethane foam insulation and hermetic compressor systems to maintain temperatures between minus eighteen and minus twenty-five degrees Celsius for long-term preservation of perishable goods. Deep freezers occupy the largest volume share within product-type segmentation due to entrenched household penetration across price-sensitive markets. Energy Star Certified units command premium positioning and superior margin pools, while commercial freezer demand among restaurants and supermarkets is expanding fastest as food safety protocols intensify cold-chain redundancy requirements.
The EPA Energy Star program and DOE appliance standards govern minimum efficiency thresholds and test procedures for units sold in the United States, directly influencing compressor selection and insulation thickness specifications. Ecodesign requirements under the EU F-Gas Regulation restrict refrigerant choices and mandate lower global-warming-potential alternatives, reshaping product development cycles for Electrolux Group and Liebherr-International GmbH. Stakeholders must monitor refrigerant-phase-down schedules and efficiency-tier migrations to align capital deployment with emerging compliance baselines.
Market Dynamics
Energy Star 5.0 compliance deadlines are compressing product development cycles and forcing simultaneous redesign of compressor architectures and insulation systems across the supplier base.
Growth Catalysts
- Restaurant cold-chain mandates:Food safety protocols in the United States and Brazil are mandating redundant freezer capacity for protein storage, accelerating commercial unit procurement.
- EU F-Gas phase-down:Lower global-warming-potential refrigerant requirements are triggering equipment refresh cycles as operators replace non-compliant legacy systems.
- Supermarket retrofit programs:Brazil's retail modernization initiatives are driving bulk freezer placements in São Paulo and Minas Gerais food retail corridors.
Market Restraints
- Polyurethane foam input volatility:Isocyanate and blowing-agent price swings compress margin predictability for insulation-dependent manufacturers.
- Hermetic compressor supply concentration:Production of high-efficiency compressor cores clusters among a limited set of Asian component specialists, creating single-source vulnerability.
- Refrigerant compatibility friction:EPA SNAP restrictions and EU F-Gas overlapping timelines force parallel inventory management for transitional refrigerant chemistries.
Strategic Opportunities
- Connected temperature monitoring convergence:Integration of IoT sensors with freezer hardware creates recurring-service revenue streams for commercial fleet operators.
- Rural electrification corridors:Grid extension programs in Brazil's interior states are opening first-time appliance penetration in previously unserved communities.
- Energy Star 5.0 certification premium:Certified units command measurable price premiums in US retail channels, rewarding early compliance investment.
Industry Challenges
- Thermodynamic engineering talent scarcity:Specialized expertise in low-global-warming-potential refrigerant system design remains concentrated among a narrow cohort of senior engineers.
- Dual certification timeline compression:Simultaneous EPA Energy Star 5.0 and DOE test procedure updates require parallel validation workflows, straining laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chest Freezers Market |
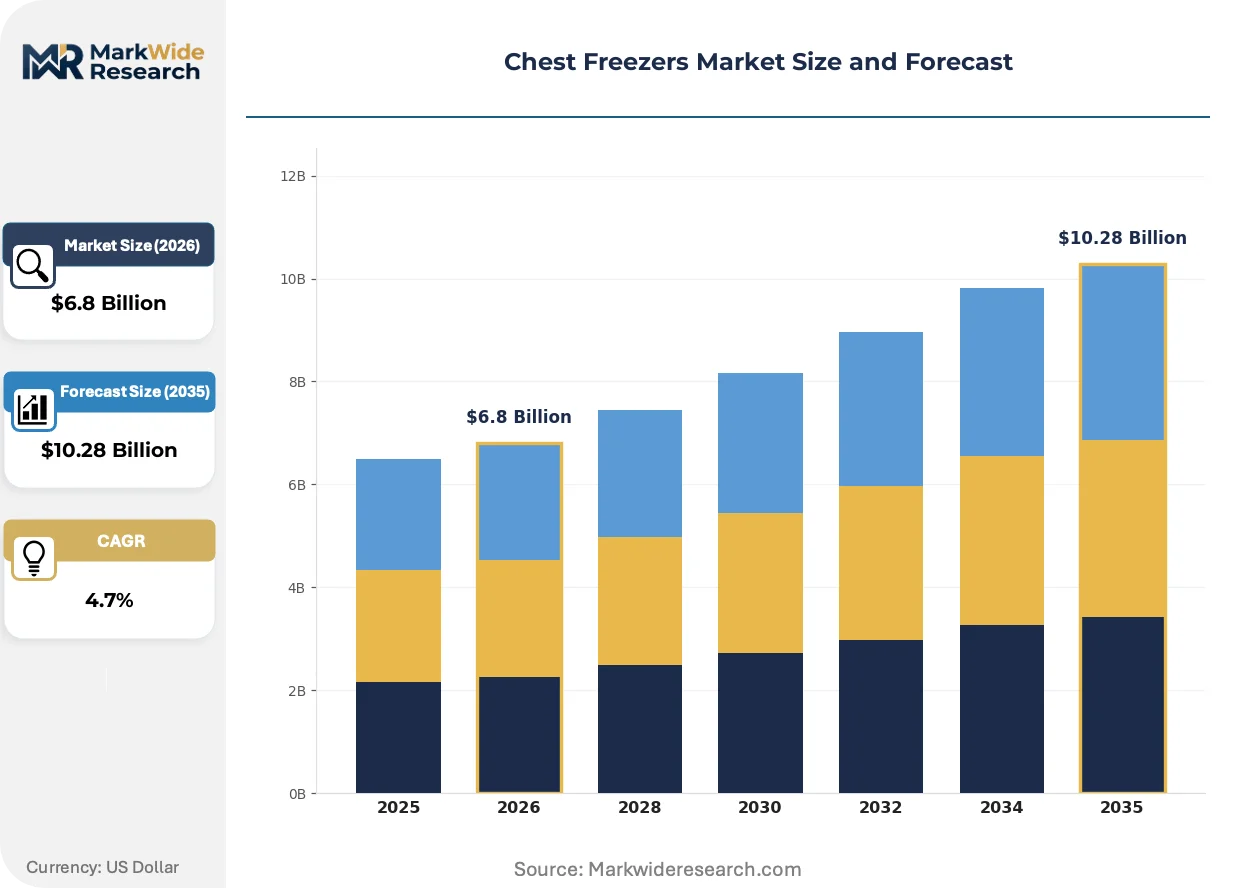
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright Freezers, Deep Freezers, Commercial Freezers, Convertible Freezers End User: Households, Restaurants, Supermarkets, Food Processors Application: Food Storage, Ice Production, Pharmaceutical Storage, Floral Preservation Energy Efficiency: Energy Star Certified, Standard Efficiency, High Efficiency, Low Energy Consumer |
| Companies Covered | LG Electronics, Midea America Corp., Whirlpool Corp., Electrolux Group, Haier, Hisense Inc., Frigidaire, Danby, Liebherr-International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chest Freezers Market Evolving Landscape
Refrigeration hardware is undergoing simultaneous pressure from refrigerant chemistry transitions and digital connectivity integration, reshaping how manufacturers organize R&D and field service operations.
Vacuum-insulation-panel technology is fragmenting traditional polyurethane-foam dominance in premium freezer segments. High-end commercial buyers in the United States and Germany are specifying VIP cores for thickness-constrained installations. This material shift is fragmenting supplier relationships as foam-in-place equipment investments depreciate against flat-panel assembly lines.
EPA Energy Star 5.0 test procedure revisions are tightening maximum energy-consumption thresholds for units under twenty-five cubic feet. Manufacturers must now validate compressor cycling efficiency across wider ambient-temperature ranges. The residential and light-commercial segments are responding by consolidating model variants to amortize certification costs across higher production volumes.
Foodservice procurement is consolidating freezer purchasing through national distributor contracts rather than fragmented local equipment dealers. Large restaurant chains in the United States are mandating standardized connected-freezer specifications across franchise locations. This pattern is most visible in quick-service and fast-casual verticals where central procurement controls equipment uniformity.
Chest Freezers Market Segmentation
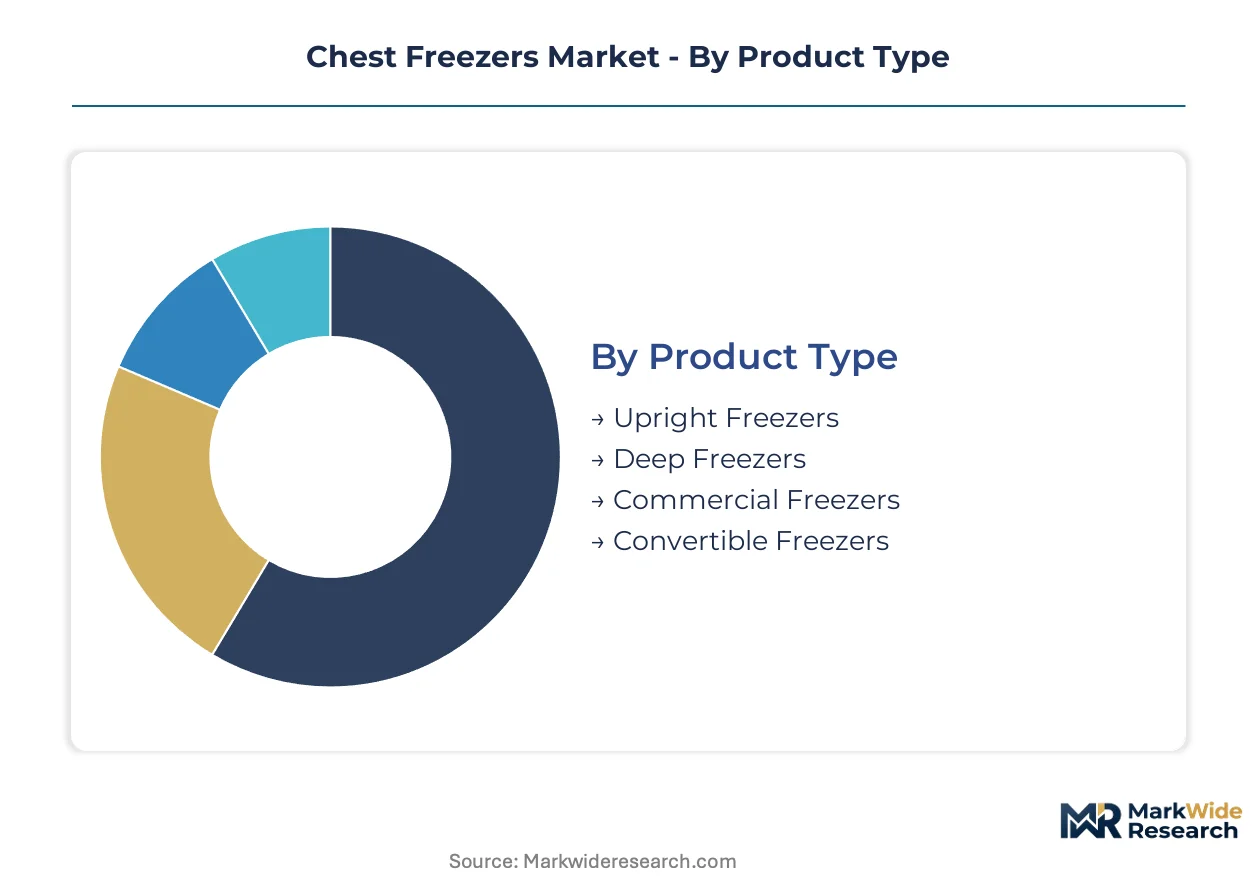
Chest freezer segmentation reflects divergent compliance burdens across residential and commercial deployments. EPA Energy Star 5.0 thresholds and EU F-Gas refrigerant mandates create tiered cost structures that reshape procurement patterns by product type and end user.
Product Type:
Regulatory differentiation separates residential-certified units from commercial-grade systems facing stricter DOE test procedures and NSF sanitation standards.
- Deep Freezers:Horizontal-lid polyurethane-foam insulated cabinets with hermetic compressor systems dominate household penetration across price-sensitive markets. Demand concentrates in Brazil's rural electrification corridors where first-time appliance acquisition outpaces replacement cycles.
- Commercial Freezers:Reinforced stainless-steel construction with forced-air circulation supports restaurant cold-chain redundancy mandates. Procurement accelerates in São Paulo and Minas Gerais food retail corridors where supermarket retrofit programs drive bulk unit placements.
- Upright Freezers:Vertical-door configurations optimize floor-space efficiency for constrained urban households.
- Convertible Freezers:Dual-mode refrigeration/freezer operation appeals to seasonal harvest preservation in agricultural communities.
Established volume favors Deep Freezers; emerging adoption favors Commercial Freezers.
End User:
Cost tier separation distinguishes mass-market residential procurement from premium commercial fleet specifications with connected monitoring requirements.
- Restaurants:Food safety protocol intensification mandates redundant protein storage capacity with temperature logging compliance. United States quick-service chains consolidate purchasing through national distributor contracts specifying standardized connected-freezer specifications.
- Supermarkets:Brazil's retail modernization initiatives drive high-volume freezer bank installations with remote temperature monitoring integration.
- Households:Price-sensitive acquisition patterns favor basic insulation and compressor efficiency tiers.
- Food Processors:Bulk ingredient preservation requirements specify heavy-duty compressor cycling durability.
Volume concentration sits with Households; specification complexity climbs fastest among Restaurants.
Application:
Application-driven margin structures separate commodity food preservation from specialized pharmaceutical cold-chain segments with validation documentation requirements.
- Food Storage:Long-term protein and produce preservation at minus eighteen to minus twenty-five degrees Celsius constitutes the core functional specification across residential and commercial deployments.
- Pharmaceutical Storage:Vaccine and biologic cold-chain compliance demands calibrated temperature uniformity with continuous data logging for FDA and EMA regulatory submission.
- Ice Production:Dedicated freezing plates optimize crystal formation for foodservice and hospitality bulk ice requirements.
- Floral Preservation:Humidity-controlled low-temperature environments extend cut-flower shelf life for retail distribution.
Commodity scale favors Food Storage; margin premium concentrates in Pharmaceutical Storage.
Energy Efficiency:
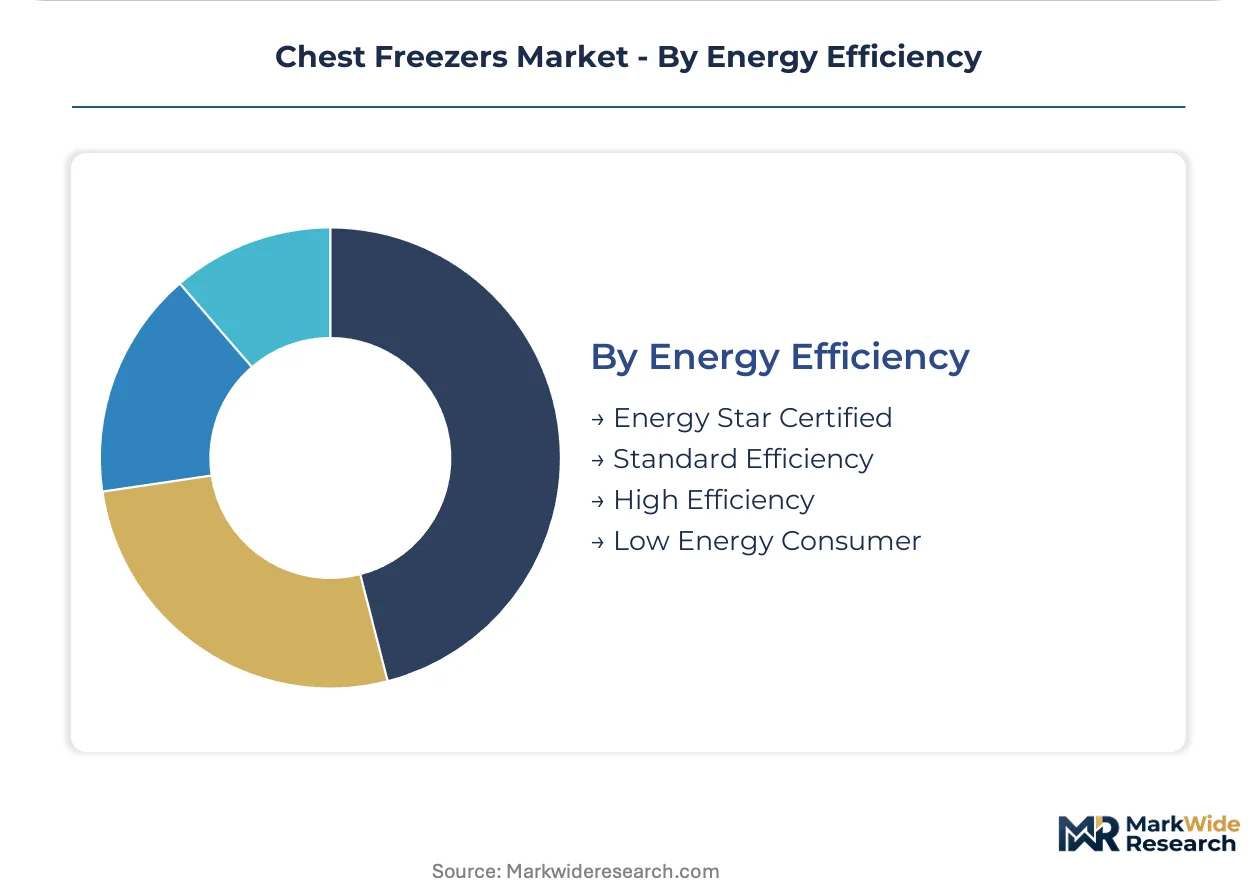
Certification grade determines pricing stratification and channel access, with Energy Star 5.0 compliance becoming a threshold requirement for major retail distribution.
- Energy Star Certified:Validated compressor cycling efficiency and insulation thermal resistance meeting EPA maximum consumption thresholds command measurable price premiums in US retail channels.
- High Efficiency:Advanced insulation thickness and variable-speed compressor operation target utility rebate eligibility and total-cost-of-ownership buyers.
- Standard Efficiency:Baseline hermetic compressor and polyurethane-foam construction serves replacement markets with minimal regulatory exposure.
- Low Energy Consumer:Basic specification units penetrate extreme price-sensitive segments with limited electricity access or intermittent grid reliability.
Certification premium accrues to Energy Star Certified; volume foundation rests with Standard Efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports chest freezer units throughout Latin America while importing compressor components from China. Trade corridors connect São Paulo manufacturing clusters to Argentine and Chilean retail distribution networks.
United States
Restaurant cold-chain mandates and supermarket retrofit programs accelerate commercial freezer procurement. EPA Energy Star 5.0 specifications tighten insulation standards and compressor benchmarks for units under twenty-five cubic feet. Procurement concentrates in Texas and California foodservice corridors where quick-service chains consolidate national distributor contracts.
Brazil
Supermarket modernization initiatives and food processor capacity additions drive bulk unit placements. ANVISA food safety protocols mandate redundant cold-chain infrastructure for protein storage. São Paulo and Minas Gerais retail corridors host accelerating freezer bank installations with remote temperature monitoring integration.
Germany
EU F-Gas Regulation phase-down schedules trigger equipment refresh cycles as operators replace non-compliant legacy systems. Ecodesign requirements restrict refrigerant choices and mandate lower global-warming-potential alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia reshape product development cycles for premium commercial deployments.
China
Domestic appliance demand and compressor component manufacturing anchor supply-side capacity. GB standards and MIIT efficiency directives govern minimum performance thresholds for domestic sales. Yangtze River Delta and Pearl River Delta production bases supply hermetic compressor cores to global assembly operations.
India
Rural electrification programs and first-time appliance penetration expand household freezer adoption. BIS appliance standards and FSSAI cold-chain mandates create tiered compliance structures for residential and commercial segments. Maharashtra and Gujarat distribution networks channel units into previously unserved agricultural communities.
Chest Freezers Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base organizes around three strata: multinational appliance conglomerates with full-category portfolios, regional specialists with captive component supply, and private-label fabricators serving price-sensitive channels. Two strategic archetypes dominate: vertically integrated manufacturers controlling compressor and insulation supply, and connectivity-focused providers bundling hardware with IoT monitoring services. Competitive moves concentrate on Energy Star 5.0 certification racing and Brazilian distribution network expansion.
Among multinational appliance conglomerates, Whirlpool Corp. and Electrolux Group occupy positions representing scale-driven certification compliance. Midea America Corp. anchors the specialist tier with upstream control over compressor manufacturing. Haier exemplifies the connectivity-focused archetype through integrated temperature monitoring systems for commercial fleet deployments.
| Leading Market Players |
|---|
| LG Electronics |
| Midea America Corp. |
| Whirlpool Corp. |
| Electrolux Group |
| Haier |
| Hisense Inc. |
| Frigidaire |
| Danby |
| Liebherr-International GmbH |
| Others |
Value Network & Pricing Analysis
Compressor manufacturing scale economies in China and Thailand anchor global supply concentration, simultaneously depressing price floors for standard-efficiency units while creating margin pressure for non-integrated assemblers. This scale dynamic forces tiered pricing stratification: Energy Star 5.0 certified units from vertically integrated manufacturers command premium positioning, while commodity polyurethane-foam dependent producers compete on input-cost volatility absorption.
Pricing Analysis
Next-generation refrigerant chemistry pricing gaps separate F-Gas compliant R290 systems from legacy HFC units and emerging CO2 cascade architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and compressor efficiency tier differentiation. Pricing pressure stems from polyurethane foam input volatility as isocyanate and blowing-agent costs swing unpredictably. Household buyers in Brazil and India exhibit extreme price sensitivity, while US restaurant chains prioritize total-cost-of-ownership over acquisition cost.
Supply Chain Analysis
Inventory lead times for hermetic compressor cores have extended as production concentrates among Yangtze River Delta and Pearl River Delta specialists. Supply draws from China for compressor manufacturing, Brazil for cabinet assembly, and Germany for vacuum insulation panel technology. Raw material dependencies center on MDI isocyanates, hydrocarbon refrigerants, and cold-rolled steel. Single-source vulnerability in high-efficiency compressor cores creates structural risk. Distribution runs through national appliance retailers in the United States, supermarket procurement consortia in Brazil, and fragmented dealer networks in rural India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected temperature monitoring platforms are repositioning chest freezers from capital equipment to subscription-enabled infrastructure, with IoT integration creating interoperability standards that favor ecosystem-ready manufacturers over hardware-only suppliers.
For Market Incumbents: Consolidate compressor supply security through backward integration or long-term offtake agreements with Yangtze River Delta specialists, as hermetic core concentration creates single-source vulnerability. Lock in Energy Star 5.0 certification ahead of DOE test procedure updates to defend retail channel access against emerging connectivity-focused competitors. For New Entrants and Emerging Players: Energy Star 5.0 certification fast-track through third-party laboratory partnerships opens US retail channel access currently blocked to uncertified imports. Target Brazil's rural electrification corridors in Minas Gerais and interior São Paulo states where first-time appliance penetration outpaces replacement demand. Lead with solar-compatible low-energy-consumption units optimized for intermittent grid reliability. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive compressor supply and connected-fleet service revenue streams over pure hardware assemblers. Long-term viability hinges on refrigerant-transition readiness and IoT platform attach rates. The signal to watch is supermarket procurement consolidation toward national distributor contracts specifying standardized connected-freezer specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Star 5.0 Certification Acceleration | EPA compliance thresholds now gate US retail channel access for units under twenty-five cubic feet. |
| Backward Integration into Compressor Manufacturing | Yangtze River Delta production concentration creates margin capture opportunity for integrated assemblers. |
| IoT Temperature Monitoring Platform Launch | Restaurant cold-chain mandates in Texas and California foodservice corridors drive recurring-service revenue potential. |
| Brazil Distribution Network Expansion | São Paulo and Minas Gerais retail corridors host accelerating supermarket retrofit program procurement. |
| R290 Hydrocarbon Refrigerant Transition | EU F-Gas phase-down schedules trigger equipment refresh cycles requiring compliant system architectures. |
Research Methodology
The analysis maps deep freezer, commercial freezer, and convertible freezer sub-sectors, each validated through appliance manufacturing executives, commercial foodservice procurement directors, and supermarket facilities managers. Primary interview insights triangulate against secondary sources including EPA Energy Star certification databases, ANVISA food safety protocol filings, and Brazil's BIS-equivalent appliance standards documentation. Bottom-up unit shipment estimates by product type and end user reconcile with top-down market value assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation by product type, end user, application, and energy efficiency tier, with regional regulatory cluster as an additional dimension. CAGRs derive from fitted growth curves applied to validated baseline estimates, incorporating compressor efficiency improvement trajectories and refrigerant-phase-down compliance timelines as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of continued EPA Energy Star 5.0 enforcement and EU F-Gas phase-down adherence; material deviation in regulatory timelines or refrigerant chemistry transitions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Aquarium Hydrometers Market
Household Items
Steam Cleaners Market
Household Items
Shoe Dryer Market
Household Items
Global Electric Scissors Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Dishwasher Tablets Market
Household Items
Enameled Cookware Market
Household Items
Jet Hand Dryer Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Compressed Tablet Towel Market
Household Items
Flatware Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Insulated Lunch Box Market
Household Items
Cookware Market