
 Tumor Lysis Syndrome Treatment Market | 2026-2036
Tumor Lysis Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Lysis Syndrome Treatment Market Analytics
EMA's updated oncology biomarker qualification framework is rebalancing the cost-of-entry calculus for novel TLS therapeutics across European markets. Sanofi leverages its established allopurinol manufacturing scale to sustain supply security for high-volume hospital contracts. Roche anchors its position through specialized diagnostics integration that supports prophylactic rasburicase decision-making. Takeda Pharmaceutical Company Limited competes via differentiated febuxostat positioning in oral prophylaxis segments.
Tumor Lysis Syndrome Treatment encompasses pharmacologic and fluid-based interventions designed to prevent or manage the metabolic derangements—hyperuricemia, hyperkalemia, hyperphosphatemia, and hypocalcemia—that follow rapid malignant cell lysis during chemotherapy induction. Rasburicase dominates the product type landscape due to its enzymatic uric acid degradation mechanism, while hydration solutions represent the mature baseline standard with compressed margins. The therapy area segmentation shows acute lymphoblastic leukemia commanding the largest addressable population, with non-Hodgkin lymphoma representing the fastest-growing indication as aggressive B-cell protocols expand.
FDA oncology drug guidance shapes trial design requirements for TLS prophylaxis endpoints, while EMA pediatric investigation plans mandate age-stratified safety data that extend development timelines. The country's national pharmaceutical regulators in Japan enforce localized pharmacokinetic bridging studies that filter market access for foreign-origin biologics. Stakeholders must monitor evolving prophylaxis guidelines from major hematology societies that will determine whether intravenous rasburicase or oral febuxostat becomes the standard-of-care anchor in intermediate-risk patient stratification.
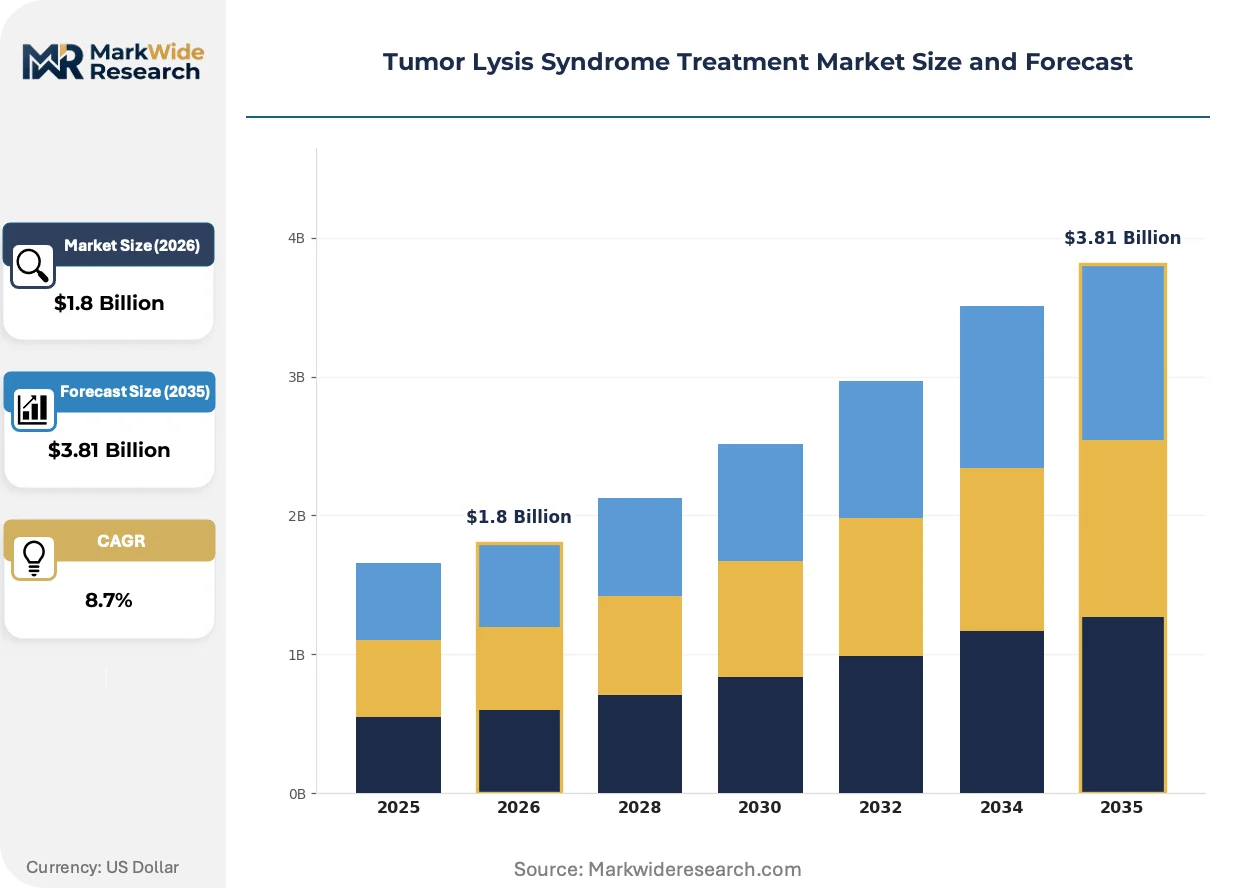
Market Dynamics
FDA oncology drug guidance and EMA pediatric investigation plans are compressing development timelines while simultaneously expanding the evidence burden for TLS prophylaxis approvals, forcing sponsors to front-load biomarker strategy and age-stratified safety architecture.
Growth Catalysts
- Expanding aggressive B-cell protocols:Non-Hodgkin lymphoma treatment intensification in academic medical centers is widening the addressable population for enzymatic uric acid management.
- EMA biomarker qualification framework:Streamlined validation pathways for predictive hyperuricemia markers are reducing regulatory friction for novel therapeutic entrants across European markets.
- Specialized cancer center proliferation:Japan's designated cancer hospital network and Germany's comprehensive cancer center certification program are institutionalizing prophylactic TLS protocols as standard induction care.
Market Restraints
- Rasburicase manufacturing concentration:Recombinant enzyme production capacity clusters with a limited supplier base, creating vulnerability to batch contamination or yield shortfalls.
- Febuxostat cardiovascular safety signals:Post-marketing surveillance data linking oral urate-lowering therapy to cardiac events in oncology populations has triggered prescriber caution and formulary restrictions.
- PMDA pharmacokinetic bridging requirements:Japan's national pharmaceutical regulator mandates localized exposure studies for foreign-origin biologics, extending market access timelines by 18-24 months.
Strategic Opportunities
- Intermediate-risk stratification protocols:Underdefined clinical guidelines between low-risk hydration-only and high-risk rasburicase patients create white space for oral prophylaxis positioning.
- Diagnostics-therapeutics convergence:Real-time uric acid monitoring integration with automated dosing algorithms represents unclaimed value in closed-loop TLS management.
- India's CDSCO oncology pathway:Accelerated approval mechanisms for drugs addressing unmet needs in hematologic malignancies offer expedited entry for differentiated mechanisms.
Industry Challenges
- Pediatric formulation development:Age-appropriate dosing delivery for neonates and infants requires specialized stability testing and palatability engineering that extends CMC timelines.
- Cold chain integrity across emerging markets:Rasburicase temperature sensitivity demands validated distribution infrastructure that many hospital procurement systems lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Lysis Syndrome Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allopurinol, Rasburicase, Febuxostat, Hydration Solutions Therapy Area: Acute Lymphoblastic Leukemia, Non-Hodgkin Lymphoma, Acute Myeloid Leukemia, Chronic Lymphocytic Leukemia Delivery Mode: Intravenous, Oral, Subcutaneous, Prophylactic End User: Oncology Clinics, Hospitals, Research Institutes, Outpatient Facilities |
| Companies Covered | Sanofi, Roche, Takeda Pharmaceutical Company Limited, AstraZeneca, Harman Finochem, Ironwood Pharmaceuticals, Mylan, Bristol-Myers Squibb Company, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Lysis Syndrome Treatment Market Evolving Landscape
Enzymatic uric acid degradation is converging with point-of-care metabolic monitoring, while regulatory frameworks on both sides of the Atlantic are hardening evidentiary standards for prophylaxis labeling claims.
Subcutaneous rasburicase formulations are integrating sustained-release polymer matrices that extend enzymatic half-life from 18 hours to 72 hours, reducing infusion burden. Outpatient oncology clinics in the United States are piloting these depot injections for intermediate-risk lymphoma patients, compressing hospitalization requirements and shifting site-of-care economics toward ambulatory settings.
REACH-compliant manufacturing audits are reshaping supplier qualification for recombinant biologics used in EU oncology protocols. EMA's tightened expectations for host cell protein documentation and viral clearance validation are filtering contract manufacturer selection, with German and French hospital consortia now requiring full supply chain transparency from fermentation through fill-finish.
Oncology pharmacy directors are consolidating purchasing decisions through integrated delivery networks rather than individual hospital formulary committees. This buyer concentration in the United States is compressing price negotiation cycles and demanding outcome guarantees on TLS prophylaxis efficacy, with Texas and Florida cancer networks leading the shift toward risk-sharing arrangements based on hyperuricemia event rates.
Tumor Lysis Syndrome Treatment Market Segmentation
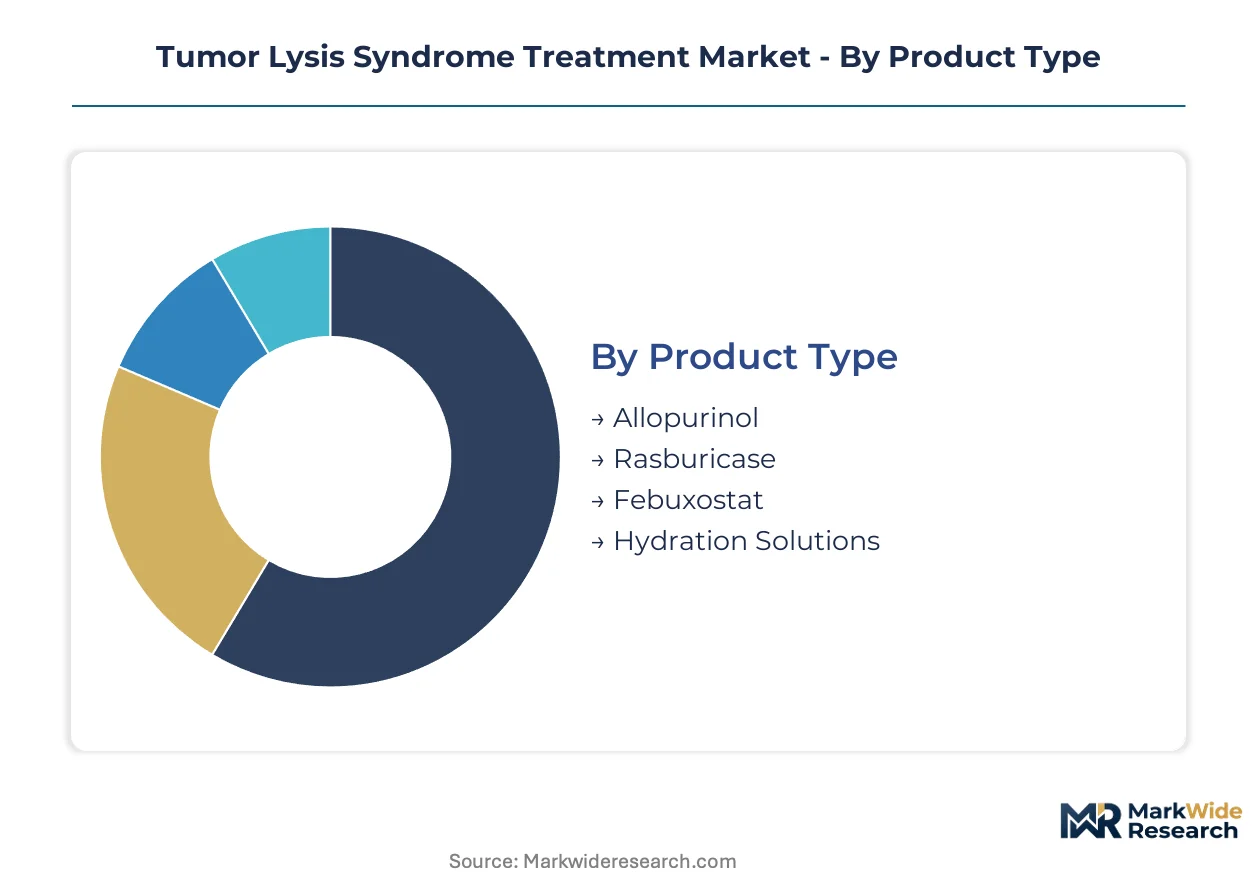
TLS treatment segmentation reveals how clinical risk stratification, reimbursement pathways, and site-of-care economics fragment purchasing authority across oncology settings. Supply concentration in recombinant enzyme manufacturing and oral generic commoditization create divergent margin profiles that reshape competitive positioning.
Product Type:
Recombinant uric acid oxidase production clusters with a limited supplier base, while oral xanthine oxidase inhibitors face commoditized pricing pressure.
- Rasburicase:Recombinant uric acid oxidase enzyme catalyzes uric acid conversion to allantoin, enabling rapid clearance in high-risk chemotherapy induction. Demand concentrates in academic medical centers managing aggressive B-cell lymphoma protocols, where enzymatic efficacy justifies premium reimbursement despite cold chain complexity.
- Allopurinol:Generic xanthine oxidase inhibitor blocks uric acid synthesis through competitive enzyme inhibition, representing the established oral standard for low-to-intermediate risk patients. Volume concentrates in Germany and Japan where hospital formularies prioritize cost containment over enzymatic speed.
- Febuxostat:Non-purine selective xanthine oxidase inhibitor offers oral bioavailability without allopurinol metabolite requirements.
- Hydration Solutions:Isotonic crystalloid infusions maintain renal perfusion and electrolyte dilution as foundational prophylaxis.
Rasburicase absorbs the bulk of installed capacity; Febuxostat is expanding most quickly.
Therapy Area:
Leukemia-lymphoma incidence patterns and treatment intensity determine prophylaxis protocol selection across hematology services.
- Acute Lymphoblastic Leukemia:Pediatric and adult ALL induction regimens produce rapid blast lysis requiring standardized rasburicase prophylaxis in high-burden presentations. Demand clusters in specialized cancer centers in the United States and Germany where pediatric investigation plans mandate enzymatic coverage.
- Non-Hodgkin Lymphoma:Aggressive B-cell subtypes treated with dose-intense R-CHOP and CAR-T preconditioning generate intermediate-to-high TLS risk profiles. Academic medical centers in Japan are expanding prophylactic protocols fastest as CD19-directed therapy adoption accelerates.
- Acute Myeloid Leukemia:High-burden AML induction with cytarabine-anthracycline combinations drives institutional rasburicase stocking.
- Chronic Lymphocytic Leukemia:BTK inhibitor and venetoclax protocols create delayed TLS risk requiring extended monitoring.
Acute Lymphoblastic Leukemia commands the largest addressable population; Non-Hodgkin Lymphoma is climbing the fastest.
Delivery Mode:
Route selection reflects site-of-care economics, patient risk stratification, and reimbursement bundling across oncology settings.
- Intravenous:Hospital-based infusion of rasburicase and hydration enables immediate therapeutic intervention with nursing supervision. Demand concentrates in inpatient oncology units where bundled payment models favor acute care containment over readmission risk.
- Oral:Outpatient allopurinol and febuxostat administration supports ambulatory prophylaxis for intermediate-risk patients with reliable adherence. Oncology clinics in the United States are piloting oral-first protocols fastest as integrated delivery networks push site-of-care migration.
- Subcutaneous:Sustained-release depot formulations extend enzymatic half-life for intermediate-risk lymphoma patients.
- Prophylactic:Pre-emptive protocol initiation before chemotherapy exposure dominates evidence-based guidelines.
Intravenous absorbs the bulk of installed capacity; Oral is gaining share fastest.
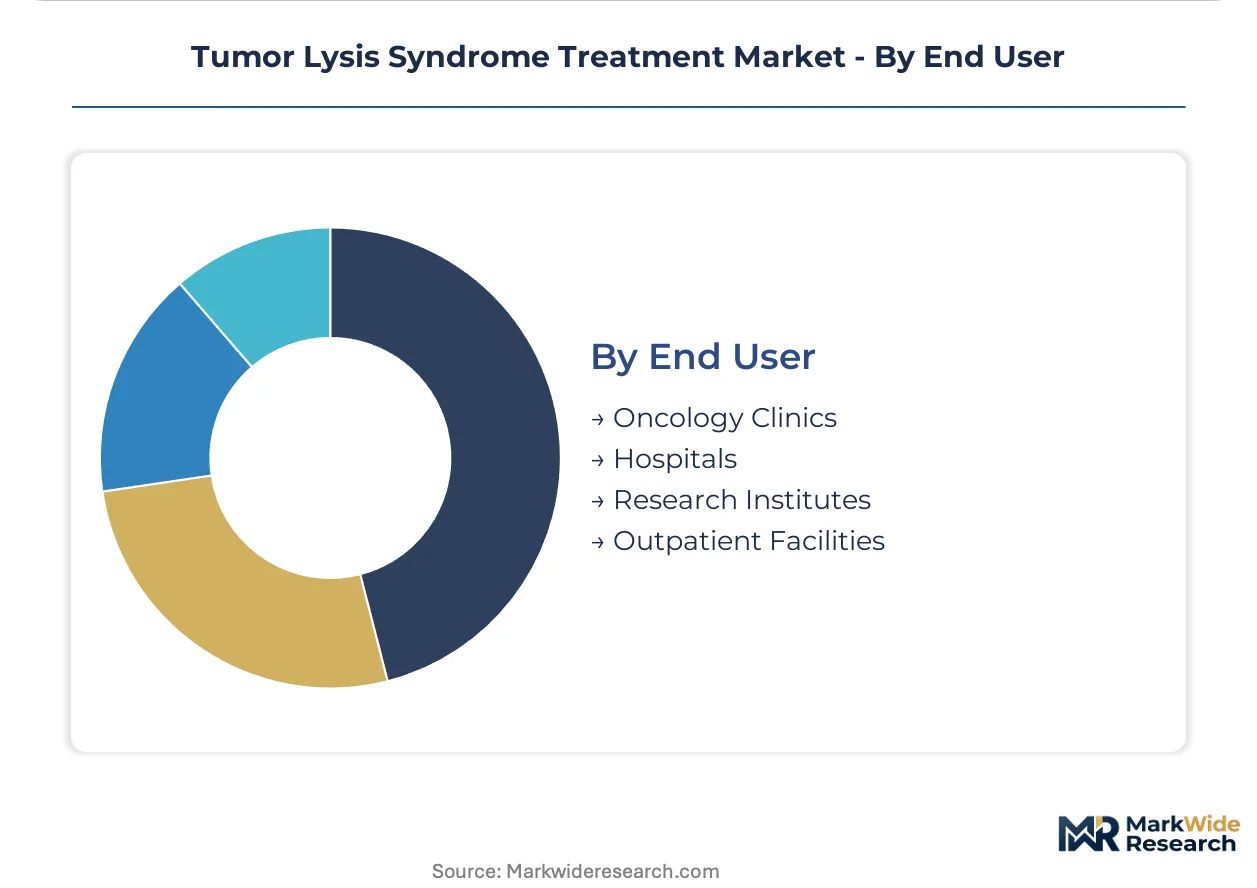
End User:
Purchasing authority consolidation through integrated delivery networks and specialized cancer center certification reshape procurement patterns.
- Oncology Clinics:Ambulatory infusion centers and community oncology practices manage low-to-intermediate risk patients with oral prophylaxis and rapid hydration protocols. Demand concentrates in United States outpatient facilities where site-of-care payment differentials incentivize treatment migration from inpatient settings.
- Hospitals:Inpatient hematology-oncology units handle high-risk induction and TLS complication management with full therapeutic armamentarium. Academic medical centers in Germany and Japan anchor volume through comprehensive cancer center designation requirements.
- Research Institutes:Early-phase oncology trials generate protocol-specified TLS prophylaxis demand.
- Outpatient Facilities:Standalone infusion centers and ambulatory surgery centers expand subcutaneous depot administration.
Hospitals absorb the bulk of installed capacity; Oncology Clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tumor lysis syndrome prophylaxis clusters in countries with dense networks of specialized cancer centers and established reimbursement for high-cost biologics. The United States, Germany, and Japan absorb the bulk of rasburicase volume, while emerging protocols in India and Brazil reshape access dynamics.
United States
FDA oncology drug guidance mandates TLS prophylaxis endpoints in hematologic malignancy trials, expanding the evidence base for enzymatic intervention. Integrated delivery networks in Texas and Florida now require outcome guarantees on hyperuricemia event rates. Academic medical centers in Boston and Houston anchor volume through CAR-T preconditioning protocols.
Germany
Comprehensive cancer center certification institutionalizes prophylactic TLS coverage as standard induction care. EMA pediatric investigation plans extend development timelines but secure age-stratified safety data for adolescent ALL protocols. Hospital consortia in Bavaria and North Rhine-Westphalia enforce REACH-compliant manufacturing audits for recombinant biologics.
Japan
PMDA pharmacokinetic bridging requirements filter market access for foreign-origin biologics, extending timelines by 18-24 months. Designated cancer hospital networks in Tokyo and Osaka standardize rasburicase stocking for aggressive lymphoma protocols. CD19-directed therapy adoption accelerates fastest in Kansai academic centers.
India
CDSCO oncology pathway offers accelerated approval for hematologic malignancy drugs addressing unmet needs. Cost containment pressures favor oral xanthine oxidase inhibitors over enzymatic therapy in government hospital formularies. Mumbai and Delhi private cancer centers pilot risk-stratified prophylaxis protocols for medical tourism patients.
Brazil
ANVISA streamlines review for drugs targeting chemotherapy complications in the public health system. SUS reimbursement negotiations concentrate purchasing authority at the federal level, compressing price realization for originator biologics. São Paulo state cancer institutes anchor demand through pediatric leukemia referral networks.
Tumor Lysis Syndrome Treatment Market Competitive Landscape
United States and European producers anchor the premium biologics tier; Japanese and Indian specialists hold positions in oral generics and regional distribution. Market structure concentrates recombinant enzyme supply with three dominant suppliers, while xanthine oxidase inhibitors fragment across commoditized manufacturers. Strategic archetypes include vertically integrated biologics manufacturers, diagnostics-therapeutics convergers, and oral generic portfolio builders. Capacity expansion and diagnostics integration represent the dominant competitive moves.
Within the biologics tier, Sanofi and Roche exemplify divergent positioning strategies—one leveraging manufacturing scale for hospital contract security, the other anchoring through specialized diagnostics integration. Takeda Pharmaceutical Company Limited occupies a distinct position in oral prophylaxis segments. These three entities represent the competitive anchors around which smaller manufacturers and generic entrants must navigate.
| Leading Market Players |
|---|
| Sanofi |
| Roche |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca |
| Harman Finochem |
| Ironwood Pharmaceuticals |
| Mylan |
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up hospital purchasing consortia in the United States and Germany are consolidating procurement authority for recombinant biologics, compressing price negotiation cycles while simultaneously demanding outcome guarantees on hyperuricemia event rates. This ownership concentration reshapes supply behavior as manufacturers front-load inventory commitments to secure multi-year hospital contracts, embedding pricing discipline through volume-offtake minimums that filter smaller enzyme suppliers from premium tier access.
Pricing Analysis
Premium pricing for rasburicase orders with sub-48-hour lead times reflects cold chain urgency and batch-release testing bottlenecks, while spot inventory of oral xanthine oxidase inhibitors trades at commoditized discounts. Three-tier pricing structure across originator biologics, authorized generics, and unbranded commodities anchors the model, with differentiation driven by FDA tier certification and after-sales clinical support bundling. Cost compression in the oral segment intensifies because integrated delivery networks in Texas and Florida are consolidating formularies around febuxostat. Community oncology clinics exhibit highest price sensitivity; academic medical centers with bundled payment carve-outs show lowest.
Supply Chain Analysis
Specialized fermentation workforce availability in France, Germany, and Massachusetts constrains recombinant uric acid oxidase expansion, with trained cell-culture technicians commanding recruitment premiums that feed into manufacturing cost structures. Geographic supply concentration clusters in France for Sanofi's established allopurinol scale, Switzerland for Roche's diagnostics-integrated biologics, and Japan for Takeda's regional febuxostat production. Raw material dependencies draw from Chinese-sourced recombinant DNA vectors, German-engineered bioreactor systems, and US-origin chromatography resins. Single-source vulnerability runs through the limited recombinant enzyme supplier base. Distribution runs through hospital consortia and specialized oncology distributors with validated cold-chain credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tumor lysis syndrome treatment market is becoming a vertical-integration race as manufacturers pursue upstream control over recombinant enzyme fermentation capacity to defend margin structures against purchasing consortium concentration.
For Market Incumbents: Cement manufacturing scale advantages through captive bioreactor expansion in REACH-compliant jurisdictions, insulating hospital contract security from batch contamination risks that could trigger formulary switching. Prioritize diagnostics-therapeutics convergence investments that embed rasburicase dosing algorithms within real-time uric acid monitoring platforms, creating switching costs against oral prophylaxis substitution.
For New Entrants and Emerging Players: Enter via India's CDSCO accelerated oncology pathway for differentiated mechanisms addressing intermediate-risk stratification white space, where clinical guidelines remain undefined between hydration-only and enzymatic prophylaxis. Target oral prophylaxis segments in cost-constrained government hospital formularies across Brazil and India, leveraging local manufacturing partnerships to bypass cold-chain infrastructure deficits that constrain recombinant biologic distribution.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap oral generic specialists with established distribution in emerging markets, where currency depreciation and reimbursement compression are filtering weaker competitors from hospital tender processes. Long-term viability hinges on positioning for diagnostics-therapeutics convergence rather than commodity xanthine oxidase inhibition. Watch EMA biomarker qualification decisions as the inflection signal for novel therapeutic entrant viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive bioreactor expansion in REACH-compliant jurisdictions secures hospital contract continuity against supply disruption. |
| Diagnostics Integration | Real-time uric acid monitoring with automated dosing algorithms creates closed-loop TLS management value. |
| Regulatory Approval Pathway | EMA pediatric investigation plan compliance extends development timelines but locks adolescent ALL protocol access. |
| Licensing Agreement | Subcutaneous depot formulation partnerships shift site-of-care economics toward ambulatory settings. |
| Pipeline Diversification | Intermediate-risk oral prophylaxis positioning captures white space between hydration and enzymatic standards. |
Research Methodology
Multi-period observation of FDA oncology drug guidance amendments, EMA pediatric investigation plan submissions, and hematology society prophylaxis protocol updates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA assessment reports, ClinicalTrials.gov protocol specifications, and formulary database audits. Bottom-up patient-flow modeling across leukemia and lymphoma indications was triangulated against top-down pharmaceutical revenue estimates.
Segment-weighting approaches applied differential growth assumptions across recombinant enzyme, oral xanthine oxidase inhibitor, and hydration solution product categories, with further stratification by therapy area, delivery mode, and end-user setting. CAGRs were derived from patient incidence projections, treatment intensity trends, and protocol penetration rates across the analysis window. Forecast inputs incorporated PMDA pharmacokinetic bridging timeline assumptions and integrated delivery network purchasing consolidation patterns.
Revisions become necessary when FDA guidance shifts alter TLS prophylaxis endpoint requirements, EMA biomarker qualification decisions accelerate novel therapeutic entry, or major hematology society guidelines redefine risk stratification thresholds. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Peritoneal Cancer Treatment Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Thymus Cancer Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Oncology Devices Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Cancer Cachexia Market
Oncology
Angiosarcomas Treatment Market
Oncology
Tumor Lysis Syndrome Market
Oncology
America Cancer Immunotherapy Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Esophageal Cancer Market
Oncology
Gallbladder Cancer Treatment Market