
 Tugboat Market | 2026-2036
Tugboat Market Size, Share, and Industry Trends Forecast 2026-2036
Tugboat Market Outlook
Port authority procurement is consolidating around fewer, larger fleet operators with multi-decade service agreements. Crowley Maritime Corporation leverages its integrated logistics network to secure long-term harbor contracts along the US Gulf Coast. Damen Shipyards Group anchors European demand through standardized tug designs that reduce delivery lead times. Kotug International competes in the high-specification offshore segment with azimuth stern drive technology.
A tugboat is a compact, high-bollard-pull vessel designed to maneuver ships in confined waters, typically generating thrust through controllable-pitch propellers or Z-drive azimuth thrusters with power ratings from 1,000 to over 100,000 horsepower. Its primary commercial purpose is to assist berthing, unberthing, and escort operations for vessels that cannot self-navigate narrow channels or dense port environments. Harbor tug demand leads volume globally as mega-container terminals require 70-tonne-plus bollard pull capacity for Ultra Large Container Vessels. Electric and hybrid power source categories are expanding fastest where port authorities face zero-emission mandates, though diesel still dominates installed base economics. Specialty tug configurations command premium pricing in ice-class and deep-sea salvage applications where regulatory certification barriers limit supplier entry.
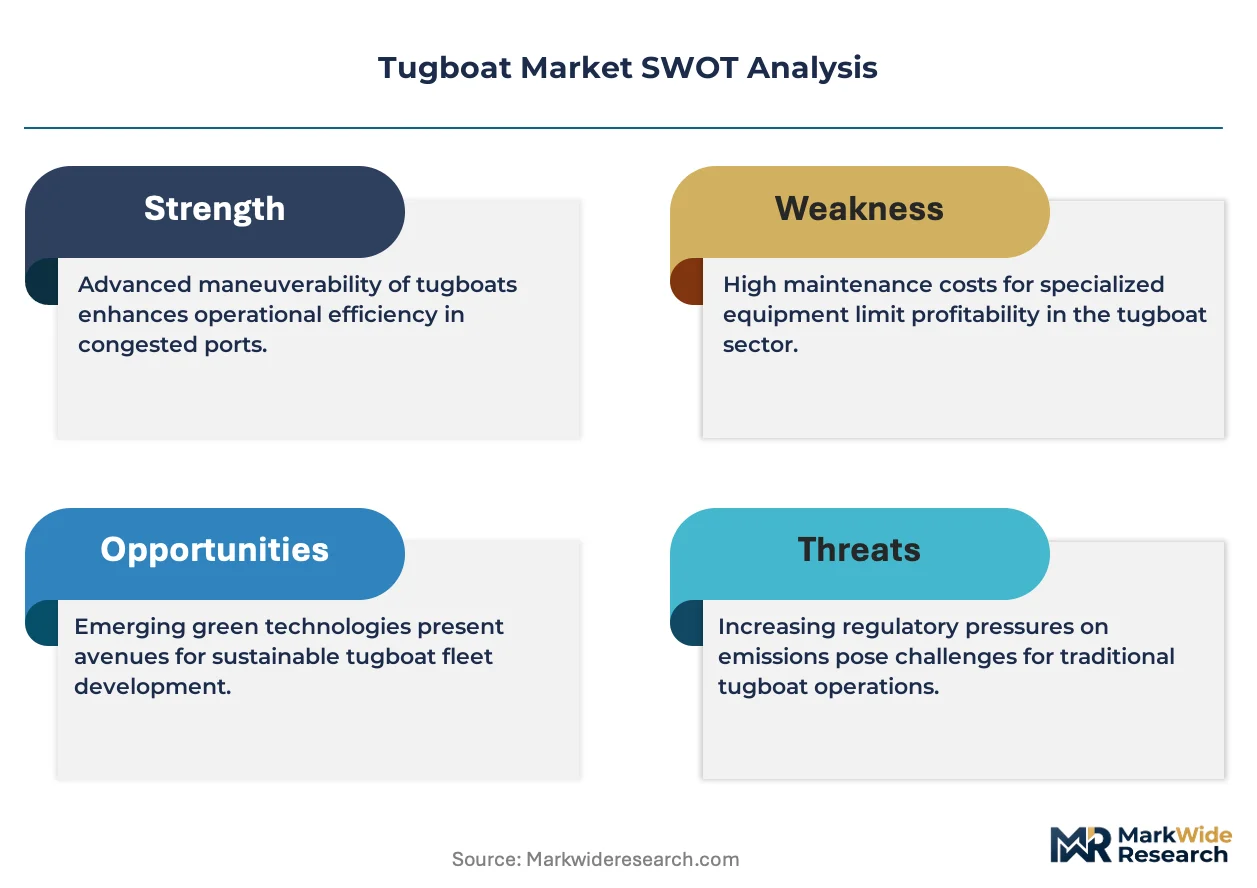
IMO Tier III standards, EPA marine engine rules, and EU Green Deal port decarbonization targets are reshaping newbuild specifications toward alternative fuels and battery-hybrid architectures. Classification societies including Lloyd's Register and Bureau Veritas have introduced notation systems for autonomous tug operations that will condition insurance and charter access. Stakeholders must monitor which port clusters commit first to shore charging infrastructure for fully electric fleets.
Market Dynamics
Port authority zero-emission mandates are compressing diesel tug replacement cycles and forcing capital reallocation toward shore charging infrastructure and battery-hybrid architectures.
Growth Catalysts
- IMO Tier III Standards:The International Maritime Organization's nitrogen oxide emission limits are compelling harbor fleets across Singapore, Rotterdam, and Los Angeles to accelerate newbuild orders for LNG and electric propulsion systems.
- Mega-Container Terminal Expansion:Ultra Large Container Vessel deployment at Shanghai, Busan, and Antwerp terminals is generating demand for 70-tonne-plus bollard pull capacity that legacy tugs cannot deliver.
- State-Owned Shipyard Scaling:Chinese state-owned yards are securing domestic and export contracts for electric harbor tugs, concentrating production capacity and reducing delivery lead times for Asian port authorities.
Market Restraints
- Battery Cost Volatility:Lithium-ion cell price fluctuations and supply concentration in Chinese cathode processing are inflating electric tug capital costs and compressing operator ROI timelines.
- Shore Infrastructure Gaps:Port electrification requires grid reinforcement and high-voltage charging installations that municipal utilities in Hamburg, Long Beach, and Yokohama have not yet committed capital to deploy.
- Azimuth Thruster Supply Concentration:Z-drive and cycloidal propulsion systems rely on a narrow supplier base concentrated in European and Japanese marine engineering houses, creating procurement bottlenecks.
Strategic Opportunities
- Autonomous Tug Operations:Lloyd's Register and Bureau Veritas notation systems for remote-controlled harbor assistance are creating first-mover advantages for operators investing in sensor fusion and collision-avoidance AI.
- EU Green Deal Port Decarbonization:The European Union's binding emission reduction targets for maritime transport are unlocking public financing for zero-emission fleet conversions at Rotterdam, Algeciras, and Piraeus.
- Ice-Class Specialization:Arctic route expansion and year-round LNG terminal operations in Norway and Russia are generating premium pricing for tugs with Ice Class 1A Super certification and redundant propulsion.
Industry Challenges
- Marine Electrical Engineering Talent Scarcity:Battery system integration, thermal management, and high-voltage safety protocols require skill sets that traditional diesel-mechanical tug crews and shipyard workforces do not possess.
- Classification Society Certification Timelines:Novel propulsion architectures face extended review periods at Lloyd's Register, DNV, and American Bureau of Shipping, delaying revenue service entry for newbuild electric tugs by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tugboat Market |
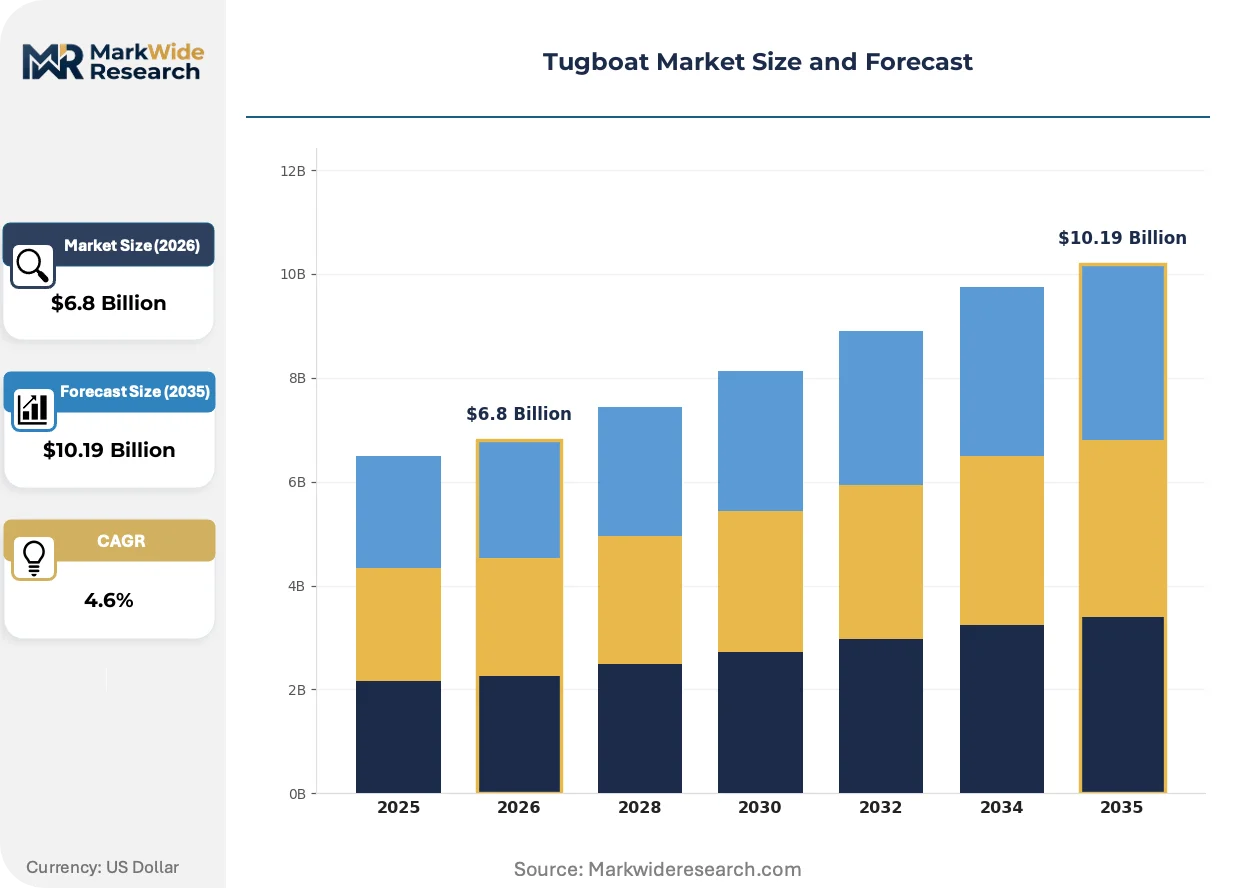
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Harbor Tug, Ocean Tug, River Tug, Specialty Tug Power Source: Diesel, Hybrid, Electric, LNG End User: Shipping Lines, Port Authorities, Offshore Operators, Coastal Services Service Type: Assistance, Salvage, Offshore Support, Ship Management |
| Companies Covered | Mazagon Dock Shipbuilders Limited, Crowley Maritime Corporation, Damen Shipyards Group, Kotug International, Svitzer, Cashman Equipment Corp., Cheoy Lee Shipyards Ltd, Curtin Maritime Corp., Jiangsu Zhenjiang Shipyard Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tugboat Market Strategic Shifts
Propulsion electrification is converging with autonomous navigation development to redefine tug specifications, procurement criteria, and operational economics across major port clusters.
Modular battery-electric propulsion architectures are absorbing the engineering complexity that previously locked tug designs to single-fuel configurations. Port authorities in Singapore and Los Angeles are specifying swappable battery container systems that extend operational range without shore charging downtime. This flexibility is absorbing capital risk for operators uncertain about grid infrastructure buildout timelines.
REACH chemical restrictions and EU F-Gas Regulation phase-down schedules are pressuring European tug operators to abandon high-GWP refrigerants in HVAC and deck machinery systems. The industrial consequence is accelerated specification of CO2-based refrigeration and natural working fluid heat pumps in newbuild contracts. Harbor fleets in Hamburg and Antwerp are most affected, with operators now requiring shipyards to certify full life-cycle refrigerant compliance before contract award.
Long-term service agreements with embedded availability guarantees are displacing spot charter contracting for harbor tug services. Terminal operators in Shanghai, Busan, and Rotterdam are consolidating vendor relationships around integrated fleet management contracts that bundle vessel provision, crewing, maintenance, and emission compliance reporting. This concentration is most visible in the Asia-Pacific container terminal segment, where PSA International and COSCO Shipping Ports are standardizing multi-decade concession terms that lock in tug capacity planning.
Tugboat Market Segmentation
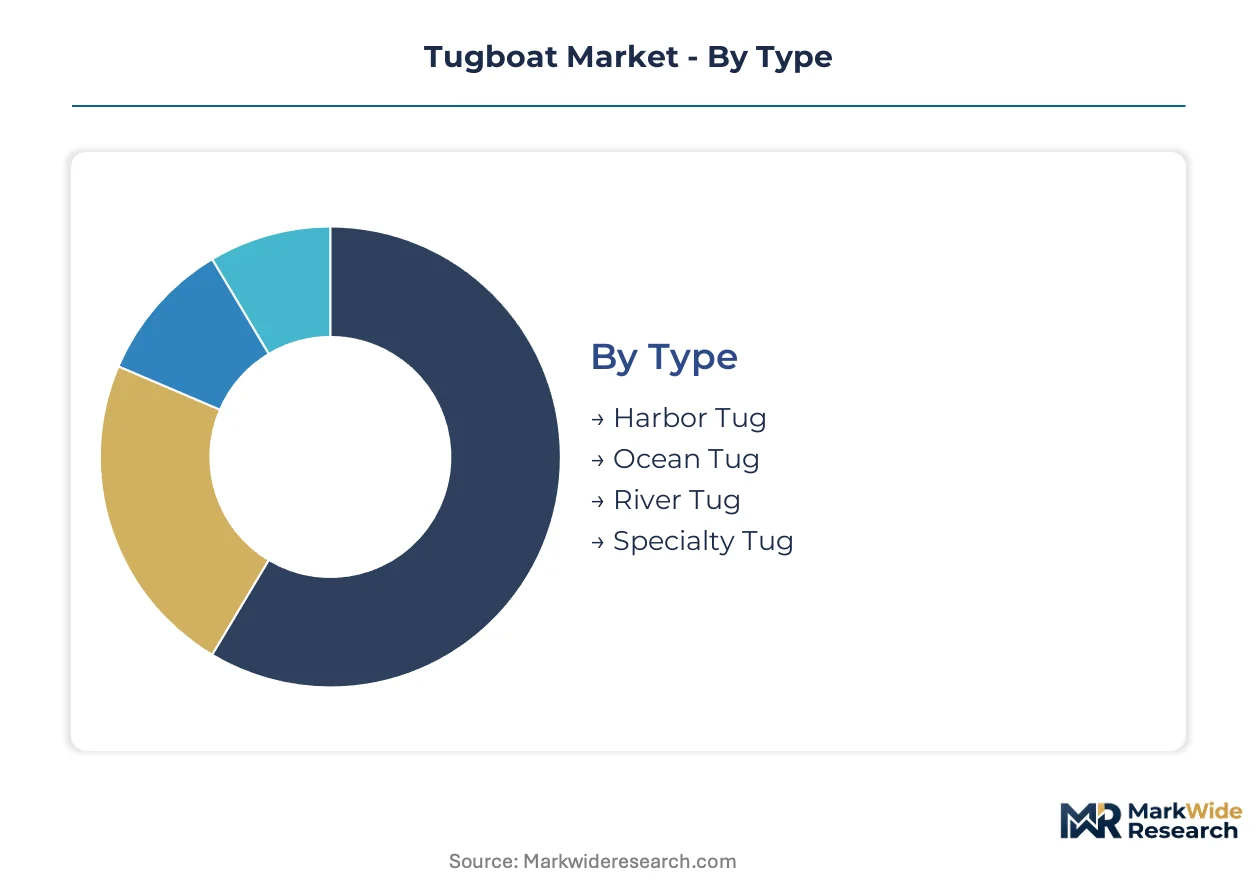
Tugboat procurement specifications diverge sharply across operating environments, with bollard pull requirements and emission compliance driving fundamentally different vessel architectures. Port authorities, offshore operators, and shipping lines each impose distinct technical criteria that reshape propulsion choices and contract structures.
Type:
Propulsion specifications and hull form factor vary dramatically by operating environment, with harbor constraints versus open-water endurance dictating fundamentally different design priorities.
- Harbor Tug:Compact hull designs with azimuth stern drive or tractor configurations deliver 50-100 tonne bollard pull for Ultra Large Container Vessel maneuvering in confined terminals. Demand concentrates at Shanghai, Rotterdam, and Los Angeles where mega-container terminal expansion is forcing 70-tonne-plus fleet replacements.
- Ocean Tug:Deep-sea endurance hulls with 10,000+ nautical mile range and heavy towing winch systems support transoceanic convoy operations. Arctic route development and floating production storage offloading unit repositioning contracts are expanding Ice Class 1A Super specifications in Norwegian and Russian waters.
- River Tug:Shallow-draft propulsion with retractable wheelhouses navigates seasonal water level fluctuations on inland waterways. European Danube and Rhine corridor operators favor modular propulsion for fleet standardization.
- Specialty Tug:Configured for ice-breaking, fire-fighting, or salvage operations with redundant systems and certification barriers limiting supplier entry. Premium pricing reflects regulatory certification complexity and limited yard capacity.
Mature deployment sits with Harbor Tug configurations. Newer deployment is concentrated in Specialty Tug segments where climate adaptation and emergency response capabilities command procurement priority.
Power Source:
Capital allocation patterns reveal operator risk tolerance for emerging propulsion technologies versus proven installed base economics.
- Diesel:Mechanical direct-drive and diesel-electric systems dominate existing fleet economics with established maintenance networks and parts availability. Legacy harbor fleets in Hamburg and Yokohama face compressed replacement cycles as IMO Tier III standards phase in.
- Hybrid:Battery-diesel architectures enable zero-emission terminal operations with conventional range extension for transit legs. Singapore and Los Angeles port authorities are specifying swappable battery container systems to defer shore infrastructure capital commitments.
- Electric:Fully battery-electric propulsion with shore charging dependency suits predictable duty cycles in enclosed harbors. Chinese state-owned yards are scaling production for domestic and export contracts, concentrating manufacturing capacity.
- LNG:Dual-fuel or pure gas systems satisfy IMO Tier III NOx limits without battery weight penalties for high-bollard-pull applications. European Green Deal port decarbonization targets are unlocking public financing for fleet conversions at Rotterdam and Algeciras.
Established fleet composition favors Diesel. Steepest expansion trajectory is concentrated in Hybrid architectures that bridge infrastructure gaps while meeting emission mandates.
End User:
Contract duration and risk allocation structures diverge based on asset ownership models and regulatory liability exposure.
- Shipping Lines:Charter-based tug access for scheduled liner services prioritizes cost predictability over fleet control. Mediterranean Shipping Company and Maersk Line negotiate terminal concession bundles that embed harbor assistance.
- Port Authorities:Direct fleet ownership or long-term concession agreements with availability guarantees dominate mega-terminal procurement. PSA International and COSCO Shipping Ports are standardizing multi-decade service contracts with integrated emission compliance reporting.
- Offshore Operators:Dynamic positioning and anchor-handling specifications for floating production unit support command premium day-rates. North Sea and Gulf of Mexico contract awards favor azimuth stern drive technology with redundancy certification.
- Coastal Services:General cargo and short-sea shipping support requires flexible deployment across multiple port jurisdictions. European cabotage operators face fragmented regulatory compliance across member state emission zones.
Traditional contracting concentration sits with Shipping Lines. Newer deployment is concentrated in Port Authorities pursuing vertical integration of terminal logistics.
Service Type:
Revenue model stability varies from predictable harbor assistance tariffs to contingency-based salvage awards.
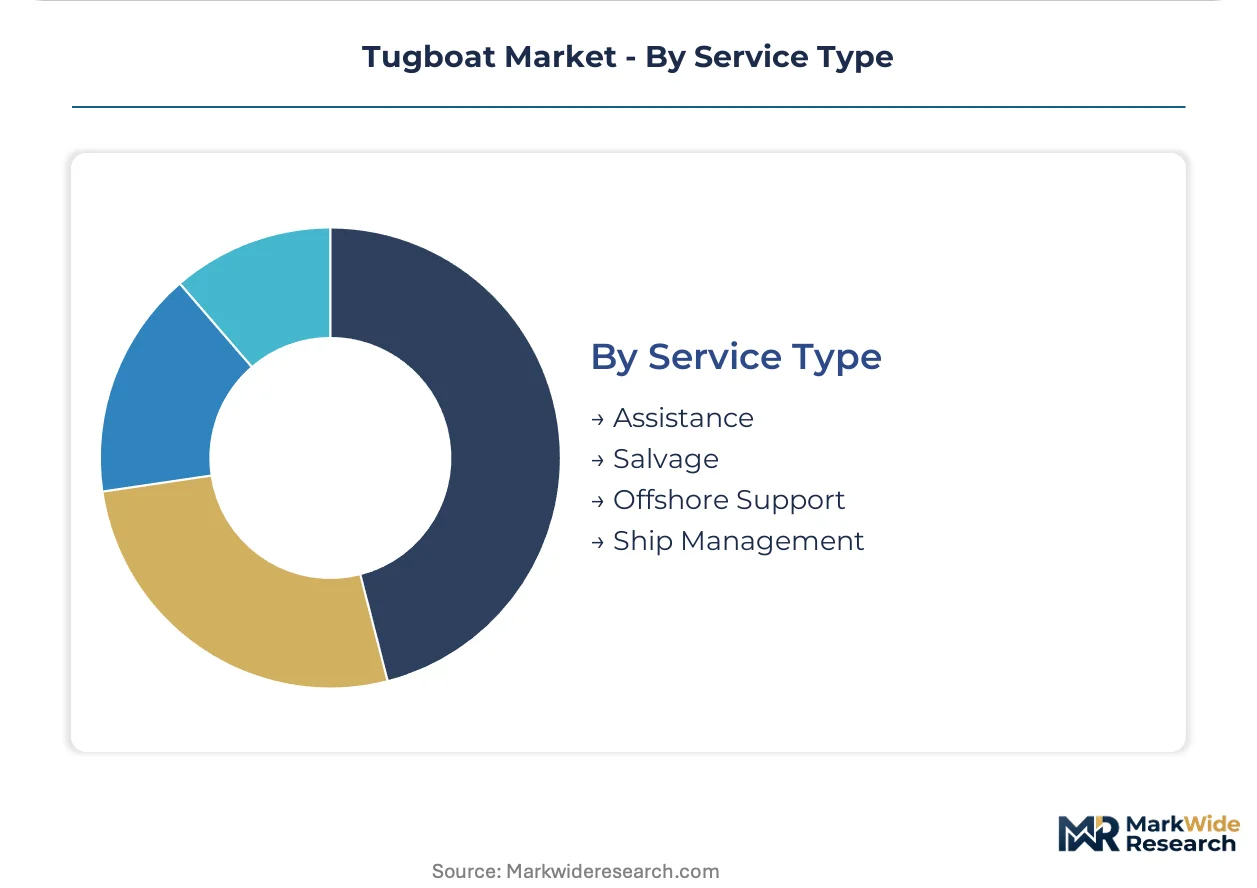
- Assistance:Scheduled berthing and unberthing operations generate recurring revenue with weather-dependent volume variability. Container terminal throughput directly correlates with tug utilization rates.
- Salvage:Lloyd's Open Form and similar no-cure-no-pay contracts expose operators to high-risk, high-reward emergency response. International Salvage Union membership limits competitive entry.
- Offshore Support:Platform supply, anchor handling, and rig move services tie revenue to oil and gas capital expenditure cycles. Decommissioning activity in UK and Norwegian sectors is extending vessel demand.
- Ship Management:Technical management and crewing services for third-party tug owners generate fee-based income without capital deployment. Greek and Singapore-based operators dominate this segment.
Volume concentration sits with Assistance services. Margin expansion is concentrated in Salvage where regulatory certification and response capability scarcity sustain premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port authority fleet modernization concentrates demand in China, the United States, and Northern Europe where emission mandates and mega-container terminal expansion coincide. State-owned shipyard scaling and shore charging infrastructure commitments are reshaping regional competitive dynamics.
China
State-owned shipyards at Jiangsu Zhenjiang and Shanghai Waigaoqiao dominate electric harbor tug production for domestic and export contracts. MEE dual carbon goals accelerate battery-hybrid newbuild specifications at Ningbo-Zhoushan and Shanghai Yangshan terminals. Manufacturing gravity centers on the Yangtze River Delta where integrated supply chains reduce delivery lead times for Asian port authorities.
United States
Crowley Maritime and Curtin Maritime anchor Gulf Coast harbor service consolidation through multi-decade port authority agreements. EPA marine engine Tier IV standards compress diesel tug replacement cycles in Los Angeles and Long Beach. California Air Resources Board zero-emission mandates are forcing capital allocation toward shore charging infrastructure at the San Pedro Bay port complex.
Netherlands
Damen Shipyards Group standardizes modular tug designs that reduce European delivery timelines for Rotterdam and Amsterdam port authorities. EU Green Deal port decarbonization targets unlock public financing for LNG and electric fleet conversions. The Rotterdam-Moerdijk industrial cluster concentrates azimuth thruster integration and classification society certification capacity.
Singapore
PSA International standardizes multi-decade harbor service contracts with embedded emission compliance reporting for the Tuas mega-terminal. IMO Tier III NOx limits accelerate LNG dual-fuel newbuild orders at Sembcorp Marine and Keppel yards. The Maritime and Port Authority mandates shore power readiness for all new harbor tug deliveries from 2025.
Norway
Arctic route development and year-round LNG terminal operations generate premium demand for Ice Class 1A Super tugs at Hammerfest and Melkøya. Norwegian Maritime Authority zero-emission fjord regulations drive battery-hybrid specifications for coastal towage. Kongsberg Maritime anchors autonomous tug sensor fusion development for remote-controlled harbor operations.
Tugboat Market Competitive Environment
Dutch and Chinese producers anchor one tier; US Gulf Coast specialists hold long-term concession positions. The vendor base organizes around three strategic archetypes: integrated logistics operators securing multi-decade harbor contracts, standardized-design shipyards compressing delivery timelines, and high-specification offshore specialists commanding premium day-rates. Competitive moves concentrate on fleet electrification partnerships with port authorities and classification society certification for autonomous operations.
Within the integrated logistics tier, Crowley Maritime Corporation and Svitzer exemplify operators leveraging terminal concession bundling to lock in capacity planning. Damen Shipyards Group occupies a position as the standardized-design archetype, while Kotug International sits within the high-specification offshore segment. Mazagon Dock Shipbuilders Limited represents state-owned yard vertical integration into domestic fleet supply. Jiangsu Zhenjiang Shipyard Co. Ltd. anchors Chinese electric tug export manufacturing.
| Leading Market Players |
|---|
| Mazagon Dock Shipbuilders Limited |
| Crowley Maritime Corporation |
| Damen Shipyards Group |
| Kotug International |
| Svitzer |
| Cashman Equipment Corp. |
| Cheoy Lee Shipyards Ltd |
| Curtin Maritime Corp. |
| Jiangsu Zhenjiang Shipyard Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Marine electrical engineering talent scarcity in European and Japanese engineering clusters widens pricing spreads between diesel-mechanical and battery-hybrid tug configurations, compressing margins for operators lacking in-house integration capabilities.
Pricing Analysis
Volume concentrates in standardized harbor assistance contracts while margins accrue to specialty salvage and ice-class configurations. Three-tier pricing structure across premium, standard, and economy levels separates Ice Class 1A Super certification from IMO Tier III compliance from legacy diesel specifications. Cost compression in electric newbuilds is intensifying because lithium-ion cathode processing concentrates in Chinese supply chains. Coastal services operators exhibit highest price sensitivity, whereas offshore operators accept premium day-rates for dynamic positioning redundancy.
Supply Chain Analysis
Refurbishment flows for azimuth thruster systems and cycloidal propulsion units concentrate service revenue at Kongsberg Maritime and Schottel facilities in Norway and Germany. Manufacturing gravity draws from Chinese state-owned yards at Jiangsu Zhenjiang and Shanghai Waigaoqiao, South Korean builders at Sembcorp Marine, and Dutch modular specialists at Damen Shipyards Group. Battery cell supply hinges on cathode processing concentration in Chinese chemical complexes. Single-source vulnerability runs through European and Japanese marine engineering houses for Z-drive integration. Distribution runs through port authority concession bundling and long-term service agreements rather than spot charter markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tugboat fleet modernization is a consolidation play. IMO Tier III emission standards and shore infrastructure capital requirements are forcing sub-scale operators toward acquisition or exit.
For Market Incumbents: Deploy backward integration into battery system integration capabilities to capture margin currently leaking to third-party marine electrical specialists. Crowley Maritime and Svitzer demonstrate the defensive value of multi-decade port authority concession bundling that locks in capacity planning. Incumbents must counter emerging Chinese yard competition by accelerating classification society certification for autonomous operations at Lloyd's Register and Bureau Veritas.
For New Entrants and Emerging Players: Digital-channel route through remote-controlled harbor assistance notation systems offers lower capital entry than vessel ownership. White-space targets include autonomous tug sensor fusion development for Singapore and Rotterdam port authorities, and swappable battery container system integration for operators deferring shore charging infrastructure commitments. The most penetrable segment is coastal services where fragmented regulatory compliance across European cabotage jurisdictions disadvantages incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated logistics operators given EU Green Deal public financing unlocking for zero-emission fleet conversions. Long-term viability favors operators with captive port authority relationships spanning the analysis window. Acquisition target archetype: mid-scale harbor fleets with concession renewal visibility and untapped emission compliance reporting capabilities. Monitor shore charging infrastructure commitment timelines at Hamburg, Long Beach, and Yokohama as inflection indicator for electric tug demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Azimuth Thruster Backward Integration | Captive supply of Z-drive systems reduces procurement bottlenecks at European and Japanese engineering houses. |
| Autonomous Operations Certification | Lloyd's Register and Bureau Veritas notation systems condition insurance access and charter eligibility. |
| Swappable Battery Container Systems | Modular architectures defer shore infrastructure capital commitments for Singapore and Los Angeles operators. |
| Ice Class 1A Super Specialization | Arctic route development at Hammerfest and Melkøya commands premium pricing with limited yard competition. |
| Long-Term Concession Bundling | PSA International and COSCO Shipping Ports standardize multi-decade contracts locking in capacity planning. |
Study Parameters
IMO regulatory filings, port authority fleet procurement databases, and classification society certification records formed the secondary backbone. Primary interviews with harbor fleet managers, marine electrical engineering directors, shipyard procurement leads, and port authority concession officers combined with customs trade data and SEC filings from listed operators. Bottom-up and top-down triangulation validated vessel delivery schedules against terminal expansion timelines.
Bottom-up modeling aggregated individual port authority fleet replacement programs while top-down analysis tracked regional emission mandate implementation. Segmentation dimensions included tug type, power source architecture, end-user contracting structure, and service revenue model across the projection horizon. CAGRs derived from weighted average of newbuild order backlogs and shore infrastructure deployment timelines. Industry-specific forecast inputs incorporated azimuth thruster delivery lead times and battery cell price trajectories.
The model holds under steady regulatory enforcement timelines; deviation in IMO Tier III implementation delays or lithium supply disruptions would shift fleet replacement schedules. Forecasts reflect documented assumptions about port electrification capital commitments. Practitioners should monitor shore charging infrastructure award announcements at municipal utilities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Fuel Injection System Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Amphibious Vehicle Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Global Outboard Motors Market