
 Meningitis Treatment Market | 2026-2036
Meningitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Meningitis Treatment Market Outlook
Aftermarket service revenue for vaccine cold-chain logistics is tilting toward integrated distribution networks. Pfizer Inc. leverages its established cold-chain infrastructure to sustain competitive advantage in temperature-sensitive meningitis vaccine delivery. Merck & Co., Inc. anchors its position through deep R&D investment in conjugate vaccine platforms. GlaxoSmithKline plc differentiates via broad geographic coverage across emerging and established markets.
Meningitis treatment encompasses pharmacological and immunological interventions targeting inflammation of the meninges, typically requiring cerebrospinal fluid penetration thresholds of therapeutically effective concentrations. The primary purpose centers on pathogen eradication, inflammation reduction, and prevention of neurological sequelae including hearing loss and cognitive impairment. Vaccines command the dominant product type position due to preventive economics and public health prioritization, while intravenous delivery mode captures critical-care margin pools in hospital settings. Bacterial meningitis therapy area generates the most intensive treatment protocols given mortality risks and antibiotic resistance surveillance requirements.
FDA breakthrough therapy designation and EMA PRIME eligibility criteria shape clinical trial investment patterns and accelerate patient access timelines for novel meningitis therapeutics. WHO prequalification standards govern procurement eligibility for multinational immunization programs, directly determining manufacturer market access across low-income country tenders. Stakeholders must monitor antimicrobial resistance surveillance data and regulatory pathway harmonization between FDA and EMA to anticipate portfolio prioritization shifts and manufacturing capacity allocation decisions.
Market Dynamics
FDA breakthrough therapy designation and EMA PRIME eligibility criteria are compressing clinical development timelines for novel meningitis therapeutics while reshaping manufacturer R&D prioritization across antimicrobial and vaccine portfolios.
Growth Catalysts
- WHO prequalification standards:Procurement eligibility for multinational immunization programs in low-income countries is expanding manufacturer addressable markets through tender access.
- Hospital procurement acceleration:Advanced meningitis therapeutic purchasing is intensifying in the United States, Germany, and India as national surveillance infrastructure strengthens.
- Conjugate vaccine platform maturation:Deep R&D investment in multivalent serotype coverage is enabling broader protective immunization schedules against bacterial meningitis.
Market Restraints
- Antimicrobial resistance surveillance costs:Mandatory pharmacovigilance reporting to FDA and EMA for novel antibiotics is elevating post-market compliance expenditure.
- Cold-chain infrastructure concentration:Temperature-sensitive vaccine distribution depends on consolidated logistics networks with limited geographic redundancy.
- Diagnostic confirmation delays:Cerebrospinal fluid culture turnaround times in resource-limited settings extend empiric therapy windows and elevate resistance selection pressure.
Strategic Opportunities
- India national immunization expansion:Government procurement scale-up for pentavalent and pneumococcal conjugate vaccines is creating volume anchors for local manufacturing partnerships.
- mRNA platform convergence:Nucleic acid manufacturing flexibility combined with established lipid nanoparticle formulation is enabling rapid serotype adaptation for outbreak response.
- Integrated distribution networks:Direct-to-hospital vaccine logistics with real-time temperature monitoring is displacing fragmented wholesale channels in European markets.
Industry Challenges
- Specialized formulation expertise scarcity:Cerebrospinal fluid penetration pharmacology and central nervous system drug delivery competency sits with limited academic and contract research organizations.
- Legacy antibiotic manufacturing reconfiguration:Converting fermentation-based cephalosporin production to continuous processing requires capital-intensive facility retooling with extended regulatory requalification timelines.
- Multinational trial coordination complexity:Harmonizing FDA and EMA pediatric investigation plans across diverse meningitis epidemiology creates protocol amendment overhead and site activation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meningitis Treatment Market |
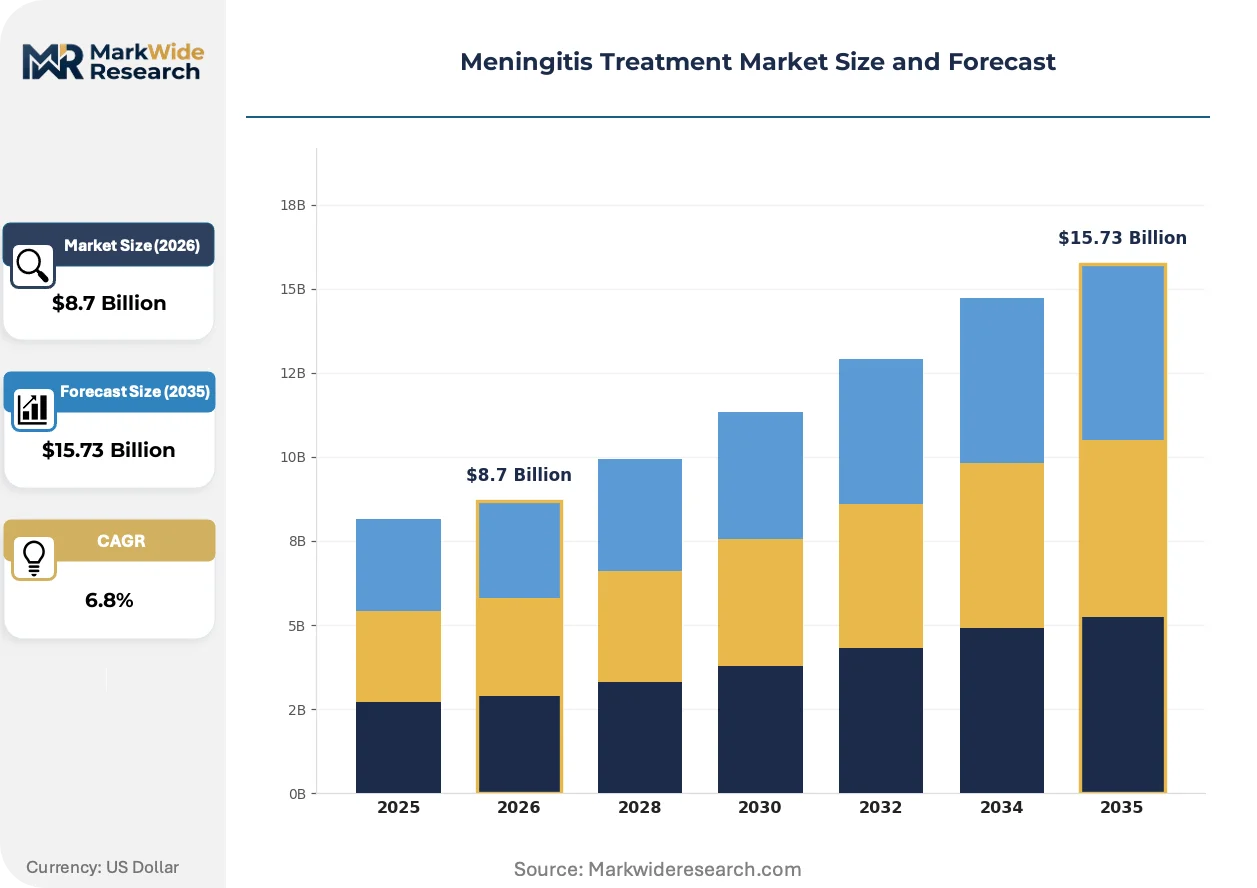
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Antivirals, Corticosteroids Therapy Area: Bacterial Meningitis, Viral Meningitis, Fungal Meningitis, Parasitic Meningitis Delivery Mode: Intravenous, Oral, Intramuscular, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Sanofi S.A., Novartis AG, Johnson & Johnson, Serum Institute of India Pvt. Ltd., Novavax, Inc., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meningitis Treatment Market Strategic Shifts
Digital health infrastructure is virtualizing patient monitoring and treatment adherence across meningitis care pathways while regulatory harmonization and procurement centralization reshape competitive access models.
Artificial intelligence-driven molecular screening is virtualizing early-stage antibacterial discovery by predicting blood-brain barrier permeability and bacterial target engagement. Mid-cap pharmaceutical developers and academic translational centers are adopting these in silico platforms to compress lead optimization cycles. The technology is virtualizing traditional high-throughput screening economics and enabling smaller research footprints for CNS-targeted antimicrobial programs.
EMA's PRIME eligibility criteria and FDA breakthrough therapy designation are compressing Phase II-to-approval timelines for novel meningitis therapeutics by enabling rolling review and accelerated assessment pathways. Manufacturers are restructuring clinical development organizations to parallel-track manufacturing scale-up with pivotal trials. Bacterial meningitis antibiotic programs with mortality endpoints are capturing disproportionate regulatory resource allocation compared to preventive vaccine candidates.
Hospital procurement consortia are consolidating meningitis therapeutic purchasing through centralized tender mechanisms with outcome-linked contract terms. Group purchasing organizations in the United States and regional hospital alliances in Germany are displacing individual pharmacy negotiations. This concentration is most visible in academic medical centers managing high-volume neurocritical care units where formulary standardization reduces inventory complexity.
Meningitis Treatment Market Segmentation
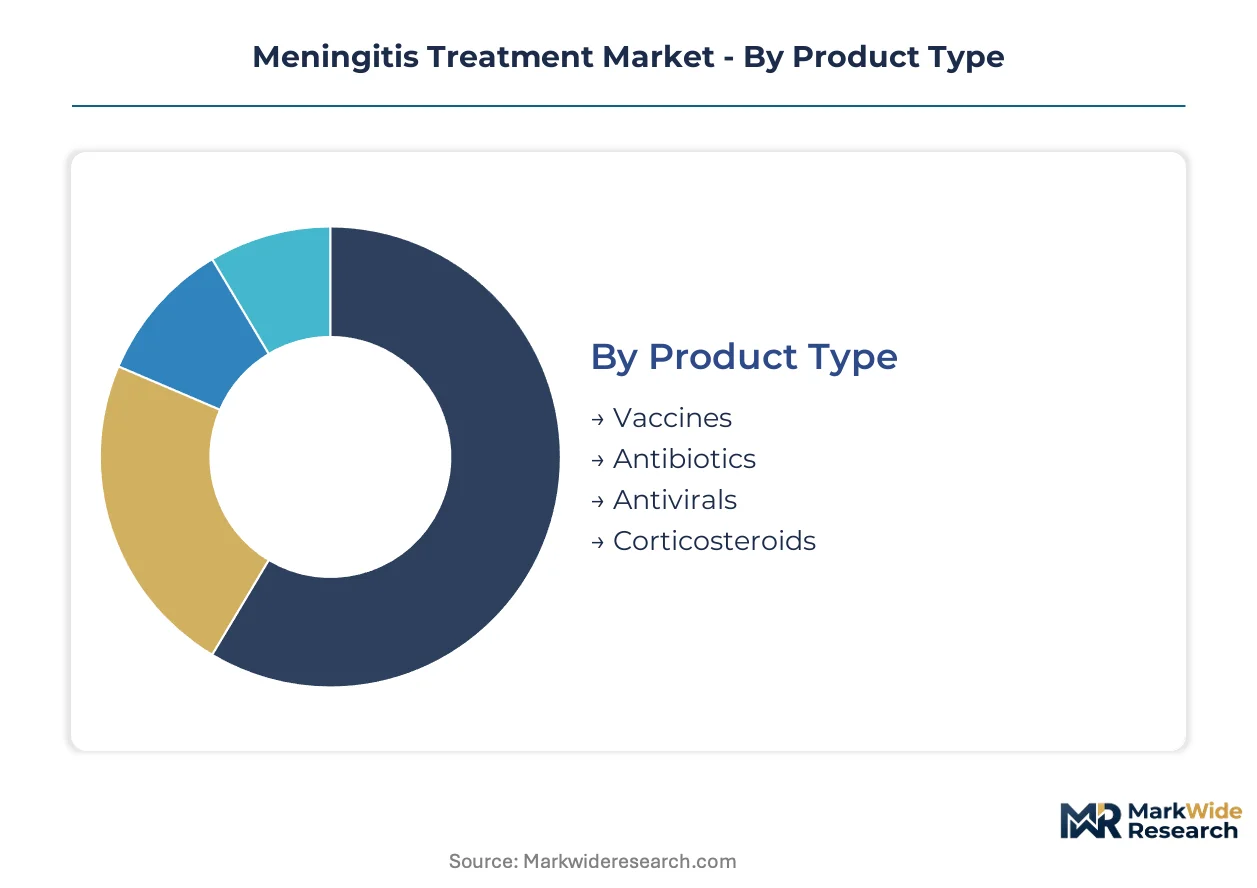
Meningitis treatment segmentation reflects divergent clinical pathways across preventive and curative interventions. Product type stratification separates high-volume immunization programs from acute-care pharmaceutical procurement. Therapy area delineation determines regulatory scrutiny intensity and hospital formulary positioning.
Product Type:
Cost tier separation distinguishes preventive population-scale deployment from acute therapeutic procurement with premium pricing structures.
- Vaccines:Conjugate and polysaccharide formulations targeting serogroups A, C, W, Y, and B dominate preventive public health budgets. Demand concentrates in national immunization programs across the United States, Germany, and India as governments expand pediatric and adolescent coverage schedules. WHO prequalification governs procurement eligibility for low-income country tenders.
- Antibiotics:Third-generation cephalosporins, vancomycin, and carbapenems constitute first-line empiric therapy for bacterial meningitis. Hospital procurement in academic medical centers drives volume, with FDA breakthrough therapy designation accelerating novel antimicrobial development timelines. Resistance surveillance mandates elevate post-market compliance expenditure.
- Antivirals:Acyclovir and related nucleoside analogs target herpes simplex virus meningitis with narrower indication profiles.
- Corticosteroids:Adjunctive dexamethasone protocols reduce inflammatory sequelae in bacterial cases per IDSA guidelines.
Vaccines command the established base. The steepest expansion runs through antibiotics as resistance surveillance intensifies hospital formulary updates.
Therapy Area:
Application severity determines treatment protocol intensity and mortality endpoint requirements in regulatory trials.
- Bacterial Meningitis:Streptococcus pneumoniae, Neisseria meningitidis, and Haemophilus influenzae type b drive intensive care admission and prolonged antibiotic courses. Mortality risks above 10% in pneumococcal cases mandate rapid cerebrospinal fluid penetration thresholds. EMA PRIME eligibility criteria prioritize novel antibacterial programs with mortality endpoints.
- Viral Meningitis:Enterovirus and herpesvirus etiologies predominate with supportive care protocols and selective antiviral deployment. Outpatient management in clinics and home care settings characterizes typical patient pathways, reducing hospital margin capture compared to bacterial cases.
- Fungal Meningitis:Cryptococcus neoformans in immunocompromised populations requires extended amphotericin B and fluconazole courses.
- Parasitic Meningitis:Rare neurocysticercosis and cerebral malaria presentations concentrate in tropical geography referral centers.
Bacterial meningitis anchors hospital revenue concentration. Viral applications expand most quickly through outpatient channel displacement.
Delivery Mode:
Volume distribution reflects acute-care infrastructure dependency versus ambulatory care expansion trajectories.
- Intravenous:Cephalosporin and vancomycin infusion dominates inpatient neurocritical care with centralized pharmacy compounding. Academic medical centers in the United States and Germany standardize protocols through group purchasing organization formularies. Real-time therapeutic drug monitoring optimizes cerebrospinal fluid penetration.
- Oral:Step-down therapy and outpatient prophylaxis enable hospital discharge acceleration. Pharmacies in India capture volume through government program distribution networks for rifampin chemoprophylaxis in meningococcal exposure settings.
- Intramuscular:Vaccine administration in clinics and pharmacies supports preventive campaign logistics.
- Inhalation:Investigational aerosolized antimicrobial delivery targets non-invasive meningitis adjunctive therapy.
Intravenous delivery commands the established base. Oral formulations gain share fastest through hospital readmission reduction incentives.
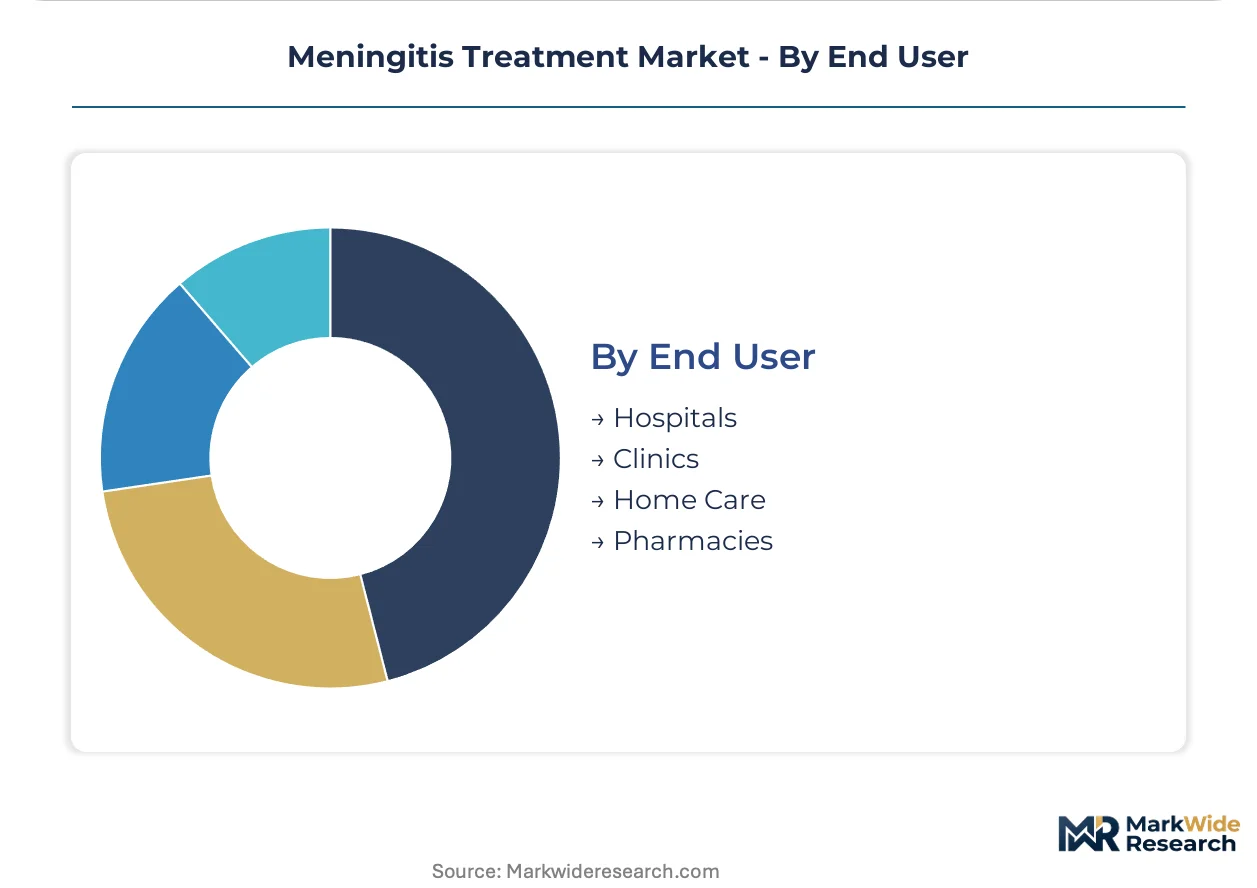
End User:
Customer type concentration shapes procurement channel structure and pricing negotiation leverage.
- Hospitals:Neurocritical care units and infectious disease services drive advanced therapeutic procurement with outcome-linked contract terms. Regional hospital alliances in Germany and group purchasing organizations in the United States consolidate tender mechanisms. Formulary standardization reduces inventory complexity in high-volume academic centers.
- Clinics:Outpatient vaccination and post-discharge monitoring extend care continuity with lower capital intensity. India's national immunization program channels pentavalent and pneumococcal vaccines through government health centers with local manufacturing partnership requirements.
- Home Care:Oral antibiotic step-down and prophylaxis administration reduces hospital length-of-stay.
- Pharmacies:Retail distribution captures over-the-counter symptom management and prescription fulfillment.
Hospitals command the established base. Clinics climb the fastest through preventive immunization scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across procurement contexts. Hospital buyers in Germany and the United States absorb premium pricing for advanced therapeutics, while government tenders in India and Nigeria prioritize cost minimization in national immunization scale-up.
United States
Academic medical centers in Boston and the Research Triangle drive neurocritical care procurement with outcome-linked contracts. FDA breakthrough therapy designation accelerates novel antimicrobial access timelines. The Southeast corridor from Atlanta to Miami anchors CDC-coordinated resistance surveillance infrastructure.
Germany
Regional hospital alliances consolidate meningitis therapeutic purchasing through centralized tenders. EMA PRIME eligibility criteria compress Phase II-to-approval windows for novel antibiotics. Bavaria's Munich-Stuttgart corridor concentrates pharmaceutical R&D and manufacturing for CNS-targeted formulations.
India
Government procurement scale-up for pentavalent and pneumococcal conjugate vaccines creates volume anchors for local manufacturing. CDSCO accelerated approval pathways for WHO-prequalified products streamline tender eligibility. Maharashtra's Pune-Hyderabad corridor houses contract manufacturing organizations serving multinational vaccine developers.
United Kingdom
NHS England's specialized commissioning frameworks concentrate meningitis care in designated neurocritical care centers. MHRA rolling review procedures align with EMA accelerated assessment for mortality-endpoint antibacterial programs. The London-Oxford-Cambridge triangle anchors translational research for blood-brain barrier penetration pharmacology.
Brazil
Ministry of Health immunization campaigns drive seasonal demand spikes for meningococcal conjugate vaccines. ANVISA priority review vouchers for neglected tropical diseases extend to cryptococcal meningitis therapeutics. São Paulo's Butantan Institute anchors domestic vaccine production and regional distribution logistics.
Meningitis Treatment Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three tiers: multinational pharmaceutical conglomerates with integrated cold-chain infrastructure, mid-cap vaccine specialists with geographic niche dominance, and diagnostic-device manufacturers extending into therapeutic adjacencies. Competitive moves center on conjugate platform R&D partnerships and direct-to-hospital distribution network buildout.
Among the multinational tier, Pfizer Inc., Merck & Co., Inc., and GlaxoSmithKline plc exemplify divergent strategic positioning. Pfizer occupies a position anchored in temperature-sensitive logistics infrastructure. Merck represents deep investment in multivalent serotype coverage platforms. GlaxoSmithKline sits within broad emerging-market access capabilities spanning preventive and acute-care portfolios.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Novartis AG |
| Johnson & Johnson |
| Serum Institute of India Pvt. Ltd. |
| Novavax, Inc. |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Maharashtra's Pune-Hyderabad corridor anchors global vaccine contract manufacturing capacity, and its utilization rates directly determine pricing leverage for multinational developers tendering into WHO prequalification programs. Cold-chain infrastructure scarcity in sub-Saharan Africa and South Asia feeds back into premium logistics surcharges that concentrate margin capture with integrated distributors.
Pricing Analysis
Long-term offtake agreements with government immunization programs dominate vaccine procurement, while hospital antibiotic purchasing runs through annual group purchasing organization tenders with outcome-linked terms. Three-tier pricing structure across premium, standard, and economy levels separates patented conjugate vaccines from WHO-prequalified alternatives and regional generic antibiotics. Cost compression in standard-tier cephalosporins is intensifying because of fermentation capacity expansion in India and China. National program procurement managers exhibit highest price sensitivity; academic medical center pharmacy directors absorb premium pricing for mortality-endpoint therapeutics.
Supply Chain Analysis
Active pharmaceutical ingredient fermentation draws from specialized chemical precursors concentrated in China, India, and select European facilities. Lipid nanoparticle formulation components and bacterial cell culture media represent critical input dependencies. Single-source vulnerability in temperature-controlled air freight lanes between Brussels and Lagos elevates outbreak response risk. Distribution runs through direct-to-hospital channels with real-time temperature monitoring displacing fragmented wholesale networks in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA breakthrough therapy designation and EMA PRIME eligibility create multi-year approval timelines that freeze out opportunistic entrants.
For Market Incumbents: Build regulatory data exclusivity moats by accelerating pediatric investigation plan submissions ahead of competitor entry. Deepen backward integration into bacterial polysaccharide fermentation to secure serotype coverage expansion without API supply disruption. Threat substitution from mRNA platform developers demands preemptive conjugate platform patent estate reinforcement. Capacity addition in India's CDSCO-inspected facilities secures tender eligibility for pentavalent and pneumococcal programs. For New Entrants and Emerging Players: Outpatient oral antibiotic step-down protocols in India's government health centers represent the most penetrable entry point for differentiated pharmacokinetic profiles. Diagnostic-device manufacturers extending into therapeutic adjuvancies in cryptococcal meningitis capture underserved immuno-compromised populations. Go-to-market execution should anchor on hospital readmission reduction incentive alignment with United States Medicare bundled payment programs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because manufacturing capacity scarcity and regulatory pathway complexity favor scale accumulation over greenfield development. Acquisition targets should display WHO prequalification status or FDA breakthrough therapy designation with mortality endpoints in bacterial meningitis. Signal to watch: CDSCO accelerated approval pathway utilization rates as proxy for Indian government procurement volume commitment.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks tender eligibility across Gavi-funded national immunization programs in low-income countries. |
| Conjugate Platform Licensing | Enables rapid serotype expansion without de novo manufacturing facility construction timelines. |
| Cold-Chain Distribution Partnership | Secures temperature integrity guarantees required for CDC and EMA-compliant vaccine logistics. |
| Antimicrobial Resistance Surveillance Integration | Positions novel antibiotics for formulary preference in academic medical center group purchasing organizations. |
| mRNA Manufacturing Scale-Up | Captures platform flexibility for outbreak-responsive serotype adaptation in meningococcal vaccines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at academic medical centers. Secondary validation drew from FDA filings, EMA assessment reports, ClinicalTrials.gov protocol registries, and WHO prequalification product lists. Bottom-up patient-volume modeling across therapy areas and top-down immunization program budget allocation analysis were triangulated for convergence.
Calibration against historical tender award values and procurement volume disclosures from national immunization programs anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, therapy area severity, delivery mode, and end-user procurement channel, with regional regulatory cluster differentiation for FDA, EMA, and CDSCO pathways. CAGRs were derived from epidemiological incidence projections cross-referenced with treatment protocol intensity assumptions and vaccine schedule expansion timelines.
Practitioners should monitor antimicrobial resistance surveillance data releases and regulatory pathway harmonization announcements for early signals of portfolio prioritization shifts. Forecasts reflect assumptions regarding immunization program budget continuity and cold-chain infrastructure investment trajectories. Cross-checking against CDC and EMA pharmacovigilance database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market