
 Digital Inspection Tools Market | 2026-2036
Digital Inspection Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Inspection Tools Market Analysis
Skilled NDT technician shortages across heavy manufacturing is unwinding traditional inspection workflows and accelerating automation procurement. Olympus sustains technology leadership in phased array ultrasonic systems through deep R&D commitments. Cognex dominates machine vision hardware for automotive assembly lines with tightly integrated software stacks. Hexagon anchors metrology-grade inspection across aerospace supply chains with precision coordinate measuring systems.
Digital inspection tools encompass integrated hardware-software systems that capture, process, and analyze dimensional, structural, or material data using sensors operating at resolutions from micrometers to meters, with outputs rendered through cloud dashboards or edge devices for real-time quality decisions. Hardware Devices command the largest revenue share due to capital-intensive sensor platforms and replacement cycles, while AI Integration represents the fastest-expanding technology segment as neural network inference shifts to edge processors. Cloud Services are maturing fastest in oil and gas remote monitoring, where margin pools concentrate in subscription analytics rather than device sales.
FDA device-quality regulations, OSHA workplace safety mandates, and ISO 17025 laboratory accreditation standards collectively shape product certification requirements and buyer procurement criteria across North American and European markets. The EU AI Act imposes additional conformity obligations on automated inspection systems making safety-critical determinations. Stakeholders must weigh algorithmic explainability investments against speed-to-market pressures as regulatory divergence between jurisdictions deepens.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing inspection system vendors to rearchitect neural network architectures for explainability, compressing development timelines and elevating compliance costs across safety-critical deployments in aerospace and heavy manufacturing.
Growth Catalysts
- Phased Array Ultrasonic Testing:Aerospace MRO facilities in Germany and France are deploying automated flaw-detection systems to eliminate human error in turbine blade inspections. The technology reduces downtime cycles by enabling simultaneous multi-angle scanning without probe repositioning.
- EU AI Act Conformity Requirements:Safety-critical inspection systems must now demonstrate algorithmic explainability for automated pass-fail determinations. This regulatory pressure is accelerating procurement of certified edge-AI platforms that embed interpretability layers directly into inference pipelines.
- Munich-Stuttgart Industrial Cluster Demand:Automotive and precision engineering concentrations in southern Germany are driving metrology-grade adoption. Local OEMs require sub-micron dimensional verification for electric drivetrain components, pulling advanced coordinate measuring systems into production lines.
Market Restraints
- Sensor Platform Capital Intensity:High-resolution phased array systems and thermal imaging arrays require substantial upfront investment, constraining adoption among mid-tier contract manufacturers with compressed capital allocation cycles.
- Specialized Technician Scarcity:Qualified NDT Level III certificants command premium compensation in heavy manufacturing hubs, creating operational bottlenecks that automation cannot fully offset during transitional deployment phases.
- Silicon Supply Concentration:Edge-AI processor fabrication concentrates in Taiwan and South Korea foundries, exposing inspection hardware vendors to geopolitical disruption risk and extended lead times for neural network inference modules.
Strategic Opportunities
- Wind Turbine Blade Remote Monitoring:Offshore wind installations in the North Sea and Baltic Sea require continuous structural health assessment. Drone-mounted ultrasonic systems with cellular backhaul create subscription revenue pools beyond equipment sales.
- Medical Device Additive Manufacturing:FDA 21 CFR Part 820 quality system regulations mandate dimensional verification for patient-specific implants. Laser scanning systems integrated with build-chamber feedback loops address this emerging compliance requirement.
- 5G-Enabled Edge Analytics:Ultra-reliable low-latency connectivity allows cloud-trained models to execute inference at inspection stations without local GPU hardware, reducing platform costs for distributed quality control networks in automotive supply chains.
Industry Challenges
- ISO 17025 Accreditation Timelines:Laboratory certification for automated inspection systems requires 12-18 month validation cycles, delaying revenue recognition and complicating sales forecasting for vendors targeting aerospace and medical device verticals.
- Legacy CMM Integration Complexity:Brownfield manufacturing facilities operate 15-20 year-old coordinate measuring machines with proprietary data formats. Retrofitting digital thread connectivity demands custom middleware development that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Inspection Tools Market |
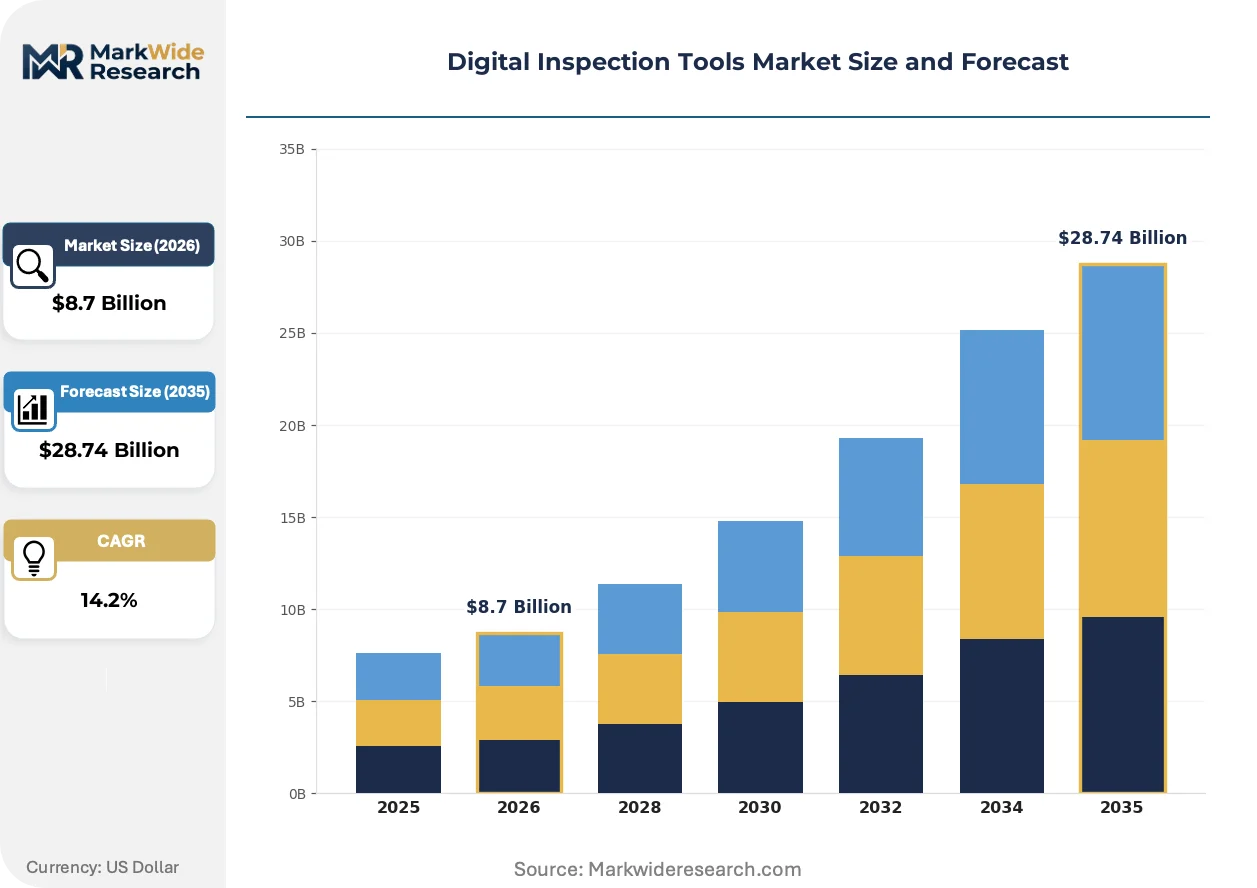
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Cloud Services, Mobile Applications Technology: AI Integration, 3D Imaging, IoT Connectivity, Augmented Reality Application: Aerospace, Automotive Manufacturing, Construction, Oil & Gas End User: Quality Control, Maintenance Teams, Compliance Officers, Inspection Agencies |
| Companies Covered | General Electric, Olympus, Mistras Group, Cognex, Hexagon, Zetec, Nikon, Omron, Keyence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Inspection Tools Market Emerging Trajectories
Edge-AI inference is redistributing computational load from cloud data centers to inspection station processors, enabling millisecond-latency quality decisions while complicating software update and security patch distribution architectures across distributed manufacturing networks.
Digital twin synchronization is fragmenting traditional inspection workflows by embedding metrology data directly into virtual production models. Automotive OEMs in Germany are adopting real-time dimensional feedback loops that adjust CNC toolpaths without human intervention. This convergence of simulation and measurement is compressing the boundary between quality control and process control functions.
REACH substance restrictions on hexavalent chromium coatings are forcing aerospace suppliers to adopt alternative surface treatments with different electromagnetic signatures. Eddy current inspection systems must recalibrate sensitivity thresholds for cadmium-free corrosion protection layers, driving hardware refresh cycles across European supply chains. Vendors are responding with multi-frequency probe architectures that adapt to variable conductivity profiles.
Subscription analytics contracts are displacing perpetual software licenses in oil and gas pipeline monitoring. Operators in the Permian Basin and North Sea now procure corrosion-rate forecasting as a service rather than owning predictive maintenance platforms. This consumption-model shift concentrates vendor margin pools in recurring revenue streams while reducing buyer capital deployment and internal IT infrastructure requirements.
Digital Inspection Tools Market Segmentation
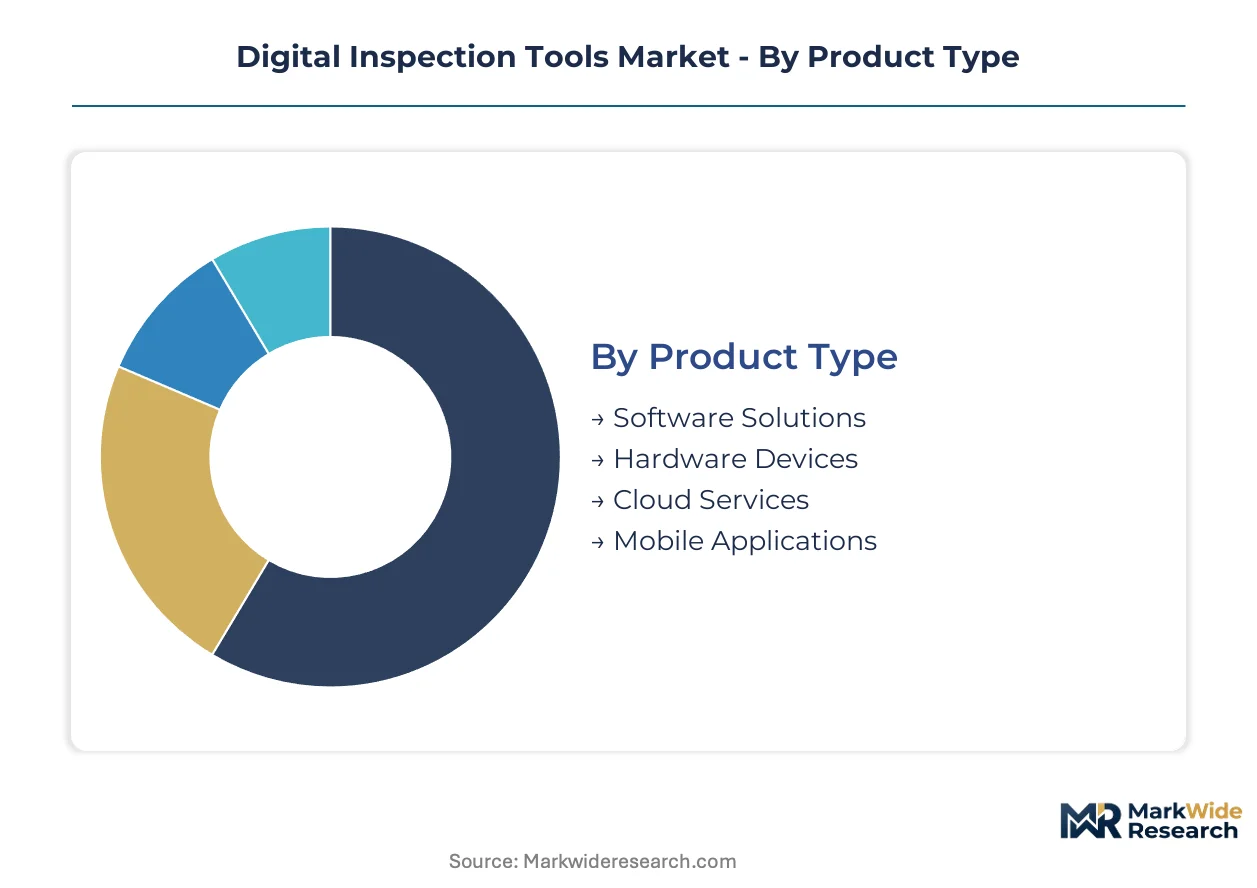
Digital inspection tools span hardware-software ecosystems where regulatory requirements fragment procurement criteria across jurisdictions. Segmentation reveals how compliance obligations, capital intensity, and workflow integration demands reshape vendor competitive positioning.
Product Type:
FDA device-quality regulations, OSHA workplace safety mandates, and ISO 17025 laboratory accreditation standards collectively shape certification requirements and buyer procurement criteria across North American and European markets. The EU AI Act imposes additional conformity obligations on automated inspection systems making safety-critical determinations.
- Hardware Devices:Capital-intensive sensor platforms—phased array ultrasonic systems, thermal imaging arrays, and coordinate measuring machines—operate at resolutions from micrometers to meters. Aerospace MRO facilities in Germany and France deploy automated flaw-detection systems to eliminate human error in turbine blade inspections, though high upfront investment constrains adoption among mid-tier contract manufacturers.
- Cloud Services:Subscription analytics platforms process inspection data through remote servers, enabling centralized quality dashboards across distributed manufacturing networks. Oil and gas operators in the Permian Basin and North Sea now procure corrosion-rate forecasting as a service rather than owning predictive maintenance platforms, concentrating vendor margin pools in recurring revenue streams.
- Software Solutions:Embedded applications for data acquisition, neural network training, and dimensional analysis run on edge processors or host systems.
- Mobile Applications:Tablet and smartphone interfaces provide field technicians with portable access to inspection protocols and real-time reporting tools.
Hardware Devices handles the majority of throughput; Cloud Services is the fastest mover on share.
Technology:
Cost tier differentiation separates enterprise-grade deployments with dedicated GPU infrastructure from mid-market solutions relying on cloud inference.
- AI Integration:Neural network inference shifts to edge processors, enabling millisecond-latency quality decisions while complicating software update distribution. Safety-critical inspection systems must demonstrate algorithmic explainability for automated pass-fail determinations under EU AI Act mandates, accelerating procurement of certified edge-AI platforms that embed interpretability layers directly into inference pipelines.
- 3D Imaging:Laser scanning and structured light systems capture sub-micron dimensional data for metrology-grade verification. Automotive OEMs in southern Germany require sub-micron dimensional verification for electric drivetrain components, pulling advanced coordinate measuring systems into production lines around Munich and Stuttgart industrial clusters.
- IoT Connectivity:Sensor networks transmit inspection data to centralized platforms for trend analysis and predictive maintenance scheduling.
- Augmented Reality:Overlay systems guide technicians through complex inspection protocols with visual annotations and remote expert assistance.
AI Integration commands premium pricing; 3D Imaging is expanding most quickly in precision manufacturing verticals.
Application:
Volume concentration follows aerospace and automotive manufacturing where regulatory scrutiny and defect costs drive technology investment.
- Aerospace:Automated inspection systems reduce human error and downtime in maintenance operations. REACH substance restrictions on hexavalent chromium coatings force European aerospace suppliers to adopt alternative surface treatments, requiring eddy current systems to recalibrate sensitivity thresholds for cadmium-free corrosion protection layers.
- Automotive Manufacturing:Machine vision hardware with tightly integrated software stacks dominates assembly line quality control. Real-time dimensional feedback loops adjust CNC toolpaths without human intervention, compressing the boundary between quality control and process control functions.
- Oil & Gas:Remote pipeline monitoring leverages drone-mounted ultrasonic systems with cellular backhaul for continuous structural health assessment.
- Construction:Geotechnical and structural inspection applications deploy ground-penetrating radar and thermal imaging for subsurface defect detection.
Aerospace absorbs the highest equipment value per installation; Automotive Manufacturing generates the largest aggregate unit demand.
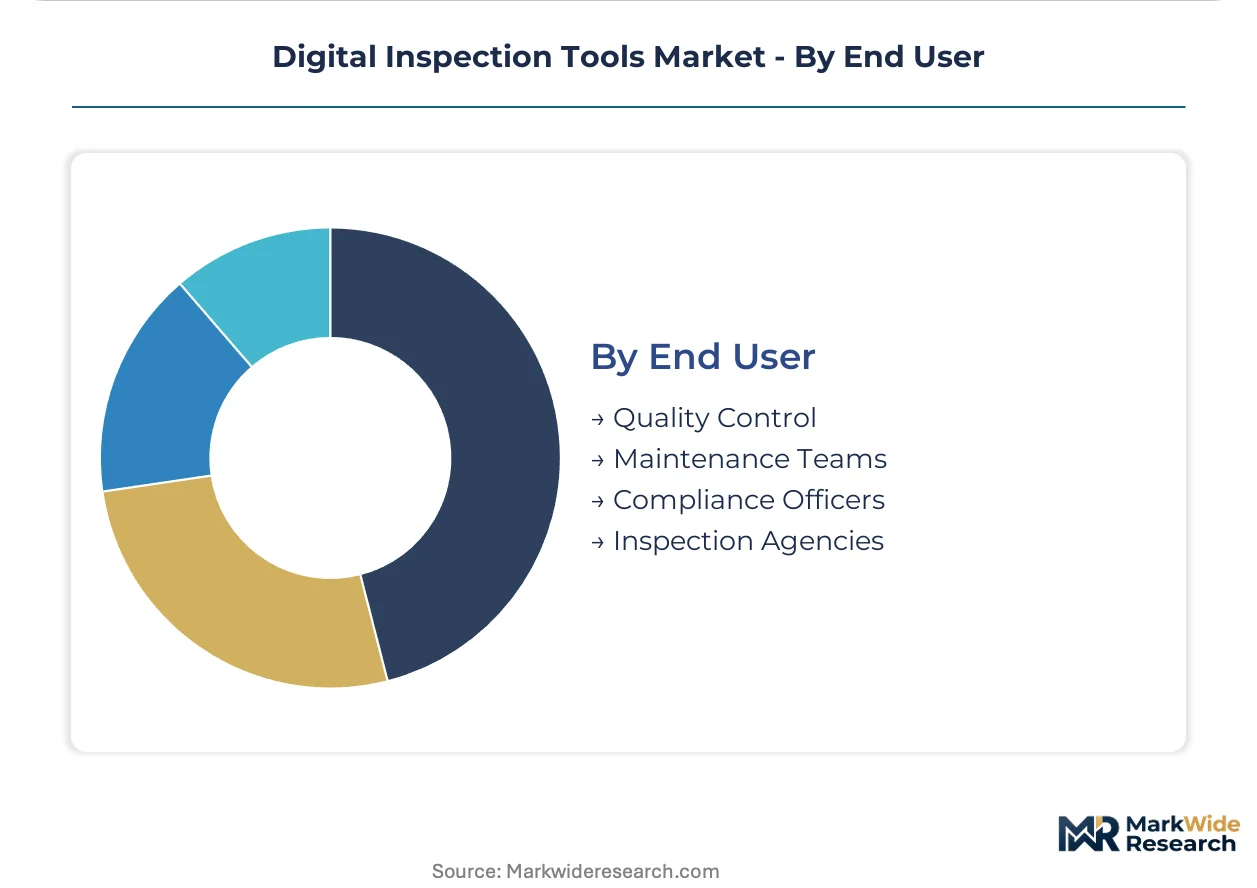
End User:
Customer type determines feature prioritization, with compliance officers driving explainability requirements and maintenance teams emphasizing field durability.
- Quality Control:Production-line personnel execute dimensional verification and defect detection using integrated hardware-software systems. ISO 17025 laboratory certification for automated inspection systems requires 12-18 month validation cycles, delaying revenue recognition for vendors targeting aerospace and medical device verticals.
- Maintenance Teams:Field technicians perform in-service inspection of operating equipment using portable ultrasonic and eddy current instruments. Qualified NDT Level III certificants command premium compensation in heavy manufacturing hubs, creating operational bottlenecks that automation cannot fully offset during transitional deployment phases.
- Compliance Officers:Regulatory personnel document adherence to FDA, OSHA, and EU AI Act mandates through audit trails and algorithmic transparency reports.
- Inspection Agencies:Third-party certification bodies provide independent verification services for supplier qualification and regulatory submission support.
Quality Control represents the largest installed base; Maintenance Teams are gaining share fastest as predictive maintenance programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device-quality regulations anchor United States procurement criteria, while the EU AI Act imposes algorithmic transparency mandates across European safety-critical deployments. Industrial clusters in southern Germany and aerospace hubs in France concentrate advanced manufacturing demand.
United States
Aerospace MRO facilities and automotive assembly lines drive phased array ultrasonic and machine vision procurement. FDA 21 CFR Part 820 quality system regulations mandate dimensional verification protocols for medical device manufacturers. Houston's energy corridor and Seattle's aerospace cluster anchor oil and gas remote monitoring deployments.
Germany
Automotive OEMs and precision engineering suppliers require sub-micron dimensional verification for electric drivetrain components. The EU AI Act conformity requirements accelerate certified edge-AI platform procurement for automated pass-fail determinations. Munich-Stuttgart industrial clusters pull advanced coordinate measuring systems into production lines.
France
Aerospace suppliers deploy automated flaw-detection systems to eliminate human error in turbine blade inspections. REACH substance restrictions force recalibration of eddy current systems for cadmium-free corrosion protection layers. Toulouse and Nantes aerospace hubs concentrate MRO facility investment.
China
Heavy manufacturing expansion and domestic automotive production create demand for automated quality control systems. GB standards and MIIT industrial policy shape local certification requirements. Yangtze River Delta manufacturing corridors integrate digital inspection into smart factory initiatives.
Japan
Precision electronics and automotive component manufacturing sustain metrology-grade equipment demand. METI industrial standards and JIS certification requirements structure procurement decisions. Nagoya automotive cluster and Kanto precision engineering belt anchor coordinate measuring system deployment.
Digital Inspection Tools Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated positions in phased array ultrasonic and machine vision hardware contrasting against fragmented software and services provision. The market separates into three strategic archetypes: capital-intensive sensor platform vendors, integrated machine vision specialists, and subscription analytics providers. Competitive moves concentrate on M&A for technology tuck-ins and strategic partnerships for edge-AI distribution.
Within the integrated sensor tier, General Electric and Olympus exemplify capital-intensive platform vendors with deep R&D commitments. Cognex anchors the machine vision specialist position with tightly integrated software-hardware stacks. These three occupy positions spanning aerospace MRO, automotive assembly, and heavy manufacturing verticals.
| Leading Market Players |
|---|
| General Electric |
| Olympus |
| Mistras Group |
| Cognex |
| Hexagon |
| Zetec |
| Nikon |
| Omron |
| Keyence |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with Taiwan and South Korea foundries lock in edge-AI processor access while anchoring hardware platform pricing visibility for inspection system vendors navigating silicon supply volatility. These contractual structures bundle volume commitments with fixed-price tranches that insulate aerospace OEMs from spot-market semiconductor inflation.
Pricing Analysis
German industrial buyers face 15-20% hardware premiums over North American equivalents due to EU AI Act certification costs embedded in edge-AI platforms. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade phased array systems from automotive machine vision and mid-tier contract manufacturer offerings. Cost compression in standard-tier ultrasonic equipment is intensifying because South Korean entrants are undercutting established sensor vendors on replacement probe arrays. Mid-tier contract manufacturers exhibit highest price sensitivity; aerospace MRO facilities demonstrate lowest sensitivity due to downtime cost structures.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for neural network inference modules, while Germany and Japan concentrate precision sensor assembly and metrology-grade calibration. Hardware production draws from gallium arsenide substrates, rare-earth magnetic components, and specialized optical glass. Single-source vulnerability concentrates in EUV lithography equipment for sub-7nm edge processors. Distribution runs through authorized distributor networks with factory-direct relationships for aerospace and automotive OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified NDT Level III certificants command compensation premiums that outpace automation substitution timelines, creating persistent capability gaps that reshape competitive positioning across heavy manufacturing verticals.
For Market Incumbents: Fortify algorithmic explainability investments ahead of EU AI Act enforcement waves that will disqualify black-box neural architectures from safety-critical aerospace contracts. Deepen backward integration into edge-AI processor supply through strategic foundry partnerships that bypass Taiwan concentration risk. For New Entrants and Emerging Players: Lead with drone-mounted ultrasonic subscription services targeting offshore wind operators in the North Sea and Baltic Sea, where equipment-as-a-service models displace capital-intensive platform sales. White-space concentration sits in corrosion-rate forecasting analytics for Permian Basin pipeline operators seeking to outsource predictive maintenance infrastructure. For Investors and Strategic Acquirers: Edge-AI software specialists with embedded interpretability layers represent the most defensible acquisition archetype as regulatory compliance becomes a procurement gate. Long-term viability hinges on recurring revenue share exceeding 40% of total contract value. The signal to watch is ISO 17025 accreditation backlog duration as a proxy for vendor qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Unlocks aerospace and medical device procurement channels requiring algorithmic transparency documentation. |
| Edge-AI Processor Supply Agreement | Secures neural network inference capacity from Taiwan and South Korea foundries amid geopolitical disruption risk. |
| Subscription Analytics Platform Launch | Captures recurring revenue pools in oil and gas remote monitoring where operators prefer service consumption. |
| Drone-Mounted Ultrasonic Integration | Addresses offshore wind blade inspection demand across North Sea installations with cellular backhaul connectivity. |
| ISO 17025 Laboratory Accreditation | Enables vendor qualification for aerospace and medical device verticals with 12-18 month validation cycles. |
Methodological Framework
A standing panel of NDT Level III certificants, aerospace MRO procurement directors, automotive quality engineers, and edge-AI platform architects provided ongoing calibration across primary interview cycles. Secondary validation drew from FAA airworthiness directives, EASA certification databases, FDA 510(k) filings, and MIIT smart factory policy disclosures. Bottom-up unit economics triangulated against top-down market sizing from customs trade data and industrial automation capital expenditure surveys.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor equipment trade associations and metrology instrument shipment reports. The analytical framework modeled product type, technology tier, application vertical, and end-user archetype dimensions across the projection horizon. CAGRs derived from segment-level growth rate convergence with macro industrial production indices and regulatory implementation timelines for EU AI Act conformity requirements.
Forecasts assume regulatory continuity in EU AI Act enforcement and FDA 21 CFR Part 820 quality system mandates; material policy shifts would require re-modeling pass-fail algorithm deployment schedules. Specific risks include REACH substance restriction expansion affecting eddy current calibration protocols and Taiwan Strait disruption extending edge-AI processor lead times. Recalibration cycles align with material shifts in NDT technician labor availability and aerospace MRO facility automation procurement waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Roughness Tester Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
EMC Testing Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Heat Deformation Tester Market