
 5G Testing Devices Market | 2026-2036
5G Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
5G Testing Devices Market Insights
RF engineering talent scarcity is reorganizing vendor priorities across the 5G testing landscape. Keysight Technologies leverages deep calibration IP to dominate mmWave validation workflows. Rohde & Schwarz sustains European laboratory market share through dense channel emulation portfolios. Anritsu Corporation anchors Asia-Pacific field testing with portable spectrum analyzer platforms.
5G testing devices comprise calibrated instrumentation for measuring radio frequency performance across sub-6 GHz and millimeter-wave bands, typically achieving phase noise below -100 dBc per Hz and EVM accuracy within 0.5 percent for 256-QAM signals. These instruments enable conformance verification against 3GPP Release 16 and 17 specifications prior to network equipment authorization. Network emulators capture the largest margin pool as carriers validate core-to-radio latency under one millisecond for ultra-reliable low-latency service classes. Massive MIMO test sets represent the fastest-expanding technology segment, driven by 64T64R antenna array commissioning requirements. Field testing applications absorb disproportionate capital allocation as operators shift from laboratory qualification to live network optimization.
FCC Part 27 rules and the EU Radio Equipment Directive shape product access requirements across North America and Europe, compelling manufacturers to pre-certify for regional emission masks and spectrum aggregation protocols. China's MIIT issues mandatory GB standard compliance certificates for 5G new radio equipment before commercial deployment. Stakeholders must monitor O-RAN Alliance test specifications as disaggregated baseband architectures proliferate and redefine interoperability benchmarks.
Market Dynamics
The transition from 5G non-standalone to standalone architectures is forcing testing vendors to recalibrate their portfolios for core network validation, creating a bifurcation between legacy LTE-interoperable equipment and native 5G instrumentation.
Growth Catalysts
- MIIT Certification Mandates:China's Ministry of Industry and Information Technology requires domestic base station interoperability testing before commercial licensing, creating captive demand for network emulators and protocol analyzers.
- O-RAN Disaggregation:The O-RAN Alliance's open interface specifications are multiplying test points across radio units, distributed units, and central units, expanding the addressable instrument count per deployment.
- mmWave Spectrum Allocation:Auctions in the United States, Germany, and Japan for 26 GHz and 28 GHz bands are accelerating demand for calibrated over-the-air test chambers and beamformer validation systems.
Market Restraints
- GaN Semiconductor Supply Concentration:Gallium nitride substrates essential for high-frequency test equipment face production bottlenecks concentrated in Japanese and Korean foundries, constraining amplifier module availability.
- FCC Equipment Authorization Complexity:Part 27 and Part 30 certification timelines for 5G new radio have extended to 14-18 months, delaying revenue recognition for manufacturers dependent on North American market access.
- Software-Defined Radio Substitution:Low-cost SDR platforms from commercial vendors are encroaching on entry-level spectrum analysis applications, compressing margins for traditional hardware suppliers.
Strategic Opportunities
- Private Network Deployments:Industrial campuses in Germany, Japan, and the United States are procuring dedicated 5G infrastructure, creating demand for localized drive-test and optimization services outside carrier procurement channels.
- EU Cybersecurity Certification:The European Cybersecurity Act's forthcoming 5G network equipment assurance framework will mandate security testing modules, opening adjacent revenue streams for vulnerability assessment tools.
- AI-Driven Test Automation:Machine learning algorithms for anomaly detection in massive MIMO channel measurements are converging with robotic positioning systems, enabling unattended conformance testing workflows.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave circuit design expertise pools concentrate in defense and satellite communications sectors, forcing test vendors to compete for specialized microwave engineering resources.
- Multi-Band Certification Overlap:Simultaneous 3GPP Release 16, 17, and 18 validation requirements are extending product development cycles and fragmenting R&D allocation across incompatible protocol stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Testing Devices Market |
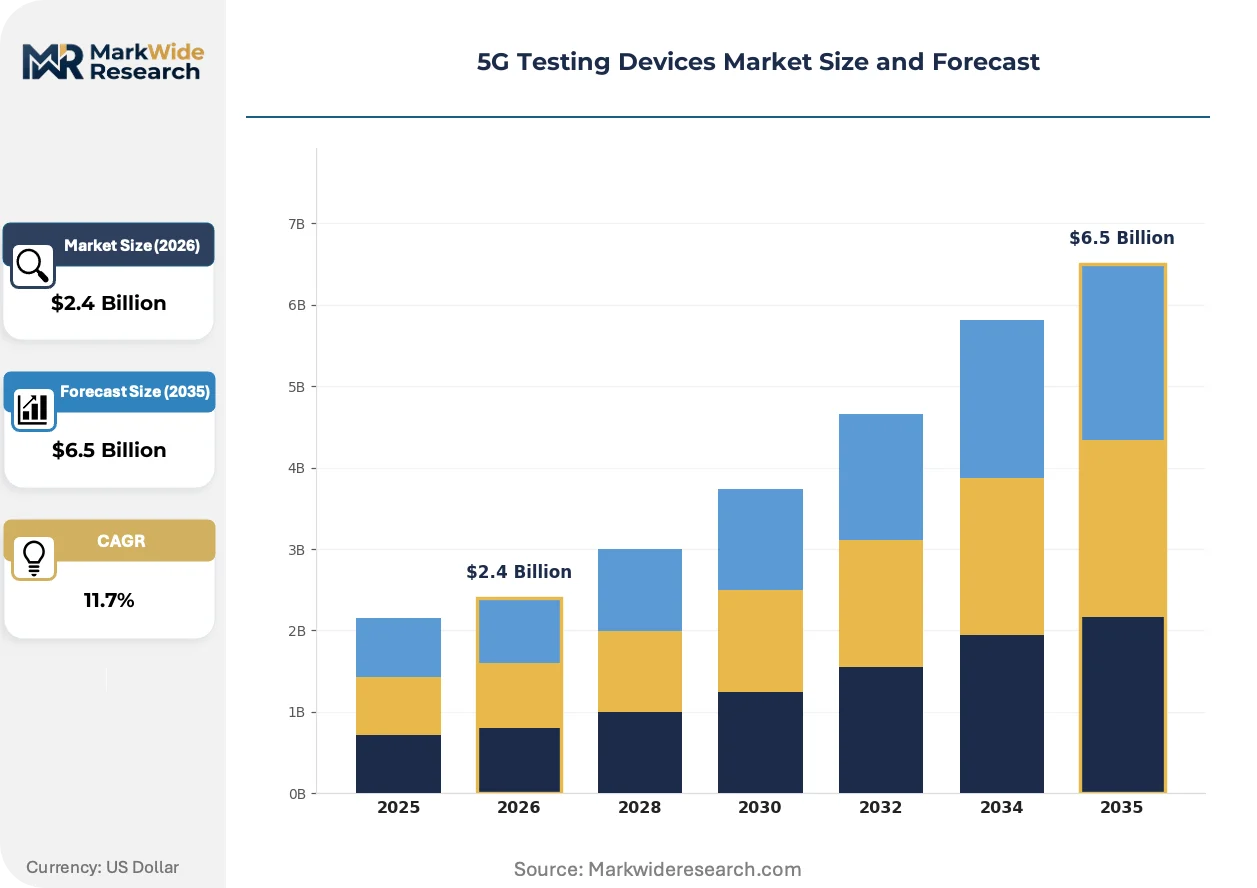
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Network Emulator, Signal Generator, Channel Emulator, Test Set Technology: Sub-6 GHz, mmWave, Hybrid, Massive MIMO Application: Field Testing, Laboratory Testing, Performance Validation, Network Planning End User: Telecom Operators, Network Equipment Providers, Research Institutions, Enterprises |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu Corporation, National Instruments Corporation, Teradyne Inc., Spirent Communications, VIAVI Solutions Inc., EXFO Inc., Intertek Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Testing Devices Market Trends and Innovations
Testing instrumentation is pivoting from laboratory-centric validation toward continuous monitoring architectures embedded within live network operations, blurring historical boundaries between R&D and deployment-phase equipment categories.
Over-the-air test methodologies for massive MIMO arrays are fragmenting traditional conducted testing workflows. Base station manufacturers now require spherical near-field chambers capable of 64-element beamforming validation. Tier-one operators in South Korea and the United States are adopting these systems for pre-deployment screening, compressing field trial durations from months to weeks.
REACH restrictions on fluorinated greenhouse gases are compelling European test chamber manufacturers to redesign thermal management systems for environmental chambers. The F-Gas Regulation's phasedown schedules are accelerating adoption of CO2-based cascade refrigeration in climatic test equipment. German and French certification laboratories are retrofitting existing infrastructure to maintain EU market access for temperature-cycled RF validation.
Carrier procurement departments are unbundling hardware acquisition from calibration service contracts, reversing decade-long bundled pricing conventions. Network operators in Japan and the United Kingdom are negotiating separate multi-year metrology agreements with third-party calibration houses. This disaggregation is visible most acutely in the United States, where Verizon and T-Mobile have issued distinct RFPs for instrument maintenance distinct from capital equipment purchases.
5G Testing Devices Market Segmentation
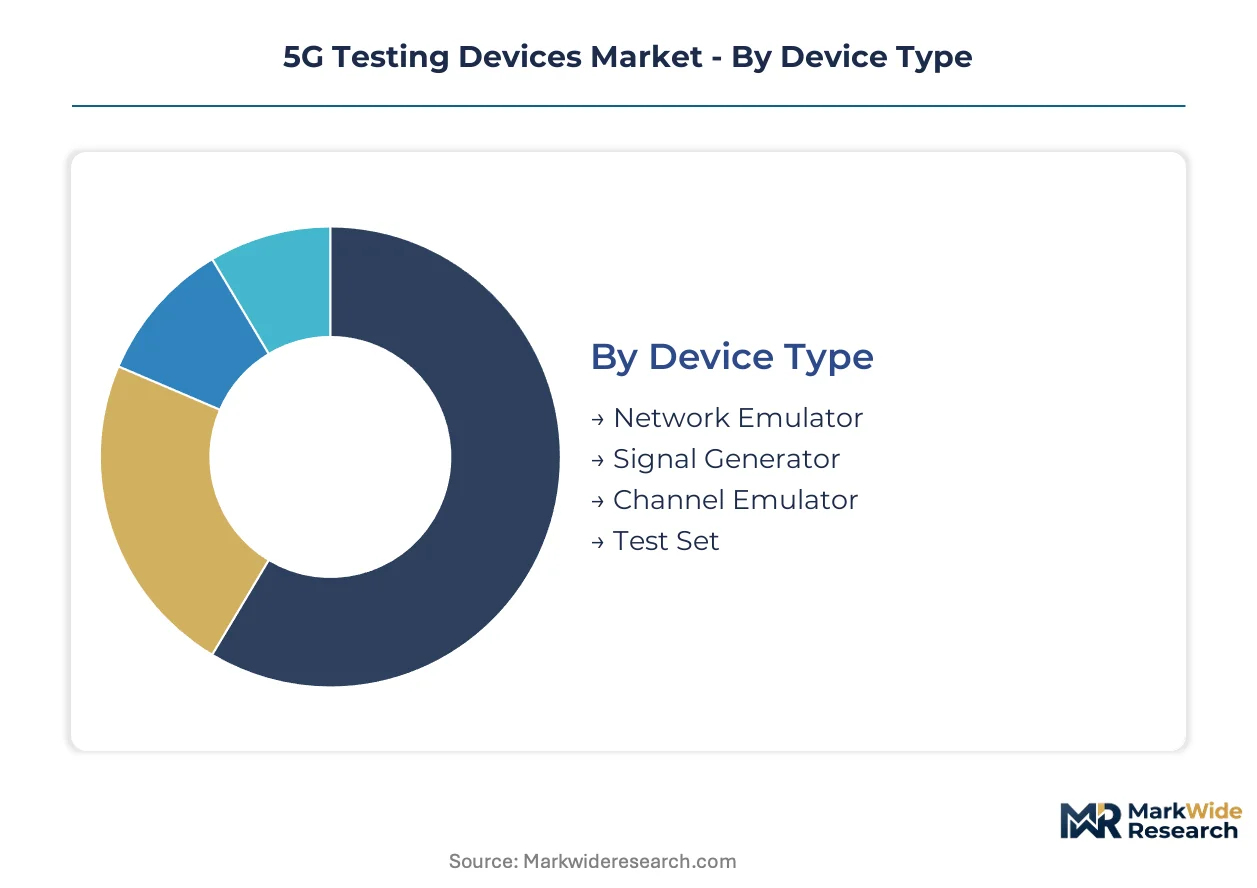
5G testing device procurement channels diverge sharply by segment complexity. Network emulators flow through carrier direct contracts, while portable analyzers distribute via specialized test equipment resellers. Understanding these channel dynamics reveals where margin pools concentrate and which segments face pricing pressure from software-defined alternatives.
Device Type:
Network emulators dominate carrier capital budgets, while signal generators concentrate in R&D laboratory procurement channels. Channel Emulator and Test Set volumes flow through equipment lessors serving mid-tier manufacturers.
- Network Emulator:Hardware-software systems replicate 5G core and radio access network behavior under controlled load conditions. China's MIIT certification mandates for base station interoperability concentrate demand among domestic equipment manufacturers seeking commercial licensing. These systems command the highest unit economics due to protocol stack complexity.
- Signal Generator:Calibrated sources produce precise RF waveforms for receiver sensitivity and spurious emission testing. South Korean and Japanese semiconductor fabs anchor demand for sub-6 GHz and mmWave variants supporting 3GPP Release 16 conformance. Modular architectures allow frequency band upgrades without full instrument replacement.
- Channel Emulator:Replicates multipath fading and Doppler effects for mobility scenario validation.
- Test Set:Integrated platforms combining signal generation, analysis, and reporting for field technicians.
By volume, Test Set leads due to fleet deployment across operator maintenance organizations. By growth pace, Network Emulator is ahead on standalone core network validation requirements.
Technology:
Cost tiers separate these segments sharply. mmWave instrumentation carries 3-4x sub-6 GHz pricing due to GaN amplifier content and precision machining requirements. Massive MIMO test systems occupy a premium tier between hybrid and dedicated mmWave platforms.
- Sub-6 GHz:Workhorse frequency range covering 3.3-4.2 GHz and 4.4-5.0 GHz bands with mature amplifier architectures. Indian and Southeast Asian operators anchor volume demand as these markets prioritize coverage over peak capacity. Equipment authorization timelines compress relative to mmWave variants due to established FCC Part 27 precedents.
- mmWave:26 GHz, 28 GHz, and 39 GHz validation requires over-the-air chambers with positioning robotics and thermal management. United States and German spectrum auctions concentrate demand among base station manufacturers qualifying beamforming arrays. REACH F-Gas Regulation compliance adds cost to European climatic test chamber procurement.
- Hybrid:Dual-band instruments switching between sub-6 GHz and mmWave operation for flexible R&D workflows.
- Massive MIMO:Dedicated test systems for 64T64R antenna array calibration and beam pattern verification.
By volume, Sub-6 GHz leads on deployment scale across emerging markets. By margin contribution, mmWave is ahead due to specialized component content and calibration service attachment rates.
Application:
Customer type determines procurement patterns here. Field testing applications sell to carrier operations departments with recurring calibration contracts. Laboratory testing serves R&D budgets with longer replacement cycles but higher per-unit specifications.
- Field Testing:Portable spectrum analyzers and drive-test systems validate live network coverage and interference conditions. Verizon and T-Mobile procurement in the United States favors ruggedized platforms with cloud-connected data upload. Battery life and IP67 environmental sealing differentiate competitive offerings.
- Laboratory Testing:Controlled-environment validation against 3GPP conformance specifications precedes regulatory submission. European notified bodies and FCC Telecommunication Certification Bodies anchor demand for fully documented test campaigns. Automation software integration reduces technician labor content per test sequence.
- Performance Validation:Latency and throughput benchmarking for ultra-reliable low-latency service classes.
- Network Planning:Propagation modeling tools supporting 5G site selection and capacity forecasting.
By volume, Field Testing leads on fleet deployment across maintenance organizations. By value concentration, Laboratory Testing is ahead due to chamber infrastructure and software licensing components.
End User:
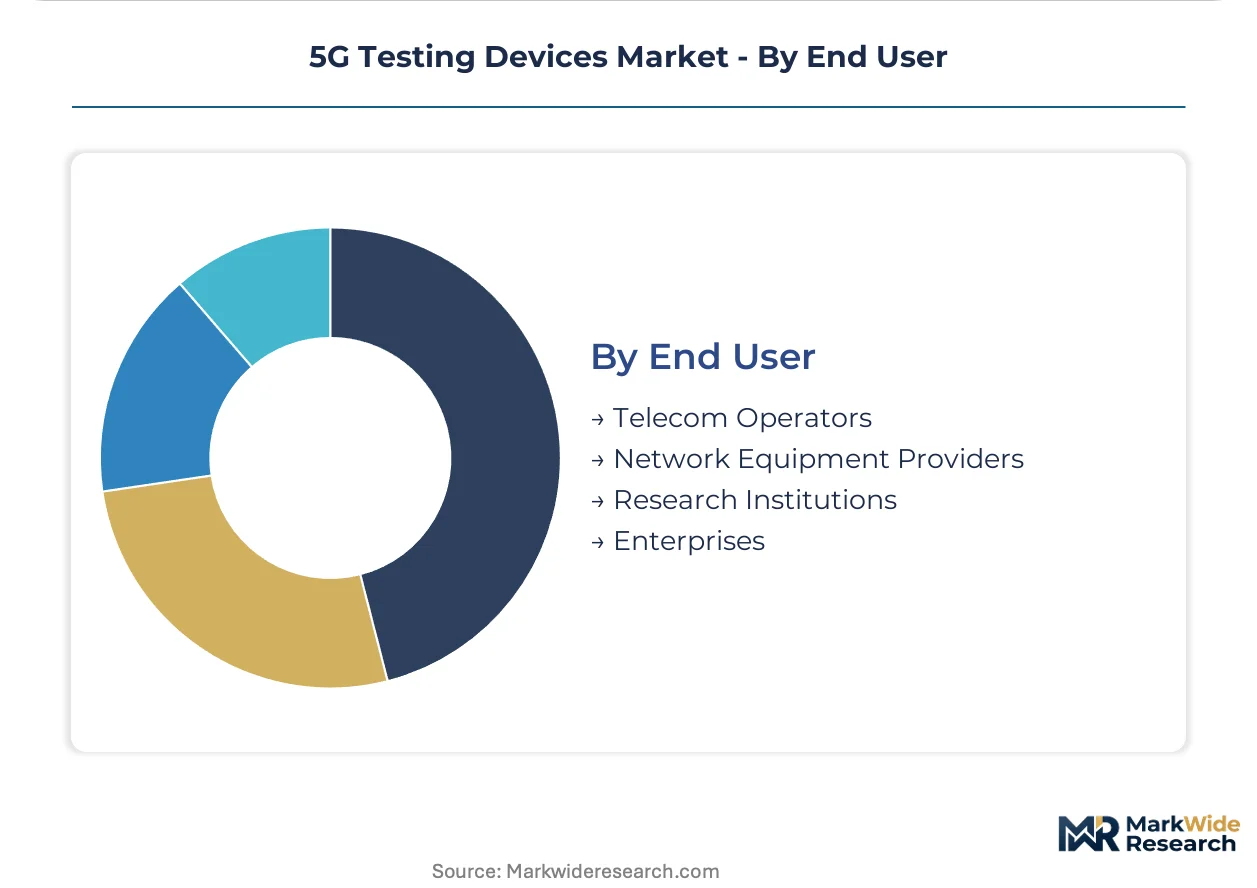
Maturity stages differentiate these segments. Telecom operators represent established demand with formalized procurement processes. Enterprise adopters exhibit exploratory buying patterns with shorter decision cycles but smaller transaction sizes.
- Telecom Operators:Tier-one carriers in Japan, South Korea, and the United States maintain dedicated test laboratories with multi-year instrument refresh programs. NTT Docomo and SK Telecom specify custom firmware features supporting proprietary network optimization workflows. Volume commitments secure preferred pricing and priority technical support access.
- Network Equipment Providers:Base station and core network manufacturers validate products before operator tender submission. Ericsson, Nokia, and Huawei internal laboratories anchor demand for high-channel-count emulators. Pre-certification investment accelerates as O-RAN disaggregation multiplies interoperability test points.
- Research Institutions:University and government laboratories pursue 3GPP Release 17 and 18 early validation.
- Enterprises:Industrial campuses and private network operators procure localized test capabilities outside carrier channels.
By volume, Telecom Operators lead on fleet scale and replacement cycles. By expansion trajectory, Enterprises are climbing the fastest on private 5G deployment momentum in Germany, Japan, and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification mandates in China concentrate base station interoperability demand, while FCC Part 27 rules and EU F-Gas Regulation reshape equipment authorization timelines across North America and Europe.
United States
Verizon and T-Mobile drive field testing fleet procurement for live network optimization. FCC Part 27 and Part 30 certification timelines now stretch 14-18 months, compressing vendor revenue recognition. The Dallas-Fort Worth metroplex anchors domestic test laboratory concentration for mmWave beamforming validation.
China
Domestic equipment manufacturers face mandatory GB standard compliance before commercial 5G NR deployment. MIIT interoperability testing requirements for base stations create captive demand for network emulators. Shenzhen and Beijing host the principal concentration of conformance laboratories serving Huawei and ZTE supply chains.
Germany
Industrial campuses in Bavaria and North Rhine-Westphalia procure private 5G infrastructure outside carrier channels. REACH F-Gas Regulation mandates CO2-based thermal systems in climatic test chambers, adding retrofit costs. Munich anchors European laboratory market share for O-RAN disaggregation test points.
Japan
NTT Docomo and SoftBank maintain dedicated test laboratories with multi-year instrument refresh programs. METI spectrum policy for 28 GHz band allocation accelerates mmWave chamber demand. Tokyo-Osaka corridor concentrates R&D procurement for 3GPP Release 16 and 17 conformance.
South Korea
SK Telecom and KT Corporation specify custom firmware for proprietary network optimization workflows. National 5G spectrum auction outcomes mandate rapid beamformer validation for 26 GHz deployment. Seoul metropolitan area hosts spherical near-field chamber installations for 64T64R antenna array commissioning.
5G Testing Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with portfolio breadth separating premium-positioned vendors from focused instrumentation providers. The upper tier commands carrier direct contracts through bundled hardware-calibration service offerings, while specialists capture R&D laboratory niches with modular frequency-upgradeable platforms. Two dominant competitive moves define current positioning: geographic expansion into private network deployment zones and strategic partnerships with O-RAN Alliance test specification development. Technology licensing for mmWave calibration intellectual property represents a secondary vector for differentiation.
Within the integrated instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify full-spectrum portfolio positioning across sub-6 GHz and millimeter-wave validation workflows. Anritsu Corporation anchors the Asia-Pacific field testing segment through portable spectrum analyzer platforms. These three entities represent distinct geographic anchoring strategies—United States, Germany, and Japan respectively—while occupying complementary positions in the laboratory-to-field equipment continuum.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu Corporation |
| National Instruments Corporation |
| Teradyne Inc. |
| Spirent Communications |
| VIAVI Solutions Inc. |
| EXFO Inc. |
| Intertek Group Plc |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month FCC equipment authorization timelines concentrate pricing power among vendors with pre-certified module libraries, while GaN amplifier inventory cycles of 90-120 days tether cost structures to Japanese and Korean foundry output schedules. Buyers with multi-year metrology contracts negotiate hardware-calibration bundles that compress margins for standalone instrument suppliers.
Pricing Analysis
United States-Germany price spreads of 15-25 percent reflect REACH F-Gas Regulation compliance costs for European climatic test chambers. Three-tier pricing structure across premium, standard, and economy levels segments by calibration IP depth and channel emulation channel count. Cost compression in entry-level spectrum analysis intensifies because software-defined radio platforms displace hardware analyzers below 6 GHz. Enterprise private network buyers exhibit highest price sensitivity; tier-one carriers with dedicated laboratory budgets show lowest.
Supply Chain Analysis
Ninety-to-one-hundred-twenty-day GaN substrate lead times concentrate upstream dependency on Japanese and Korean foundries for high-frequency amplifier modules. Manufacturing draws from precision machining clusters in Germany, semiconductor packaging in Taiwan, and RF component assembly in China. Single-source vulnerability sits with gallium nitride wafer suppliers exposed to export licensing protocols. Distribution runs through carrier direct contracts for network emulators and specialized test equipment resellers for portable analyzers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
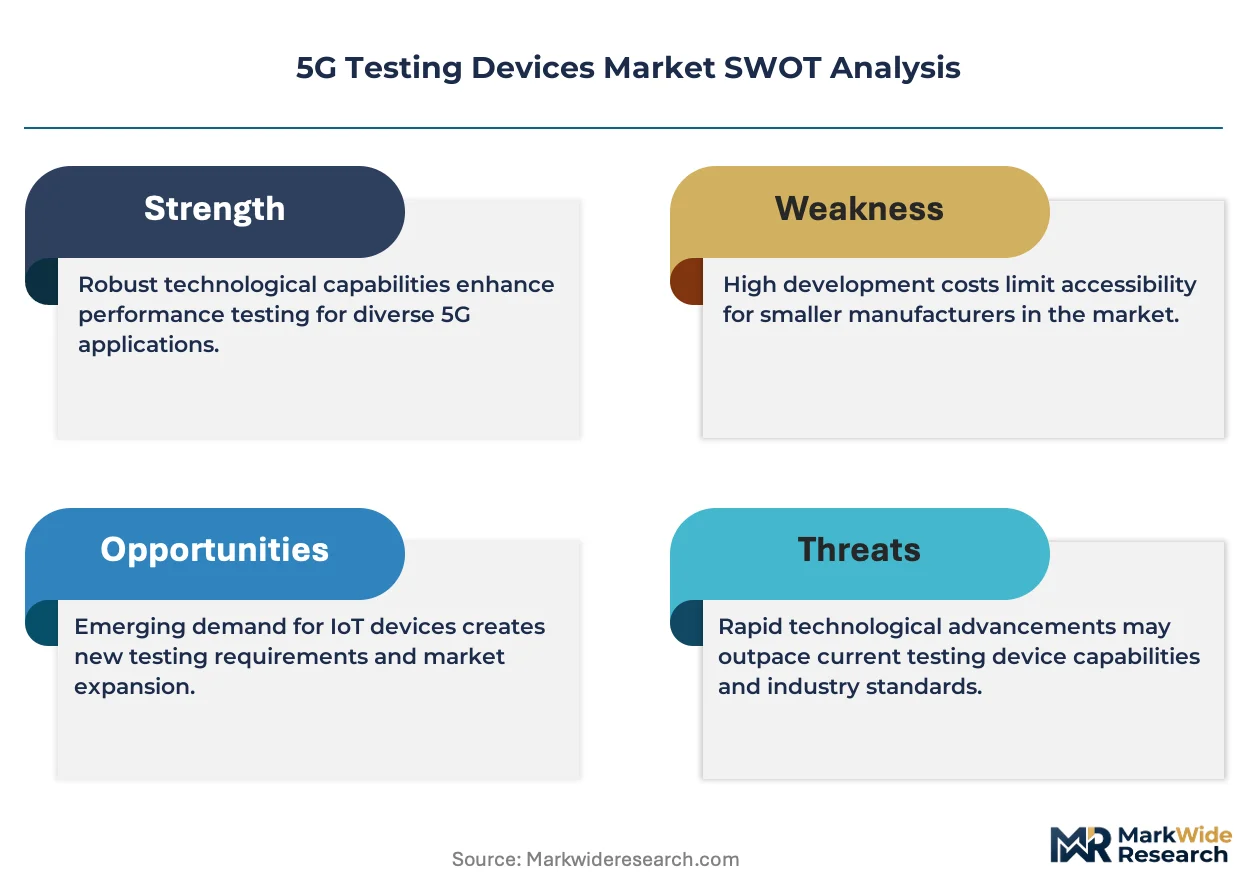
This market functions as a regulatory-entrenchment defensive moat: MIIT, FCC, and EU authorization requirements create multi-year certification backlogs that embed incumbent relationships and fragment competitive entry.
For Market Incumbents: Compound calibration IP moats through acquisition of third-party metrology houses in Japan and Germany, reversing carrier procurement disaggregation trends. Deepen GaN amplifier backward integration to offset single-source foundry exposure. Anchor priority technical support contracts with NTT Docomo and SK Telecom to lock out modular-upgrade competitors. For New Entrants and Emerging Players: Lead with AI-driven test automation modules that attach to existing Keysight and Rohde & Schwarz installed bases rather than displacing core hardware. Private 5G deployments in German industrial campuses offer the most penetrable geography outside carrier procurement channels. Pursue O-RAN Alliance specification development partnerships to embed interface test points before standards finalize. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture compounder because certification timeline extensions and multi-release 3GPP validation requirements continuously refresh incumbent revenue visibility. Target acquisition profile centers on mmWave calibration specialists with spherical near-field chamber IP and established FCC TCB relationships. Watch for MIIT expanding GB standard mandates to terminal devices as inflection signal for emulator demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Unbundling | Verizon and T-Mobile's separate RFPs for instrument maintenance create third-party metrology house acquisition targets. |
| AI-Driven Test Automation | Machine learning anomaly detection converges with robotic positioning to enable unattended massive MIMO conformance workflows. |
| GaN Supply Security Investment | Japanese and Korean foundry capacity constraints force amplifier module manufacturers toward captive wafer supply arrangements. |
| O-RAN Test Specification Embedding | Radio unit, distributed unit, and central unit disaggregation multiplies instrument count per deployment for early specification contributors. |
| Private Network Field Service Expansion | Industrial campuses in Bavaria and North Rhine-Westphalia procure localized drive-test capabilities outside traditional carrier channels. |
Research Methodology
Desk research of 3GPP release documentation, FCC equipment authorization databases, and EU notified body conformity records preceded structured interviews with RF test laboratory directors, carrier procurement officers, and semiconductor foundry planning executives. Primary fieldwork with base station manufacturers in Shenzhen and Seoul validated secondary trade flow analysis. Bottom-up instrument shipment tracking triangulated against top-down carrier capital expenditure disclosures.
Variance decomposition across device type, technology band, and application use case shaped analytical framework outputs over the projection horizon. Segmentation dimensions modeled include network emulator versus signal generator procurement channels, sub-6 GHz versus mmWave frequency tiers, and field testing versus laboratory validation environments. CAGRs derived from instrument replacement cycle analysis and spectrum auction pipeline timing. O-RAN disaggregation test point multiplication and MIIT certification mandate expansion served as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained 5G standalone deployment momentum or accelerated O-RAN commercialization would require recalibration. Forecasts reflect assumptions of stable GaN substrate supply and continued regulatory fragmentation across FCC, MIIT, and EU authorization regimes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Test Socket Market
Test and Measurement
Digital Multimeter Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Slovakia and Czech Republic Calibration Services Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Dosimeter Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Analog Multimeters Market