
 Triethyl Citrate Market | 2026-2036
Triethyl Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Triethyl Citrate Market Analytics
The capital-intensity divergence between fermentation-based and chemical-synthesis routes is unwinding competitive parity among established producers. Jungbunzlauer leverages its integrated citric acid fermentation platform to sustain European supply reliability. BASF SE anchors industrial-scale chemical esterification capacity for coating and polymer applications. Vertellus competes through specialized high-purity grades targeting pharmaceutical excipient qualifications.
Triethyl citrate is the ethyl ester of citric acid, produced through esterification of citric acid with ethanol under acid catalysis, yielding a colorless, odorless liquid with a boiling point near 294°C and excellent compatibility with cellulose derivatives. It functions primarily as a non-phthalate plasticizer, solvent, and film-forming agent across pharmaceutical coatings, food packaging, and cosmetic formulations. Plasticizers command the largest volume share as formulators replace restricted orthophthalates in enteric and sustained-release tablet coatings. Pharmaceutical applications represent the fastest-expanding segment as excipient qualification standards tighten under USP and EP monographs, while food additive grades face margin compression from commoditized citrate supply.
REACH restrictions on phthalate plasticizers and FDA guidance on inhalation drug device materials reshape formulation specifications across the European and North American markets. China's GB standards and NMPA pharmaceutical excipient registration requirements create divergent compliance pathways for exporters. Stakeholders must monitor regulatory parity between pharmacopeial monographs and evolving national chemical inventory listings to secure long-term formulation approvals.
Market Dynamics
The transition from phthalate-based to citrate ester plasticizers is restructuring procurement priorities across pharmaceutical and polymer supply chains, with excipient qualification timelines now determining supplier selection criteria.
Growth Catalysts
- REACH phthalate restrictions:The European Chemicals Agency's ongoing evaluation of orthophthalates in medical devices and food contact materials is accelerating substitution programs among coating formulators.
- Controlled-release drug expansion:Sustained-release tablet coatings for chronic disease therapeutics are consuming higher-grade triethyl citrate volumes as pharmaceutical pipelines pivot toward long-acting oral dosages.
- China's citric acid fermentation scale:Domestic production capacity expansion in Shandong and Jiangsu provinces is compressing regional raw material costs and enabling downstream esterification economics.
Market Restraints
- Ethanol feedstock volatility:Bioethanol pricing fluctuations tied to corn harvest cycles and fuel-blending mandates in the US and Brazil create margin unpredictability for ester producers.
- Pharmacopeial qualification duration:USP and EP monograph compliance timelines extending 18-24 months for new excipient grades delay market entry for emerging suppliers.
- Acetyl tributyl citrate substitution:Higher-molecular-weight citrate esters with lower migration rates are capturing share in food packaging applications where fat contact resistance matters.
Strategic Opportunities
- Inhalation device materials:FDA guidance on leachables and extractables in metered-dose inhalers is opening qualification pathways for high-purity grades previously reserved for parenteral applications.
- India's pharmaceutical excipient localization:CDSCO's push for domestic active pharmaceutical ingredient and excipient manufacturing under production-linked incentive schemes creates import-substitution demand.
- Biodegradable polymer compatibilization:Polylactic acid and polyhydroxyalkanoate processors are testing citrate esters as processing aids to improve flexibility without compromising compostability certification.
Industry Challenges
- Excipient master file navigation:Drug master file compilation and Type II drug master file reference procedures demand specialized regulatory affairs capabilities that mid-scale producers struggle to staff.
- Batch-to-batch pharmacopeial consistency:Maintaining USP-specified ester content, acidity, and water specifications across fermentation-derived citric acid feedstocks requires analytical infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triethyl Citrate Market |
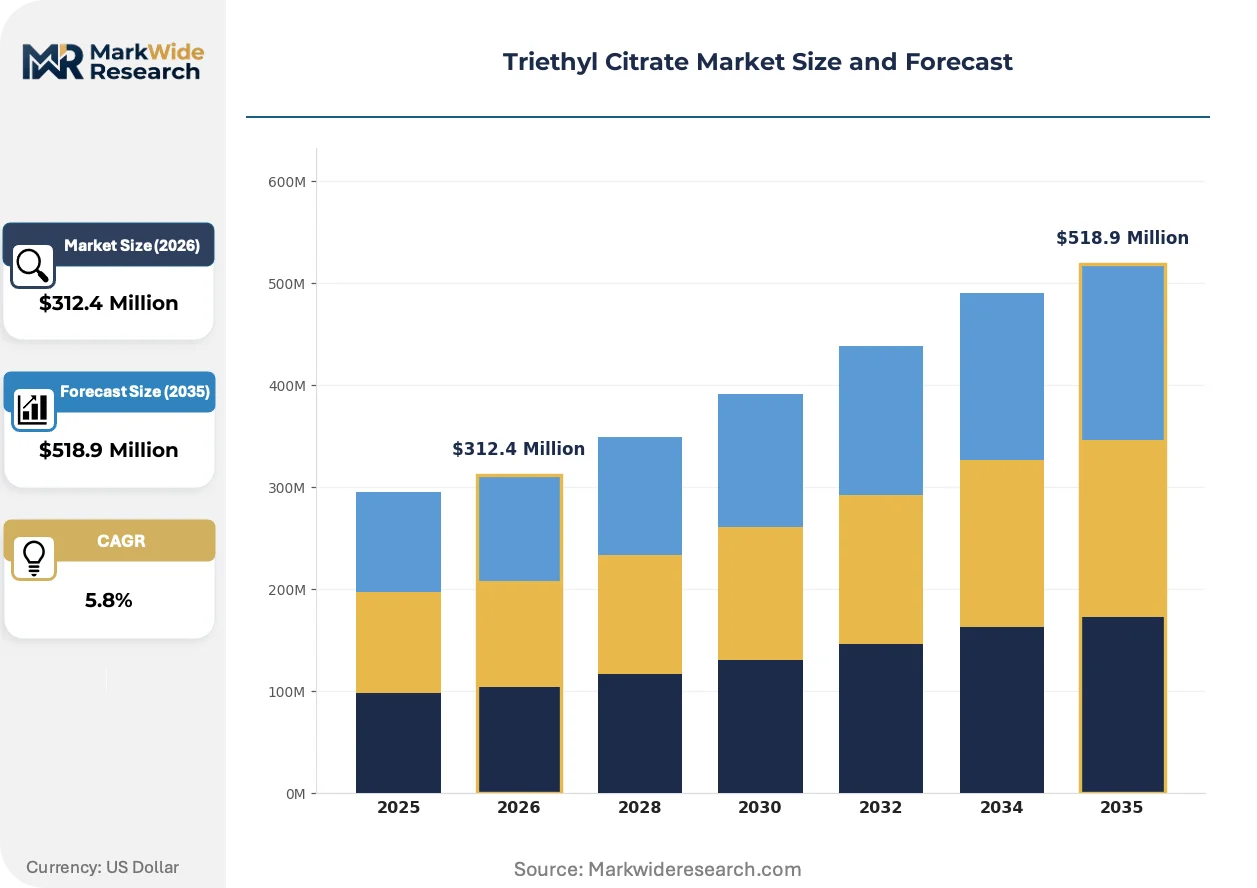
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Food Additives, Solvents, Cosmetic Ingredients Application: Pharmaceuticals, Food & Beverage, Personal Care, Industrial Coatings End User: Pharmaceutical Manufacturers, Food Processors, Cosmetic Brands, Chemical Industries Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Shandong Kunda Biotechnology, Fuso Chemical, Jungbunzlauer, Tokyo Chemical Industry, Anhui Leafchem, Merck KGaA, Zhengzhou Meiya Chemical, BASF SE, Vertellus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triethyl Citrate Market Evolving Landscape
Process intensification and regulatory chemistry are converging to redefine manufacturing economics and product positioning across citrate ester value chains.
Continuous flow esterification reactors are displacing conventional batch processing in new capacity installations. Specialty chemical producers in Germany and Switzerland are adopting modular flow chemistry platforms to reduce solvent volumes and thermal degradation. This displacement is compressing capital requirements for pharmaceutical-grade production while tightening impurity profiles beyond batch-reactor capabilities.
REACH authorization list expansion for endocrine-disrupting phthalates is forcing reformulation across European medical device coatings. ECHA's 2024-2025 evaluation timeline for DEHP, DBP, and BBP in healthcare applications is accelerating technical documentation for citrate alternatives. Coating houses in Italy and the Netherlands are pre-qualifying triethyl citrate grades to secure uninterrupted device certification.
Pharmaceutical procurement teams are consolidating excipient supplier panels from twelve-vendor portfolios to three-vendor strategic partnerships. This concentration is displacing spot-market purchasing for film-coating plasticizers and shifting volume commitments toward multi-year supply agreements with audited manufacturing sites. The trend is most visible among US-based generic drug manufacturers facing FDA inspection intensity for supply chain documentation.
Triethyl Citrate Market Segmentation
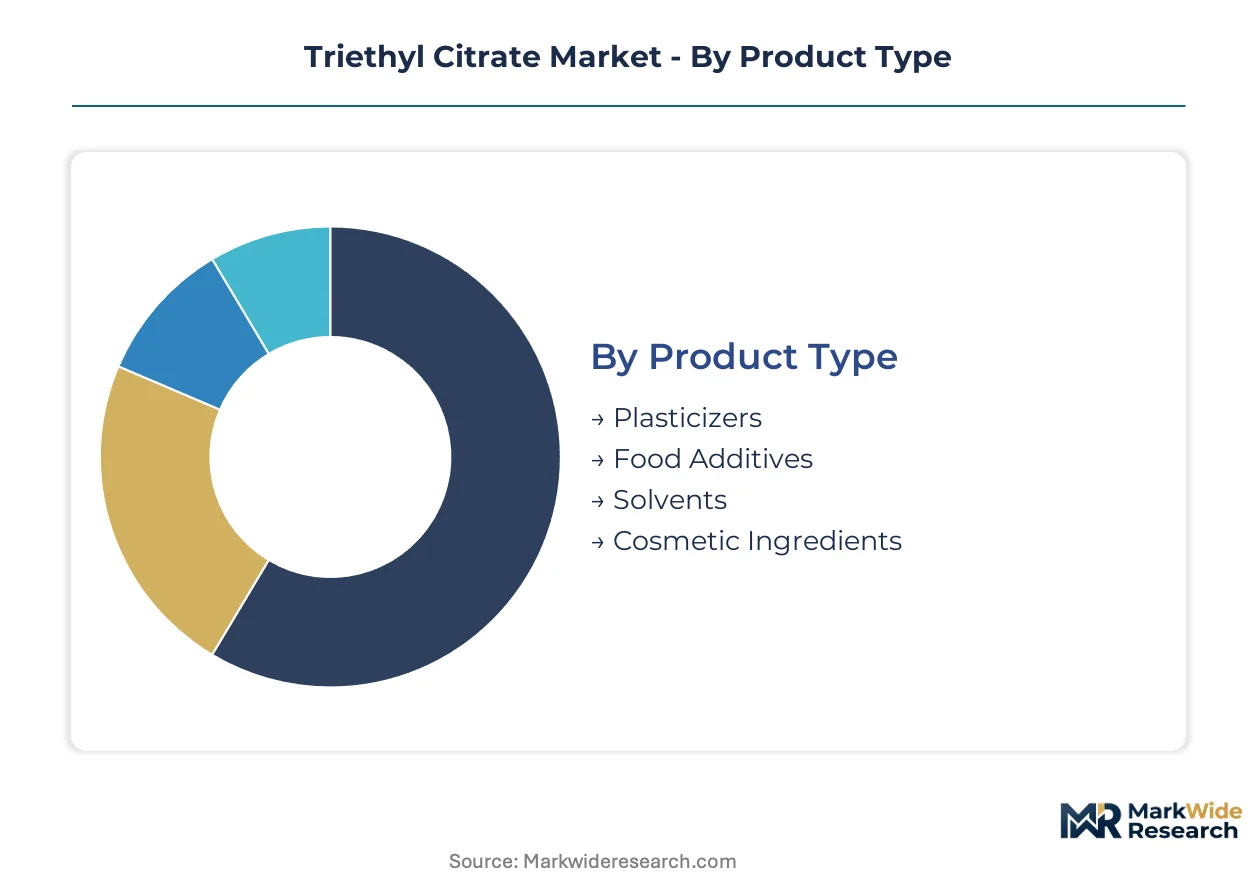
Triethyl citrate's functional versatility across plasticization, solvation, and film-forming creates distinct margin architectures by product grade and regulatory qualification level. Segmentation reveals where fermentation-derived feedstock advantages translate to pricing power versus commoditized specification pressures.
Product Type:
Margin pools concentrate in pharmaceutical-grade plasticizers where USP and EP monograph compliance commands sustained premium positioning over food and industrial specifications.
- Plasticizers:Non-phthalate plasticizers for enteric and sustained-release tablet coatings carry the highest qualification barriers and longest supplier approval timelines. Demand concentrates among generic drug manufacturers in the US and India replacing restricted orthophthalates under FDA and CDSCO guidance.
- Food Additives:Citrate ester formulations for food packaging and direct food contact face margin compression from commoditized citric acid supply and substitution pressure from acetyl tributyl citrate in high-fat applications. China's GB standards compliance dominates volume procurement.
- Solvents:High-purity solvent grades for pharmaceutical extraction and coating applications require controlled water content and acidity specifications.
- Cosmetic Ingredients:Fragrance-free, colorless grades for deodorant and skincare formulations compete on sensory neutrality and dermatological safety documentation.
Plasticizers hold installed capacity. Food Additives is rotating up the share rankings.
Application:
Application-level profitability tracks directly to regulatory scrutiny intensity and excipient master file requirements.
- Pharmaceuticals:Controlled-release tablet coatings, film-forming agents, and plasticizers for oral dosage forms represent the steepest expansion trajectory as chronic disease therapeutics pivot toward long-acting formulations. USP and EP monograph compliance timelines extending 18-24 months create defensive moats for qualified suppliers.
- Food & Beverage:Packaging plasticizers and direct food additives face accelerating substitution toward higher-molecular-weight citrate esters with superior fat-contact resistance under EFSA migration limits.
- Personal Care:Deodorant base solvents and skincare formulation additives compete on odor profile and dermatological testing documentation.
- Industrial Coatings:Cellulose derivative compatibility drives specification in specialty coating applications with lower regulatory barriers than pharmaceutical or food grades.
Pharmaceuticals captures the premium tier. Food & Beverage is compressing toward specification parity.
End User:
End-user procurement sophistication determines contract structure, with pharmaceutical manufacturers demanding audited manufacturing sites and multi-year supply agreements.
- Pharmaceutical Manufacturers:Generic drug producers and contract development manufacturing organizations consolidate supplier panels from twelve-vendor portfolios to three-vendor strategic partnerships, shifting volume commitments toward qualified fermentation-based producers with integrated citric acid supply.
- Food Processors:Packaging converters and direct food additive buyers prioritize migration testing documentation and EFSA compliance over supplier concentration.
- Cosmetic Brands:Multinational personal care companies specify dermatological safety data and REACH registration completeness.
- Chemical Industries:Industrial coating and polymer processors test citrate esters as biodegradable polymer compatibilizers for polylactic acid and polyhydroxyalkanoate applications.
Pharmaceutical Manufacturers anchor contract value. Chemical Industries is expanding trial volumes.
Distribution Channel:
Channel economics reflect lot size requirements and regulatory documentation intensity, with direct sales capturing qualified pharmaceutical volumes.
- Direct Sales:Multi-year supply agreements with audited manufacturing sites dominate pharmaceutical-grade procurement, displacing spot-market purchasing for film-coating plasticizers.
- Distributors:Regional chemical distributors serve mid-scale coating houses and food processors with standard-grade specifications.
- Online Retail:E-commerce platforms capture small-lot cosmetic ingredient and research-grade volumes.
- Wholesalers:Bulk wholesalers handle industrial-grade solvent volumes with lower documentation requirements.
Direct Sales holds contract duration. Distributors is broadening geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in pharmaceutical-grade triethyl citrate concentrates in Western Europe and the United States, while cost-competitive fermentation supply chains in Shandong and Jiangsu provinces compress margins for standard-grade material. This asymmetry shapes procurement patterns across coating formulators and generic drug manufacturers.
United States
Generic drug manufacturers and contract development organizations drive pharmaceutical-grade demand as they consolidate supplier panels under FDA inspection intensity. The agency's guidance on leachables in inhalation devices tightens qualification standards for high-purity grades. New Jersey and North Carolina pharmaceutical clusters anchor multi-year supply agreements with audited fermentation-based producers.
Germany
Coating houses in Italy and the Netherlands source through German distributors as ECHA's 2024-2025 evaluation timeline for DEHP and DBP accelerates substitution programs. REACH authorization requirements for endocrine-disrupting phthalates force reformulation across medical device coatings. BASF SE's Ludwigshafen complex anchors industrial-scale esterification capacity for polymer applications.
China
Domestic citric acid fermentation scale in Shandong and Jiangsu provinces enables downstream esterification economics for regional pharmaceutical and personal care supply chains. NMPA pharmaceutical excipient registration requirements create divergent compliance pathways for exporters. Zhengzhou and Jinan chemical clusters concentrate citrate ester production capacity serving Asia-Pacific coating formulators.
India
CDSCO's production-linked incentive schemes for domestic active pharmaceutical ingredient and excipient manufacturing generate import-substitution demand among Mumbai and Hyderabad generic producers. Excipient master file compilation requirements favor established suppliers with regulatory affairs capabilities. Gujarat and Maharashtra pharmaceutical corridors consolidate procurement toward three-vendor strategic partnerships.
Japan
Specialty chemical producers adopt modular flow chemistry platforms for pharmaceutical-grade manufacturing as PMDA tightens impurity profiling requirements. Metered-dose inhaler material qualifications open pathways for grades previously reserved for parenteral applications. Osaka and Tokyo pharmaceutical clusters test citrate esters in biodegradable polymer compatibilization for polylactic acid processing.
Triethyl Citrate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the triethyl citrate value chain. Fermentation-based producers leverage integrated citric acid platforms for feedstock security, while chemical-synthesis specialists anchor industrial-scale esterification capacity. The market structures around three archetypes: integrated fermentation platforms, industrial-scale chemical producers, and high-purity pharmaceutical specialists. Competitive moves concentrate on pharmacopeial qualification investments and backward integration into citric acid supply.
Among integrated fermentation platforms, Jungbunzlauer exemplifies European supply reliability through captive citric acid production. BASF SE occupies a position at the industrial-scale chemical synthesis tier for coating and polymer volumes. Vertellus sits within the high-purity pharmaceutical specialist archetype targeting excipient qualification standards under USP and EP monographs.
| Leading Market Players |
|---|
| Shandong Kunda Biotechnology |
| Fuso Chemical |
| Jungbunzlauer |
| Tokyo Chemical Industry |
| Anhui Leafchem |
| Merck KGaA |
| Zhengzhou Meiya Chemical |
| BASF SE |
| Vertellus |
| Others |
Value Network & Pricing Analysis
REACH authorization requirements for endocrine-disrupting phthalates simultaneously gate supplier qualification and stratify price tiers across pharmaceutical-grade triethyl citrate procurement. ECHA's evaluation timeline forces coating formulators to pre-qualify citrate alternatives, compressing margins for unqualified producers while amplifying premiums for monograph-compliant grades.
Pricing Analysis
Customization-premium spreads separate configured-to-order pharmaceutical grades from standard food and industrial specifications. Three-tier pricing structure across premium, standard, and economy levels tracks USP and EP monograph compliance, with fermentation-derived feedstock security commanding the widest spreads. Price differentiation hinges on excipient master file documentation and batch-to-batch pharmacopeial consistency. Cost compression in food additive grades is intensifying because acetyl tributyl citrate captures share in high-fat packaging applications. Generic drug manufacturers exhibit highest price sensitivity due to consolidated supplier panels, while inhalation device formulators show least sensitivity given FDA leachables guidance.
Supply Chain Analysis
Inventory positions and lead-time reliability diverge sharply between fermentation-integrated and merchant-feedstock producers. Supply concentrates in China, Germany, and India, with Shandong and Jiangsu fermentation clusters feeding downstream esterification. Raw material dependencies center on citric acid fermentation output, ethanol bioethanol pricing, and acid catalyst supply. Single-source vulnerability runs through concentrated citric acid fermentation capacity in China's eastern provinces. Distribution runs through direct multi-year agreements for pharmaceutical grades and regional distributors for standard specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified pharmacopeial documentation capabilities are scarce relative to installed esterification capacity, creating defensive moats for producers with regulatory affairs infrastructure. This asymmetry rewards early qualification investments and punishes spot-market entrants lacking master file compilation expertise.
For Market Incumbents: Fortify backward integration into citric acid fermentation to secure feedstock cost predictability against ethanol volatility. Deepen pharmacopeial qualification investments for inhalation device grades under FDA leachables guidance. Expand audited manufacturing site networks in India to capture CDSCO production-linked incentive demand. For New Entrants and Emerging Players: Lead with biodegradable polymer compatibilization trials for polylactic acid processors seeking compostability-certified plasticizers. India's pharmaceutical excipient localization under CDSCO schemes offers the most penetrable geography given import-substitution policy tailwinds. Position through specialized high-purity grades targeting metered-dose inhaler qualifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous flow esterification installations as modular chemistry platforms displace batch reactors. Long-term viability favors fermentation-integrated producers with captive citric acid supply and established regulatory affairs capabilities. Monitor ECHA authorization list expansion for DEHP and DBP as the critical inflection signal for substitution demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Fermentation | Jungbunzlauer's integrated platform demonstrates feedstock security against merchant supply volatility. |
| Continuous Flow Esterification Capacity | German and Swiss specialty producers compress capital requirements while tightening impurity profiles beyond batch capabilities. |
| Pharmacopeial Master File Compilation | USP and EP compliance timelines extending 18-24 months create defensive positioning for qualified suppliers. |
| Inhalation Device Grade Qualification | FDA guidance on leachables opens premium pathways for grades previously reserved for parenteral applications. |
| India Excipient Localization Partnership | CDSCO production-linked incentives generate import-substitution demand among Mumbai and Hyderabad generic producers. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical procurement managers, coating formulators, citric acid fermentation plant managers, and regulatory affairs specialists, then refined through secondary validation. Bottom-up triangulation combined interview intelligence with customs trade data, SEC 10-K chemical segment disclosures, ECHA authorization list documentation, and national pharmacopeial monograph updates. Top-down cross-checks anchored market sizing against regional citric acid production statistics and downstream esterification capacity announcements.
Variance decomposition across the projection horizon isolates volume drivers by grade tier, end-use industry, and regional regulatory cluster. CAGRs were synthesized from segment-level growth trajectories and input cost elasticity assumptions. Modeled inputs include fermentation capacity expansion timelines in Shandong and Jiangsu, REACH authorization progression for orthophthalates, and FDA inspection intensity for generic drug supply chain documentation.
The analysis sits within stated boundaries; outcomes outside sustained regulatory pressure on phthalate alternatives or fermentation feedstock cost stability would require recalibration. Forecasts reflect documented assumptions regarding ECHA evaluation timelines, CDSCO incentive scheme continuity, and bioethanol pricing correlation with corn harvest cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
US Esters Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Petrolatum Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Global White Oil Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Paraffin Market