
 Isodecyl Neopentanoate Market | 2026-2036
Isodecyl Neopentanoate Market Size, Share, and Industry Trends Forecast 2026-2036
Isodecyl Neopentanoate Market Analytics
A capital-intensity divergence between integrated petrochemical producers and specialty ester houses is reorganizing competitive tiers in isodecyl neopentanoate supply. Evonik Industries leverages backward integration into neopentanoic acid feedstock to sustain margin control across European personal care channels. Dow Chemical anchors volume scale through Gulf Coast oleochemical infrastructure, while Croda International differentiates via pharmaceutical-grade certification and clean beauty positioning.
Isodecyl neopentanoate is a branched-chain ester synthesized from neopentanoic acid and isodecanol, characterized by low viscosity, oxidative stability, and a silky skin feel at typical use concentrations of 1–10 percent. The compound functions primarily as an emollient and solvent in cosmetic formulations, reducing greasiness while enhancing spreadability in sun care and color cosmetics. Cosmetics applications lead volume absorption due to formulation flexibility across premium and mass skin care lines, whereas pharmaceutical-grade demand extends fastest as topical drug delivery systems adopt ester-based penetration enhancers. Emollient functionality commands the deepest margin pool among application segments, reflecting qualification burdens and performance premiums in dermocosmetic channels.
REACH registration through ECHA governs European market access, while FDA cosmetic safety substantiation rules under the Modernization of Cosmetics Regulation Act tighten U.S. ingredient documentation requirements. China's NMPA and GB standards for cosmetic raw materials add a third compliance layer for suppliers targeting Asia-Pacific personal care manufacturers. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH registration deadlines and FDA MoCRA implementation timelines are compressing supplier qualification windows, forcing formulators to consolidate raw material sourcing around pre-certified ester houses with existing dossiers.
Growth Catalysts
- Clean beauty certification expansion:Sephora's Clean at Sephora and Ulta's Conscious Beauty programs now mandate silicone-free emollient alternatives, accelerating isodecyl neopentanoate substitution in prestige skin care formulations.
- Topical drug delivery adoption:Transdermal patch manufacturers are integrating ester-based penetration enhancers into nicotine and hormone replacement therapies, expanding pharmaceutical-grade demand beyond traditional cosmetic channels.
- China NMPA streamlined registration:The 2021 cosmetic supervision regulation amendments reduced raw material filing timelines for imported esters, lowering market entry barriers for European and US suppliers.
Market Restraints
- Neopentanoic acid supply concentration:Over 70 percent of global feedstock originates from integrated German and US Gulf Coast petrochemical complexes, exposing specialty ester producers to force majeure disruptions at single-source crackers.
- Palm oil derivative cost volatility:Isodecanol feedstock pricing tracks Malaysian and Indonesian oleochemical futures, creating margin compression for non-backward-integrated formulators during El Niño-driven supply shocks.
- Silicone emollient residual preference:Dimethicone and cyclopentasiloxane maintain incumbent status in mass-market sun care due to lower per-kilogram cost and established sensory benchmarking protocols.
Strategic Opportunities
- India personal care manufacturing expansion:The country's PLI scheme for specialty chemicals is attracting contract manufacturers serving Unilever and L'Oréal regional production, creating localized ester demand without import duty exposure.
- Blue biotechnology feedstock pathways:Algae-derived fatty alcohols combined with bio-based neopentanoic acid from lignocellulosic sources enable carbon-negative emollient positioning for premium clean beauty lines.
- South Korea K-beauty export engine:Seoul-based formulators are specifying high-purity isodecyl neopentanoate for cushion compact and essence formulations distributed across Southeast Asian duty-free channels.
Industry Challenges
- ECHA dossier maintenance burden:Lead registrants face escalating costs for substance evaluation updates and exposure scenario revisions under REACH Article 22, diverting technical resources from product development.
- Analytical method standardization gaps:Absence of harmonized ISO protocols for branched-chain ester purity testing forces suppliers to maintain multiple QC workflows for USP, EP, and JP compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isodecyl Neopentanoate Market |
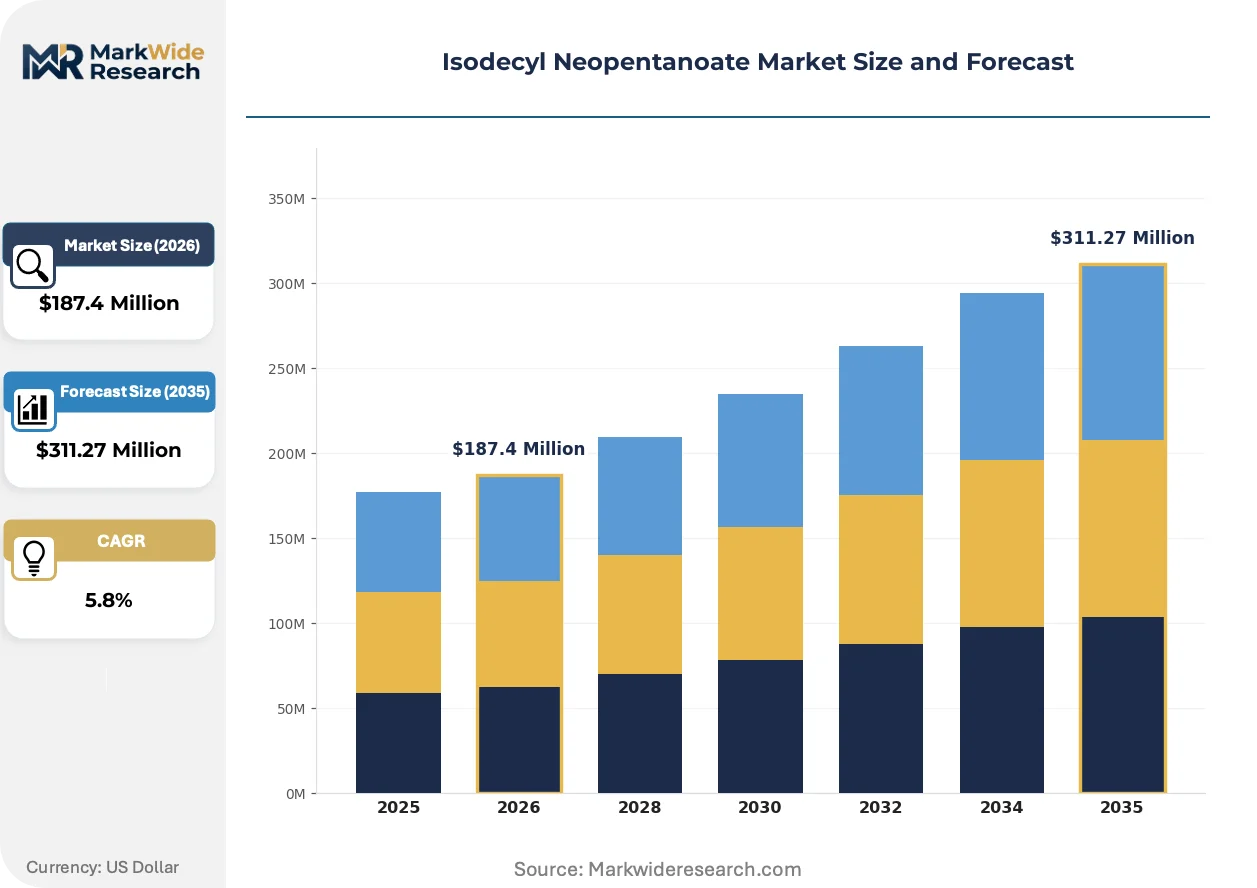
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Personal Care, Pharmaceuticals, Food Additives End Use Industry: Cosmetic Manufacturers, Food Production, Healthcare, Beverage Industry Application: Emollient, Solvent, Flavoring Agent, Fragrance Packaging Type: Bottles, Drums, Jars, Pouches |
| Companies Covered | A&A Fratelli Parodi, Evonik Industries, Lubrizol, Dow Chemical, Croda International, Ashland, BASF, Eastman Chemical, Stearinerie Dubois, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isodecyl Neopentanoate Market Evolving Landscape
Biotechnology-enabled feedstock alternatives and digital formulation platforms are disrupting traditional ester procurement relationships, while regulatory transparency mandates accelerate ingredient disclosure requirements across major personal care markets.
Bio-based isodecyl neopentanoate synthesized from fermented feedstocks is bifurcating the emollient supply base into petroleum-derived and renewable-certified tiers. L'Oréal and Estée Lauder procurement teams now require mass balance certification for new raw material qualifications. This technology is bifurcating supplier relationships, as specialty ester houses without bio-pathway partnerships lose access to premium dermocosmetic contracts.
REACH Article 33 SCIP database obligations and the EU Green Deal's chemical sustainability targets are tightening substance traceability requirements. ECHA's 2024 update to the guidance on requirements for substances in articles extends disclosure obligations to cosmetic packaging components. European contract manufacturers are now demanding full supply chain substance mapping from isodecyl neopentanoate suppliers, with German and French formulators leading compliance investments.
Direct-to-consumer skin care brands are compressing formulation development cycles from 18 months to 6 months through AI-powered ingredient screening platforms. These tools rank emollients by sensory performance scores derived from consumer panel data, bypassing traditional supplier-led recommendation protocols. This pattern is most visible in Los Angeles and Seoul, where venture-backed brands iterate formulations based on real-time e-commerce review sentiment analysis.
Isodecyl Neopentanoate Market Segmentation
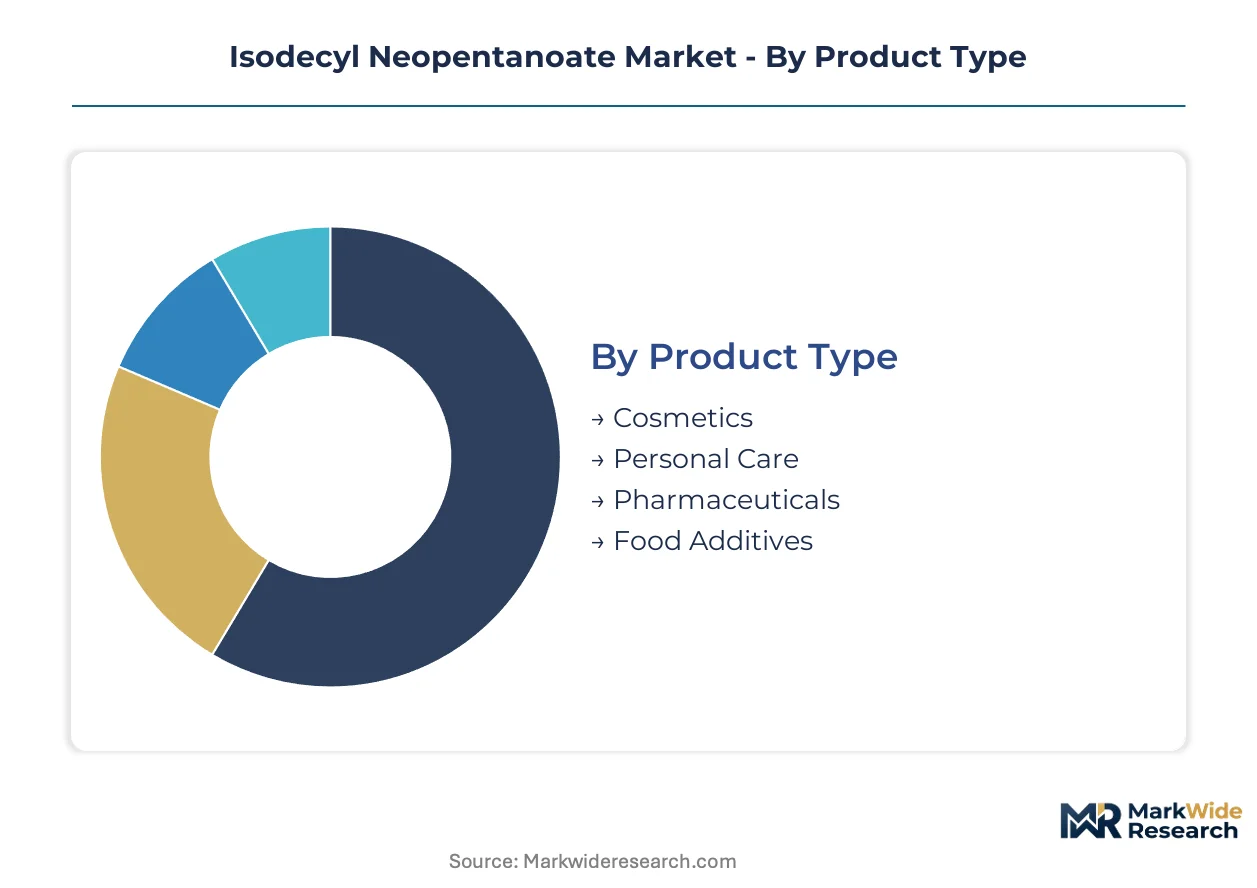
Segmentation in isodecyl neopentanoate reveals how formulation requirements diverge across cosmetic, pharmaceutical, and food-grade channels. Margin capture depends on matching purity grades to end-use qualification burdens while optimizing packaging formats for supply chain efficiency.
Product Type:
Cosmetics-grade formulations command the deepest margin pools due to sensory performance premiums and clean beauty certification requirements.
- Cosmetics:High-purity ester grades deliver silky skin feel and oxidative stability in color cosmetics and sun care. Demand concentrates in premium dermocosmetic lines across Germany and France where silicone-free formulations drive substitution.
- Pharmaceuticals:USP-grade material serves as penetration enhancer in transdermal drug delivery systems. Regulatory dossier requirements in FDA and EMA jurisdictions create qualification barriers that sustain price premiums for certified suppliers.
- Personal Care:Standard cosmetic-grade ester for mass-market lotions and hair care formulations with moderate purity thresholds.
- Food Additives:Limited application as flavor carrier in confectionery and beverage processing with strict FSSAI and FDA food contact compliance.
The dominant share belongs to Cosmetics, while Pharmaceuticals is closing the gap fastest.
End Use Industry:
Volume absorption patterns track manufacturing cluster density and import duty exposure across regional production hubs.
- Cosmetic Manufacturers:Contract manufacturers in China's Guangdong province and India's Maharashtra state drive bulk procurement for multinational brand owners. India's PLI scheme for specialty chemicals is attracting regional production from Unilever and L'Oréal supply chains.
- Healthcare:Transdermal patch producers specify pharmaceutical-grade ester for nicotine and hormone replacement therapies. FDA MoCRA documentation requirements and EMA quality standards impose dual compliance burdens on suppliers.
- Food Production:Flavor houses in Switzerland and the Netherlands utilize food-grade ester as solvent for natural extract formulations.
- Beverage Industry:Limited specialty application in alcoholic and non-alcoholic beverage flavor systems with regional regulatory variance.
Cosmetic Manufacturers absorb the largest volume, though Healthcare is expanding most quickly as drug delivery applications multiply.
Application:
Functional performance requirements determine specification tiers and pricing stratification across emollient and non-emollient uses.
- Emollient:Primary function in skin care formulations delivering spreadability without greasiness. Sephora's Clean at Sephora and Ulta's Conscious Beauty programs mandate silicone-free alternatives, accelerating specification in prestige channels.
- Solvent:Carrier function in fragrance compounding and active ingredient dissolution. Evolving EPA and ECHA volatility regulations are reshaping permissible solvent profiles in consumer products.
- Fragrance:Fixative and diluent role in fine fragrance and functional perfumery with moderate volume contribution.
- Flavoring Agent:Minor application in food-grade flavor systems with stringent purity and organoleptic requirements.
Emollient functionality captures the dominant value share, while Solvent applications are gaining specification momentum fastest.
Packaging Type:
Logistics economics and contamination risk shape format selection across bulk industrial and precision dispensing channels.
- Drums:Standard 200-liter steel and HDPE containers serve contract manufacturers and toll compounders with high-throughput requirements. Dow Chemical and integrated petrochemical producers optimize Gulf Coast distribution through drum consolidation.
- Bottles:Laboratory and pilot-scale quantities for formulation development and sampling programs. Direct-to-consumer skin care brands in Los Angeles and Seoul compress development cycles, increasing small-volume procurement frequency.
- Jars:Wide-mouth containers for viscous or solid-phase ester derivatives in specialty cosmetic applications.
- Pouches:Flexible format for single-use or travel-size product lines with sustainability positioning potential.
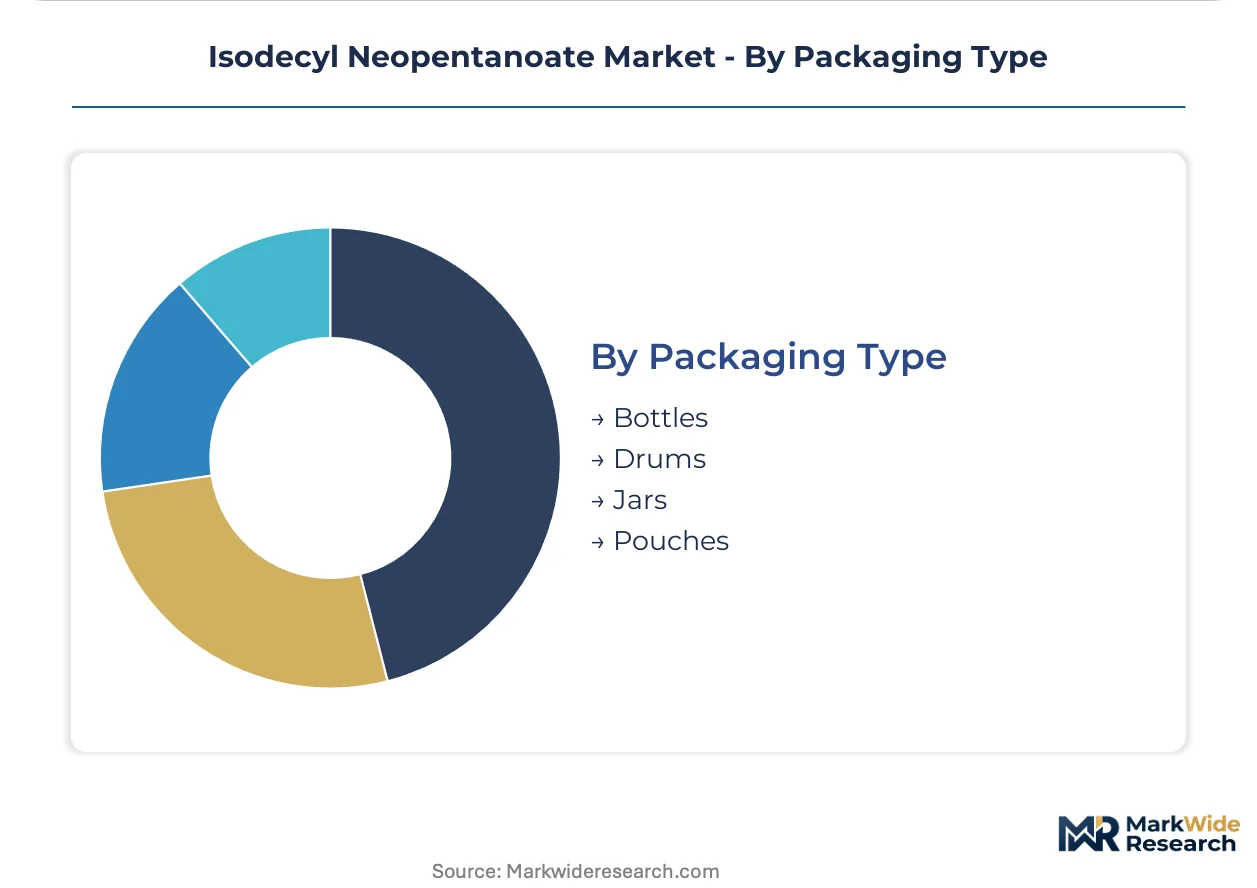
Drums maintain the dominant procurement share, though Bottles are climbing fastest on R&D sampling demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power tilts toward German specialty ester houses commanding REACH-certified premiums, while Chinese contract manufacturers extract volume discounts through Guangdong cluster consolidation. This asymmetry reshapes procurement negotiations across cosmetic supply chains.
United States
FDA MoCRA implementation tightens cosmetic ingredient documentation, compressing supplier qualification timelines. Gulf Coast oleochemical infrastructure anchors Dow Chemical's volume scale, while Los Angeles direct-to-consumer brands compress formulation cycles through AI-powered ingredient screening.
Germany
ECHA REACH dossier maintenance burdens concentrate on lead registrants, diverting technical resources from product development. Evonik Industries leverages backward integration into neopentanoic acid feedstock to sustain margin control across European personal care channels.
China
NMPA streamlined registration since 2021 reduced raw material filing timelines for imported esters. Guangdong province contract manufacturers drive bulk procurement for multinational brand owners, while Shanghai-based formulators specify high-purity grades for premium skin care exports.
India
PLI scheme for specialty chemicals attracts contract manufacturers serving Unilever and L'Oréal regional production. Maharashtra state clusters create localized ester demand without import duty exposure, though BIS cosmetic raw material standards add compliance layers.
South Korea
MFDS cosmetic safety standards align with K-beauty export specifications across Southeast Asian duty-free channels. Seoul-based formulators specify high-purity isodecyl neopentanoate for cushion compact and essence formulations distributed through regional retail networks.
Isodecyl Neopentanoate Market Competitive Landscape
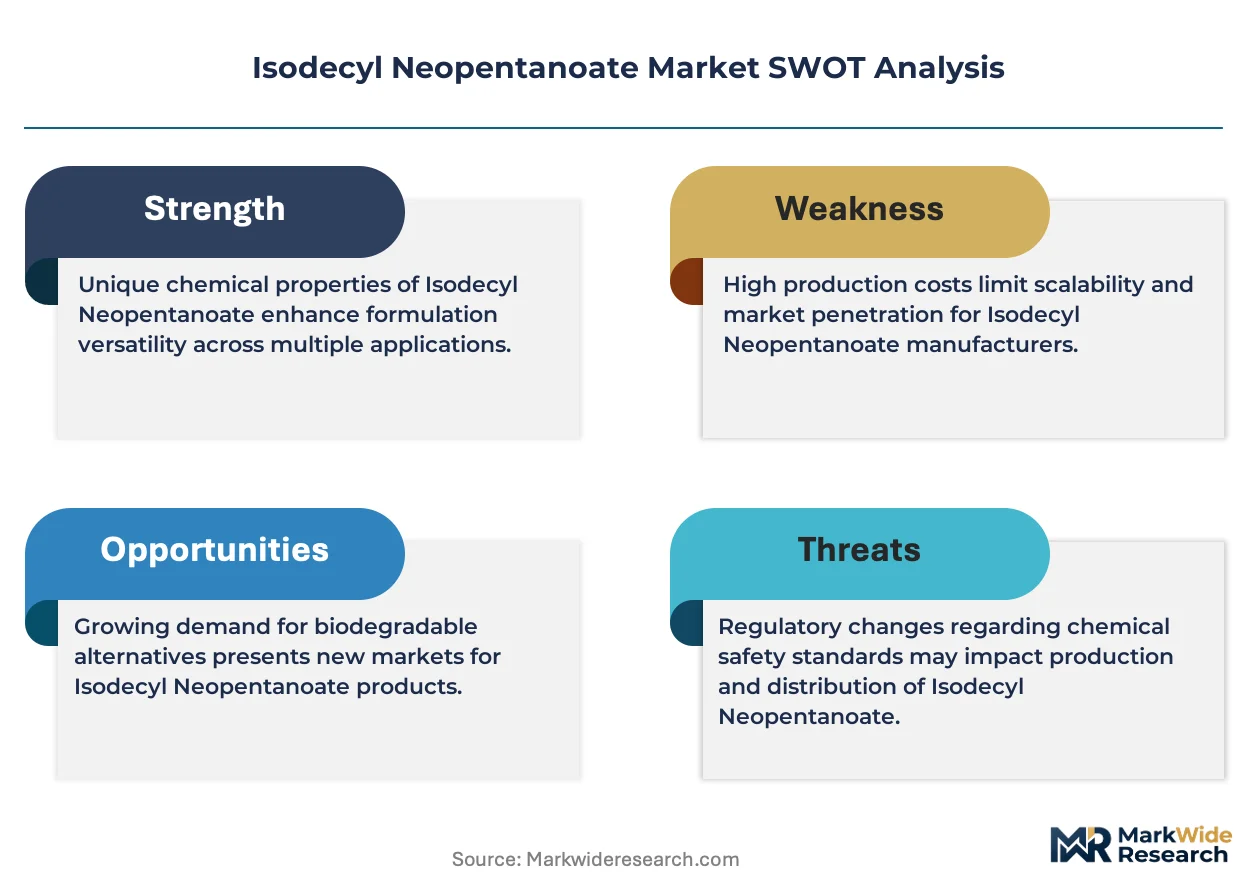
Concentration sits with integrated petrochemical producers and specialty ester houses reorganizing competitive tiers through capital-intensity divergence. The vendor base spans multinational chemical conglomerates with captive feedstock supply and regional ester specialists focused on pharmaceutical-grade certification. Three archetypes dominate: backward-integrated petrochemical majors, clean beauty-positioned specialty houses, and pharmaceutical-grade certification specialists. Competitive moves center on M&A for feedstock security and capacity expansion in India and China manufacturing clusters.
Among German chemical conglomerates, Evonik Industries and BASF exemplify the backward-integrated archetype controlling neopentanoic acid supply chains. Dow Chemical represents the Gulf Coast volume-scale position, while Croda International occupies the pharmaceutical-grade certification tier. These three anchors illustrate how feedstock control, geographic production placement, and regulatory dossier depth stratify competitive positioning across cosmetic and pharmaceutical channels.
| Leading Market Players |
|---|
| A&A Fratelli Parodi |
| Evonik Industries |
| Lubrizol |
| Dow Chemical |
| Croda International |
| Ashland |
| BASF |
| Eastman Chemical |
| Stearinerie Dubois |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Guangdong contract manufacturers and German specialty ester houses lock in REACH-certified supply access while anchoring price visibility across volatile neopentanoic acid feedstock cycles. These arrangements concentrate procurement power among backward-integrated suppliers with captive acid production, compressing spot-market liquidity for non-integrated formulators.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade material commands a substantial premium over standard cosmetic-grade deliveries, with USP certification and dual FDA-EMA dossier maintenance driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and regulatory burden, while volume-scale discounts anchor negotiations for drum-quantity procurement by multinational cosmetic manufacturers. Cost compression in standard cosmetic grades is intensifying because Malaysian oleochemical futures volatility transmits directly into isodecanol feedstock costs. Mass-market personal care brands exhibit the highest price sensitivity, whereas dermocosmetic formulators in France and Germany prioritize sensory performance over per-kilogram economics.
Supply Chain Analysis
Inventory buffers at German and US Gulf Coast petrochemical complexes typically extend lead times for specialty ester houses without backward integration into neopentanoic acid. Supply concentrates in Germany, the United States, and China, with integrated crackers in Ludwigshafen and Freeport anchoring global feedstock availability. The chain draws from neopentanoic acid, isodecanol, and catalytic esterification capacity as core inputs. Single-source vulnerability at German crackers exposes specialty producers to force majeure disruptions. Distribution runs through drum consolidation to Guangdong and Maharashtra manufacturing clusters, with laboratory-scale bottle shipments serving Seoul and Los Angeles formulation development centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isodecyl neopentanoate incumbents face a substitution defense against silicone emollient residual preference in mass-market sun care, where dimethicone maintains incumbent status through lower per-kilogram cost and established sensory benchmarking protocols.
For Market Incumbents: Shield market position by deepening backward integration into neopentanoic acid feedstock to neutralize supply concentration risk at German and US Gulf Coast crackers. Prioritize pharmaceutical-grade certification investment to capture transdermal drug delivery expansion, while accelerating clean beauty positioning through bio-based pathway partnerships to defend against silicone substitution in prestige channels.
For New Entrants and Emerging Players: Differentiate on algae-derived fatty alcohol feedstocks combined with lignocellulosic neopentanoic acid to enable carbon-negative emollient positioning for premium clean beauty lines. Target India's Maharashtra state contract manufacturing clusters, where PLI scheme incentives attract Unilever and L'Oréal regional production without import duty exposure. Lead with mass balance certification as the go-to-market wedge for European dermocosmetic procurement teams.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated specialists with REACH dossier depth and captive acid supply. Long-term viability hinges on feedstock security rather than formulation innovation, given the commodity-like behavior of standard cosmetic grades. Monitor ECHA substance evaluation updates under REACH Article 22 as the signal for qualification cost inflection and margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Evonik Industries controls neopentanoic acid supply chains to sustain margin control across European personal care channels. |
| Capacity Expansion | Dow Chemical leverages Gulf Coast oleochemical infrastructure to anchor volume scale for drum consolidation distribution. |
| Green Manufacturing Transition | Bio-based isodecyl neopentanoate from fermented feedstocks bifurcates supply into petroleum-derived and renewable-certified tiers. |
| Long-term Supply Agreement | Guangdong contract manufacturers lock in REACH-certified supply access through offtake contracts with German ester houses. |
| Joint Venture | India's PLI scheme attracts regional production partnerships serving Unilever and L'Oréal supply chains in Maharashtra state. |
Research Methodology
A standing panel of cosmetic formulation chemists, pharmaceutical procurement managers, specialty ester plant operators, and ECHA regulatory consultants provided ongoing calibration across primary data collection. This study combines structured interviews with these stakeholders against secondary validation from customs and trade data, Cefic sector reports, SEC 10-K filings, and NMPA registration databases. Bottom-up triangulation across regional manufacturing clusters and top-down reconciliation against oleochemical production statistics anchored volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon, with modeled segmentation spanning grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating clean beauty certification expansion rates and pharmaceutical-grade qualification timelines. Forecast inputs included transdermal patch manufacturer adoption curves and AI-powered formulation platform penetration in direct-to-consumer skin care development cycles.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance investment and stable Malaysian oleochemical supply conditions would require recalibration. Forecasts reflect assumptions about regulatory divergence timelines and feedstock concentration persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Tallow Amine Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Glycerine Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
US Esters Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Lipid Rich Powder Market