
 Tall Oil Rosin Market | 2026-2036
Tall Oil Rosin Market Size, Share, and Industry Trends Forecast 2026-2036
Tall Oil Rosin Market Outlook
Market Context
Petroleum-derived hydrocarbon resins is decoupling from adhesive formulations as tall oil rosin gains cost-competitive parity with improved functional performance. Kraton Corporation leverages its integrated pine chemicals platform to secure captive feedstock across North American and European operations. Georgia-Pacific Chemicals anchors its position through direct access to kraft pulping byproduct streams at scale. Ingevity Corporation differentiates via specialty hydrogenated rosin grades targeting high-performance pressure-sensitive adhesive applications.
Technical Definition and Segment Structure
Tall oil rosin is a natural resin extracted from crude tall oil, a byproduct of kraft wood pulping, comprising primarily abietic acid and pimaric acid isomers with softening points ranging from 75°C to 85°C; it functions as a tackifier, binder, and film-forming agent across coatings, adhesives, and printing ink formulations. Glycerol esters and hydrogenated rosin variants command premium positioning in food-contact and UV-resistant coatings where oxidation stability determines specification compliance. Modified rosin grades represent the fastest-expanding product category as esterification and dimerization chemistries unlock compatibility with acrylic and SBC hot-melt adhesive platforms. The end-user split favors adhesives and coatings segments where reformulation away from synthetic hydrocarbons is most advanced, while personal care applications remain nascent but specification-intensive.
Regulatory Framework and Outlook
REACH registration requirements and the EU F-Gas Regulation indirectly elevate bio-based tackifiers by constraining petrochemical alternative pathways, while FDA food-contact substance notifications govern rosin derivative migration limits in packaging adhesives sold into the United States. The U.S. EPA Toxic Substances Control Act inventory status and BIS certification mandates for imported resin derivatives in India further fragment compliance obligations across destination markets. Stakeholders must monitor feedstock availability from declining North American kraft pulp capacity and evaluate backward integration into crude tall oil fractionation to secure margin capture.
Market Dynamics
EU Green Deal mandates and REACH registration requirements are forcing rapid substitution of petroleum-derived tackifiers with bio-based alternatives, while kraft pulp mill closures in North America tighten crude tall oil feedstock availability.
Growth Catalysts
- REACH compliance acceleration:ECHA registration deadlines for synthetic hydrocarbon resins elevate tall oil rosin cost-competitiveness in adhesive formulations across EU member states.
- E-commerce logistics expansion:Pressure-sensitive adhesive consumption for corrugated packaging and shipping labels pulls disproportionate rosin offtake in automated fulfillment centers.
- Hydrogenation technology maturation:Improved catalytic hydrogenation processes yield oxidation-stable rosin grades qualifying for UV-resistant coating specifications.
Market Restraints
- Crude tall oil supply concentration:Integrated pulp-and-paper complexes in Finland, Sweden, and the southeastern United States control 70% of fractionation capacity.
- Petroleum resin price volatility:Naphtha feedstock cost swings create intermittent price inversions that disrupt bio-based substitution economics.
- Color instability limitations:Unmodified rosin grades fail specification requirements for water-white adhesive applications in optical film bonding.
Strategic Opportunities
- India BIS certification pathway:Mandatory BIS marking for imported tackifiers creates first-mover advantage for compliant tall oil derivative suppliers.
- Personal care emulsification:Hydrogenated rosin esters penetrate cosmetic formulations as silicone alternatives in hair styling and skin barrier applications.
- Hot-melt adhesive platform convergence:Esterified rosin grades unlock compatibility with styrene block copolymer systems in automotive interior assembly.
Industry Challenges
- Fractionation expertise scarcity:Specialized crude tall oil distillation knowledge concentrates among retiring engineers at legacy pulp chemical divisions.
- Food-contact notification timelines:FDA FCN submissions for novel rosin derivatives require 18-24 month review cycles that delay commercialization.
- Legacy adhesive formulation inertia:Major tape and label manufacturers maintain decade-old hydrocarbon resin qualifications that resist reformulation testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tall Oil Rosin Market |
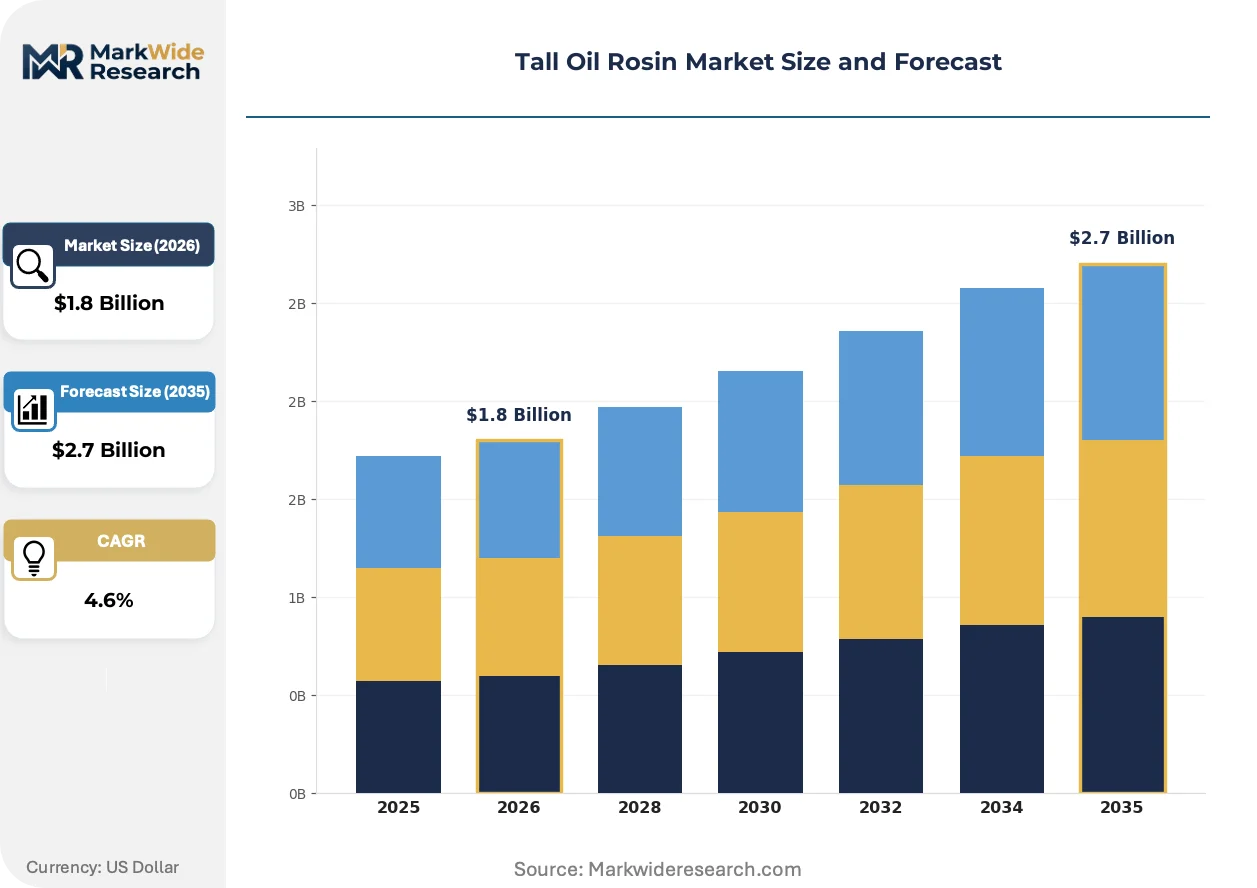
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerol Esters, Soft Rosin, Modified Rosin, Hydrogenated Rosin End User: Coatings, Adhesives, Inks, Personal Care Application: Lacquers, Pressure-Sensitive Adhesives, Paints, Sealants Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | DRT- Les Dérivés Résiniques et Terpéniques, Florachem Corp., Kraton Corporation, Harima Chemicals Group Inc., Georgia-Pacific Chemicals, Ingevity Corporation, Eastman Chemical Company, Lascaray SA, Arakawa Chemical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tall Oil Rosin Market Strategic Shifts
Advanced esterification chemistries and precision hydrogenation are expanding rosin compatibility beyond traditional applications into high-specification coating and adhesive platforms previously reserved for synthetic tackifiers.
Modified rosin esters with tailored acid numbers and softening points are integrating into acrylic hot-melt adhesive systems for automotive interior bonding. Tier-1 suppliers in Germany and Japan specify these grades for dashboard lamination where VOC emissions testing is mandatory. The technology is integrating rosin derivatives into supply chains that previously excluded natural resins on performance grounds.
EU F-Gas Regulation constraints on fluorinated polymer production indirectly elevate bio-based tackifier specifications in refrigerant-resistant gasket applications. REACH SVHC candidate list expansions for petrochemical derivatives accelerate reformulation timelines. Pressure-sensitive adhesive compounders in the Netherlands and Belgium now prioritize tall oil rosin for cold-chain packaging labels.
Brand-owner sustainability scorecards now mandate bio-based content verification through third-party certification. Major consumer goods companies in France and the United Kingdom require mass-balance documentation for packaging adhesives. Procurement teams are consolidating supplier bases to favor vertically integrated rosin producers with captive pulp mill feedstock and chain-of-custody traceability systems.
Tall Oil Rosin Market Segmentation
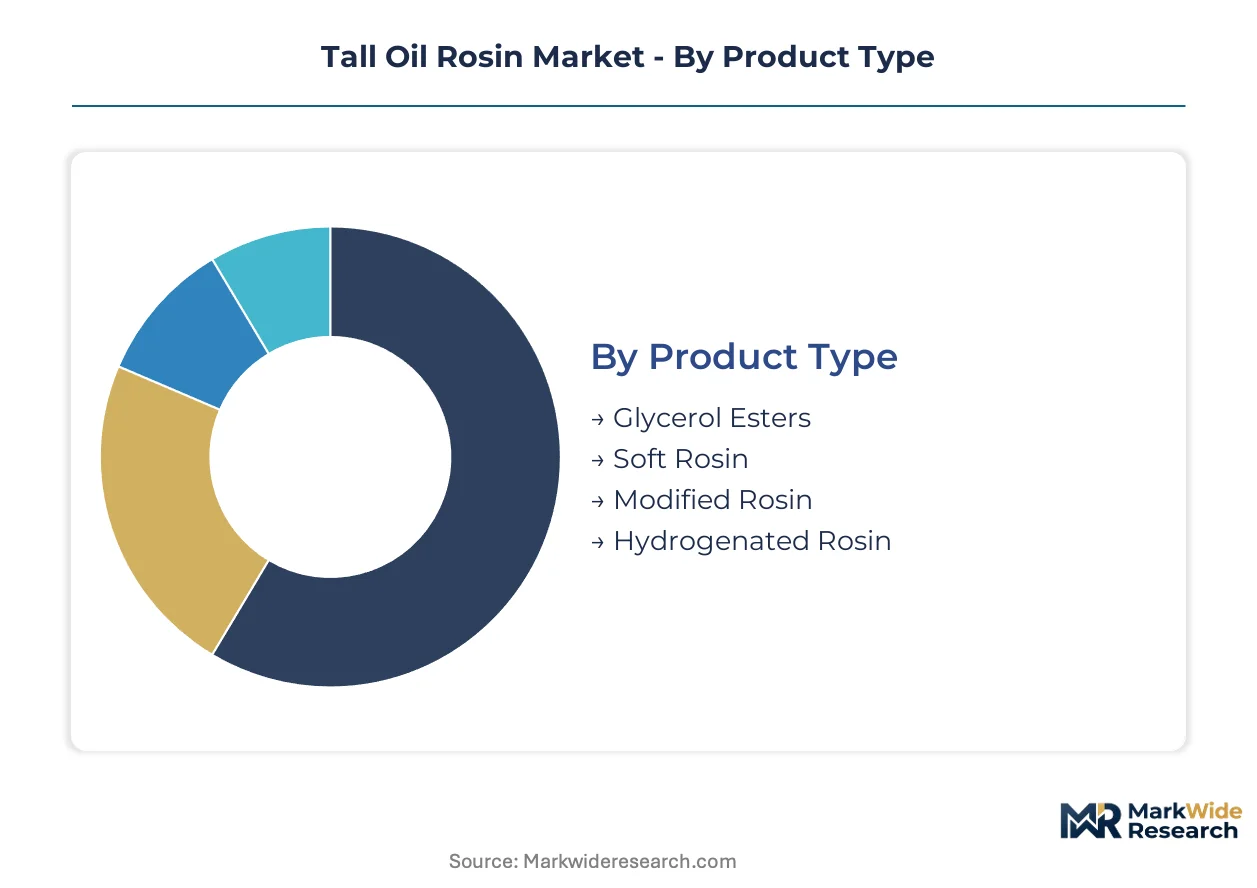
Tall oil rosin specifications vary dramatically across end-use requirements, with hydrogenation levels and esterification chemistry determining compatibility with high-performance adhesive platforms. Segmentation reveals where bio-based substitution economics favor reformulation investments versus legacy hydrocarbon resin retention.
Product Type:
Upgrade cycles in adhesive formulation are pulling rosin demand toward modified and hydrogenated grades that match synthetic tackifier performance specifications.
- Hydrogenated Rosin:Catalytic hydrogenation saturates abietic acid structures to eliminate conjugated double bonds, yielding oxidation-stable grades with Gardner color specifications below 4. German automotive interior suppliers specify these derivatives for dashboard lamination adhesives where UV exposure and VOC emissions testing is mandatory. Demand concentrates in pressure-sensitive adhesive applications requiring water-white clarity.
- Modified Rosin:Esterification and dimerization chemistries tailor acid numbers and softening points for compatibility with styrene block copolymer hot-melt systems. E-commerce logistics expansion in automated fulfillment centers across the southeastern United States and the Netherlands is accelerating specification of these grades for shipping label adhesives. Reformulation away from petroleum-derived hydrocarbon resins is most advanced in this segment.
- Glycerol Esters:Partial esterification with glycerol produces tackifiers for food-contact packaging adhesives governed by FDA migration limits.
- Soft Rosin:Unmodified grades with lower softening points serve cost-sensitive printing ink formulations where color stability requirements are relaxed.
Volume placements concentrate in Modified Rosin; the faster expansion belongs to Hydrogenated Rosin.
End User:
Cost tier differentiation separates specification-intensive segments from commodity applications, with compliance burdens driving margin stratification.
- Adhesives:Pressure-sensitive, hot-melt, and sealant formulations consume the majority of tall oil rosin offtake. E-commerce corrugated packaging demand in Germany, Finland, and the southeastern United States is pulling disproportionate volume into automated tape and label production lines. REACH registration deadlines for synthetic hydrocarbon alternatives have elevated bio-based tackifier cost-competitiveness across EU member states.
- Coatings:Industrial and protective coating applications specify hydrogenated grades for UV resistance and gloss retention. Automotive refinish coatings in Japan and Germany require oxidation-stable derivatives that maintain color integrity under accelerated weathering protocols. EU F-Gas Regulation constraints on fluorinated polymers are indirectly expanding bio-based tackifier specifications in refrigerant-resistant gasket coatings.
- Inks:Publication and packaging gravure inks utilize soft rosin grades as binders and dispersing agents.
- Personal Care:Hydrogenated rosin esters function as silicone alternatives in hair styling and skin barrier formulations, with specification intensity exceeding volume scale.
Adhesives commands the dominant placement; Coatings is climbing the fastest on automotive and industrial specification upgrades.
Application:
Customer type fragmentation separates high-volume industrial compounders from specialty formulators with divergent technical service requirements.
- Pressure-Sensitive Adhesives:Tape, label, and graphic film applications require precise tack and peel adhesion control. Modified rosin esters with tailored softening points are integrating into acrylic emulsion systems for cold-chain packaging labels in the Netherlands and Belgium. Brand-owner sustainability scorecards now mandate bio-based content verification through third-party mass-balance certification.
- Sealants:Construction and automotive gasket applications favor hydrogenated grades for thermal stability and low VOC emissions.
- Lacquers:Wood finishing and metal coating formulations utilize glycerol ester derivatives for film-forming and gloss properties.
- Paints:Industrial maintenance and marine coatings specify rosin-modified phenolic resins for corrosion resistance.
Pressure-Sensitive Adhesives holds the volume concentration; Sealants shows the steepest expansion trajectory on regulatory compliance advantages.
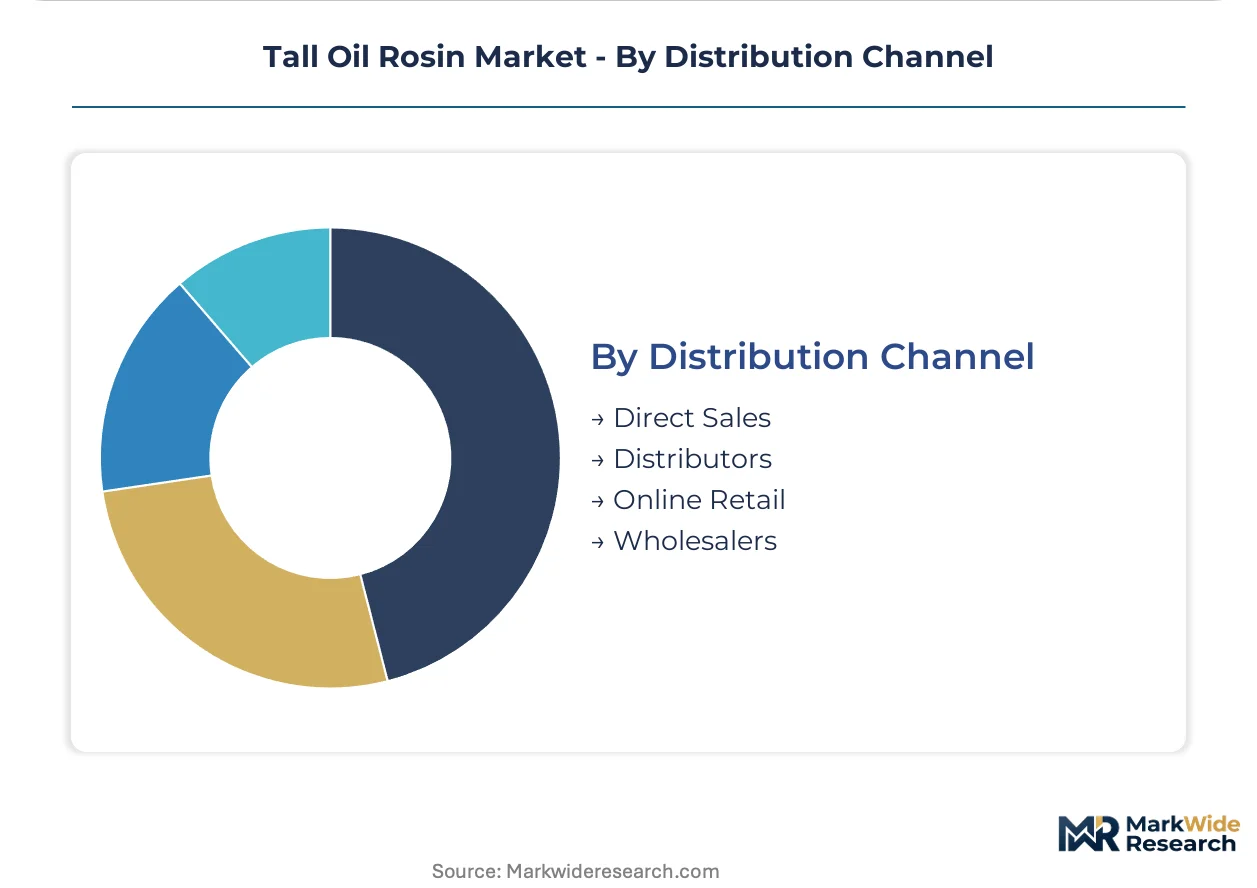
Distribution Channel:
Supply concentration in integrated pulp-and-paper complexes shapes channel economics, with captive production favoring direct relationships over intermediated sales.
- Direct Sales:Major adhesive compounders and coating manufacturers procure through long-term offtake agreements with fractionators possessing captive kraft pulp feedstock. Kraton Corporation and Georgia-Pacific Chemicals leverage integrated pine chemicals platforms to secure direct supply relationships across North American and European operations. Chain-of-custody traceability requirements for sustainability certification reinforce direct channel preference.
- Distributors:Regional chemical distributors serve mid-tier formulators requiring technical service support and smaller lot sizes.
- Wholesalers:Bulk resin traders aggregate volume for cost-sensitive printing ink and lower-specification coating applications.
- Online Retail:E-procurement platforms capture minor share for specialty grades in personal care and artisan coating segments.
Direct Sales dominates volume placement; Distributors is gaining share fastest on mid-tier formulator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tall oil rosin concentrates in pulp-and-paper corridors where integrated fractionation secures feedstock access. Germany, Finland, and the southeastern United States anchor consumption through adhesive compounders and coating manufacturers.
Germany
Automotive interior suppliers in Bavaria and Baden-Württemberg specify hydrogenated rosin grades for dashboard lamination adhesives subject to VOC emissions testing. REACH registration deadlines for synthetic hydrocarbon resins elevate bio-based tackifier cost-competitiveness. The Stuttgart industrial cluster drives disproportionate offtake for UV-resistant coating specifications.
Finland
Kraft pulp mill complexes around Kotka and Kemi control captive crude tall oil fractionation capacity serving Nordic adhesive manufacturers. EU Green Deal mandates accelerate substitution away from petroleum-derived resins in packaging applications. The Uusimaa region concentrates hydrogenated rosin production for cold-chain logistics labels.
United States
E-commerce fulfillment centers across Georgia and the Carolinas pull modified rosin esters into pressure-sensitive adhesives for corrugated packaging and shipping labels. EPA Toxic Substances Control Act inventory status governs rosin derivative commercialization timelines. The southeastern pulp-and-paper corridor secures backward integration advantages for domestic fractionators.
Japan
Automotive refinish coatings manufacturers in Aichi and Kanagawa prefectures require oxidation-stable rosin derivatives for accelerated weathering protocols. METI industrial standards influence specification adoption across Asia-Pacific coating supply chains. The Nagoya industrial zone concentrates technical rosin imports for high-performance adhesive platforms.
India
Packaging adhesive compounders in Maharashtra and Gujarat face mandatory BIS certification for imported tackifiers, creating compliance barriers for non-certified suppliers. Central government procurement preferences for bio-based materials indirectly elevate domestic rosin derivative demand. The Mumbai-Pune manufacturing belt drives testing and qualification investments.
Tall Oil Rosin Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp chemical divisions commanding direct sales relationships and independent fractionators serving distributor channels. Market structure tilts toward consolidation among players with captive kraft pulp feedstock, while specialty hydrogenation and esterification capabilities concentrate in a narrower tier. Three archetypes dominate: vertically integrated forest products conglomerates, pine chemicals specialists with fractionation expertise, and diversified chemical companies with rosin derivative portfolios. Competitive moves center on backward integration into crude tall oil distillation and strategic partnerships with adhesive compounders for co-development of modified grades.
Within the integrated forest products tier, Georgia-Pacific Chemicals exemplifies captive feedstock advantages through direct kraft pulping byproduct access. Kraton Corporation occupies a position spanning North American and European pine chemicals platforms. Ingevity Corporation anchors the specialty hydrogenation segment with differentiated rosin grades for pressure-sensitive adhesive applications.
| Leading Market Players |
|---|
| DRT- Les Dérivés Résiniques et Terpéniques |
| Florachem Corp. |
| Kraton Corporation |
| Harima Chemicals Group Inc. |
| Georgia-Pacific Chemicals |
| Ingevity Corporation |
| Eastman Chemical Company |
| Lascaray SA |
| Arakawa Chemical Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Major adhesive compounders in Germany and the southeastern United States concentrate procurement through long-term offtake agreements, locking in contract-based pricing that insulates integrated fractionators from spot volatility while squeezing distributor margins.
Pricing Analysis
Volume placements favor standard modified rosin grades traded on per-unit transactional terms, while hydrogenated derivatives command value-based premiums tied to FDA food-contact certification and automotive VOC compliance. Price differentiation hinges on oxidation stability ratings and chain-of-custody mass-balance documentation demanded by brand-owner sustainability scorecards. Cost compression in unmodified soft rosin is intensifying because Asian printing ink formulators prioritize specification relaxation over performance upgrades. Mid-tier distributors serving regional coating manufacturers exhibit highest price sensitivity; automotive Tier-1 suppliers in Stuttgart and Nagoya demonstrate lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
EU Green Deal domestic-content mandates and India's BIS certification requirements are reshaping sourcing patterns toward fractionators with verifiable pulp-mill provenance. Feedstock supply concentrates in Finland, Sweden, and the southeastern United States where integrated kraft complexes control crude tall oil fractionation. Downstream production draws from catalytic hydrogenation equipment, specialty esterification reactors, and food-contact-grade processing lines. Single-source vulnerability runs through the Kotka-Kemi corridor where two Finnish complexes handle disproportionate European hydrogenated rosin output. Distribution runs through direct sales channels for major compounders, with regional distributors capturing mid-tier formulator volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over crude tall oil fractionation to escape feedstock scarcity as North American kraft pulp capacity contracts.
For Market Incumbents: Hedge against feedstock concentration risk by securing long-term crude tall oil supply agreements with Scandinavian pulp complexes before rival bidders lock in capacity. Deepen backward integration into captive fractionation at southeastern US mill sites to defend margin position against emerging hydrogenation specialists. Prioritize R&D investment in oxidation-stable grades that qualify for automotive interior specifications where qualification timelines create switching costs. For New Entrants and Emerging Players: Hydrogenated rosin esters for personal care emulsification offer the most penetrable white-space target, as cosmetic formulators actively seek silicone alternatives with bio-based certification narratives. India's BIS-compliant import pathway presents a geographic entry point with first-mover advantages for compliant suppliers. Pursue co-development partnerships with mid-tier adhesive compounders in the Netherlands and Belgium seeking modified grades for cold-chain packaging labels. For Investors and Strategic Acquirers: The window for entry favors fractionation specialists with proven crude tall oil distillation expertise and existing relationships with Nordic pulp mills. Long-term viability rests on securing positions before feedstock scarcity drives valuation premiums for captive supply assets. Watch for inflection in automotive interior adhesive qualification cycles, as dashboard lamination specification wins signal durable revenue capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crude Tall Oil Fractionation | Captive feedstock access insulates margin from kraft pulp mill closure cycles in North America. |
| Hydrogenation Capacity Expansion | Oxidation-stable grades unlock automotive interior specifications governed by Stuttgart VOC testing protocols. |
| Long-term Supply Agreement with Pulp Complexes | Finnish and Swedish mill relationships secure preferential crude tall oil offtake amid tightening availability. |
| Food-Contact Certification Investment | FDA FCN submission capabilities accelerate commercialization timelines for packaging adhesive derivatives. |
| Joint Venture with Adhesive Compounders | Co-development of modified ester grades penetrates SBC hot-melt platforms in e-commerce logistics applications. |
Study Parameters
Multi-period observation of kraft pulp capacity utilization, crude tall oil pricing spreads, and adhesive formulation qualification timelines anchored the trend analysis, supplemented by interviews with fractionation plant managers, procurement leads at German automotive Tier-1 suppliers, distribution channel partners in the Benelux region, and technical R&D directors at hydrogenation specialists. Secondary validation drew from customs and trade data, SEC filings of pine chemicals specialists, Cefic sector reports, and FDA food-contact substance notification databases. Bottom-up volume modeling triangulated against top-down market sizing across product grades and end-use segments.
Segment-weighting approaches applied differential growth assumptions to hydrogenated versus modified versus unmodified rosin grades, with end-use splits across adhesives, coatings, inks, and personal care calibrated to REACH substitution timelines and automotive specification adoption curves. CAGRs were derived from elasticity-adjusted demand projections and feedstock availability constraints across the analysis window. Industry-specific forecast inputs included kraft pulp mill closure announcements and EU F-Gas Regulation implementation phases affecting refrigerant-resistant gasket coatings.
Several conditions sit outside the modeled scope, including potential breakthroughs in synthetic hydrocarbon resin bio-derivatization, abrupt pulp mill curtailments from energy cost spikes, and trade policy shifts affecting tall oil rosin tariff classifications. Forecasts reflect documented assumptions about fractionation capacity expansion schedules and adhesive compounder reformulation willingness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Stearic Acid Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Oleophilic Materials Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Global Emollient Esters Market