
 Global White Oil Market | 2026-2036
Global White Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global White Oil Market Analysis
Modular packaging formats across drum, bottle, and pail configurations is broadening procurement flexibility for buyers across cosmetics and pharmaceutical channels. ExxonMobil Corporation leverages its integrated refining footprint to secure feedstock consistency. Sonneborn LLC specializes in high-purity pharmaceutical and cosmetic grades. Sasol anchors supply reliability through its Fischer-Tropsch-derived base stock operations in South Africa.
Global white oil comprises highly refined, colorless, odorless mineral oils produced through severe hydrotreating or acid treatment of paraffinic or naphthenic base stocks, achieving viscosity ranges typically between 10 and 90 cSt at 40°C and sulfur content below 10 ppm. Its primary purpose spans food-grade lubricants, cosmetic emollients, pharmaceutical carriers, and industrial textile and plasticizer applications. Pharmaceutical-grade white oil commands premium positioning due to USP and EP compliance burdens, while technical-grade volumes dominate tonnage through bulk industrial offtake. Cosmetics applications are expanding fastest as formulators replace silicone alternatives in skin-care and hair-care products.
REACH registration requirements in Europe, FDA 21 CFR 172.878 and 178.3620(a) food-contact rules in the United States, and USP/NF monograph standards collectively shape product specifications, testing protocols, and market access conditions across major jurisdictions. India's BIS certification and China's GB standards add further compliance layers for import-dependent buyers. Stakeholders must track evolving pharmacopeial updates and regional purity benchmarks to sustain formulation approvals and avoid supply disqualification.
Market Dynamics
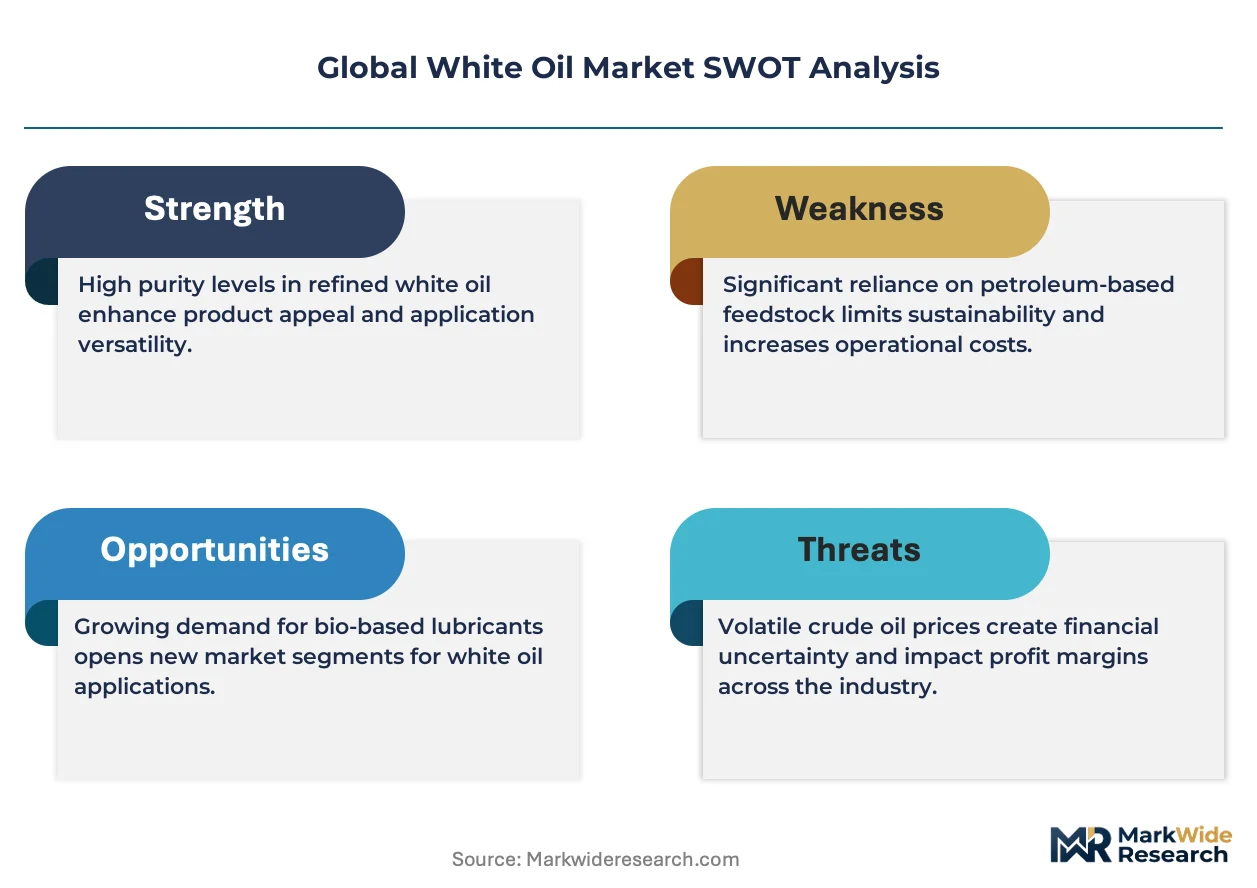
Pharmaceutical-grade purity requirements are compressing technical-grade margins while concentrating supply among hydrotreating-capable refiners. FDA 21 CFR and REACH registration burdens now filter market access, rewarding integrated producers with captive base stock supply.
Growth Catalysts
- REACH registration:European purity mandates are disqualifying non-compliant imports, tightening supply and elevating pricing power for registered producers serving cosmetic and pharmaceutical channels.
- Silicone displacement:Formulators in skin-care and hair-care segments are substituting white oil for cyclic silicones under regulatory pressure from ECHA restrictions on D4/D5/D6 compounds.
- India technical-grade demand:Textile and plasticizer manufacturers in Gujarat and Maharashtra are absorbing rising volumes of industrial white oil for fiber lubrication and PVC processing.
Market Restraints
- Base stock concentration:Paraffinic feedstock supply clusters in US Gulf Coast and Middle Eastern refining hubs, exposing buyers to regional disruption risk.
- Severe hydrotreating capex:Pharmaceutical-grade production requires high-pressure hydrogen units and sulfur guard beds that demand $50-100 million per train investment.
- Group III+ synthetic substitution:Polyalphaolefin and gas-to-liquids base stocks from Fischer-Tropsch operations are capturing high-viscosity lubricant applications.
Strategic Opportunities
- China GB standard alignment:Domestic cosmetic brands in Shanghai and Guangzhou are seeking import-grade white oil as local quality inconsistencies persist.
- Food-contact lubricants:FDA 21 CFR 178.3620(a) compliance is opening bakery and beverage processing equipment applications previously served by synthetic alternatives.
- Modular packaging:Drum-to-pail format flexibility is enabling direct-to-formulator distribution, bypassing traditional bulk terminal intermediaries.
Industry Challenges
- Pharmacopeial update lag:USP-NF and EP monograph revisions require 18-24 month revalidation cycles that freeze formulation approvals mid-process.
- Hydrogen supply security:Renewable hydrogen cost and availability constraints are complicating decarbonization pledges for hydrotreating-intensive producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global White Oil Market |
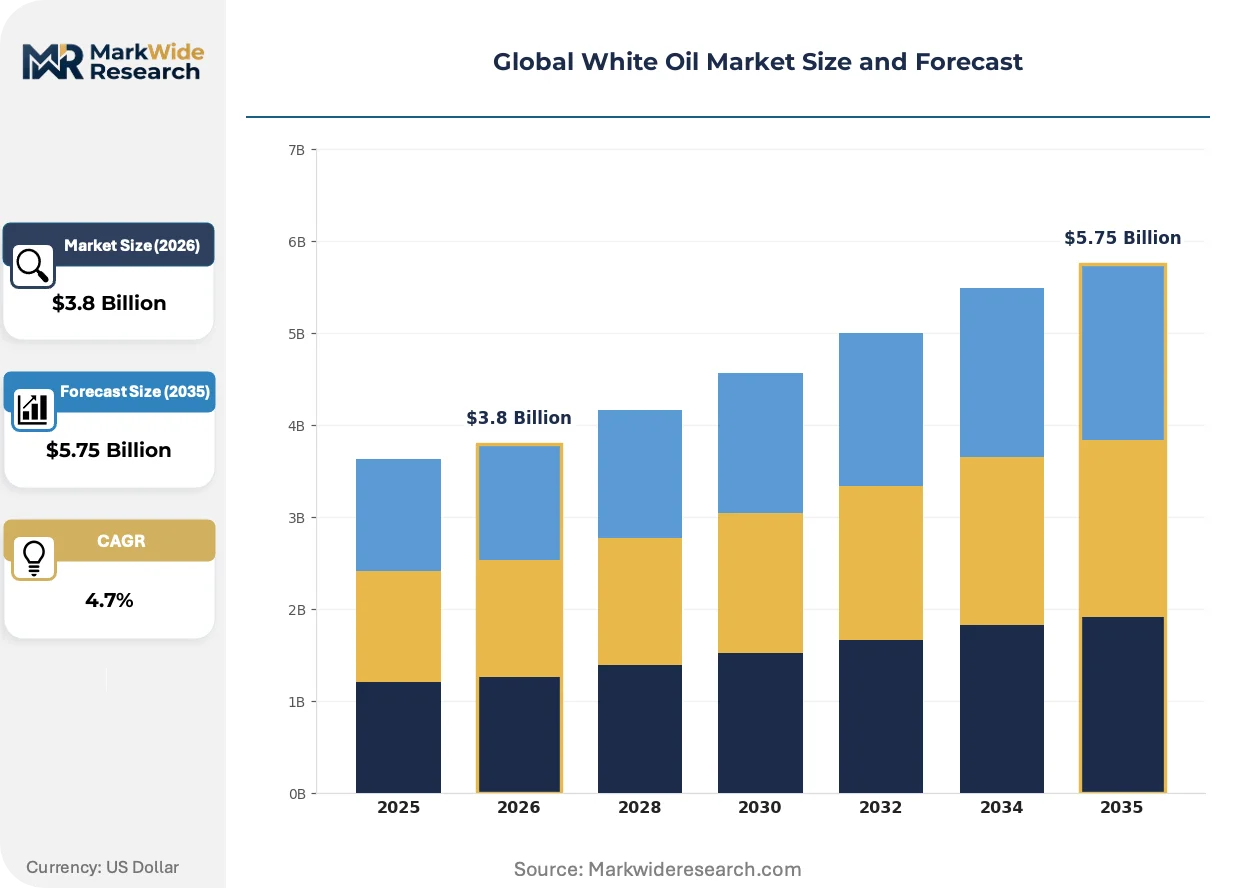
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Technical Grade, Cosmetic Grade Application: Cosmetics, Food Processing, Pharmaceuticals, Industrial Lubricants End User: Manufacturers, Distributors, Retailers, Healthcare Providers Packaging Type: Bulk Containers, Drum, Bottle, Pail |
| Companies Covered | ExxonMobil Corporation, Shell plc, China Petroleum & Chemical Corporation, Chevron Corporation, Calumet, Inc., Sasol, TotalEnergies, Petro-Canada Lubricants Inc., Sonneborn LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global White Oil Market Emerging Trajectories
Refining technology advances and regulatory chemistry restrictions are jointly redirecting formulation choices across personal care and pharmaceutical applications. Three developments are restructuring competitive positioning.
Gas-to-liquids Fischer-Tropsch base stocks are expanding into pharmaceutical-grade white oil production. Sasol's South African operations and Shell's Pearl facility in Qatar are supplying ultra-low-aromatic feedstocks that meet USP standards without conventional solvent extraction. Cosmetic formulators in France and Germany are adopting these stocks for traceability advantages under EU cosmetic regulation.
REACH Annex XVII restrictions on microplastics are pressuring cosmetic emollient selection. ECHA's 2023 broadened definition captures synthetic polymers previously used in rinse-off products, redirecting demand toward mineral oil alternatives. Personal care contract manufacturers in Italy and Spain are reformulating around white oil to preempt enforcement actions.
Direct procurement from refinery gate is consolidating buyer-seller relationships. Large cosmetics houses in Switzerland and the Netherlands are negotiating multi-year offtake agreements with integrated producers, displacing distributor intermediaries. This pattern is most pronounced among fragrance and skin-care multinationals seeking supply security for EU Green Deal compliance roadmaps.
Global White Oil Market Segmentation
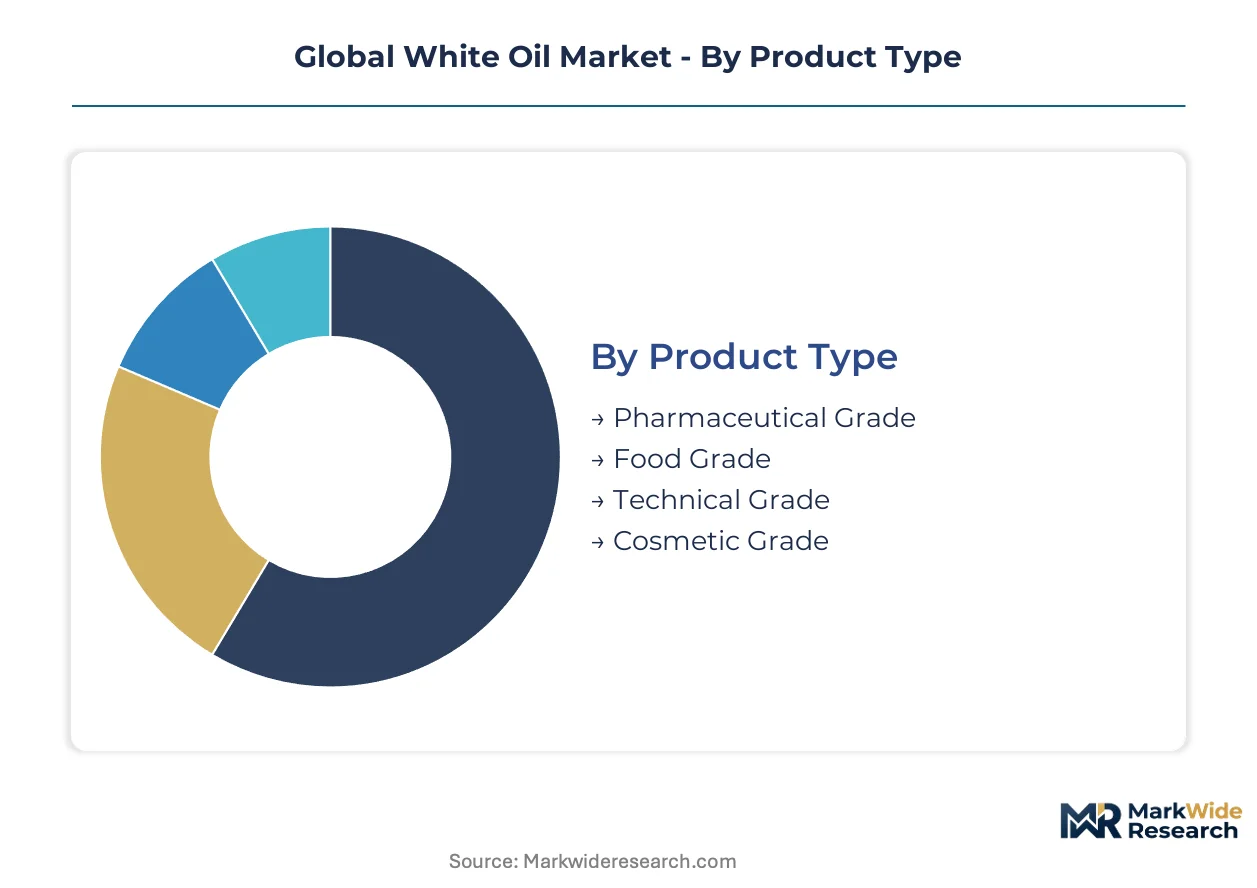
White oil specifications diverge sharply across purity tiers, with hydrotreating intensity and pharmacopeial compliance determining accessible end-use markets. Segmentation logic follows certification boundaries rather than viscosity alone, as FDA 21 CFR and REACH registrations gate commercial viability for each grade.
Product Type:
Purity thresholds separate four distinct specification bands, each demanding progressively severe refining and sulfur guard bed investment.
- Pharmaceutical Grade:Achieves USP/NF and EP monograph compliance through multi-stage hydrotreating, yielding aromatics below 0.1% and sulfur under 10 ppm. Demand concentrates among parenteral drug manufacturers in Germany and Switzerland, where EMA inspections enforce batch-level traceability. FDA 21 CFR 172.878 compliance burdens compress supplier pools to integrated refiners with captive hydrogen supply.
- Cosmetic Grade:Meets EU cosmetic regulation safety assessments and REACH Annex XVII microplastic restrictions, serving skin-care formulators replacing cyclic silicones. Italian and Spanish contract manufacturers are absorbing rising volumes as ECHA D4/D5/D6 limitations tighten.
- Food Grade:Satisfies FDA 21 CFR 178.3620(a) for incidental food-contact lubricants in bakery and beverage processing equipment.
- Technical Grade:Supplies textile fiber lubrication and PVC plasticizer applications across Gujarat and Maharashtra industrial corridors.
Mature deployment sits with Technical Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
End-use specifications range from pharmacopeial injectable standards to industrial bulk lubrication, with regulatory density determining margin structure.
- Cosmetics:Emollient and carrier functions in skin-care and hair-care formulations are expanding most quickly as formulators abandon silicones under ECHA pressure. French and German brands prioritize Fischer-Tropsch-derived stocks for EU Green Deal traceability requirements.
- Pharmaceuticals:Parenteral and topical drug delivery systems demand USP-compliant white oil with comprehensive batch documentation.
- Food Processing:Incidental contact lubricants for processing machinery require FDA 21 CFR 178.3620(a) certification, opening bakery and beverage equipment segments previously served by synthetics.
- Industrial Lubricants:Textile fiber lubrication and metalworking applications absorb technical-grade volumes in India and China manufacturing clusters.
Volume leadership belongs to Industrial Lubricants. Margin concentration favors Pharmaceuticals.
End User:
Procurement patterns split between direct refinery offtake by large formulators and distributor-mediated supply for fragmented industrial buyers.
- Manufacturers:Integrated personal care and pharmaceutical producers in Switzerland and the Netherlands negotiate multi-year refinery gate agreements, bypassing traditional distributor intermediaries for EU Green Deal compliance security.
- Distributors:Serve mid-sized cosmetics houses and regional pharmaceutical compounders requiring drum-to-pail format flexibility.
- Retailers:Pharmacy chains and cosmetic specialty stores stock consumer-facing white oil products in bottle configurations.
- Healthcare Providers:Hospital systems and clinical networks procure pharmaceutical-grade stocks for compounding pharmacies.
Direct procurement is concentrating among Manufacturers. Distributor channels retain fragmented regional accounts.
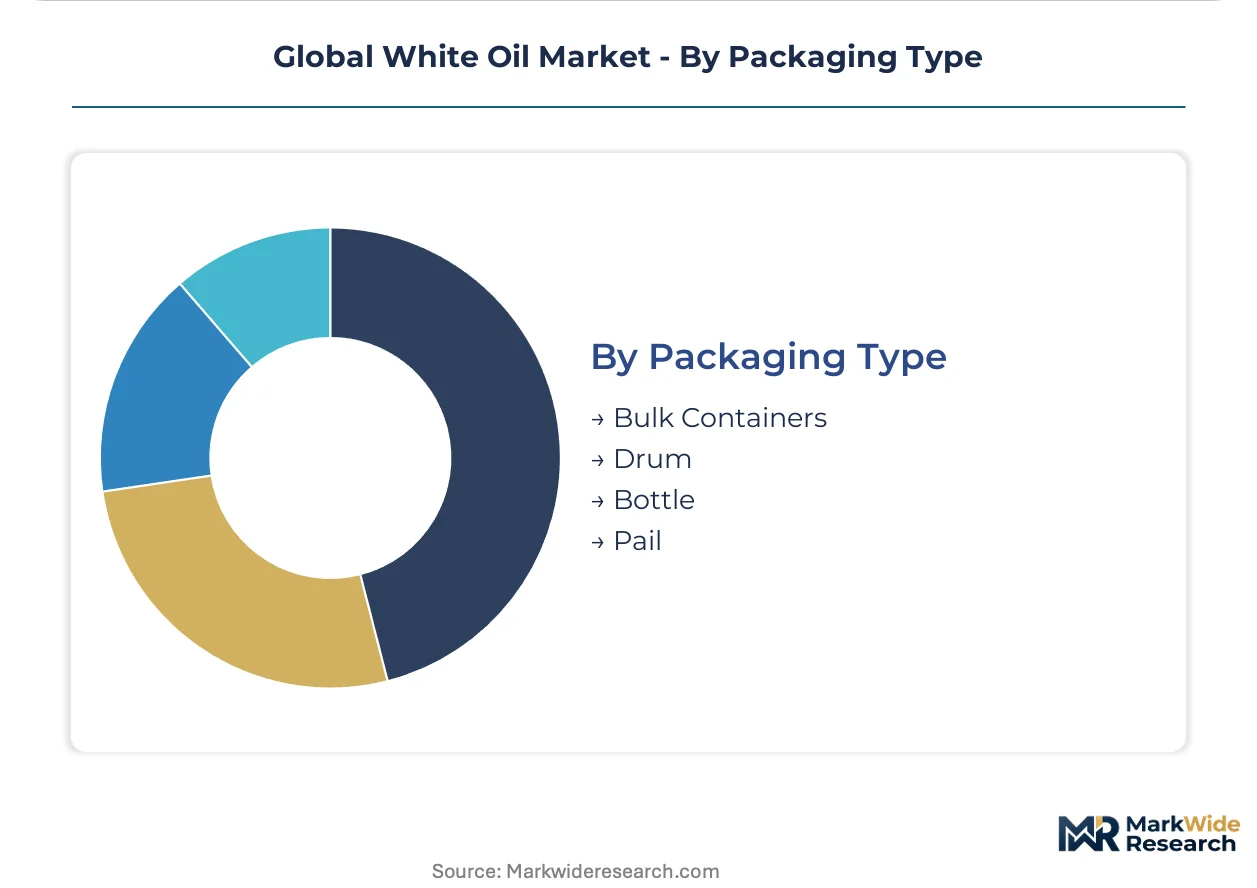
Packaging Type:
Format selection tracks order scale and handling infrastructure, with modular configurations enabling direct-to-formulator distribution strategies.
- Bulk Containers:Rail and tanker deliveries serve large textile and plasticizer manufacturers in Gujarat and Maharashtra with dedicated storage infrastructure.
- Drum:Standard 200-liter units bridge industrial and cosmetic applications, offering handling flexibility for mid-volume pharmaceutical compounders.
- Bottle:Consumer-facing and clinical pharmacy formats require pharmaceutical-grade filling operations with contamination controls.
- Pail:Small-batch cosmetic formulators in Shanghai and Guangzhou prefer pail configurations for just-in-time inventory management.
Industrial scale favors Bulk Containers. Format experimentation is concentrated in Pail configurations for emerging cosmetic brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra anchor India's technical-grade white oil demand, while pharmaceutical-grade consumption clusters in Swiss and German manufacturing corridors under EU Green Deal traceability mandates.
United States
Pharmaceutical-grade white oil demand concentrates among parenteral drug manufacturers in New Jersey and Pennsylvania. FDA 21 CFR 172.878 and 178.3620(a) standards enforce batch-level documentation requirements that filter supplier pools. Gulf Coast refining hubs in Texas and Louisiana supply paraffinic base stocks to hydrotreating facilities serving cosmetic and food-contact lubricant channels.
Germany
Cosmetic formulators in Hamburg and Düsseldorf are substituting white oil for cyclic silicones under ECHA D4/D5/D6 restrictions. REACH registration burdens disqualify non-compliant imports, tightening supply for registered producers. The Rhine-Ruhr industrial corridor hosts pharmaceutical compounders demanding USP-compliant stocks with comprehensive traceability documentation.
China
Domestic cosmetic brands in Shanghai and Guangzhou seek import-grade white oil as local quality inconsistencies persist. GB standards and SAMR oversight add compliance layers for foreign suppliers entering personal care channels. Yangtze River Delta textile manufacturers absorb rising technical-grade volumes for fiber lubrication applications.
India
Textile and plasticizer manufacturers in Gujarat and Maharashtra drive technical-grade consumption for PVC processing and industrial lubrication. BIS certification requirements create import friction for non-compliant suppliers. The Delhi-Mumbai Industrial Corridor anchors bulk container procurement patterns among mid-sized compounders.
Switzerland
Fragrance and skin-care multinationals in Geneva and Basel negotiate multi-year refinery gate agreements for EU Green Deal compliance security. Swissmedic oversight enforces pharmacopeial standards for pharmaceutical-grade stocks. Direct procurement from integrated producers is displacing traditional distributor intermediaries among large formulators.
Global White Oil Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across purity tiers, with integrated refiners commanding pharmaceutical-grade positioning and regional blenders serving technical-grade bulk demand. The market structure concentrates among hydrotreating-capable producers with captive base stock supply, filtering access for non-integrated entrants. Three archetypes dominate: integrated oil majors with global refining footprints, Fischer-Tropsch specialists leveraging gas-to-liquids technology, and regional processors serving industrial bulk channels. Competitive moves center on backward integration into base stock production and multi-year offtake agreements with cosmetics and pharmaceutical formulators.
Among integrated oil majors, ExxonMobil Corporation anchors supply reliability through its Gulf Coast refining footprint, while Shell plc exemplifies gas-to-liquids positioning through Fischer-Tropsch-derived feedstocks. Sonneborn LLC occupies a specialist tier focused on high-purity pharmaceutical and cosmetic grades, representing the pure-play archetype against diversified conglomerate competition.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| China Petroleum & Chemical Corporation |
| Chevron Corporation |
| Calumet, Inc. |
| Sasol |
| TotalEnergies |
| Petro-Canada Lubricants Inc. |
| Sonneborn LLC |
| Others |
Supply Flow & Price Mechanics
Specialized hydrotreating engineers concentrated along the US Gulf Coast and Rhine-Ruhr corridor command wage premiums that compress margins for pharmaceutical-grade producers while widening spreads against technical-grade alternatives sourced from lower-cost manufacturing clusters in India and China.
Pricing Analysis
Short lead-time premiums distinguish contract pharmaceutical-grade supply from spot technical-grade availability, with registered producers capturing pricing power through REACH-compliant batch documentation. Three-tier pricing structure across pharmaceutical, cosmetic, and technical grades reflects certification burden and hydrotreating intensity. Cost compression in technical-grade channels is intensifying because textile manufacturers in Gujarat negotiate volume aggregates against spot suppliers. Pharmaceutical compounders exhibit lowest price sensitivity due to pharmacopeial revalidation costs, while PVC plasticizer buyers in Maharashtra absorb rising spot volatility.
Supply Chain Analysis
USP and EP certification gates filter supplier pools to integrated refiners with captive hydrogen infrastructure, compressing eligible sources for pharmaceutical-grade offtake. Paraffinic base stock production clusters in the United States, Saudi Arabia, and South Korea, with Fischer-Tropsch feedstocks from Qatar and South Africa anchoring ultra-low-aromatic alternatives. Supply chain risk centers on hydrogen supply security for hydrotreating-intensive producers facing renewable hydrogen cost escalation. Distribution runs through refinery gate direct agreements for large cosmetics multinationals, with drum-to-pail intermediaries serving fragmented regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around hydrotreating-capable integrated producers as REACH registration burdens and pharmacopeial compliance costs force non-integrated blenders toward exit or acquisition.
For Market Incumbents: To counter Group III+ synthetic substitution in high-viscosity lubricant applications, prioritize backward integration into Fischer-Tropsch base stock supply through long-term offtake agreements with gas-to-liquids operators in Qatar and South Africa. Secure channel control by expanding modular pail packaging capacity for direct-to-formulator distribution in Shanghai and Guangzhou cosmetic clusters. For New Entrants and Emerging Players: Capture technical-grade white-space in India's Delhi-Mumbai Industrial Corridor by targeting mid-sized PVC plasticizer manufacturers currently served by inconsistent local suppliers. Penetration runs through BIS certification investment and bulk container logistics partnerships with Gujarat textile distributors, bypassing established refinery gate relationships. For Investors and Strategic Acquirers: The window for entry favors hydrotreating-capable regional processors with latent pharmaceutical-grade upgrade potential, particularly those with existing hydrogen supply infrastructure. Long-term viability hinges on EU Green Deal traceability alignment and REACH registration completion. Watch for ECHA microplastic enforcement acceleration as inflection signal redirecting cosmetic emollient demand toward mineral oil alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fischer-Tropsch Feedstocks | Sasol's South African operations demonstrate captive ultra-low-aromatic supply security for USP compliance. |
| REACH Registration Completion | EMA inspections enforce batch traceability that filters competitor pools in German parenteral drug channels. |
| Modular Packaging Capacity Expansion | Pail configurations enable just-in-time delivery to Shanghai cosmetic formulators bypassing bulk terminals. |
| Direct Refinery Gate Agreements | Swiss fragrance multinationals negotiate multi-year offtake for EU Green Deal compliance security. |
| Pharmaceutical-Grade Hydrotreating Upgrade | High-pressure hydrogen unit investment opens FDA 21 CFR 172.878 parenteral drug delivery markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with refinery operations managers, cosmetic formulator procurement leads, pharmaceutical compounding supervisors, and Fischer-Tropsch process engineers. FDA 21 CFR submissions, ECHA REACH registration databases, USP-NF monograph updates, and BIS certification records provided validation benchmarks. Bottom-up grade-by-grade volume estimates triangulated against top-down end-use consumption models across pharmaceutical, cosmetic, food-contact, and industrial lubricant channels.
Reconciliation of production capacity disclosures, import-export flows, and downstream offtake patterns shaped analytical frameworks across the analysis window. Segmentation modeling incorporated purity tier, application end-use, packaging format, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand projections and capacity expansion timelines, with hydrogen supply cost curves and ECHA enforcement probability weighting scenario outputs.
The model holds under stable REACH registration timelines and consistent pharmacopeial standards; deviation in ECHA microplastic enforcement acceleration or renewable hydrogen cost spikes would shift grade-level margin projections. A model refresh is warranted upon material change in EU Green Deal traceability mandates or FDA food-contact rule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Paraffin Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Europe Wax Market
Oleochemicals
1-Decene Market
Oleochemicals
Ethylene Bis Stearamide Market