
 Candelilla Wax Market | 2026-2036
Candelilla Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Candelilla Wax Market Analysis
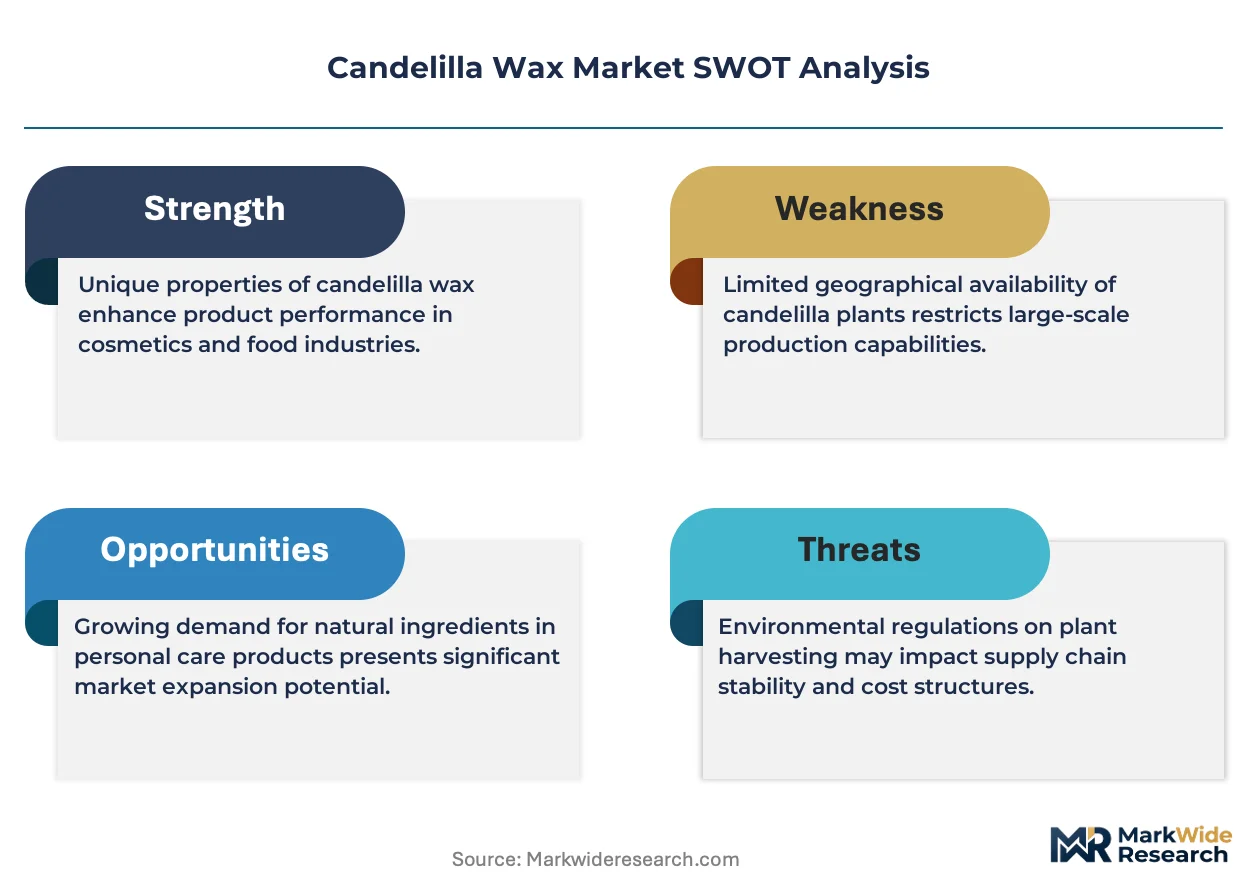
Plant-based emulsification technology is reconfiguring how cosmetic formulators replace synthetic thickeners and stabilizers. Multiceras S.A. de C.V. anchors Mexican supply chains through direct cultivation partnerships in the Chihuahuan Desert. Koster Keunen differentiates via specialized refining capabilities for pharmaceutical-grade material. Strahl & Pitsch competes in European personal care channels with certified sustainable sourcing programs.
Candelilla wax is a hard, brittle vegetable wax extracted from the leaves of Euphorbia antisyphilitica, containing hydrocarbons, esters, and free alcohols with a melting point of 68-73°C; it functions primarily as a glazing agent, binder, and viscosity modifier across food, cosmetic, and industrial applications. Refined candelilla wax commands premium positioning in pharmaceutical coatings where purity specifications exclude unprocessed grades. Cosmetics applications lead volume consumption due to clean-label momentum, while emulsified variants represent the fastest-growing product type as formulators seek ready-to-disperse solutions. Powder and flake forms dominate industrial procurement, though pearl grades capture margin pools in luxury personal care.
FDA food additive regulations under 21 CFR 184.1976 govern candelilla wax safety in edible coatings, while ECHA REACH compliance shapes European import requirements for residual solvent content. Mexico's SEMARNAT environmental permits restrict wild harvesting volumes, tightening raw material availability. Stakeholders must monitor evolving bioprospecting agreements and certification schemes that determine access to premium-priced sustainable segments.
Market Dynamics
Clean-label mandates across personal care and food packaging are compressing demand for petroleum-derived waxes, redirecting procurement toward botanical alternatives with verified supply chain documentation. ECHA REACH compliance requirements and FDA food additive standards now function as de facto market gatekeepers, filtering out unprocessed grades and rewarding refined, certified material.
Growth Catalysts
- REACH substitution rules:European chemical safety standards under ECHA tighten residual solvent limits, forcing formulators to replace synthetic glazing agents with plant-derived alternatives that meet purity specifications.
- Emulsified product formats:Ready-to-disperse candelilla wax solutions reduce manufacturing complexity for cosmetic compounders, accelerating adoption in mid-tier personal care operations lacking in-house refining capability.
- Chihuahuan Desert cultivation clusters:Concentrated wild harvesting and nascent domestication programs in Mexico's northern states anchor raw material availability for premium-grade extraction.
Market Restraints
- Input cost volatility:Rainfall-dependent wild harvesting of Euphorbia antisyphilitica creates raw material availability swings that compress processor margins during drought cycles.
- Supply concentration risk:SEMARNAT environmental permitting restricts harvest volumes to specific desert municipalities, creating single-point vulnerability for unrefined wax flows.
- Substitution threat:Carnauba wax from Brazilian palm cultivation competes directly in high-temperature coating applications where melting point performance overlaps.
Strategic Opportunities
- Pharmaceutical coating expansion:USP-grade material for tablet binders and enteric coatings commands price multiples over food-grade equivalents, with FDA 21 CFR 184.1976 compliance enabling market access.
- Bioprospecting agreements:Structured benefit-sharing contracts with indigenous harvester cooperatives unlock certified sustainable sourcing credentials demanded by European personal care brands.
- Direct-to-compounder distribution:Bypassing traditional chemical distributor networks via specialized ingredient platforms reduces lead times for mid-size cosmetic manufacturers.
Industry Challenges
- Refining skill scarcity:Solvent extraction and bleaching expertise required for pharmaceutical-grade output concentrates among a limited pool of Mexican and Dutch processors.
- Certification timeline compression:Organic and fair-trade accreditation processes spanning 18-24 months delay market entry for new cultivation partnerships seeking premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candelilla Wax Market |
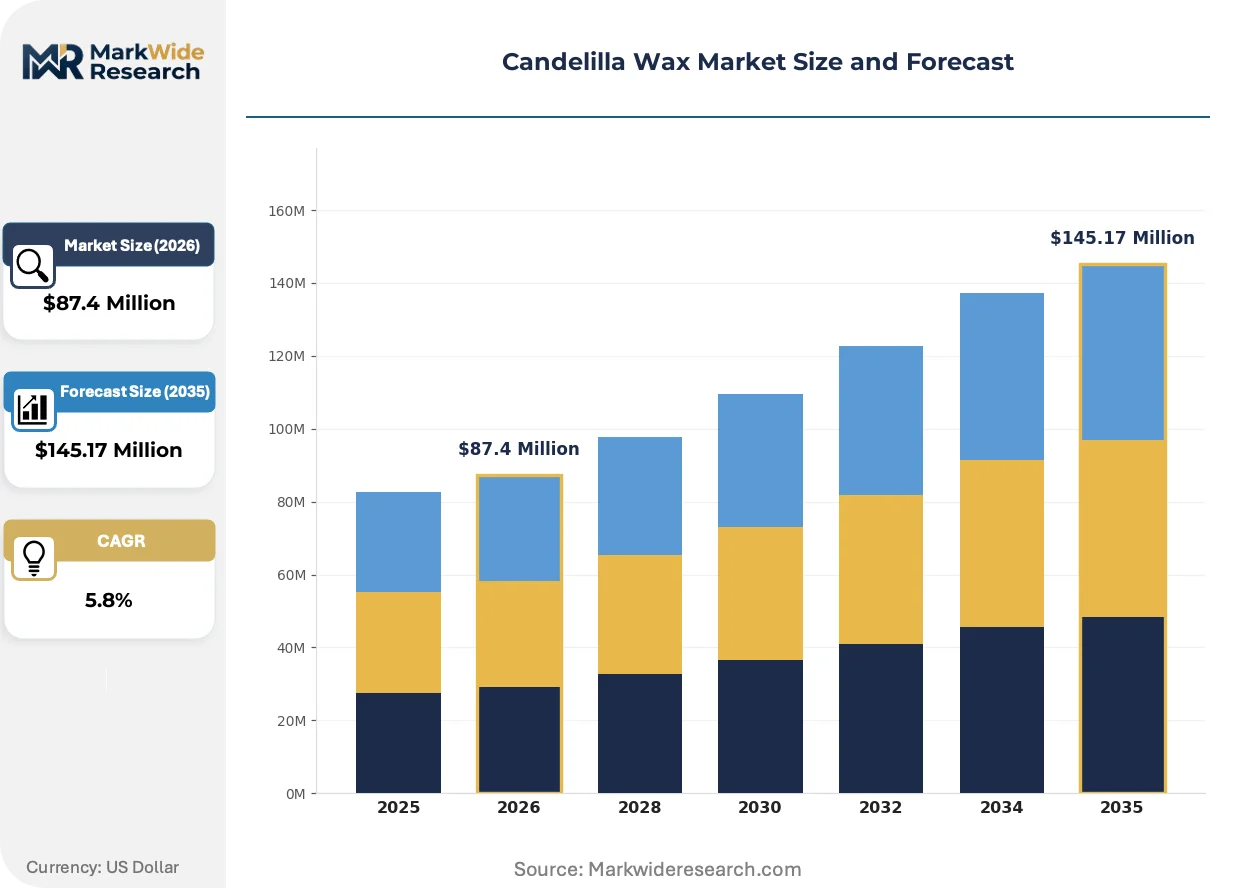
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Candelilla Wax, Refined Candelilla Wax, Emulsified Candelilla Wax, Liquid Candelilla Wax Application: Cosmetics, Pharmaceuticals, Food Industry, Coatings End User: Personal Care Manufacturers, Food Processors, Paper Manufacturers, Pharmaceutical Companies Form: Pearl, Powder, Granule, Flake |
| Companies Covered | Multiceras S.A. de C.V., International Group IGI, Koster Keunen, Arjun Beeswax Industries, KahlWax, Strahl & Pitsch, Carmel Group, Desert King International, Norevo GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candelilla Wax Market Emerging Trajectories
Formulation science and procurement protocols are converging to redefine how vegetable waxes integrate into industrial supply chains, with purity verification and dispersibility emerging as decisive technical battlegrounds.
Micro-emulsion technology for candelilla wax is hybridizing traditional solid-flake processing with liquid-delivery formats. Mid-size cosmetic manufacturers lacking in-house melting and dispersion equipment are adopting these pre-emulsified concentrates at accelerating rates. The shift is compressing equipment capex requirements for market entry while concentrating value capture among specialized refiners with proprietary dispersion chemistry.
ECHA REACH Annex XVII restrictions on residual toluene and hexane in imported waxes are tightening testing and documentation burdens. European personal care brands now require third-party solvent-content certificates for every batch, filtering out unrefined Mexican exports. German and Dutch importers are responding by integrating in-house GC-MS testing capability or sourcing exclusively from REACH-registered refiners.
Specification-driven buying patterns are displacing commodity-grade spot purchasing among North American personal care compounders. Cosmetic formulators now issue multi-year offtake agreements tied to specific acid value, saponification number, and color-grade parameters. This behavioral shift is most visible in California and New Jersey formulation clusters, where clean-label brand positioning requires documented batch-to-batch consistency unavailable through traditional broker channels.
Candelilla Wax Market Segmentation
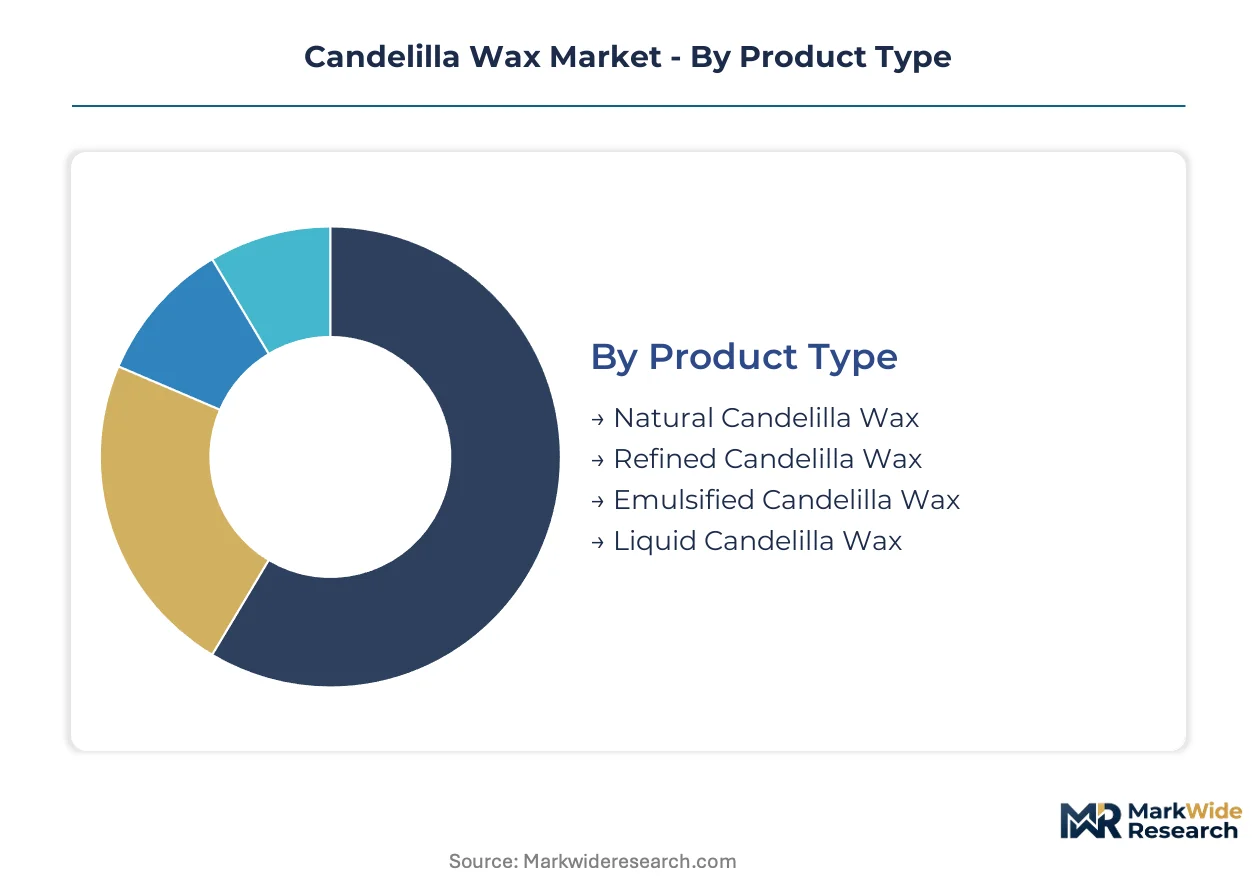
Segmentation in the candelilla wax market reveals how purification depth and physical form determine pricing power and customer access. Procurement patterns diverge sharply between specification-driven pharmaceutical buyers and cost-sensitive industrial compounders.
Product Type:
Cycle times vary from immediate-spot purchasing for unprocessed grades to 18-month qualification timelines for pharmaceutical-certified material. Refined and emulsified variants turn inventory fastest as cosmetic formulators pre-approve specifications.
- Refined Candelilla Wax:Solvent-extracted and bleached material meeting acid value and saponification specifications for pharmaceutical coatings. FDA 21 CFR 184.1976 compliance enables access to tablet binder applications where unprocessed grades face rejection.
- Emulsified Candelilla Wax:Pre-dispersed aqueous solutions eliminate in-house melting equipment for mid-tier personal care manufacturers. California and New Jersey formulation clusters adopt these concentrates to compress equipment capex requirements.
- Natural Candelilla Wax:Unprocessed wild-harvested material with higher hydrocarbon content for industrial glazing.
- Liquid Candelilla Wax:Low-viscosity derivatives for spray-applied coating systems.
Refined candelilla wax dominates installed base. Emulsified candelilla wax is where expansion concentrates.
Application:
Margin structures stratify across certification intensity, with pharmaceutical and food coatings commanding multiples over industrial uses.
- Cosmetics:Clean-label lipsticks, mascaras, and hair styling products leverage candelilla wax as a vegan alternative to beeswax. ECHA REACH-compliant documentation now gates European personal care procurement.
- Pharmaceuticals:Enteric tablet coatings and sustained-release binders require USP-grade material with verified residual solvent profiles.
- Food Industry:Edible fruit coatings and confectionery glazes under FDA 21 CFR 184.1976.
- Coatings:Wood furniture and paperboard sizing applications.
Cosmetics commands revenue concentration. Pharmaceuticals is climbing the fastest.
End User:
Customer scale determines contract structure, with multinational pharmaceutical companies locking multi-year offtakes while regional food processors buy spot.
- Personal Care Manufacturers:Clean-label brand owners in California issue specification-driven purchase orders tied to batch-to-batch consistency parameters.
- Pharmaceutical Companies:Tablet and capsule producers require REACH-registered supply chains with third-party solvent-content certificates.
- Food Processors:Citrus and apple coating operations in Mexico and the United States.
- Paper Manufacturers:Sizing and moisture-barrier applications.
Personal care manufacturers dominate installed base. Pharmaceutical companies is where expansion concentrates.
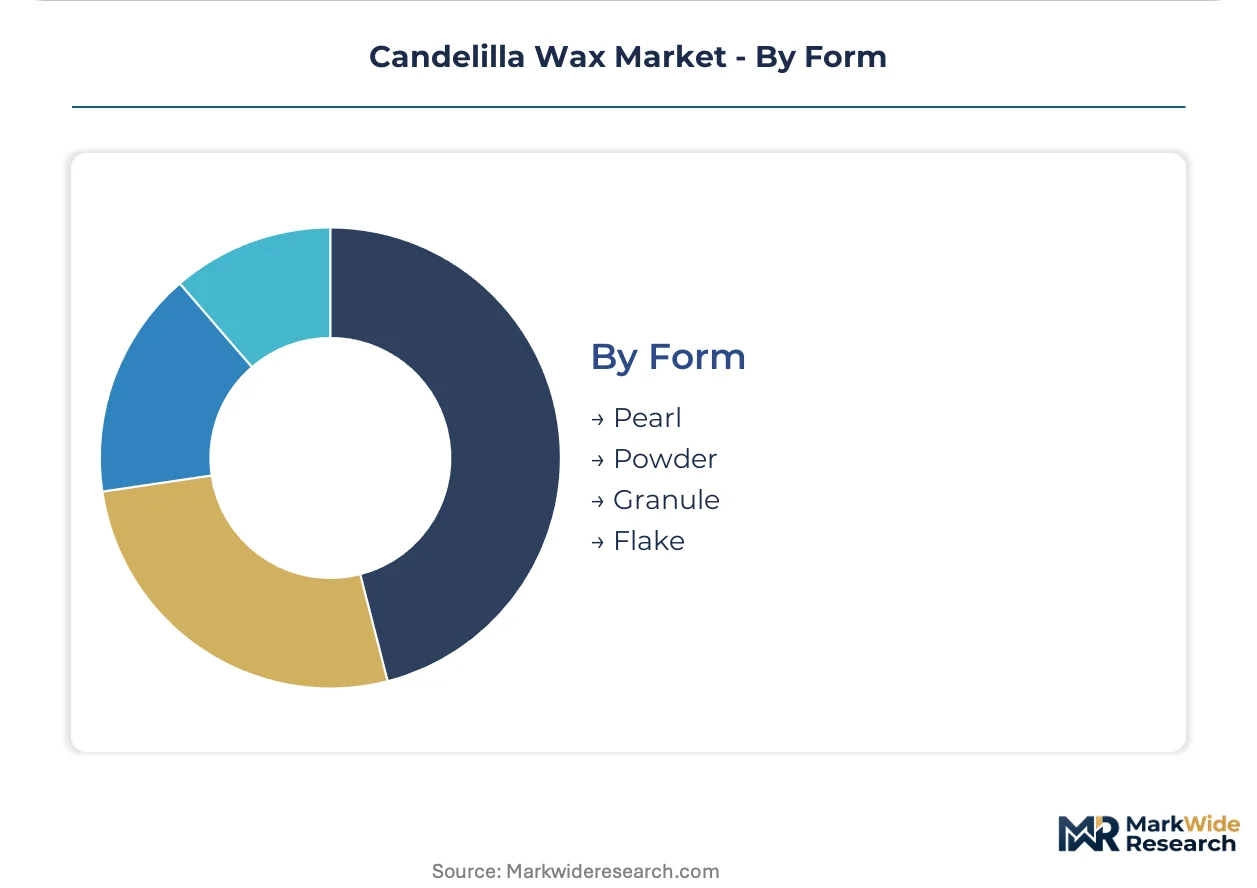
Form:
Physical morphology dictates handling infrastructure, with pearl grades requiring specialized melting vessels while powders feed standard compounders.
- Flake:Standard industrial feedstock for hot-melt compounding. Paper manufacturers and coating operations in Chihuahuan Desert processing clusters consume bulk volumes.
- Pearl:Spherical particles for luxury personal care where visual aesthetics support premium positioning.
- Powder:Micronized material for dry-blend cosmetic formulations.
- Granule:Intermediate sizing for food-grade glazing operations.
Flake dominates installed base. Pearl is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate between Mexican extraction zones and North American and European formulation hubs. The United States and Germany import refined grades for pharmaceutical and personal care compounding, while unprocessed material moves through Dutch and Belgian distribution nodes for REACH compliance processing.
United States
Personal care formulators in California and New Jersey drive specification-driven procurement for clean-label cosmetics. FDA 21 CFR 184.1976 governs food-grade applications for edible coatings on citrus and apples. The New Jersey pharmaceutical corridor consumes USP-grade material for tablet binders and enteric coatings.
Germany
ECHA REACH Annex XVII restrictions on residual solvents filter import flows toward registered refiners with GC-MS documentation capability. German cosmetic brands require third-party solvent-content certificates for every batch. The Cologne-Düsseldorf chemical cluster processes imported Mexican wax for redistribution across European personal care channels.
Mexico
Wild harvesting of Euphorbia antisyphilitica concentrates in Chihuahuan Desert municipalities under SEMARNAT environmental permit restrictions. Domestic refiners supply both export markets and local food processors coating citrus for US export. Multiceras S.A. de C.V. anchors cultivation partnerships in northern desert states.
Netherlands
Rotterdam and Amsterdam serve as REACH compliance gateways for Mexican wax entering European cosmetic supply chains. Dutch importers integrate in-house testing capability or source exclusively from ECHA-registered refiners. The country's specialty chemical distribution infrastructure supports just-in-time delivery to German and French formulators.
India
Arjun Beeswax Industries and domestic compounders process imported candelilla wax for regional cosmetic and pharmaceutical applications. FSSAI food safety standards govern edible coating uses for domestic fruit processing. Mumbai and Ahmedabad formulation clusters adopt plant-based waxes for export-oriented personal care manufacturing.
Candelilla Wax Market Vendor Landscape
On the supply side, the industry is bifurcated between Mexican wild-harvesting cooperatives and specialized European refiners with pharmaceutical-grade capability. The vendor base stratifies across three tiers: desert-based raw material aggregators, mid-scale regional processors, and integrated specialists with REACH-registered refining assets. Competitive moves concentrate on bioprospecting agreements with indigenous harvester communities and backward integration into controlled cultivation programs.
Within the integrated specialist tier, Multiceras S.A. de C.V. and Koster Keunen exemplify divergent geographic anchoring strategies. Multiceras occupies a position tied to Chihuahuan Desert sourcing infrastructure, while Koster Keunen sits within European pharmaceutical-grade refining networks. Strahl & Pitsch represents the sustainability-certification archetype, with positioning shaped by European personal care channel requirements. Desert King International and Norevo GmbH anchor North American and Central European distribution nodes respectively.
| Leading Market Players |
|---|
| Multiceras S.A. de C.V. |
| International Group IGI |
| Koster Keunen |
| Arjun Beeswax Industries |
| KahlWax |
| Strahl & Pitsch |
| Carmel Group |
| Desert King International |
| Norevo GmbH |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Chihuahuan Desert harvesting zones during drought cycles simultaneously elevates raw material spot prices and compresses processor margins, forcing refiners to prioritize long-term offtake contracts over spot sales while buyers front-load inventory positions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pharmaceutical-grade material commanding premiums over food-grade equivalents based on USP certification and REACH registration status. Price differentiation rests on acid value specifications and third-party solvent-content documentation. Cost compression in unprocessed wild-harvested tiers is intensifying because SEMARNAT harvest restrictions constrain supply elasticity. Personal care compounders in California exhibit lowest price sensitivity due to clean-label brand positioning requirements.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculus for North American pharmaceutical buyers. Geographic concentration centers on Mexico, the United States, and Germany, with raw material flows drawing from Euphorbia antisyphilitica wild harvesting, solvent extraction chemicals, and bleaching agents. Single-source vulnerability concentrates in Chihuahuan Desert municipalities under SEMARNAT permitting. Distribution runs through Rotterdam and Amsterdam as REACH compliance gateways for European cosmetic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment functions as the market's defensive moat: ECHA REACH registration and FDA 21 CFR 184.1976 compliance create switching costs that lock in qualified suppliers and filter out unprocessed competitors.
For Market Incumbents: Pre-empt carnauba wax substitution threats by deepening backward integration into controlled cultivation programs in northern Mexican desert states. Anchor capacity addition in Chihuahuan Desert clusters to secure SEMARNAT permit allocations before competitor filings. Prioritize USP-grade certification investment to capture pharmaceutical coating expansion. For New Entrants and Emerging Players: Pursue emulsified candelilla wax white space in mid-tier California and New Jersey personal care operations lacking in-house refining equipment. Target Indian pharmaceutical compounders in Mumbai and Ahmedabad as the most penetrable geography given FSSAI regulatory alignment and export-oriented manufacturing growth. Deploy direct-to-compounder digital ingredient platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across emulsified product manufacturing as dispersion chemistry modularizes. Long-term viability favors REACH-registered refiners with proprietary micro-emulsion capabilities and bioprospecting agreements with indigenous harvester cooperatives. Acquisition target archetype: mid-scale Mexican processors with SEMARNAT permits and unexploited pharmaceutical-grade capacity. Watch ECHA Annex XVII solvent limit revisions as the inflection signal for compliance cost step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | SEMARNAT permit holdings in Chihuahuan Desert municipalities secure raw material access against drought volatility. |
| REACH Registration Investment | ECHA compliance documentation gates European pharmaceutical and personal care procurement channels. |
| Micro-Emulsion Product Development | Ready-to-disperse formats capture mid-tier cosmetic manufacturers lacking in-house melting infrastructure. |
| Bioprospecting Agreement Structuring | Benefit-sharing contracts with indigenous harvester cooperatives unlock certified sustainable sourcing credentials. |
| USP-Grade Refining Capacity Expansion | FDA 21 CFR 184.1976-compliant material commands price multiples in tablet binder and enteric coating applications. |
Methodological Framework
Operator-level perspectives from wax refinery plant managers, procurement leads at California personal care OEMs, distribution channel partners in Rotterdam, and SEMARNAT compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from Mexican customs export data, ECHA REACH registration databases, FDA 21 CFR filings, and SEC 10-K disclosures for listed chemical processors. Bottom-up volume modeling across extraction zones and top-down demand triangulation from end-use industries cross-validated projections.
Scenario-bracketing around drought frequency, REACH solvent limit stringency, and carnauba wax price competitiveness bounded the forecast range across the analysis window. Segmentation dimensions modeled include purification grade, physical form, application vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution coefficients between vegetable wax alternatives. Industry-specific inputs captured SEMARNAT harvest permit issuance rates and California clean-label formulation adoption curves.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, European energy costs affecting refining economics, and personal care consumer discretionary spending would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and harvest yield distributions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Global Palm Wax Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Global Oxidized Polyethylene Wax Market