
 Petrolatum Market | 2026-2036
Petrolatum Market Size, Share, and Industry Trends Forecast 2026-2036
Petrolatum Market Analysis
Refinery technician shortages across specialty lubricant hubs is reorganizing how petrolatum suppliers secure operational capacity. Sasol leverages its Fischer-Tropsch synthesis expertise to sustain high-purity output for cosmetic and pharmaceutical grades. ExxonMobil anchors North American supply through integrated refining complexes that dominate industrial-grade distribution. Calumet Specialty Products Partners specializes in white petrolatum batches tailored to FDA monograph specifications, differentiating against commodity competitors.
Petrolatum is a semi-solid mixture of hydrocarbons derived from petroleum dewaxing, with melting points typically ranging from 38°C to 60°C and viscosity graded by penetration values measured in tenths of a millimeter. It functions primarily as an occlusive agent, lubricant base, and moisture barrier across topical formulations, mechanical assemblies, and food-contact coatings. Medical-grade petrolatum commands premium positioning due to USP compliance burdens and pharmaceutical validation requirements, while cosmetic-grade volumes lead absolute consumption through skin care and hair care applications. Industrial-grade segments face margin compression from synthetic alternatives, though lubrication demand in manufacturing end users preserves baseline offtake.
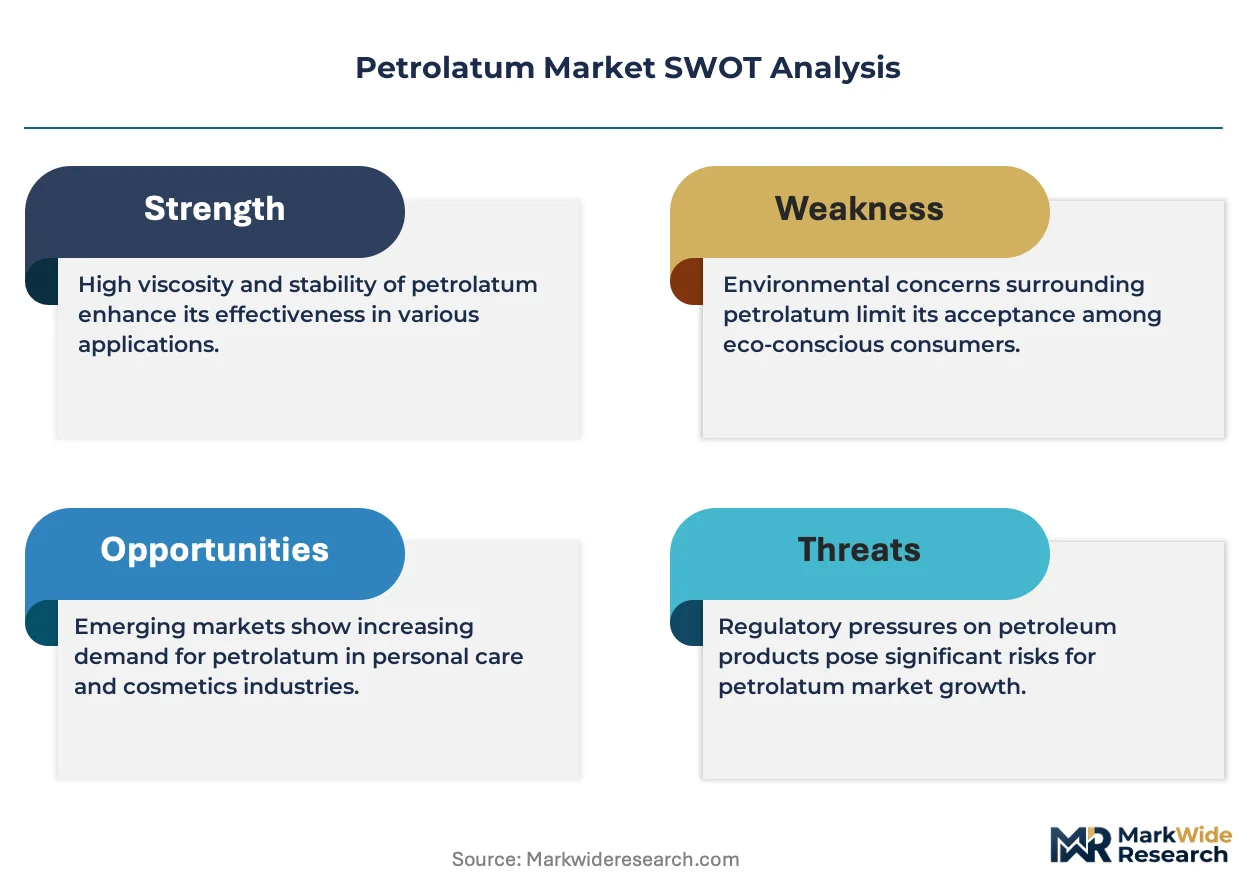
FDA monograph revisions and USP-NF updates govern pharmaceutical-grade petrolatum purity in the United States, while REACH and the EU Cosmetics Regulation impose full-substance registration and safety-assessment obligations across European supply chains. India's BIS certification and CDSCO excipient guidelines create parallel compliance tracks for imported and domestic petrolatum streams. Stakeholders must monitor regulatory divergence between pharmacopeial standards and industrial chemical frameworks, as compliance cost allocation between grades will determine portfolio profitability.
Market Dynamics
FDA monograph updates are compressing pharmaceutical-grade petrolatum supply chains, forcing manufacturers to revalidate excipient purity against tightened USP-NF standards while cosmetic formulators absorb REACH-driven substitution costs in Europe.
Growth Catalysts
- Pharmaceutical ointment expansion:Topical drug manufacturers in India are scaling CDSCO-compliant petrolatum procurement as domestic excipient standards tighten and import substitution policies favor certified suppliers.
- REACH compliance redirection:European formulators facing ECHA registration burdens are consolidating procurement around pre-certified petrolatum grades, creating premium positioning for compliant producers.
- Personal care volume pull:India's skin care and hair care segments are absorbing rising white petrolatum volumes as urban consumption patterns shift toward occlusive moisturizers and protective balms.
Market Restraints
- Crude-linked feedstock volatility:Petrolatum output tracks vacuum gas oil and slack wax availability from lube base oil production, exposing margins to refinery run-rate decisions.
- Specialty refinery concentration:High-purity petrolatum synthesis clusters in Fischer-Tropsch and integrated refining complexes, limiting geographic diversification of pharmaceutical-grade supply.
- Plant-based substitution pressure:Cosmetic brands facing EU Green Deal disclosure requirements are piloting squalane and shea butter alternatives in skin care formulations.
Strategic Opportunities
- Underpenetrated Southeast Asia:Indonesia and Vietnam present white-space demand as local personal care manufacturing scales without domestic petrolatum refining infrastructure.
- Medical device coating convergence:Petrolatum lubricant bases are penetrating catheter and syringe manufacturing as silicone supply constraints persist.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients creates captive demand for USP-grade excipients including petrolatum.
Industry Challenges
- Refinery technician scarcity:Specialty lubricant hubs face operational capacity constraints as dewaxing unit expertise concentrates among aging workforce cohorts.
- Pharmacopeial validation timelines:USP-NF compliance documentation for new petrolatum batches extends qualification cycles, delaying contract manufacturing onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petrolatum Market |
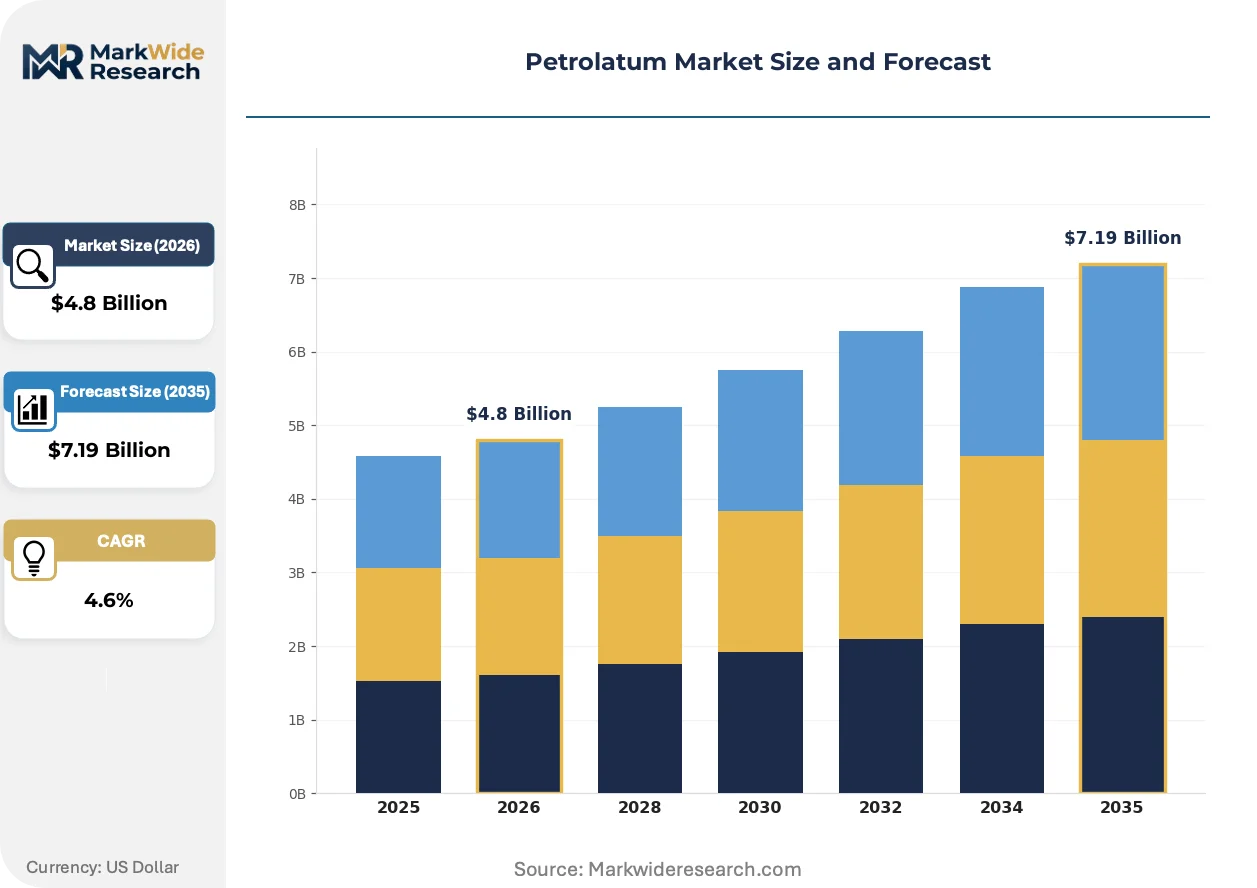
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Grade, Cosmetic Grade, Industrial Grade, Food Grade Application: Skin Care, Hair Care, Pharmaceutical, Lubrication Form: Gel, Ointment, Balm, Cream End User: Pharmacies, Personal Care Industry, Food Industry, Manufacturing |
| Companies Covered | Sasol, Sonneborn LLC, Eastern Petroleum, Unilever, International Group, Inc., Calumet Specialty Products Partners, ExxonMobil, Raj Petro Specialities Pvt. Ltd., Unisynth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petrolatum Market Emerging Trajectories
Formulation science and regulatory disclosure requirements are splitting petrolatum demand along purity-grade lines, with pharmaceutical and cosmetic segments diverging in sourcing criteria while industrial applications absorb synthetic displacement.
White petrolatum refinement is bifurcating across cosmetic and pharmaceutical specifications as molecular distillation and hydrotreating advances enable tighter control over polycyclic aromatic hydrocarbon content. USP-grade buyers in North America and Europe are locking in multi-year supply contracts with certified refiners. This technology shift is compressing commodity-grade margins while concentrating premium volume around validated producers.
REACH substance registration and the EU Cosmetics Regulation are imposing full supply-chain disclosure obligations on European petrolatum importers, requiring Safety Data Sheet updates and extended substance dossiers. Formulators are responding by consolidating procurement around ECHA-registered suppliers with pre-validated cosmetic-grade streams. Small-scale compounders lacking compliance infrastructure are exiting the market or switching to certified alternatives.
Contract manufacturers are unbundling excipient sourcing from finished formulation services, with pharmaceutical tollers demanding segregated petrolatum storage and dedicated batch documentation. This procurement model change disrupts traditional distributor relationships in India and Southeast Asia, where integrated chemical merchants previously dominated. The shift is most visible in Mumbai and Ahmedabad, where CDSCO-registered facilities are building direct ties to refinery-certified suppliers.
Petrolatum Market Segmentation
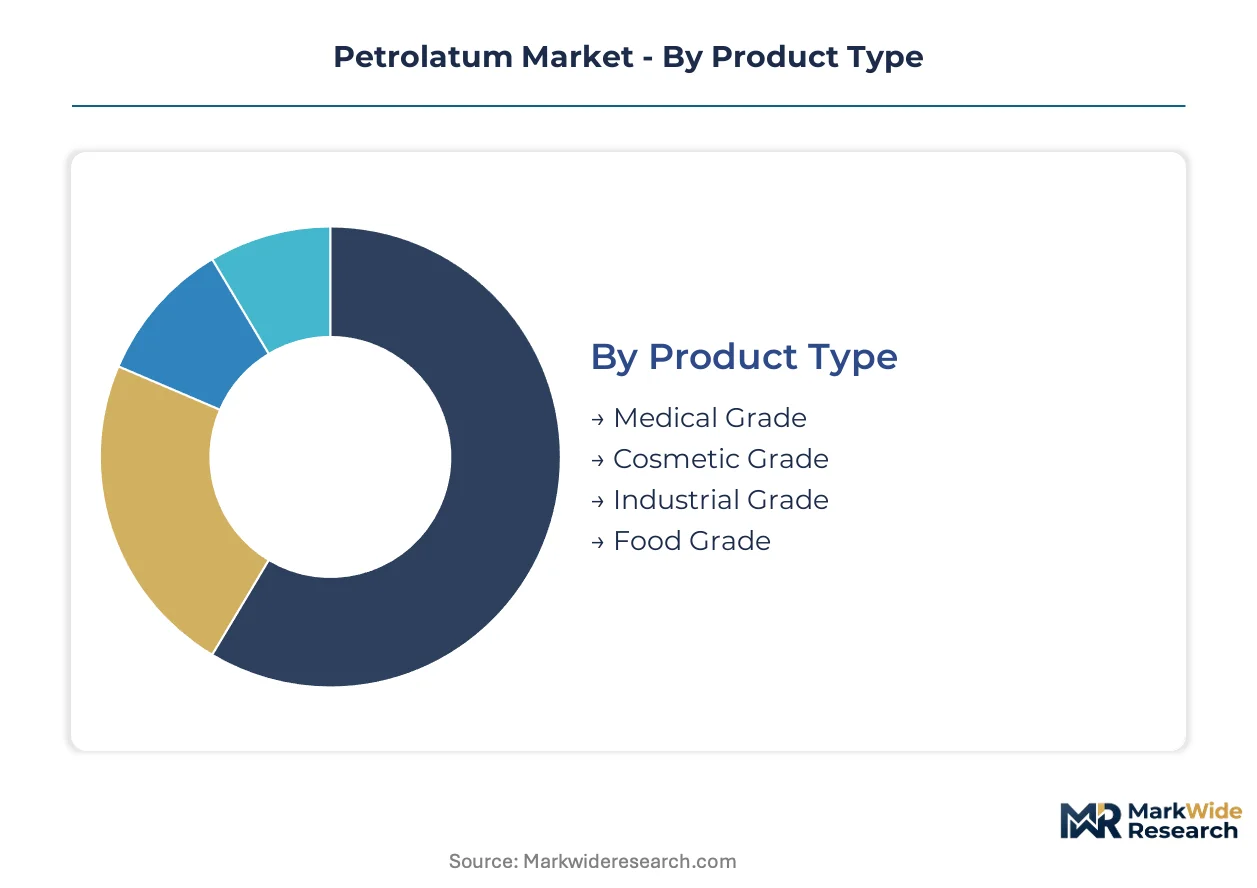
Petrolatum segmentation separates margin capture from volume throughput, with pharmaceutical and cosmetic grades commanding premium positioning against industrial commodity streams. Grade purity specifications and regulatory compliance burdens create distinct competitive arenas that suppliers must navigate simultaneously.
Product Type:
Margin pools concentrate in certified pharmaceutical and cosmetic grades where USP-NF compliance and REACH registration create defendable pricing power.
- Medical Grade:USP-NF compliant petrolatum undergoes hydrotreating and molecular distillation to achieve polycyclic aromatic hydrocarbon content below detectable limits. FDA monograph revisions are compressing qualified supplier lists as ointment manufacturers in India and the United States revalidate excipient streams against tightened purity thresholds.
- Cosmetic Grade:White petrolatum refined to meet EU Cosmetics Regulation safety assessments serves as the occlusive backbone in moisturizers, lip balms, and hair pomades. REACH substance registration burdens in Europe are redirecting procurement toward ECHA-registered suppliers with pre-validated cosmetic-grade streams, consolidating volume around certified producers.
- Industrial Grade:Standard petrolatum lubricates mechanical assemblies and protects metal surfaces in manufacturing environments, facing margin pressure from synthetic hydrocarbon substitutes.
- Food Grade:Petrolatum meeting FDA 21 CFR 172.880 specifications coats food-contact paper and cardboard, with limited volume relative to topical-grade segments.
The dominant share belongs to Cosmetic Grade, while Medical Grade is closing the gap fastest as pharmaceutical ointment manufacturers scale CDSCO-compliant procurement.
Application:
Application segmentation tracks how formulation science and regulatory disclosure requirements split demand across personal care, pharmaceutical, and industrial end-uses.
- Skin Care:Occlusive moisturizers, healing ointments, and protective balms absorb the largest white petrolatum volumes as urban consumption patterns in India shift toward barrier-repair formulations.
- Pharmaceutical:Topical drug bases, wound care dressings, and rectal suppositories demand USP-grade petrolatum with full batch documentation and segregated storage protocols.
- Hair Care:Pomades, edge control products, and conditioning treatments utilize petrolatum for hold and shine, facing substitution pressure from plant-based alternatives under EU Green Deal disclosure requirements.
- Lubrication:Industrial machinery, medical devices, and food processing equipment employ petrolatum as a lubricant base, with silicone supply constraints opening catheter and syringe manufacturing applications.
Skin Care holds the volume lead, though Pharmaceutical applications are expanding most quickly as India's PLI scheme for active pharmaceutical ingredients drives captive excipient demand.
Form:
Form differentiation reflects manufacturing process requirements and consumer usage patterns rather than fundamental compositional variation.
- Ointment:Semi-solid petrolatum bases dominate pharmaceutical compounding and over-the-counter topical drug manufacturing, requiring precise penetration value control.
- Balm:Thicker consistency petrolatum formulations serve protective and therapeutic skin applications, with added waxes modifying rheological properties.
- Cream:Oil-in-water emulsions incorporate petrolatum as the occlusive phase, demanding compatibility with emulsifier systems and preservative packages.
- Gel:Petrolatum-thickened systems appear in specialized pharmaceutical and veterinary applications with limited cosmetic penetration.
Ointment forms command the largest share, while Balm formats are gaining share fastest in premium personal care positioning.
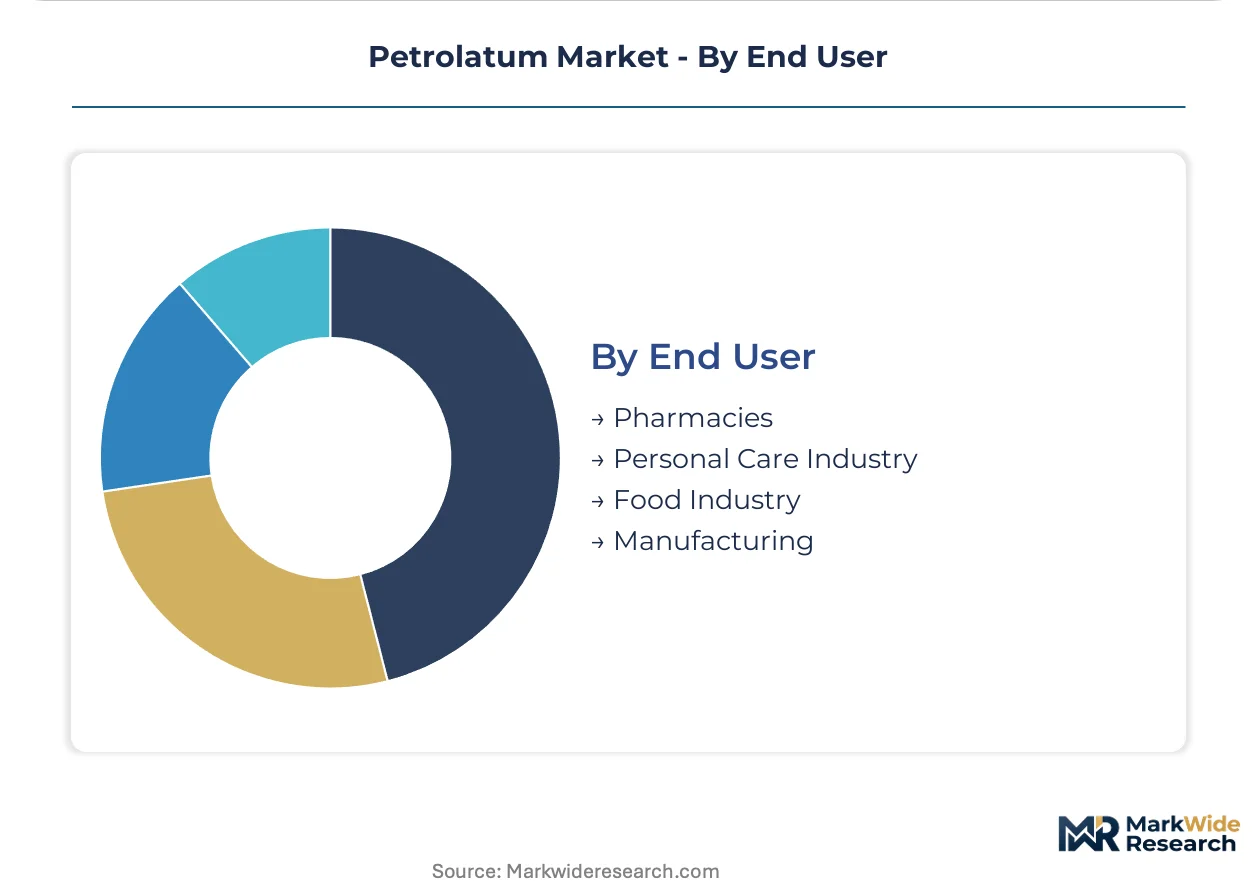
End User:
End user segmentation reveals procurement model shifts as contract manufacturers unbundle excipient sourcing from finished formulation services.
- Personal Care Industry:Cosmetic formulators in India, Indonesia, and Vietnam scale white petrolatum procurement as domestic manufacturing expands without local refining infrastructure.
- Pharmacies:Compounding pharmacies and hospital procurement departments demand USP-grade petrolatum with certificate of analysis documentation for every batch.
- Manufacturing:Industrial lubricant blenders and metalworking facilities absorb commodity-grade petrolatum, with margins compressed by synthetic alternatives.
- Food Industry:Paper and packaging converters apply food-grade petrolatum coatings, representing a stable but low-growth consumption segment.
Personal Care Industry holds the dominant position, while Pharmacies are climbing the fastest as CDSCO-registered facilities build direct ties to refinery-certified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA monograph revisions in the United States are compressing pharmaceutical-grade petrolatum supply chains, while CDSCO standards in India and REACH obligations in Europe reshape procurement patterns across three distinct regulatory zones.
United States
Pharmaceutical ointment manufacturers in New Jersey and Pennsylvania are revalidating excipient streams against tightened USP-NF polycyclic aromatic hydrocarbon thresholds. FDA monograph updates for over-the-counter topical drug products now require segregated petrolatum storage with full batch documentation. Houston-area refining complexes anchor North American supply for industrial-grade distribution.
Germany
Cosmetic formulators in Hamburg and Düsseldorf face ECHA registration burdens that redirect procurement toward pre-certified petrolatum grades. REACH substance dossier requirements impose full supply-chain disclosure obligations on importers. The Rhine-Ruhr industrial corridor concentrates lubricant blending demand for food-contact and mechanical applications.
India
Domestic personal care manufacturing in Mumbai and Ahmedabad absorbs rising white petrolatum volumes as urban consumption shifts toward occlusive moisturizers. CDSCO tightened topical drug excipient standards and PLI scheme incentives for active pharmaceutical ingredients create captive demand for USP-grade supply. Gujarat-based refining infrastructure remains underdeveloped for high-purity output.
China
Skin care contract manufacturers in Guangdong and Jiangsu provinces scale petrolatum procurement without domestic Fischer-Tropsch synthesis capacity for pharmaceutical grades. NMPA excipient registration requirements for imported petrolatum extend qualification timelines. The Yangtze River Delta hosts the largest concentration of cosmetic formulation tolling.
Brazil
Personal care compounders in São Paulo state import white petrolatum as domestic dewaxing infrastructure lacks cosmetic-grade certification. ANVISA pharmaceutical excipient guidelines create parallel compliance tracks for topical drug manufacturers. The Southeast industrial corridor dominates finished formulation output for Latin American distribution.
Petrolatum Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure bifurcating along purity-grade lines. Sasol and ExxonMobil anchor the upper tier through Fischer-Tropsch synthesis and integrated refining respectively, while Calumet Specialty Products Partners occupies a mid-tier position focused on FDA-monograph compliance. Strategic moves concentrate on pharmacopeial validation investments and direct supply relationships with CDSCO-registered facilities in India.
Among integrated energy majors, ExxonMobil and Sasol exemplify divergent technological paths—Fischer-Tropsch synthesis versus conventional dewaxing—each anchoring distinct premium-grade supply positions. Calumet Specialty Products Partners represents the specialist archetype, with batch-level certification capabilities that differentiate against commodity competitors. Sonneborn LLC and Raj Petro Specialities Pvt. Ltd. sit within the regional distributor tier, where procurement consolidation around certified suppliers is compressing margins for non-validated streams.
| Leading Market Players |
|---|
| Sasol |
| Sonneborn LLC |
| Eastern Petroleum |
| Unilever |
| International Group, Inc. |
| Calumet Specialty Products Partners |
| ExxonMobil |
| Raj Petro Specialities Pvt. Ltd. |
| Unisynth Group |
| Others |
Supply Flow & Price Mechanics
Fischer-Tropsch synthesis scale economies at Sasol's South African facilities and ExxonMobil's integrated Gulf Coast refining complexes anchor pharmaceutical-grade petrolatum price floors. These concentrated production bases create asymmetric bargaining power against downstream formulators while vacuum gas oil feedstock volatility transmits crude-linked cost pressure across all purity tiers.
Pricing Analysis
Geographic price spreads between USP-grade petrolatum in North America and cosmetic-grade streams in India reflect certification burden differentials and freight cost structures. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates USP-NF validated batches from REACH-registered cosmetic streams and commodity lubricant bases. Cost compression in industrial-grade segments is intensifying because synthetic hydrocarbon substitutes erode volume offtake from manufacturing end users. Personal care compounders in Southeast Asia exhibit highest price sensitivity due to undeveloped domestic refining infrastructure, while pharmaceutical tollers in Mumbai and Ahmedabad absorb premium pricing for segregated storage and batch documentation.
Supply Chain Analysis
Strait of Malacca transit underwrites white petrolatum flows to Indonesian and Vietnamese personal care manufacturers lacking domestic dewaxing capacity. High-purity output concentrates in South Africa, the United States, and Germany through Fischer-Tropsch synthesis and integrated refining infrastructure. Raw material dependencies rest on vacuum gas oil from lube base oil production, slack wax availability, and hydrotreating catalyst supply. Single-source vulnerability characterizes pharmaceutical-grade streams where USP-NF validation timelines extend qualification cycles. Distribution runs through direct refinery relationships with CDSCO-registered facilities, bypassing traditional chemical merchants in Mumbai and Ahmedabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA monograph revisions and REACH substance registration obligations are compressing qualified supplier lists faster than incumbent capacity expansion, creating a high-growth disruption window for validated producers. CDSCO's tightened excipient standards and India's PLI scheme for active pharmaceutical ingredients accelerate this inflection.
For Market Incumbents: Secure backward integration into vacuum gas oil supply through long-term offtake agreements with lube base oil refiners, insulating margin exposure to crude-linked feedstock volatility. Expand hydrotreating and molecular distillation capacity in Gujarat to capture CDSCO-registered pharmaceutical demand. Certification investment represents the priority lever against plant-based substitution pressure from squalane and shea butter alternatives in EU Green Deal disclosure environments. For New Entrants and Emerging Players: Lead with USP-grade batch certification capabilities targeting compounding pharmacies and hospital procurement departments in tier-two Indian cities where direct refinery relationships remain undeveloped. Indonesia and Vietnam present the most penetrable geographies as local personal care manufacturing scales without domestic petrolatum refining infrastructure. A go-to-market angle anchored to ECHA-registered cosmetic-grade streams with pre-validated Safety Data Sheet documentation bypasses distributor consolidation barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialist refiners with batch-level FDA monograph compliance capabilities over integrated commodity producers. Long-term viability rests on pharmacopeial validation infrastructure and direct supply relationships with CDSCO-registered facilities as regulatory divergence between pharmacopeial standards and industrial chemical frameworks intensifies. The signal to watch is USP-NF polycyclic aromatic hydrocarbon threshold revisions that further compress qualified supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Gas Oil Supply | Long-term offtake agreements with lube base oil refiners in the US Gulf Coast stabilize feedstock costs. |
| USP-NF Batch Certification Investment | Hydrotreating and molecular distillation upgrades enable pharmaceutical-grade qualification against tightened FDA monograph thresholds. |
| Direct Supply Relationships with CDSCO-Registered Facilities | Bypassing traditional chemical merchants in Mumbai and Ahmedabad captures PLI scheme-linked excipient demand. |
| ECHA Registration and REACH Compliance Infrastructure | Pre-validated cosmetic-grade streams consolidate procurement from European formulators facing substance dossier burdens. |
| Capacity Expansion in Gujarat | Proximity to Ahmedabad's pharmaceutical formulation cluster reduces logistics costs for USP-grade petrolatum delivery. |
Methodological Framework
A spread of perspectives from refinery operations managers, pharmaceutical procurement leads at CDSCO-registered facilities, cosmetic formulators in Hamburg and Düsseldorf, and distribution channel partners in Mumbai converged on the working assumptions. Primary interviews combined with secondary validation from USP-NF monograph documentation, ECHA substance registration databases, CDSCO excipient guidelines, and SEC filings from specialty products partners. Bottom-up volume modeling across grade tiers triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include product grade tier, end-use application, formulation form, and geographic regulatory cluster across the analysis window. CAGRs were derived from regression-based extrapolation of historical procurement patterns and regulatory-driven demand inflections. Industry-specific forecast inputs encompassed refinery run-rate decisions affecting vacuum gas oil availability and CDSCO registration timelines for imported petrolatum streams.
Forecasts assume regulatory continuity in US FDA monograph frameworks, EU REACH substance registration requirements, and Indian CDSCO excipient standards; material policy shifts would require re-modeling across pharmaceutical and cosmetic grade demand projections. Practitioners should keep alternative scenarios live as refinery technician scarcity and plant-based substitution pilot programs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
1-Decene Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Oleophilic Materials Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Isopropyl Esters Market