
 Stearic Acid Market | 2026-2036
Stearic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Stearic Acid Market Analysis
REACH is restructuring the cost-of-entry calculus for stearic acid suppliers serving European personal care and pharmaceutical channels. Wilmar International Ltd leverages its integrated palm oil supply chain from plantation to oleochemical refining, sustaining cost advantages across multiple grades. BASF SE anchors its position through pharmaceutical-grade certification depth, while Emery Oleochemicals differentiates via specialty esterification technology for high-purity derivatives.
Stearic acid is a saturated long-chain fatty acid with an 18-carbon backbone, typically derived from animal fats or vegetable oils through hydrolysis or saponification, and functions primarily as a surfactant, emulsifier, and lubricant across industrial and consumer formulations. Industrial grade dominates volume throughput due to its ubiquity in rubber processing and plastics manufacturing, while pharma grade commands premium positioning as FDA and EMA purity requirements tighten. Personal care applications represent the fastest-expanding demand pool as cosmetic companies reformulate away from petrochemical emulsifiers toward plant-derived alternatives.
EPA oversight of chemical manufacturing emissions, FDA food-contact substance notifications, and REACH registration requirements collectively elevate compliance burdens for new market entrants. ISO 9001 and HACCP certifications have become baseline qualifiers rather than differentiators for suppliers serving multinational food and pharmaceutical firms. Stakeholders must monitor feedstock volatility between palm and tallow origins, as sustainability certification trajectories will determine which supply corridors retain preferential access to premium-grade segments.
Market Dynamics
REACH compliance deadlines are compressing supplier margins while palm oil sustainability certification trajectories determine which feedstock corridors retain access to European personal care and pharmaceutical channels.
Growth Catalysts
- Clean-label cosmetic reformulation:Personal care brands are replacing petrochemical emulsifiers with plant-derived stearic acid to meet consumer preference shifts documented by ECHA substance evaluations.
- REACH registration completion:Full dossier compliance for stearic acid and its derivatives has unlocked sustained access to EU pharmaceutical and food-contact applications.
- Malaysian oleochemical cluster expansion:Integrated palm oil refining complexes in Port Klang and Pasir Gudang are capturing incremental volume through captive feedstock advantages.
Market Restraints
- Palm oil price volatility:El Niño-driven harvest variability and Indonesian export policy shifts create input cost instability for vegetable-grade producers.
- Tallow supply concentration:North American rendering facility consolidation limits alternative feedstock security for animal-derived grade manufacturers.
- Glycerol ester substitution:Polyglycerol esters and sucrose esters are displacing stearic acid in select food emulsification applications.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO manufacturing expansion and domestic generic API production growth are creating new high-purity grade consumption nodes.
- EU Green Deal bio-based mandates:Renewable carbon content thresholds in packaging and cosmetics are accelerating certified-sustainable palm and tallow derivative adoption.
- Direct-to-formulator digital channels:Specialty chemical platforms are compressing distributor layers for mid-volume personal care compounders in Southeast Asia.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA drug master file and EMA certificate of suitability procedures extend qualification cycles by 18-24 months.
- Multi-feedstock quality harmonization:Blending palm and tallow origins while maintaining consistent iodine values and melting profiles requires advanced process control investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stearic Acid Market |
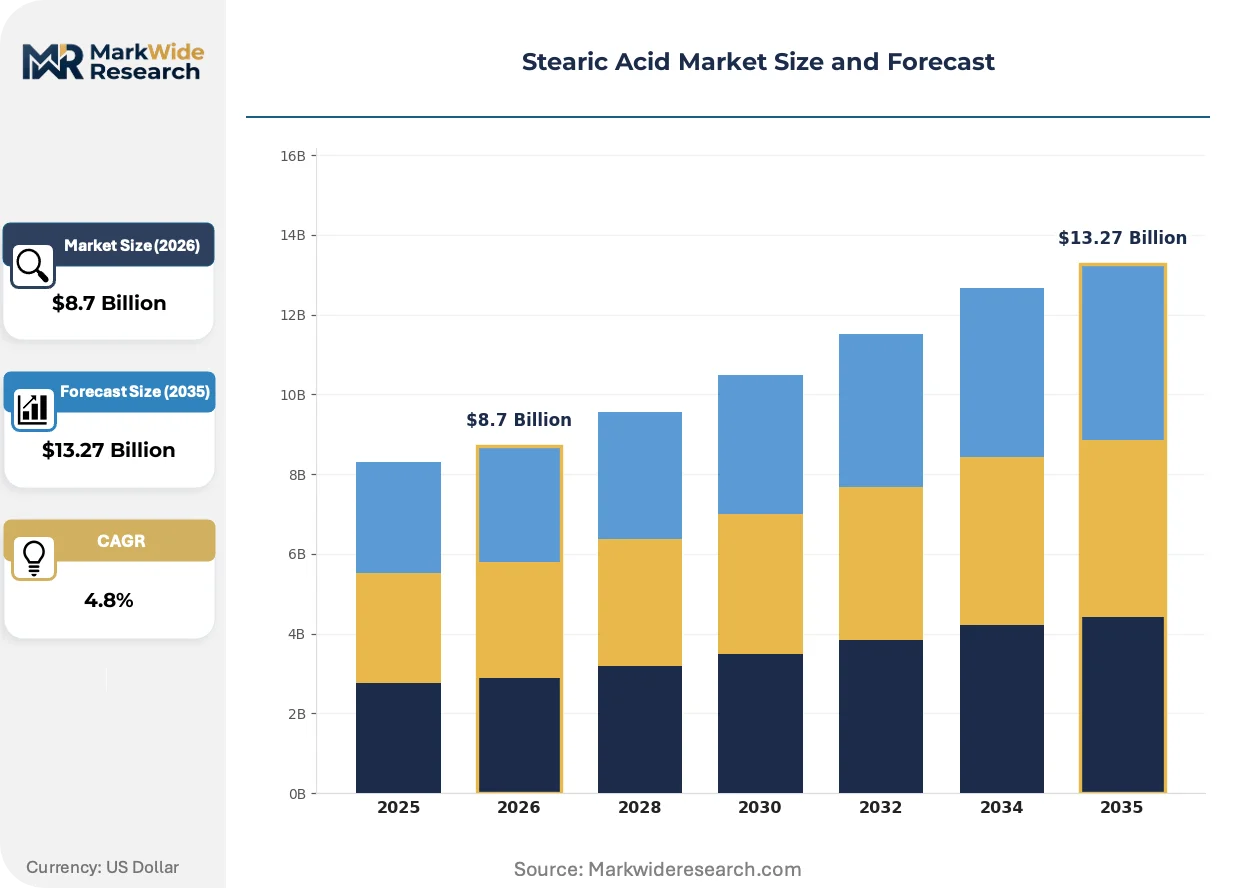
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharma Grade, Technical Grade Application: Personal Care, Pharmaceuticals, Food Processing, Plastics End User: Cosmetic Companies, Food Manufacturers, Pharmaceutical Firms, Chemical Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Wilmar International Ltd, BASF SE, Emery Oleochemicals, KLK Oleo, IOI Oleochemical, 3F Industries LTD, Oleon NV, Godrej Industries Limited, Pacific Oleochemicals Sdn Bhd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stearic Acid Market Emerging Trajectories
Digital process control and sustainability verification technologies are restructuring how stearic acid quality is assured and communicated across fragmented downstream supply chains.
Continuous hydrolysis reactor technology is automating separation efficiency in high-volume oleochemical plants. Malaysian and Indonesian integrated refiners are deploying these systems to reduce steam consumption and improve fatty acid cut sharpness. The technology is automating labor-intensive monitoring tasks while compressing batch-to-batch variability that previously required manual intervention.
REACH substance evaluation dossier updates are tightening impurity thresholds for polycyclic aromatic hydrocarbons and heavy metals in cosmetic-grade material. ECHA's 2024-2026 rolling review schedule is forcing suppliers to invest in additional purification capacity or exit personal care channels. German and French formulators are now requiring third-party laboratory certification beyond standard REACH compliance declarations.
Beauty brand procurement teams are consolidating supplier panels around vertically integrated oleochemical producers with certified sustainable palm oil traceability. Direct sourcing agreements are replacing spot market purchases for personal care compounders serving multinational cosmetics houses. This pattern is most pronounced in formulations destined for Sephora and Ulta retail channels in North America and Douglas and Sephora Europe distribution networks.
Stearic Acid Market Segmentation
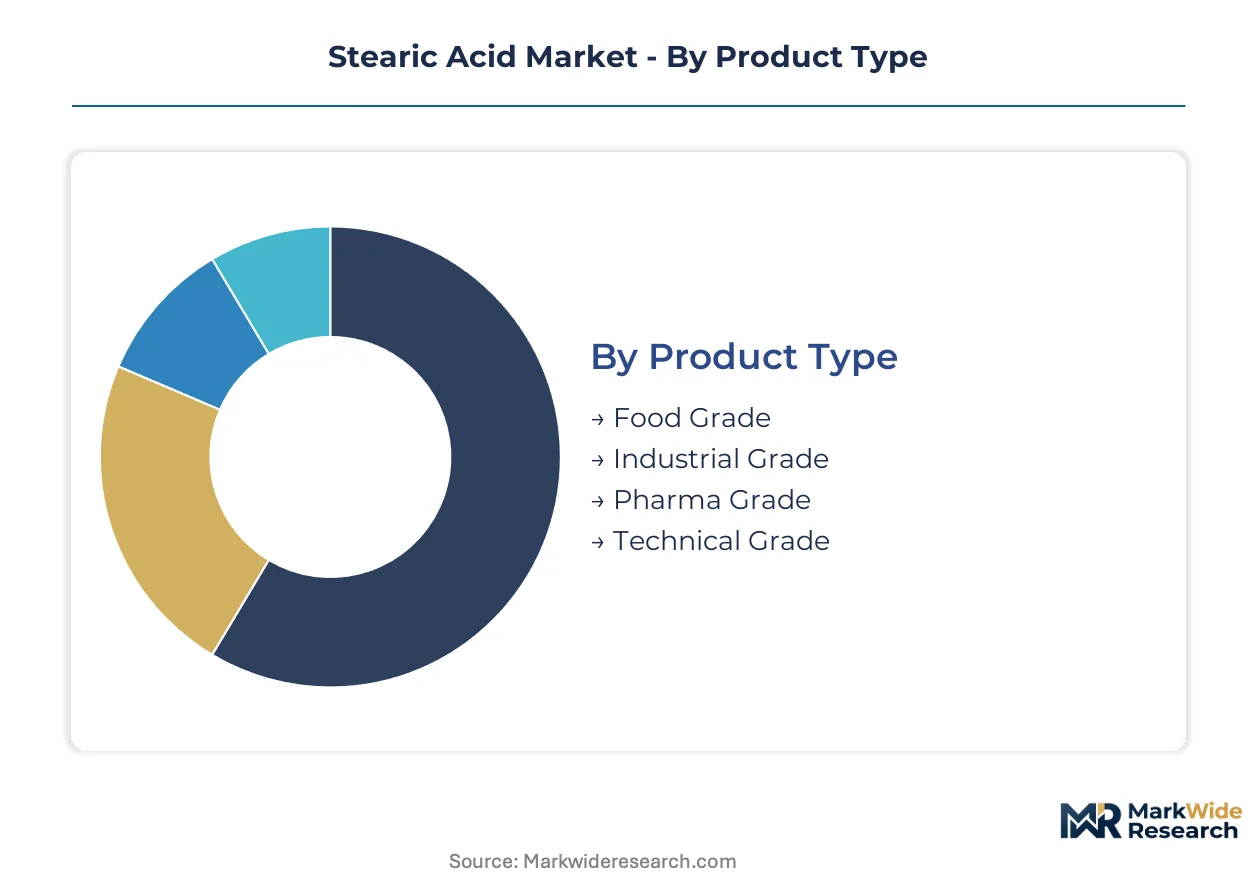
Stearic acid segmentation reflects divergent purity thresholds, regulatory burdens, and margin structures across industrial and consumer channels. Feedstock origin and certification depth increasingly determine which segments suppliers can access profitably.
Product Type:
Capital intensity escalates sharply with purity grade, as pharmaceutical and food applications demand dedicated hydrogenation trains and analytical testing infrastructure that industrial grades do not require.
- Industrial Grade:Standard 40-60% stearic acid content with higher oleic and linoleic fractions serves rubber compounding and PVC lubrication. Tire manufacturers in Thailand and Vietnam absorb volume through integrated procurement contracts with Malaysian oleochemical clusters.
- Pharma Grade:USP-NF and EP monograph compliance demands iodine values below 2.0 and complete absence of residual solvents. FDA drug master file registration and EMA certificate of suitability procedures compress supplier pools to those with dedicated GMP facilities.
- Food Grade:FSSAI and FDA food-contact substance notifications govern direct and indirect food applications. Hydrogenated vegetable origins dominate over tallow for kosher and halal certification requirements.
- Technical Grade:Intermediate purity for metalworking fluids and textile processing carries minimal certification overhead. Price-sensitive buyers in India and Brazil source through spot market channels with limited traceability documentation.
Industrial grade absorbs the bulk of installed capacity; pharma grade is expanding most quickly as generic API production migrates to regulated markets.
Application:
End-use differentiation tracks regulatory exposure, with personal care and pharmaceutical channels demanding supply chain transparency that industrial applications bypass.
- Personal Care:Emulsifier and thickener functions in creams and lotions drive demand for RSPO-certified sustainable palm derivatives. Sephora and Ulta retail channels now mandate third-party sustainability verification beyond standard INCI compliance.
- Pharmaceuticals:Tablet lubricant and sustained-release matrix applications require compendial-grade material with validated manufacturing processes. CDSCO manufacturing expansion in India is creating new consumption nodes for imported high-purity grades.
- Food Processing:Mold release and anti-caking functions in confectionery and baking compete with glycerol ester substitutes. Clean-label positioning favors plant-derived stearic acid over synthetic alternatives in premium product lines.
- Plastics:Internal and external lubrication in PVC processing and polyolefin manufacturing tolerates lower purity thresholds. Price volatility in palm feedstocks has accelerated interest in tallow-derived alternatives for cost stability.
Personal care commands the steepest expansion trajectory; plastics retains the largest volume base despite slower growth.
End User:
Procurement sophistication varies dramatically, with multinational cosmetic and pharmaceutical firms imposing supplier qualification protocols that regional chemical producers circumvent.
- Cosmetic Companies:L'Oréal and Estée Lauder procurement teams consolidate supplier panels around vertically integrated producers with certified sustainable palm oil traceability. Direct sourcing agreements are displacing distributor relationships for high-volume compounders.
- Pharmaceutical Firms:Pfizer and Novartis manufacturing networks require dual-sourced API excipients with documented supply security. Qualification timelines extend 18-24 months, locking in incumbent suppliers.
- Food Manufacturers:Nestlé and Unilever sustainability commitments are filtering down to emulsifier specifications. RSPO mass balance certification is becoming a baseline qualifier for preferred supplier status.
- Chemical Producers:Regional surfactant and ester manufacturers prioritize cost minimization over certification depth. Spot market purchasing dominates with limited long-term contracting.
Cosmetic companies absorb the bulk of certified-sustainable supply; pharmaceutical firms are expanding procurement most rapidly as generic manufacturing scales.
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with large-volume buyers bypassing intermediaries while smaller formulators rely on distributor inventory buffers.
- Direct Sales:Annual contract volumes exceeding 500 metric tons typically qualify for producer-direct pricing and dedicated technical support. Malaysian integrated refiners favor this channel for relationship control with multinational accounts.
- Distributors:Regional chemical distributors maintain blended inventory positions across multiple oleochemical grades. Brenntag and Univar Solutions networks provide formulation expertise that commodity producers lack.
- Online Retail:Alibaba and specialty chemical platforms are compressing lead times for mid-volume personal care compounders in Southeast Asia. Digital channels remain marginal for pharmaceutical and food-grade material due to documentation requirements.
- Wholesalers:Traditional bulk commodity traders serve price-sensitive industrial buyers with minimal technical service. Margin compression in this channel is accelerating consolidation among regional players.
Distributors retain the largest transaction volume; direct sales is gaining share fastest as procurement digitization enables efficient large-account management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian oleochemical clusters absorb the largest share of global stearic acid production capacity, while Indian pharmaceutical demand and European regulatory compliance reshape import flows across major consuming regions.
Malaysia
Port Klang and Pasir Gudang integrated refineries process captive palm oil feedstock into industrial and personal care grades. Malaysian Palm Oil Board sustainability certification requirements filter export eligibility for EU-bound shipments. Klang Valley facilities now supply direct-to-formulator contracts for Sephora and Ulta retail channel producers.
Indonesia
Export policy volatility and El Niño harvest variability create input cost instability for vegetable-grade producers serving Asian plastics compounders. Ministry of Trade export levy adjustments shift relative competitiveness against Malaysian supply corridors. Dumai and Belawan port clusters concentrate oleochemical output for intra-ASEAN rubber processing demand.
United States
FDA food-contact substance notification requirements and EPA chemical manufacturing emissions oversight elevate compliance burdens for domestic compounders. North American rendering facility consolidation limits tallow-derived grade security. Gulf Coast petrochemical corridors blend imported Malaysian material with domestic fatty acid production for PVC lubrication applications.
Germany
ECHA REACH substance evaluation dossier updates tighten polycyclic aromatic hydrocarbon thresholds for cosmetic-grade imports. BASF SE pharmaceutical-grade certification depth anchors domestic supply for EMA-regulated drug manufacturing. Ludwigshafen and Marl chemical parks maintain hydrogenation capacity for high-purity derivative production.
India
CDSCO manufacturing expansion and domestic generic API production growth create new high-purity grade consumption nodes. FSSAI food-grade specifications govern confectionery and baking applications. Gujarat and Maharashtra pharmaceutical clusters import compendial material for tablet lubricant formulations, bypassing underdeveloped domestic hydrogenation infrastructure.
Stearic Acid Market Vendor Landscape
Malaysian and Indonesian producers anchor the volume-driven tier; European and Indian specialists hold premium-grade positioning through certification depth. Market structure tilts toward consolidation among integrated palm oil refiners with captive feedstock access, while pharmaceutical-grade segments retain fragmented supplier pools due to qualification timeline barriers. Three archetypes dominate: plantation-integrated oleochemical refiners, pharmaceutical-grade certification specialists, and regional esterification technology providers. Capacity expansion in Southeast Asian clusters and backward integration into plantation assets represent the dominant competitive moves.
Within the integrated refiner archetype, Wilmar International Ltd and KLK Oleo exemplify plantation-to-oleochemical control structures that sustain cost advantages across multiple grades. BASF SE occupies a position on the pharmaceutical-grade certification vector, representing the European specialist model anchored through EMA and FDA registration depth. Emery Oleochemicals sits within the specialty derivatives tier, illustrating how esterification technology capabilities differentiate positioning in high-purity personal care channels.
| Leading Market Players |
|---|
| Wilmar International Ltd |
| BASF SE |
| Emery Oleochemicals |
| KLK Oleo |
| IOI Oleochemical |
| 3F Industries LTD |
| Oleon NV |
| Godrej Industries Limited |
| Pacific Oleochemicals Sdn Bhd |
| Others |
Supply Flow & Price Mechanics
Captive plantation-to-refinery integration across Malaysian and Indonesian oleochemical clusters anchors both supply security and pricing power for industrial-grade producers, while pharmaceutical and personal care channels extract premiums through certification depth that fragmented tallow-renderers cannot match. REACH compliance investments and RSPO traceability requirements widen the cost-of-entry gap between integrated refiners and spot-market suppliers.
Pricing Analysis
Volume throughput concentrates in industrial-grade rubber and plastics applications where contract-based long-term offtake dominates, while margin capture clusters in pharmaceutical and personal care grades where USP-NF certification and EMA dossier depth enable price premiums. Price differentiation rests on feedstock certification tier and hydrogenation purity, with RSPO mass balance material commanding substantial uplifts over uncertified alternatives. Cost compression in industrial channels is intensifying as Malaysian integrated refiners leverage captive palm oil supply. Chemical producers in India and Brazil exhibit the highest price sensitivity, while cosmetic procurement teams at L'Oréal and Estée Lauder prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian export policy volatility, which disrupts vegetable-grade flows to Asian plastics compounders when Ministry of Trade levy adjustments shift relative competitiveness against Malaysian supply corridors. Geographic supply concentration centers on Malaysia, Indonesia, and India, with Port Klang and Pasir Gudang clusters processing captive feedstock while Gujarat pharmaceutical importers bypass underdeveloped domestic hydrogenation infrastructure. Raw material dependencies draw from crude palm oil, tallow rendering output, and hydrogenation catalysts. Tariff exposure on EU-bound shipments creates structural risk as ECHA substance evaluations tighten impurity thresholds. Distribution runs through direct sales for volumes exceeding 500 metric tons, with Brenntag and Univar Solutions networks serving mid-volume compounders requiring formulation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH registration deadlines and pharmaceutical-grade qualification timelines force capital-constrained regional producers toward exit or acquisition by integrated refiners with compliance infrastructure.
For Market Incumbents: Cement supply security through backward integration into certified sustainable palm plantation assets or long-term feedstock offtake agreements with Malaysian Palm Oil Board-compliant producers. Expand hydrogenation capacity in Port Klang or Pasir Gudang to capture incremental pharmaceutical-grade demand from CDSCO-registered Indian generic API manufacturers. Glycerol ester substitution in food emulsification represents the priority threat requiring defensive R&D into polyglycerol ester compatibility.
For New Entrants and Emerging Players: Capture white space in Indian pharmaceutical excipient supply by establishing compendial-grade toll manufacturing partnerships with Gujarat or Maharashtra API producers lacking in-house hydrogenation infrastructure. Direct-to-formulator digital channels through specialty chemical platforms offer the most penetrable route for mid-volume personal care compounders in Southeast Asia, bypassing entrenched distributor relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in plantation-integrated oleochemical refiners with RSPO certification depth and established FDA drug master file registrations, as these assets command scarcity premiums in a consolidating supplier landscape. Long-term viability favors producers with captive feedstock security and multi-grade flexibility across industrial, food, and pharmaceutical tiers. Watch for inflection in palm oil sustainability certification trajectory, as mass balance versus segregated supply chain commitments determine which corridors retain European personal care access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive palm oil supply from Malaysian estates secures cost advantages against spot-feedstock competitors. |
| Pharmaceutical-Grade Certification Investment | FDA drug master file registration unlocks dual-sourced excipient contracts with Pfizer and Novartis networks. |
| Continuous Hydrolysis Reactor Deployment | Automation of separation efficiency reduces steam consumption and sharpens fatty acid cut consistency. |
| Direct-to-Formulator Digital Channel Expansion | Specialty chemical platforms compress distributor layers for Sephora and Ulta retail channel compounders. |
| RSPO Mass Balance Certification Program | Sustainability verification secures preferred supplier status with Nestlé and Unilever procurement teams. |
Methodological Framework
Independent corroboration across primary interviews with oleochemical plant managers, downstream procurement leads at tire manufacturers and PVC compounders, distribution channel partners, and technical R&D directors at personal care formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, Malaysian Palm Oil Board sustainability reports, SEC 10-K filings of listed refiners, and ECHA substance evaluation dossiers. Bottom-up capacity and utilization estimates triangulate against top-down demand segmentation across rubber processing, pharmaceutical excipient, and cosmetic emulsifier applications.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion, with CAGRs derived from segmented modeling across grade tier, end-use industry, and regional production hub dimensions. The framework incorporates feedstock price elasticity between palm and tallow origins, REACH compliance cost pass-through assumptions, and substitution elasticity for glycerol esters in food processing channels.
The model holds under sustained palm oil sustainability certification adoption and stable Indonesian export policy; deviation in El Niño harvest severity or ECHA impurity threshold tightening would shift volume and value trajectories. Forecasts reflect documented assumptions on feedstock substitution rates and qualification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Paraffin Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Glycerine Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Lauric Aldehyde Market