
 Octyl Octanoate Market | 2026-2036
Octyl Octanoate Market Size, Share, and Industry Trends Forecast 2026-2036
Octyl Octanoate Market Analytics
Personal care manufacturers are unwinding their reliance on heavier mineral oil bases in favor of plant-derived esters like octyl octanoate. Stepan Company leverages its integrated oleochemical platform to secure consistent fatty alcohol feedstock for ester production. Merck KGaA anchors its position through pharmaceutical-grade certification and exacting purity protocols that command premium positioning in regulated applications. Emery Oleochemicals dominates natural-based ester supply through backward integration into palm and palm kernel oil sourcing across Southeast Asian plantations.
Octyl octanoate is a medium-chain fatty acid ester synthesized from octanoic acid and octyl alcohol, exhibiting a low viscosity of approximately 8-10 cP at 25°C and a neutral odor profile that makes it ideal for cosmetic formulations requiring non-greasy slip and rapid spreadability. The personal care application segment leads current volume consumption due to widespread incorporation into lotions, sunscreens, and color cosmetics where silicone-free texture modification is valued. Chemical intermediate usage represents the fastest-expanding structural category as pharmaceutical and agrochemical manufacturers adopt octyl octanoate as a reaction solvent and coupling agent in peptide synthesis and active ingredient delivery systems.
REACH registration requirements in Europe mandate full toxicological dossiers for cosmetic-grade esters above one-tonne annual thresholds, while the FDA maintains voluntary cosmetic ingredient review panels that increasingly scrutinize ester safety profiles for dermal sensitization potential. China's NMPA and GB standards for cosmetic raw materials impose additional heavy metal and peroxide value limits that filter out non-compliant imports. Stakeholders must monitor regulatory divergence between these three jurisdictions to avoid formulation reformulation costs and supply chain disqualification.
Market Dynamics
Personal care formulators are accelerating their shift away from petroleum-derived emollients toward plant-based esters, driven by tightening purity specifications under REACH and evolving FDA cosmetic safety guidance that disqualify legacy mineral oil formulations.
Growth Catalysts
- REACH compliance mandates:European ECHA registration requirements for cosmetic-grade esters above one-tonne thresholds are filtering out non-compliant suppliers and consolidating demand around certified producers.
- Silicone-free texture modification:Sunscreen and color cosmetics manufacturers are adopting octyl octanoate as a lightweight, rapid-spreadability alternative to cyclomethicones facing environmental scrutiny.
- China's domestic manufacturing clusters:NMPA-aligned production facilities in Guangdong and Zhejiang provinces are scaling specialty ester output for regional personal care brands and export markets.
Market Restraints
- Palm and palm kernel oil price volatility:Natural-based ester producers face margin compression from feedstock fluctuations tied to Malaysian and Indonesian plantation output cycles.
- Heavy metal and peroxide value limits:China's GB standards for cosmetic raw materials impose testing burdens that disqualify smaller import sources lacking analytical capabilities.
- Isopropyl myristate substitution:Lower-cost synthetic esters retain share in mass-market lotions where spreadability requirements are less stringent.
Strategic Opportunities
- Peptide synthesis solvents:Pharmaceutical manufacturers are expanding octyl octanoate use as a reaction medium and coupling agent in active ingredient delivery systems.
- Agrochemical formulation carriers:Crop protection producers are testing medium-chain esters as biodegradable solvent alternatives to petroleum-derived aromatic hydrocarbons.
- Pharmaceutical-grade certification:Exact purity protocols aligned with USP and EP monographs command premium positioning in regulated dermal and transdermal applications.
Industry Challenges
- Toxicological dossier compilation:REACH registration requires extensive dermal sensitization and ecotoxicity studies that strain mid-cap ester producers' regulatory affairs capacity.
- Multi-jurisdictional specification divergence:Formulators must maintain separate inventory streams to satisfy FDA voluntary review panels, ECHA dossier requirements, and NMPA heavy metal limits simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octyl Octanoate Market |
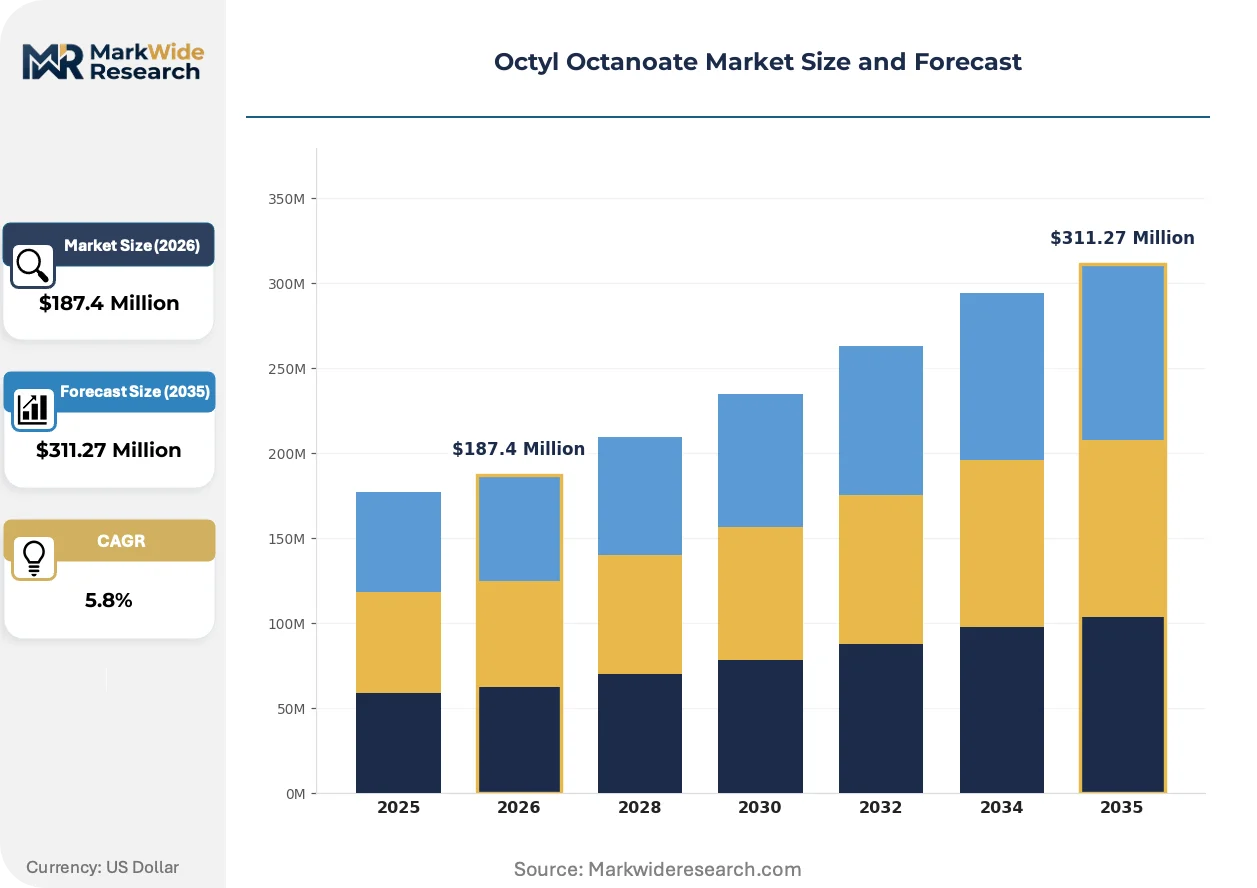
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Flavorings, Fragrances Application: Personal Care, Food Additive, Industrial Solvent, Chemical Intermediate End User: Manufacturers, Retailers, Wholesalers, Research Institutions Distribution Channel: Online Sales, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Bench Chemicals, Penta Manufacturing Company, Merck KGaA, Stepan Company, Zschimmer & Schwarz, BOC Sciences, Synerzine, Emery Oleochemicals, BRAS Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octyl Octanoate Market Evolving Landscape
Ester chemistry platforms are fragmenting into dual-track development paths serving cosmetic versus pharmaceutical purity tiers, while regulatory authorities on three continents tighten divergent safety protocols.
Biocatalytic ester synthesis is bifurcating the production landscape between lipase-catalyzed routes favored by European specialty chemical houses and traditional chemical esterification retained by Asian volume producers. Enzymatic processes deliver chirally pure outputs for pharmaceutical intermediates. Cosmetic-grade manufacturers in Germany and Switzerland are retrofitting batch plants with immobilized enzyme columns. This technology is bifurcating supplier tiers into premium-certified and commodity-standard camps with widening price spreads.
REACH registration renewal deadlines for existing cosmetic-grade ester dossiers are forcing toxicological data upgrades that smaller importers cannot fund. ECHA's 2024-2026 evaluation windows target medium-chain fatty acid esters for endocrine disruption screening. Personal care brands with pan-European distribution are pre-emptively reformulating around pre-registered supply chains. German and French formulators are accelerating supplier qualification timelines to secure compliant inputs before evaluation outcomes publish.
Direct procurement from integrated oleochemical producers is displacing layered distributor networks for volume personal care accounts. Multinational lotion and sunscreen manufacturers in the United States are establishing annual contracting relationships with Malaysian and Indonesian plantation-backed ester suppliers. Third-party chemical distributors are retreating to smaller regional cosmetic compounders lacking specification expertise. This consolidation is most visible in California and New Jersey formulation clusters where procurement teams have hired dedicated oleochemical category managers.
Octyl Octanoate Market Segmentation
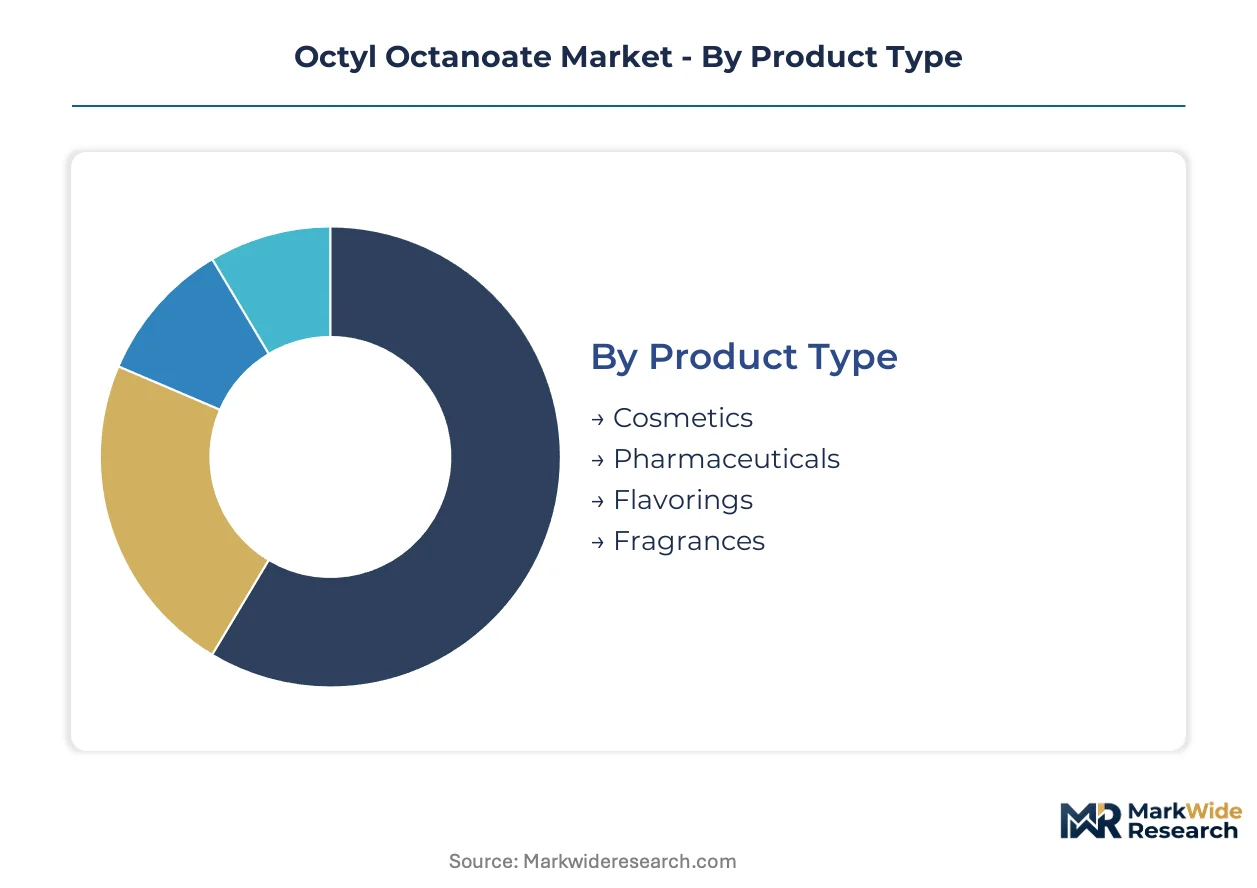
Octyl octanoate's functional versatility across viscosity profiles and purity grades creates distinct demand pockets with divergent specification requirements. Segmentation reveals how regulatory thresholds and end-use performance needs partition the market into non-interchangeable supply tiers.
Product Type:
Cosmetics-grade volumes concentrate in domestic manufacturing clusters serving regional formulators, while pharmaceutical and fragrance grades flow through export-oriented channels bound for regulated markets.
- Cosmetics:Medium-chain ester with 8-10 cP viscosity at 25°C delivers non-greasy slip for lotion and sunscreen formulations. Demand clusters in Guangdong and Zhejiang province manufacturing hubs serving regional personal care brands and export markets.
- Pharmaceuticals:USP and EP monograph-aligned purity protocols command premium positioning in dermal and transdermal applications. REACH dossier requirements and FDA guidance on cosmetic ingredient safety filter demand toward certified producers with toxicological data packages.
- Flavorings:Food-grade specifications under FSSAI and FDA food additive regulations.
- Fragrances:Neutral odor profile suits solvent carrier roles in fine fragrance compounding.
Cosmetics commands the established base. The steepest expansion runs through Pharmaceuticals.
Application:
Volume concentration aligns with customer scale, where multinational personal care manufacturers drive bulk contracting while specialty chemical houses populate the chemical intermediate tier.
- Personal Care:Silicone-free texture modification in sunscreens and color cosmetics leverages rapid spreadability characteristics. NMPA-aligned production facilities scale output for regional brands and export markets.
- Chemical Intermediate:Peptide synthesis solvent and coupling agent roles in pharmaceutical and agrochemical manufacturing. Biocatalytic ester synthesis routes deliver chirally pure outputs for active ingredient delivery systems.
- Food Additive:Carrier solvent and flavor diluent applications under food safety protocols.
- Industrial Solvent:Biodegradable alternative to petroleum-derived aromatic hydrocarbons in crop protection formulations.
Personal Care anchors current volume. Chemical Intermediate climbs the fastest as pharmaceutical manufacturers expand reaction medium adoption.
End User:
Procurement sophistication separates the tiers, with integrated manufacturers demanding backward integration into feedstock while distributors serve fragmented smaller accounts.
- Manufacturers:Multinational lotion and sunscreen producers establish annual contracting relationships with Malaysian and Indonesian plantation-backed ester suppliers. Direct procurement displaces layered distributor networks for volume accounts.
- Research Institutions:Biocatalytic synthesis development and pharmaceutical-grade protocol validation. German and Swiss cosmetic-grade manufacturers retrofit batch plants with immobilized enzyme columns for chirally pure outputs.
- Retailers:Specialty personal care brands with limited formulation expertise.
- Wholesalers:Regional chemical distributors retreating to smaller cosmetic compounders lacking specification capabilities.
Manufacturers dominate contract value. Research Institutions gain share fastest through enzymatic process development partnerships.
Distribution Channel:
Channel selection reflects buyer technical capability, with specification-savvy manufacturers bypassing intermediaries while smaller formulators rely on distributor quality assurance.
- Direct Sales:Annual contracting relationships between multinational personal care manufacturers and integrated oleochemical producers. Procurement teams in California and New Jersey formulation clusters hire dedicated oleochemical category managers.
- Distributors:Third-party chemical distributors serving smaller regional cosmetic compounders lacking REACH dossier expertise or NMPA heavy metal testing capabilities.
- Online Sales:Sample quantities and small-batch procurement for independent formulators.
- Specialty Stores:Cosmetic ingredient retailers serving artisanal and niche personal care brands.
Direct Sales captures the volume base. Distributors retain position in the fragmented long tail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oleochemical production clusters in Southeast Asia supply feedstock to specialty ester manufacturers across three continents. Malaysian and Indonesian plantation-backed suppliers anchor upstream capacity. Downstream formulation demand concentrates in personal care manufacturing hubs in China, the United States, and Germany.
China
Guangdong and Zhejiang province manufacturing clusters scale specialty ester output for regional personal care brands and export markets. NMPA and GB standards impose heavy metal and peroxide value limits that filter non-compliant imports. Domestic fragrance and personal care manufacturers in Shanghai and Guangzhou are expanding captive ester production capacity.
United States
California and New Jersey formulation clusters drive bulk contracting for silicone-free sunscreen and color cosmetic applications. FDA maintains voluntary cosmetic ingredient review panels that scrutinize ester safety profiles for dermal sensitization. Procurement teams in Los Angeles and Newark have hired dedicated oleochemical category managers to manage direct supplier relationships.
Germany
REACH registration requirements and ECHA dossier mandates consolidate demand around certified producers with toxicological data packages. Cosmetic-grade manufacturers in Hamburg and Frankfurt retrofit batch plants with biocatalytic synthesis capabilities. German formulators accelerate supplier qualification timelines to secure compliant inputs before ECHA's 2024-2026 evaluation windows conclude.
Malaysia
Backward integration into palm and palm kernel oil sourcing across Southeast Asian plantations dominates natural-based ester supply. Feedstock price volatility from plantation output cycles compresses margins for downstream ester producers. Port Klang and Pasir Gudang serve as export gateways for oleochemical derivatives bound for European and North American personal care manufacturers.
Switzerland
Pharmaceutical-grade certification and exacting purity protocols command premium positioning in regulated dermal and transdermal applications. Swissmedic-aligned producers in Basel supply chirally pure outputs for peptide synthesis solvents. Research partnerships between Basel-based specialty chemical houses and pharmaceutical manufacturers expand enzymatic process development for active ingredient delivery systems.
Octyl Octanoate Market Competitive Landscape
Concentration sits with integrated oleochemical producers and specialty chemical houses possessing toxicological dossier capabilities for REACH compliance. The vendor base separates into three tiers: plantation-backed volume suppliers, pharmaceutical-grade certified specialists, and regional compounders serving fragmented local accounts. Two dominant competitive moves define current positioning: direct annual contracting relationships displacing distributor networks, and biocatalytic synthesis retrofits creating premium-certified supply tiers.
Within the integrated oleochemical tier, Emery Oleochemicals and Stepan Company exemplify backward-integrated models controlling feedstock from Southeast Asian plantations through North American processing. Merck KGaA occupies a position on the pharmaceutical-grade vector, anchoring premium-tier supply through USP and EP monograph alignment. Zschimmer & Schwarz represents the European specialty chemical archetype with enzymatic process capabilities for cosmetic-grade outputs. Penta Manufacturing Company and BOC Sciences sit within the diversified chemical supplier segment serving research and intermediate applications.
| Leading Market Players |
|---|
| Bench Chemicals |
| Penta Manufacturing Company |
| Merck KGaA |
| Stepan Company |
| Zschimmer & Schwarz |
| BOC Sciences |
| Synerzine |
| Emery Oleochemicals |
| BRAS Chemicals |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Malaysian plantation-backed suppliers and multinational personal care manufacturers lock in feedstock access while stabilizing price visibility against palm oil volatility cycles. REACH compliance costs and NMPA testing burdens stratify supplier tiers into certified premium and non-compliant economy camps with widening spreads.
Pricing Analysis
REACH registration mandates dictate the pricing tier structure across the European market, separating certified producers with toxicological dossiers from uncertified imports facing disqualification. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels reflects purity protocol divergence and certification investment recovery. Cost compression in cosmetic-grade segments is intensifying because isopropyl myristate substitution retains share in mass-market applications. Mass-market lotion manufacturers exhibit highest price sensitivity, while pharmaceutical formulators accept premiums for USP and EP monograph alignment.
Supply Chain Analysis
Malacca Strait transit underwrites the bulk of palm and palm kernel oil feedstock movement from Indonesian and Malaysian plantations to downstream esterification facilities. Supply concentrates in Malaysia, Indonesia, and China as dominant production nodes, with octanoic acid, octyl alcohol, and immobilized enzyme catalysts as critical inputs. Single-source vulnerability in Southeast Asian plantation output creates exposure to El Niño-driven production shortfalls. Distribution runs through direct annual contracting for volume accounts, while regional distributors serve fragmented cosmetic compounders lacking specification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in this market flows from toxicological dossier capabilities and biocatalytic synthesis expertise that mid-cap producers cannot readily replicate. The capability gap between REACH-certified specialists and commodity-standard suppliers is widening faster than capital can close it.
For Market Incumbents: Secure backward integration into plantation feedstock through equity stakes or long-term offtake arrangements with Malaysian and Indonesian suppliers. Expand biocatalytic retrofit capacity in Hamburg and Frankfurt facilities before ECHA evaluation windows conclude, locking in premium positioning against emerging enzymatic competitors. For New Entrants and Emerging Players: Differentiate on peptide synthesis solvent purity for pharmaceutical intermediate applications where certification barriers filter incumbent competition. Target agrochemical formulation carriers as the most penetrable white space, leveraging biodegradable positioning against petroleum-derived aromatic hydrocarbons in crop protection. For Investors and Strategic Acquirers: Capital is best deployed toward integrated oleochemical producers possessing REACH dossier capabilities and plantation-backed feedstock security. The acquisition archetype combines toxicological data packages with enzymatic process development partnerships. Watch ECHA endocrine disruption screening outcomes as the inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Equity stakes in Malaysian plantations secure feedstock against price volatility cycles. |
| Biocatalytic Retrofit | Immobilized enzyme columns in German batch plants deliver chirally pure pharmaceutical outputs. |
| REACH Dossier Investment | Toxicological data packages filter competition and command premium positioning in European markets. |
| Long-term Supply Agreement | Annual contracting with California and New Jersey formulation clusters displaces distributor networks. |
| Pharmaceutical-grade Certification | USP and EP monograph alignment unlocks dermal and transdermal application premiums. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement managers at multinational personal care manufacturers, plant managers at Malaysian oleochemical facilities, regulatory affairs leads navigating REACH dossier preparation, and technical R&D directors developing biocatalytic synthesis routes. Secondary validation drew from ECHA registration databases, FDA cosmetic ingredient review panel proceedings, NMPA GB standard publications, and customs trade data tracking octyl octanoate flows through Port Klang and Pasir Gudang. Bottom-up volume estimates from end-use applications were triangulated against top-down capacity assessments from integrated producers.
Across the projection horizon, the analytical framework modeled segmentation dimensions including grade tier, end-use industry, and regional regulatory cluster to capture specification divergence effects. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs incorporated palm oil price volatility assumptions and ECHA evaluation window outcomes affecting supplier qualification rates.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or alternative feedstock substitution breakthroughs would require recalibration. Practitioners should keep alternative scenarios live as regulatory divergence between European, American, and Chinese jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Carbolic Oil Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
US Esters Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Esters Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Isooctyl Chloride Market